

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Main-Chain Liquid Crystalline Polymer Market: How a 7.42% CAGR Reshapes Strategy Through 2032

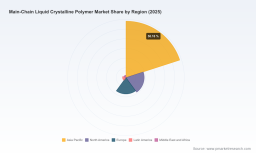
Main-Chain Liquid Crystalline Polymer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Structural Challenges
The main-chain liquid crystalline polymer (LCP) market has established itself as a critical enabler for high-performance engineering applications, driven by an unambiguous demand trajectory. Revenue expanded from approximately $1,024 million in 2020 to $1,466 million in 2025, and forward projections indicate sustained momentum toward $2,420 million by 2032. This trajectory translates to a compound annual growth rate of 7.42 percent across the 2026 to 2032 forecast horizon, reflecting a market that is no longer niche but structurally embedded in advanced manufacturing ecosystems. Growth is not evenly distributed across applications or geographies, yet the underlying expansion is anchored by sectors where dimensional stability, thermal resilience, and flow characteristics during precision molding are non-negotiable.
Despite the positive macro trajectory, the industry confronts several structural friction points that will define competitive positioning in the coming years. First, supply chain fragility around specialty monomers creates persistent cost and availability volatility. Purified terephthalic acid and hydroxybenzoate derivatives, which form the backbone of main-chain LCP chemistry, operate within constrained global supply networks. Limited supplier concentration, coupled with batch polymerization requirements, means producers cannot easily decouple from raw material price swings or logistical bottlenecks. This structural premium, often trading at roughly double the cost of high-temperature nylons, limits aggressive substitution in cost-sensitive applications while simultaneously reinforcing the material's value proposition where performance justifies expense.
Second, the regulatory environment is lengthening qualification cycles and raising compliance overhead. Updated chemical safety review frameworks in major markets, alongside evolving disclosure expectations under prevailing chemical strategies, require more extensive testing, traceability documentation, and lifecycle transparency for new LCP grades. These requirements are not peripheral; they directly impact time-to-market for formulation adjustments, additive packages, and biologically balanced variants. For high-volume electronics and mobility customers operating on tight product launch schedules, extended qualification timelines create planning uncertainty and can delay adoption even when technical performance is compelling.
Liquid Crystal Polymers (LCPs) Market
Third, the market is transitioning from performance-driven acceptance to sustainability-conditioned procurement. Original equipment manufacturers and tier suppliers increasingly expect certified green feedstocks, mass-balance traceability, and circular chemistry options alongside thermal and mechanical specifications. This shift does not eliminate demand for conventional main-chain LCPs, but it reshapes purchasing criteria and rewards producers who integrate environmental credentials into product architecture rather than treating them as aftermarket messaging. The convergence of raw material constraints, regulatory elongation, and sustainability-conditioned demand creates a market where scale alone is insufficient. Competitive advantage is migrating toward formulation agility, feedstock diversification, and qualification speed.
Key Drivers Shaping Market Trajectory
Technical Innovation and Formulation Breakthroughs
Material science progress remains the most direct catalyst for expanded LCP adoption. Recent chemistry refinements have focused on balancing high-heat resistance, flame retardancy, and injection flow without sacrificing dimensional tolerances. For high-frequency electronics, 5G infrastructure, and electric vehicle power management, formulators have engineered grades that maintain signal integrity and thermal stability while enabling thinner wall sections and higher component density. The ability to tailor monomer ratios, modify end-group terminations, and integrate specialty additives without disrupting liquid crystalline ordering has extended LCP relevance into applications that previously relied on metal substitution or lower-performance thermoplastics.
A notable example of formulation direction is the introduction of biomass-balanced grades that preserve performance while addressing procurement decarbonization requirements. By applying mass-balance accounting to bio-derived feedstocks, producers have delivered LCP variants that maintain thermal and mechanical characteristics while providing a credible pathway for customers seeking scope reductions in their supply chain emissions. This development signals a broader shift: sustainability is increasingly being engineered into polymer architecture rather than layered on through end-of-life messaging alone.
Policy and Regulatory Environment
Regulatory frameworks are actively reshaping how LCP grades are developed, qualified, and deployed. Chemicals legislation in major jurisdictions continues to tighten testing protocols, disclosure expectations, and substance evaluation timelines. For LCP producers, this means new grades and modified formulations face longer qualification cycles, and customers require more visible documentation around chemical safety, traceability, and compliance status. The operational effect is twofold: it raises barriers to rapid product churn and rewards companies with mature regulatory infrastructure, standardized testing data packages, and established customer qualification relationships.
Simultaneously, policy emphasis on safer chemistries and circular solutions is altering feedstock preferences. Procurement teams increasingly weigh certified feedstocks, mass-balance traceability, and lower-impact sourcing as material selection criteria, particularly in automotive, electronics, and medical supply chains. This environment favors producers that can deliver both performance assurance and verifiable sustainability credentials, while it pressures laggards who must retrofit compliance or feedstock strategy after product architecture decisions are already locked.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Demand-Side Evolution in Key End-Use Markets
Demand is shifting not only in magnitude but in specification. Electrical and electronics applications continue to anchor volume, driven by miniaturization, high-speed data transmission, and thermal management requirements in consumer devices, network infrastructure, and advanced driver-assistance systems. Automotive demand is growing as electrification expands the need for lightweight, heat-resistant, and dimensionally stable components in battery-related assemblies, charging systems, and under-hood modules. Aerospace and defense applications reinforce the market's high-performance core, where strict qualification standards and long service-life expectations reward materials that deliver consistent behavior under extreme thermal and mechanical stress.
Industrial and medical applications add a different growth pattern: lower volume per grade but higher specification precision, especially in semiconductor processing equipment, medical device components, and precision instrumentation. Across these segments, purchasing decisions are becoming more integrated. Procurement, engineering, and sustainability teams increasingly evaluate LCP grades against a combined scorecard of thermal performance, flow behavior, regulatory readiness, and feedstock credentials. The result is a market where multi-attribute value propositions outperform single-dimension price competition.
Supply Chain and Cost Structure Dynamics
Cost structure remains a defining constraint and opportunity. Main-chain LCP pricing carries a structural premium relative to high-temperature nylons because of batch polymerization economics and the reliance on specialty monomers sourced through narrow supply channels. This cost gap limits broad displacement into commoditized applications but protects margins for producers who can deliver differentiated performance, regional supply proximity, and qualification support. Capacity expansions in localized manufacturing footprints are increasingly important for reducing logistics risk, shortening lead times, and improving service levels for high-volume customers who require consistent supply more than marginal unit-cost savings.
The competitive response to cost and supply complexity has been uneven. Leading producers are expanding regional capacity, integrating feedstock strategy into product design, and shortening qualification timelines through standardized data packages. Smaller or less diversified players face the strain of raw material volatility, longer compliance cycles, and customer expectations that increasingly demand more than technical specifications. In this environment, the market's cost structure is not merely a pricing issue; it is a strategic variable that shapes regional supply strategy, customer partnerships, and the pace at which new grades can be commercialized.
Competitive Landscape and Leading Strategies
The main-chain LCP market is characterized by concentrated leadership, with a core group of producers capturing a substantial share of volume and value. The competitive field reflects both legacy formulation expertise and accelerating strategic maneuvering across capacity, acquisition, and sustainability-driven product development. Rather than competing purely on price, leading companies are competing on technical specificity, regional supply assurance, qualification speed, and feedstock strategy.
Among the most prominent participants, Celanese Corporation has positioned its Vectra and Zenite resin and compound portfolio around high-performance electronics, connectors, and automotive applications, emphasizing flow, heat resistance, and dimensional stability. Its recent commissioning of additional LCP production capacity in China reflects a strategic emphasis on local supply for electronics and 5G-related applications, shortening lead times and improving service responsiveness in a region that remains central to electronics demand growth. Polyplastics Co., Ltd. has built its LAPEROS brand around precision molding for semiconductors, medical technology, and automotive applications, and has advanced a biomass-balanced variant using a mass-balance approach with bio-derived raw materials. This move illustrates a broader competitive trend: sustainability is being incorporated as a product attribute rather than a separate communications exercise.
Sumitomo Chemical Co., Ltd. supplies Sumikasuper resins for electronics and high-heat applications, and its acquisition of an additional LCP neat resin business from Syensqo signals a deliberate effort to strengthen offerings in ICT and mobility applications. The transaction highlights a consolidation dynamic in which incumbents are acquiring formulation capability, customer relationships, and product breadth to accelerate positioning in high-growth applications. Toray Industries, Inc. manufactures SIVERAS main-chain LCP materials for electronics and high-frequency applications, with particular emphasis on films and precision components, reinforcing a strategy centered on specialized form factors rather than commodity resin volume. Solvay S.A. through Syensqo provides Xydar grades, including high-heat and flame-retardant variants for EV battery insulation and industrial uses, aligning its portfolio with thermal safety and electrification-driven demand. Ueno Fine Chemicals Industry, Ltd. focuses on main-chain LCP production for high-performance engineering plastics in electronics and other demanding sectors, while Kuraray Co., Ltd. offers main-chain LCP materials including films and fibers for electronics and high-strength applications, extending the material's reach into structural and functional formats beyond conventional molding resins.
The competitive landscape is evolving along several vectors. Consolidation is evident through targeted acquisitions that expand resin portfolios and deepen application coverage, particularly in ICT and mobility. Differentiation is increasingly based on formulation specificity, regulatory readiness, and sustainability-enabled product variants rather than generic performance claims. Regional supply strategy has become a competitive lever, as customers prioritize local or near-local production to mitigate logistics risk and improve responsiveness. At the same time, the market is not closing to new entrants entirely, but entry barriers are rising. Specialty monomer access, batch polymerization know-how, qualification relationships, and sustainability certification infrastructure all raise the threshold for meaningful market participation. The likely trajectory is continued concentration among established producers with diversified application coverage, while niche players survive by serving highly specialized grades or regional demand pockets that larger portfolios do not prioritize. Competitive success will increasingly depend on how effectively companies integrate technical performance with regulatory compliance, feedstock strategy, and localized supply reliability.
PW Consulting Chemical & Energy Research Center
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the main-chain LCP market is likely to follow three interlocking trends that will shape both opportunity and risk. First, demand growth will remain anchored in electrification, advanced electronics, and precision engineering, but the growth will be increasingly grade-specific. General-purpose thermal materials will face substitution pressure, while LCPs engineered for high heat, flame resistance, signal integrity, and precision molding will capture disproportionate value. This means commercial opportunity will concentrate in applications where LCP's structural advantages are difficult to replicate, especially in battery-related assemblies, high-frequency electronics, connector systems, and demanding medical or aerospace components.
Second, sustainability-enabled product architecture will move from differentiator to baseline expectation in premium procurement channels. Biomass-balanced grades, certified feedstocks, and mass-balance traceability will increasingly appear in supplier selection criteria, especially for multinational OEMs and tier suppliers with public decarbonization commitments. Companies that can pair verified sustainability credentials with consistent performance and fast qualification will gain access to a widening premium procurement segment. The risk is that sustainability claims become commoditized if they are not supported by credible mass-balance accounting, transparent disclosure, and robust qualification data.
Third, regional supply strategy and qualification speed will become more decisive in capturing volume. As raw material constraints persist and regulatory review lengthens, customers will favor suppliers that can reduce logistics risk, maintain consistent lot quality, and provide standardized compliance documentation. Capacity expansions in or near key demand regions, paired with efficient qualification support, will help secure long-term supply agreements. The downside risk is that supply expansion without feedstock diversification or regulatory readiness can strand capital in grades that lose competitiveness as customer expectations evolve.
Actionable Recommendations for Decision Makers
For manufacturers and material specifiers, the priority is to align grade selection with application-specific performance thresholds while building sustainability and regulatory readiness into the sourcing decision early. Evaluate LCP grades not only on thermal and flow properties but also on qualification timelines, feedstock credentials, and regional supply reliability. Where electrification, high-frequency electronics, or precision components are involved, prioritize grades with demonstrated performance in relevant thermal, flame, and dimensional stability conditions, and confirm that the supplier can support traceable documentation and accelerated qualification.
For investors and corporate strategists, the market rewards focused exposure to high-value applications and producers with diversified resin portfolios, regional supply footprints, and credible sustainability integration. Monitor consolidation activity, capacity additions, and product launches that deepen positioning in ICT, mobility, and precision medical or aerospace segments. Assess feedstock strategy and regulatory preparedness as leading indicators of commercial resilience, since these factors increasingly determine how quickly new grades can reach customers and how sustainably margins can be defended amid raw material volatility.
For procurement and supply chain leaders, the strategic question is no longer whether LCP delivers performance, but which supplier can deliver performance consistently under evolving compliance and sourcing expectations. Negotiate for data transparency, qualification support, and regional supply assurance alongside unit pricing. Build multi-grade sourcing strategies that balance performance-critical applications with cost-sensitive uses, and ensure that sustainability claims are supported by verifiable mass-balance or feedstock certification rather than generic messaging. Detailed segment-level volume patterns, regional demand distribution, and customized procurement or investment scenarios can sharpen these decisions significantly, and the complete market report provides the granular data needed to translate these strategic insights into concrete sourcing, investment, and product-development actions.
For detailed analysis of this topic, please visit the official page: Main-Chain Liquid Crystalline Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com