

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
High Temperature Superconductor Market: Why 11.5% CAGR and 2G HTS Shifts Define 2032 Growth
By pmarketresearch, 2026-09-21
Unlocking the High Temperature Superconductor Market: Strategic Trends and Commercial Horizons
The high temperature superconductor (HTS) market has transitioned from a niche technology space to a strategic battleground for energy infrastructure, advanced manufacturing, and next-generation computing. Over the past five years, global revenue has expanded from a modest base to a meaningful commercial tier, and the trajectory toward the end of the decade suggests an inflection point rather than a linear continuation. With a compound annual growth rate of 11.5 percent across the 2026 to 2032 horizon, the market is not merely expanding in size; it is evolving in structure, application mix, and competitive intensity. For executives and investors, the central question is no longer whether superconductors will reach broader commercial relevance, but where value will concentrate and which capabilities will separate winners from laggards.
Market Snapshot: Size, Structure, and the Emerging Inflection
The HTS market crossed from incremental expansion into a more pronounced upward phase beginning in 2023, with momentum carrying through 2025 and setting the stage for a faster growth cadence in the forecast period. Revenue progression over the historical window reflects steady adoption punctuated by acceleration as certain applications moved from demonstration to early commercial deployment. Looking ahead, the forecast figures indicate a market that does not simply add increments each year but gains pace as the addressable base broadens and more projects convert into procurement commitments. By 2032, the market is projected to reach a materially higher revenue level than today, implying that the cumulative value created over this window will be substantial relative to the starting point.
This trajectory is not uniform across the landscape. The market remains decentralized, with a relatively modest concentration among the largest players. Such fragmentation is typical of an industry where niche applications, regional demand patterns, and differentiated wire and system technologies coexist. It also signals that leadership positions are still being defined, and that the structure of the market may shift as consolidation, partnerships, and scale-up strategies mature. For decision-makers, the implication is clear: the field is open enough that strategic choices made now can influence positioning, yet concentrated enough in key technologies and regions that late movers may face steeper integration costs or higher barriers to performance credibility.
Defining Challenges at the Current Inflection Point
Despite the growth outlook, three challenges are shaping how value accrues and which business models prove durable. The first is the tension between performance gains and manufacturing scalability. As application requirements push toward higher current densities, stronger magnetic fields, and more demanding operating conditions, the industry is being asked to deliver consistency at volume. Producing advanced conductor materials with tight defect tolerances and repeatable performance remains a central bottleneck, especially as demand in priority segments begins to outpace available capacity. This is not merely a production issue; it is a commercial qualification issue, because reliability testing and standards development continue to be prerequisites for broader adoption in grid infrastructure, transport, aerospace, and high-field environments.
The second challenge is the cryogenic ecosystem. Even as HTS materials lower the temperature requirements relative to low-temperature alternatives, commercial-scale deployment still depends on reliable cooling systems that are long-lived, low-maintenance, and cost-effective. The performance of the conductor and the practicality of the cooling architecture cannot be optimized in isolation. Projects that succeed tend to integrate wire selection, thermal management, and installation constraints as a single system problem rather than as separate procurement item. This interdependency raises the barrier to entry for component-only suppliers and rewards players who can deliver integrated, field-ready solutions.
The third challenge is the evolving but still maturing regulatory and standardization context. HTS technologies generally operate within existing frameworks, but the pathway to faster deployment increasingly depends on industry-led standardization efforts that reduce compliance ambiguity and create confidence in performance verification. Efforts around reference measurement methods and interoperability expectations are helping, but broad industrial acceptance still requires continued qualification work and consistency in how performance claims are validated. For companies and buyers alike, the practical consequence is that leadership in standards engagement and credible testing can become a competitive asset, not just a compliance exercise.
Core Drivers Reshaping the Market
Performance breakthroughs expanding the application frontier
A decisive driver is the ongoing improvement in wire and tape performance that broadens the feasible application envelope. Recent product and exhibition activity signals that rare-earth-based HTS tapes are reaching higher engineering current density levels and enabling more demanding magnet and power applications. At the same time, independent development programs are targeting faster tape production lines to support high-field magnets, power transmission, fusion, and even electric aircraft concepts. These advances matter because performance improvements do more than refine existing products; they open new commercial contexts where superconductors offer advantages in footprint, efficiency, or field intensity that conventional alternatives cannot match.
The strategic significance of these breakthroughs is not limited to scientific credibility. In industrial settings, a step change in performance can reduce system size, lower cooling burden, improve power density, or enable designs that were previously impractical. For manufacturers and system integrators, that translates into differentiation potential and the ability to enter higher-value segments. For investors, it reframes risk: the opportunity is less about a single breakthrough product and more about whether a company can sustain a performance roadmap while scaling production and qualification at commercial speed.
Policy momentum and the demand signal from strategic priorities
Public-sector interest continues to shape demand by funding research, demonstration, and manufacturing initiatives that de-risk commercialization pathways. Programs associated with national energy and advanced technology priorities are supporting projects that target both end-use applications and production capability. Such support does not guarantee commercial success, but it does help bridge the gap between laboratory performance and field-ready systems, especially where capital intensity, qualification requirements, or scale-up complexity would otherwise slow private investment.
The policy environment is also reinforcing the importance of standards and interoperability. As more consortia and public agencies work to align expectations around performance verification and deployment, the regulatory direction leans toward reducing ambiguity rather than creating new barriers. That matters commercially because predictable qualification and measurement practices can shorten procurement cycles and give early movers a stronger case for adoption in infrastructure and industrial projects.
Demand-side shifts favoring power density and advanced computing
On the demand side, the most visible new driver is the pressure on power delivery in high-density environments, particularly in AI data centers and other facilities where energy throughput, space constraints, and reliability requirements are intensifying. HTS power delivery concepts are being piloted in contexts that simulate these operating conditions, and the successful demonstration of compact power delivery solutions points to a practical use case where superconducting cables can address real operational constraints. At the same time, demand from fusion energy and high-field magnet applications continues to provide a high-performance anchor for the technology roadmap, even if those applications follow longer development cycles.
This demand shift changes the commercial conversation. Traditional HTS applications have long relied on niche but stable use cases; the emerging mix adds demand sources that are larger in scale potential and more sensitive to power density and reliability. For procurement leaders and infrastructure planners, the implication is that superconductors should be evaluated not only on cost per unit but on system-level value, including reduced footprint, energy efficiency, and operational resilience in demanding environments.
PW Consulting Chemical & Energy Research Center
Supply-chain evolution and the scaling premium
A further driver is the evolving supply chain around conductor manufacturing. Demand growth is creating a premium for scale, consistency, and availability, and the companies that can expand production while maintaining performance quality will gain leverage. This dynamic is reshaping strategic behavior: some players are positioning around proprietary wire platforms, others are extending into integrated systems, and several are aligning with customer programs that require long development horizons. Scaling is not simply an operational target; it is becoming a strategic differentiator because the ability to supply qualified material reliably directly affects which applications can move forward on schedule.
The same dynamic applies to the broader ecosystem. As applications broaden, the market increasingly rewards partners who can coordinate conductor supply, cooling architecture, installation requirements, and qualification support. That integrated capability is difficult to replicate quickly, which gives incumbents with credible production and application experience a meaningful advantage. At the same time, new entrants with novel manufacturing approaches or targeted platform strategies can still find room to compete if they solve a specific bottleneck or serve a specialized application with clear performance economics.
Competitive Landscape: Leaders, Positioning, and Evolution
The competitive field includes mature manufacturers of superconducting wires and magnets, companies specializing in second-generation HTS tapes and cables, and newer entrants pursuing high-performance wire platforms and system-level power delivery. The group spans North America, Europe, Japan, China, and Russia, reflecting both long-standing technology bases and regional demand patterns. Rather than a single dominant leader, the market is characterized by differentiated capabilities, where advantage often comes from the combination of wire technology, application knowledge, and the ability to support qualification and deployment.
Several patterns stand out in how leaders are positioning themselves. One is the focus on advanced tape platforms and high-field magnet suitability, where performance density is becoming a defining attribute. Companies exhibiting rare-earth HTS tape developments and targeting fusion and high-field applications are building credibility in segments where performance thresholds are especially demanding. Another pattern is the move toward application-specific integration and commercial pilots, particularly in power delivery and grid-related use cases. Pilots that demonstrate practical power delivery in relevant environments help convert technical promise into commercial confidence and can serve as reference points for broader adoption.
Strategic differentiation and the shift toward integration
Differentiation is increasingly tied to more than material supply. In a market where cooling systems, reliability testing, and standards are central to adoption, manufacturers that provide usable solutions rather than standalone components are gaining strategic ground. This includes aligning wire performance with system constraints, supporting qualification for industrial use, and participating in standardization efforts that shape how performance is verified and compared. The companies that do this well are better placed to win projects that require multi-stakeholder confidence, where technical performance is necessary but not sufficient.
Another differentiator is the speed and credibility of scaling. In an environment where demand is beginning to outpace some supply capacities, the ability to expand production without sacrificing quality becomes a competitive lever. Board appointments, funding-supported production projects, and product catalog releases all signal how firms are trying to align capability with market timing. These moves are not isolated events; they are indicators of how companies plan to compete on scale, application breadth, and readiness for commercial deployment.
Market evolution: consolidation, specialization, and new entry points
The market structure appears likely to evolve through a mix of specialization and selective consolidation. On one hand, distinct technology niches—high-field magnets, power cables, fault current limiters, imaging systems, and advanced transport applications—create room for firms with deep application expertise. On the other hand, as projects grow in scale and as customers seek fewer, more capable partners, there is pressure for integration and strategic alignment around key platforms and regions. New entrants are likely to continue appearing where they can address a specific bottleneck, such as manufacturing speed, wire performance in a particular temperature and field regime, or compact power delivery for dense load centers.
For incumbents, the strategic challenge will be to preserve differentiation while building scale and credibility in the applications that matter most. For challengers, the opportunity lies in solving a concrete constraint that larger players have not yet fully addressed, then expanding from that foothold into adjacent applications. For buyers, the practical takeaway is that supplier selection should weigh not only current product specifications but also roadmap commitment, qualification support, and the ability to deliver in the specific operating context of the project.
Future Outlook: Three Trends Shaping the Next Few Years
Trend one: performance-led expansion into higher-value applications
Over the next three to five years, continued performance improvements are likely to pull HTS applications further into higher-value, higher-constraint use cases. Higher engineering current density and better high-field behavior will make superconductors more attractive in contexts where space, efficiency, and field intensity matter most. This expands the addressable market beyond traditional niches and increases the commercial stakes for companies with credible performance roadmaps. The opportunity for businesses is to align product development with the applications that can capture premium value, rather than competing solely on broad volume in commoditizing segments. The uncertainty is that performance claims must be matched by consistent manufacturing and credible qualification, or the market will reward only those claims that survive real-world scrutiny.
Trend two: scaling production and integration as decisive competitive factors
Scaling is likely to become a more explicit competitive battlefield. As demand broadens, the companies that can deliver qualified conductor material at volume, with dependable performance and acceptable lead times, will be positioned to capture the most important projects. At the same time, integration capability—linking conductor choice, cooling architecture, installation logistics, and standards-aligned testing—will increasingly influence procurement decisions. Businesses that build this integrated competence will have an advantage in winning multi-year infrastructure and industrial projects. The risk is that scaling without quality control or application support can damage reputation and slow future adoption, especially in sectors where reliability is paramount.
Trend three: stronger emphasis on standards, verification, and ecosystem alignment
A third trend is the likely deepening of standards and verification activity as commercial deployment expands. As more projects move into operation, buyers and regulators will demand clearer performance verification, interoperability expectations, and consistent qualification approaches. Industry consortia and reference measurement efforts are already shaping part of this environment, and their influence is likely to grow. This trend creates an opportunity for companies that actively participate in standards alignment and credible testing, because it can reduce ambiguity for customers and strengthen the commercial case for adoption. The uncertainty is that standards development is iterative and not always fast; companies that depend on rapid regulatory clarity may find progress uneven, requiring parallel investment in technical and commercial readiness.
Worldwide Low Temperature Superconductors Market
Strategic Actions for Decision-Makers
For manufacturers and technology developers
Focus investment on the intersection of performance, scale, and qualification. Advancing a wire or tape platform is necessary, but the differentiator will increasingly be the ability to produce consistently at scale and to support customers through qualification for industrial and infrastructure use. Prioritize the applications where performance improvements translate into the clearest system-level value, and build reference cases that reduce perceived risk for buyers. Engage early with standardization and measurement efforts, because credible participation can shorten adoption cycles and strengthen market positioning. Where possible, align production expansion with confirmed demand signals to avoid overbuilding capacity before it is needed, while still maintaining enough momentum to capture first-mover advantage in priority segments.
For investors and strategic capital allocators
Evaluate the market through the lens of application economics and execution risk rather than headline growth alone. The most attractive opportunities are likely to be those where performance gains directly improve system value, where scaling can be achieved with disciplined quality control, and where the company has a credible path to integration or strong partnership leverage. Assess whether a business is positioned around a durable platform, a specific high-value application, or a system-level solution, because each carries different risk and return profiles. Pay attention to signals that indicate readiness for commercialization, such as pilot completion, qualified production expansion, and engagement with industrial customers or standards bodies. Avoid assuming that technical promise alone will convert into market share; execution, consistency, and ecosystem relationships will determine which players capture lasting value.
For procurement, infrastructure planners, and demand-side buyers
Treat superconductor-based options as system-level investments rather than component purchases. Evaluate total cost, reliability, cooling requirements, installation constraints, and qualification status together, because the value case often depends on how well these elements fit the operating environment. Use pilot and demonstration results as evidence, but verify that performance claims are supported by credible measurement and testing practices relevant to your sector. For projects in power-dense or high-reliability contexts, consider how superconducting solutions may reduce footprint or improve efficiency where conventional alternatives are constrained. Build supplier evaluation criteria that include roadmap credibility, production readiness, and support for standards-aligned qualification, since these factors will influence long-term performance and operational risk more than initial specifications alone.
Superconductor Market
The strategic picture for the HTS market is one of expanding opportunity shaped by performance progress, scaling pressure, and a maturing standards environment. The window for positioning is open, but it is narrowing in the most valuable segments where execution and credibility increasingly separate leaders from the rest of the field. For organizations that need detailed segmentation data, regional and application-level projections, and tailored scenario planning, a fuller research set can provide the finer granularity required to translate these trends into specific investment, production, and procurement decisions.
For detailed analysis of this topic, please visit the official page: High Temperature Superconductor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
5-Aminolevulinic Acid Market: Why 9.8% CAGR and Pharma’s Dominance Reshape 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the 5-Aminolevulinic Acid Market: A 2032 Outlook
The global 5-Aminolevulinic Acid (5-ALA) market has transitioned from a specialized biochemical niche to a multi-sectoral growth engine, driven by converging advances in photodynamic therapies, agricultural biotechnology, and cosmetic formulations. With a compound annual growth rate of 9.8% through 2032, the sector reflects a disciplined expansion pattern rather than speculative hype. The trajectory from 2020 to 2032 demonstrates consistent value creation, with revenue rising steadily as clinical validation, manufacturing scale-up, and cross-industry adoption reinforce each other. Yet beneath the headline growth metrics lies a more nuanced reality: regulatory fragmentation, formulation bottlenecks, and an evolving competitive map are reshaping how value is captured. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where capital, R&D, and commercial execution will yield the highest risk-adjusted returns.
This analysis examines the structural drivers, competitive dynamics, and forward-looking inflection points that will define the 5-ALA landscape over the next three to five years. The goal is to translate macroeconomic momentum into actionable strategic positioning, highlighting where operational excellence, regulatory navigation, and application diversification intersect.
Market Snapshot and Core Challenges
The market has demonstrated resilient upward momentum, expanding from a baseline in 2020 to an estimated valuation in 2025, with projections pointing toward a multi-hundred-million-dollar scale by 2032. The growth profile is characterized by sustained, double-digit compounding that reflects both volume expansion and value migration toward higher-margin applications. Rather than a single breakthrough driving this trajectory, the expansion is the product of incremental clinical adoption, agricultural pilot scaling, and formulation optimization across multiple end-use sectors.
Despite this momentum, three structural challenges are redefining the commercial playbook.
Regulatory Uncertainty and Classification Gaps
The regulatory landscape for 5-ALA remains uneven across major markets. In pharmaceutical and medical device contexts, approvals have progressed through established clinical pathways, enabling commercialization in specific diagnostic and therapeutic applications. Outside these narrow indications, however, classification remains unresolved. In the United States, the absence of definitive guidance on whether 5-ALA qualifies as a New Dietary Ingredient has created ambiguity for supplement and functional nutrition ventures. Similarly, in the European Union, the compound continues to navigate Novel Food review processes, with no final determination enabling broad dietary supplement deployment. This regulatory lag is not merely a compliance issue; it dictates which business models can scale, which distribution channels remain accessible, and how quickly new formulations can reach consumers or enterprise buyers.
PW Consulting Chemical & Energy Research Center
Formulation and Delivery Optimization Constraints
While 5-ALA’s biochemical properties are well understood, translating laboratory efficacy into consistent clinical or agricultural outcomes remains a non-trivial engineering challenge. Photodynamic applications require precise timing, concentration control, and tissue-specific uptake, while agricultural and cosmetic use cases demand stability, dermal or foliar compatibility, and shelf-life reliability. Recent clinical data has demonstrated that extending the administration window for oral 5-ALA can improve procedural flexibility in diagnostic settings, underscoring that delivery protocols—not just molecule availability—are critical value drivers. Companies that treat formulation and dosing protocols as afterthoughts risk ceding margin and differentiation to competitors who integrate pharmacokinetics, user experience, and application-specific optimization into their core product architecture.
Supply Chain Concentration and Quality Standardization
The market exhibits moderate concentration among established suppliers, with a meaningful share of high-purity material flowing through a limited set of manufacturers and regional production hubs. This structure offers efficiency advantages but introduces vulnerability: batch consistency, regulatory documentation, and specialty-grade purification remain bottlenecks for downstream formulators. Moreover, as demand expands beyond research-grade supply into commercial-scale pharmaceutical, agricultural, and cosmetic volumes, the industry faces pressure to standardize quality frameworks while managing cost structures. Firms that rely on fragmented sourcing or lack robust analytical validation risk delays, compliance friction, and margin erosion as end-market specifications tighten.
Key Growth Drivers Reshaping the Landscape
The 5-ALA market’s expansion is not uniform; it is being pulled forward by a set of interlocking drivers that reward companies capable of aligning technical, regulatory, and commercial execution.
Clinical Validation and Fotodynamic Therapy Evolution
The most consequential driver is the maturation of photodynamic diagnosis and therapy applications. Clinical evidence continues to reinforce the utility of 5-ALA as a photosensitizing precursor in tumor visualization and targeted treatment protocols. Recent regulatory acknowledgments that extend oral administration windows for specific diagnostic procedures illustrate how clinical data can directly translate into procedural flexibility and broader adoption. As hospitals and specialty clinics integrate these protocols into routine workflows, demand shifts from experimental or pilot-scale use toward standardized, repeatable procurement. This transition elevates the importance of product reliability, regulatory documentation, and clinician training support, turning commercial success into a function of ecosystem enablement rather than molecule supply alone.
Policy and Regulatory Pathway Clarification
While regulatory uncertainty remains a challenge, incremental policy progress is also a growth catalyst. Where health authorities provide clearer indications for medical use, downstream investment becomes more predictable. In parallel, agricultural and cosmetic applications are shaping their own compliance trajectories, often leveraging existing biostimulant, cosmetic ingredient, or research-grade frameworks to accelerate go-to-market timelines while broader dietary classifications remain unresolved. The companies that navigate this environment effectively do not wait for a single global ruling; they design application-specific regulatory strategies that align with the fastest available pathways, using clinical or agronomic data packages to support targeted approvals and market access.
Demand-Side Shifts in Agriculture and Personal Care
Beyond the clinic, demand-side behavior is evolving rapidly. In agriculture, the push for yield optimization, stress tolerance, and reduced dependency on conventional inputs has elevated interest in biochemical biostimulants. 5-ALA’s role in chlorophyll synthesis and plant metabolic pathways positions it as a candidate for precision agricultural programs, particularly in markets where sustainability mandates and input cost pressures coincide. In cosmetics and personal care, consumer interest in biologically derived actives and skin-health benefits has spurred formulation exploration, with brands seeking ingredients that can anchor marketing narratives in mechanistic plausibility rather than purely cosmetic claims. These demand shifts expand the addressable base for 5-ALA beyond traditional medical channels, but they also require differentiated value propositions, safety data packages, and supply reliability tailored to each sector’s procurement standards.
Manufacturing and Cost Structure Improvements
Scaling production of high-purity 5-ALA and its salt forms has become a strategic priority as multi-sector demand intensifies. Advances in synthesis routes, purification processes, and quality control analytics are gradually improving cost structures and batch-to-batch consistency. The effect is twofold: it lowers barriers for formulators seeking dependable supply, and it enables incumbents to expand margins while investing in application-specific development. However, cost leadership alone is unlikely to secure durable advantage. The more durable moats are emerging around integrated quality systems, regulatory-ready documentation, and partnerships that link manufacturing capability with formulation science and end-market technical support.
Competitive Landscape and Strategic Positioning
The competitive field spans specialty pharmaceutical developers, chemical suppliers, research-grade distributors, and regional manufacturers pursuing agricultural and cosmetic applications. Rather than competing solely on price, leading players are carving out positions based on application focus, regulatory readiness, and technical service capabilities.
Differentiated Playbooks Across the Value Chain
Several companies have built recognizable identities around specific use cases. In the medical and diagnostic segment, firms with approved 5-ALA-based products for photodynamic visualization have leveraged clinical evidence, procedural training, and regulatory approvals to anchor their positions. Their advantage lies not simply in supplying the molecule, but in enabling clinical adoption through protocol clarity, product consistency, and medical affairs support.
In the research and reagent space, established chemical suppliers compete on purity certification, documentation reliability, and breadth of catalog support. Their customers prioritize batch traceability and analytical validation, which makes quality systems and supplier credibility central to retention. In the industrial and specialty chemical segment, manufacturers that can provide high-purity intermediates and customized synthesis options gain relevance among formulators who need flexibility in specifications and scale. Meanwhile, regional players in Asia have expanded their footprint by addressing both pharmaceutical and agricultural biostimulant demand, often combining API production with formulation exploration tailored to local crop and market conditions.
Strategic Advantages and Ecosystem Positioning
The most defensible positions emerge where molecule supply intersects with application expertise. Companies that combine reliable purification and manufacturing with regulatory documentation, stability data, and end-use technical support create friction for customers considering multi-sourcing or switching to lower-cost alternatives. In diagnostic and therapeutic niches, approval status and clinical protocol alignment function as strong barriers to entry. In agricultural and cosmetic channels, success increasingly depends on demonstrating consistent performance, safety profiles, and supply continuity rather than competing on commodity pricing alone.
This landscape is also being shaped by selective external collaboration. Major pharmaceutical and biotechnology players have shown interest in exploring enhanced 5-ALA formulations for photodynamic applications, signaling that formulation innovation and partnership-driven development can accelerate value creation even when internal R&D capacity is constrained. Such collaborations often focus on improving efficacy, expanding treatment or diagnostic windows, or tailoring delivery characteristics, which reinforces the broader industry shift toward formulation-led differentiation.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The market is neither fully consolidated nor highly fragmented; it is evolving through a combination of specialization and selective consolidation. In research-grade and reagent segments, brand trust and analytical reliability support stable positioning, while in commercial-scale pharmaceutical and agricultural segments, scale, regulatory readiness, and application support increasingly matter. New entrants are likely to appear where application gaps remain: niche cosmetic actives, regional agricultural biostimulant programs, and next-generation formulation concepts that improve stability, targeting, or ease of use. The strategic implication is clear: competitive advantage will belong to firms that define a precise application focus, build the corresponding regulatory and technical evidence base, and align supply chain capabilities with that focus rather than pursuing undifferentiated volume expansion.
5-Aminolevulinic Acid Hydrochloride Market
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, three trends are likely to shape how value is created and captured in the 5-ALA market.
Application-Specific Formulation as a Core Differentiator
The next phase of growth will increasingly reward companies that tailor 5-ALA products to specific end-use requirements rather than selling a uniform molecule across all channels. In medical and diagnostic settings, this means optimizing administration timing, concentration ranges, and procedural compatibility. In agriculture, it means developing formulations aligned with foliar application, stress resilience, and compatibility with existing crop management programs. In cosmetics, it means prioritizing stability, sensory attributes, and claim-supportive safety data. The commercial opportunity lies in building a portfolio architecture where each product variant is backed by the right evidence package, regulatory positioning, and technical support for its intended market.
Levulinic Acid Market
Regulatory Clarity as a Market Access Accelerator
As regulatory frameworks continue to mature, segments that secure clearer pathways will experience faster scaling, while ambiguous segments will remain dependent on workaround strategies or narrower use cases. Companies that proactively invest in data generation, dossier preparation, and early engagement with health authorities will be better positioned to convert scientific potential into commercial reach. Conversely, businesses that rely on regulatory ambiguity as a temporary advantage may face increasing scrutiny as standards tighten and downstream customers demand demonstrated compliance. The strategic lesson is to treat regulatory preparation as a growth investment rather than a compliance cost.
Supply Chain Integration and Regional Capacity Expansion
Demand diversification across regions and applications will pressure the industry to build more resilient, regionally balanced supply capability. Where production remains overly concentrated, downstream buyers will seek redundancy, quality guarantees, and localized technical support. The likely response is a mix of expanded regional manufacturing, strengthened analytical and quality frameworks, and closer integration between suppliers and formulators. This shift creates opportunities for players that can offer dependable supply, transparent documentation, and the flexibility to support application-specific requirements. It also raises the stakes for firms that cannot meet increasing quality and consistency expectations as commercial volumes grow.
These trends carry inherent uncertainty. Regulatory timelines can shift, clinical adoption can plateau if procedural barriers persist, and agricultural or cosmetic adoption can be sensitive to economic cycles and input-cost dynamics. Competitive entry may compress margins in certain segments, and formulation claims will face higher scrutiny as markets mature. The businesses that navigate these risks most effectively will be those that combine disciplined application focus with credible data, robust quality systems, and flexible commercial models.
Strategic Recommendations for Decision-Makers
For executives and investors evaluating exposure to 5-ALA, the opportunity is real but increasingly segmented. Value creation will depend less on broad commodity positioning and more on targeted application strategies, regulatory alignment, and supply chain reliability.
For Manufacturers and Product Developers
- Define a clear primary application focus and build the supporting evidence package, quality documentation, and technical support around it. A molecule-centric strategy without application-specific differentiation is increasingly vulnerable to competition and margin pressure.
- Treat formulation science and delivery protocols as core IP. Improvements in stability, timing flexibility, compatibility, and ease of use can create defensible positioning, especially in medical and diagnostic channels where procedural fit matters.
- Invest in regulatory readiness early. Proactive data generation, dossier preparation, and engagement with relevant authorities reduce time-to-access and improve customer confidence, particularly when downstream buyers are risk-averse.
For Investors and Strategic Capital Allocators
- Evaluate exposure by application pathway rather than by aggregate market growth alone. Segments with clearer regulatory status, established clinical or agronomic use, and repeatable procurement cycles tend to offer more predictable value capture than ambiguous or early-stage segments.
- Look for combination value: manufacturing reliability plus formulation capability plus application-specific support. Companies that only compete on volume or price may face structural margin risk as quality and compliance expectations rise.
- Monitor partnership activity and selective collaborations that signal formulation innovation or expanded indications. Such moves often preview where the next wave of differentiation will emerge.
For Procurement and Commercial Buyers
- Prioritize supplier consistency, analytical validation, and documentation completeness over lowest-unit-cost options, especially when formulations are integrated into regulated or performance-sensitive workflows.
- Align sourcing strategies with end-use requirements. A supplier strong in research-grade reliability may not be the best fit for commercial-scale agricultural or cosmetic programs, and vice versa.
- Build contingency planning into supply agreements. As demand grows across multiple sectors, multi-source strategies, clear quality specifications, and contractual clarity on documentation and batch traceability can reduce operational risk.
Moving from Insight to Execution
The 5-Aminolevulinic Acid market is entering a phase where breadth of opportunity is giving way to the need for precision in execution. Growth will continue, but the distribution of value will increasingly favor companies that combine scientific credibility, application-specific product design, regulatory preparedness, and dependable supply. For decision-makers, the strategic task is to identify which segment aligns with organizational capabilities, which evidence and compliance gaps must be closed, and how supply partnerships should be structured to support growth without exposing the business to unnecessary quality or continuity risk.
Detailed segmentation data, company-level profiling, and scenario-based forecasts can materially improve the quality of strategic planning in this environment. For organizations seeking a deeper, data-rich view of regional dynamics, application breakdown, competitive positioning, and tailored commercial options, the full PW Consulting market research report provides the structured detail and customized analytical support needed to translate these trends into concrete execution plans.
For detailed analysis of this topic, please visit the official page: 5-Aminolevulinic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Titanium Sponge Market 2026: Beyond the 5.25% CAGR to High Purity & Aerospace Drivers
By pmarketresearch, 2026-09-21
Titanium Sponge Market: Strategic Shifts and Commercial Opportunities Through 2032
The titanium sponge market has entered a decisive phase. Between 2020 and 2025, the sector moved from a post-pandemic recovery trajectory to a period of sustained expansion, reaching an estimated 236.8 million USD in 2025. Over the following seven years, the market is projected to grow at a compound annual rate of 5.25 percent, crossing the 338 million USD threshold by 2032. These figures reflect more than steady demand. They point to a structural realignment in how titanium sponge is produced, traded, and deployed across aerospace, medical, and industrial applications. For executives and investors, the opportunity lies not in the headline growth alone, but in understanding where value is being created, where supply vulnerabilities are concentrated, and which strategic moves will separate winners from the rest of the pack.
Worldwide Ferro Titanium Market
The current landscape is defined by a tension between robust end-use demand and persistent structural constraints. Production remains concentrated, with the top three players controlling roughly 45.6 percent of the market and the top five capturing about 68.2 percent. That concentration provides stability in normal conditions, but it also means that disruptions at a single facility or in a single trade corridor can ripple quickly through global procurement channels. At the same time, the market is navigating a pivotal transition: traditional sponge-dependent supply chains are being questioned by new domestic production initiatives, while trade policy is reshaping cost structures and routing decisions. The result is a market that is growing, but growing unevenly, with the most attractive opportunities concentrated in segments that can secure reliable feedstock, navigate regulatory shifts, and align with high-value downstream applications.
Several challenges stand out as defining issues for the next cycle. First, import dependency remains a strategic exposure for key consuming markets. The United States, for example, relies almost entirely on imports for titanium sponge, and import volumes reached a historical high in 2025. That level of reliance creates pricing sensitivity and supply continuity risk, particularly when geopolitical tensions or logistical bottlenecks intersect with concentrated sourcing patterns. Second, the industry is facing a policy-driven inflection point. Tariff adjustments and defense-oriented funding initiatives are altering the economics of domestic versus imported feedstock, forcing producers and buyers to reconsider long-standing procurement assumptions. Third, the market must balance quality and cost pressures. High-purity grades continue to command strong demand in aerospace, defense, and specialized industrial applications, while commercial-grade volumes must compete on scale and efficiency. Companies that cannot manage this dual dynamic risk margin compression or customer migration.
Key Drivers Reshaping the Market
The growth trajectory is being pulled forward by a cluster of interrelated forces. None of these drivers act in isolation; each reinforces or constrains the others, which is why strategic planning must look across technology, policy, demand behavior, and supply chain economics simultaneously.
Technology Innovation and Process Breakthroughs
One of the most consequential developments is the push to bypass or reduce reliance on traditional sponge production. New domestic initiatives are targeting a mineral-to-metal pathway that could change the cost and sourcing architecture of titanium supply. In early 2025, a U.S.-based innovator received an award of up to 47.1 million USD from the Department of Defense to accelerate an integrated domestic mineral-to-metal titanium supply chain. A subsequent 12.5 million USD in additional government funding followed later in the year to expand production operations. These moves matter because they signal a shift from incremental efficiency gains to a more fundamental rethinking of how titanium reaches end users. If successful, such approaches could reduce exposure to imported sponge, shorten lead times for critical applications, and create new competitive dynamics for established producers. The strategic implication is clear: process innovation is no longer a back-office concern. It is becoming a source of competitive advantage and a potential differentiator in procurement decisions, especially where supply security and performance specifications intersect.
Policy and Regulatory Environment
Trade policy is reshaping the market with real financial consequences. Unwrought titanium metal now faces a 15 percent ad valorem tariff under normal trade relations, a change that directly affects landed cost and sourcing calculus. At the same time, broader industrial and defense policy is encouraging domestic capacity and supply chain resilience. The combination creates a more complex decision environment for buyers and producers alike. Companies that previously optimized purely for price must now weigh tariff exposure, shipping routing, and the reliability of alternative sources. Producers outside the United States must factor in how tariff structures influence demand elasticity and whether they can maintain share through quality, service, or localized partnerships. For market participants, the regulatory shift is not a one-time adjustment; it is a persistent variable that will shape contract structures, inventory strategies, and investment timing.
Demand-Side Evolution
Demand is being driven by applications where titanium's performance characteristics are difficult to substitute. Aerospace and defense remain the dominant demand centers, reflecting the material's strength-to-weight ratio, corrosion resistance, and proven track record in critical systems. Medical applications continue to expand as implant and device manufacturers seek biocompatible materials with long-term reliability. Industrial and chemical processing applications add a further layer of demand stability, particularly where equipment longevity and resistance to harsh environments justify the material cost. Importantly, demand is not simply rising in aggregate. It is becoming more selective. Buyers in high-stakes segments increasingly prioritize supply assurance, traceability, and consistent quality over marginal price differences. That shift rewards producers with strong process control and dependable delivery records, while exposing those that compete mainly on volume without differentiated quality or service.
Supply Chain and Cost Structure Dynamics
Cost structures are being recalibrated by a mix of tariff effects, logistics exposure, and feedstock concentration. Recent trade flow data underscores how concentrated sourcing patterns can become: in the first quarter of 2025, U.S. titanium sponge imports were estimated at roughly 10,500 metric tons, with a significant share coming from Japan, and smaller portions from Kazakhstan and Saudi Arabia. Full-year import volumes reached a historical high in 2025. These patterns illustrate both the scale of reliance and the geographic concentration that underlies it. For buyers, the practical consequence is that cost planning must account for more than unit price. It must include freight variability, tariff assumptions, supplier diversification options, and the potential for policy changes to alter the relative attractiveness of different source countries. For producers, the implication is that competitive positioning increasingly depends on reliability, transparency, and the ability to help customers manage supply risk, not just on production cost alone.
Competitive Landscape and Leading Strategies
The market's competitive structure is shaped by a mix of integrated incumbents, specialized high-purity producers, and newer entrants pursuing alternative supply chain models. The incumbents bring scale, established customer relationships, and deep process expertise. The specialists differentiate through purity, consistency, and application-specific expertise. The emerging challengers are attempting to redefine the pathway from raw material to finished metal, often with a focus on domestic production and reduced dependence on conventional sponge routes.
In the United States, TIMET stands out as a fully integrated producer with a long-standing facility and a direct connection to aerospace and defense demand through internal melt operations and mill products. Its strategic positioning rests on integration and proximity to end-use customers, which supports quality control and supply continuity. IperionX represents a different strategic play. Rather than competing along the same sponge-centric axis, it is developing a mineral-to-metal supply chain aimed at domestic production for defense and advanced manufacturing. This approach is designed to address import reliance directly and align with government priorities around supply security. The recent defense award and additional funding underscore how policy alignment can accelerate capital deployment and market entry for players with a complementary technological and strategic profile.
In Russia, VSMPO-AVISMA Corporation operates as a major producer of titanium sponge and ingot for aerospace, space, and shipbuilding, and is recognized as a global leader in high-volume titanium metal supply. Its scale and breadth of product offerings make it a significant force in global supply, particularly where large-volume commitments and established aerospace relationships matter. In Japan, Toho Titanium and Osaka Titanium Technologies both occupy important positions. Toho Titanium focuses on specialized titanium sponge and high-purity titanium for semiconductors and aerospace, emphasizing stable, high-quality metals. Osaka Titanium Technologies is among the world's largest producers of titanium sponge and ingot, supplying aerospace with diversified high-performance materials. Together, these Japanese producers illustrate how quality, specialization, and scale can coexist in a market where high-purity grades and reliable delivery are valued by demanding downstream sectors.
Titanium Powder Market
In China, Baoji Titanium Industry and Zunyi Titanium add further depth to the global landscape. Baoji Titanium is a state-controlled manufacturer of titanium sponge and mill products serving aerospace, military, and industrial use, reflecting the strategic importance of titanium within domestic industrial policy and defense-related supply chains. Zunyi Titanium specializes in high-purity titanium sponge and associated materials for aerospace, industrial, and chemical processing applications. These players highlight how regional industrial strategies and application-specific focus can reinforce market presence, particularly when aligned with local demand growth and government-supported capacity development.
The competitive landscape is evolving along three axes. Consolidation remains relevant where scale, integration, and customer lock-in create durable advantages. Differentiation is becoming more important in high-value segments, where purity, traceability, and reliability can command preference even when pricing is not the lowest. And new entry is taking a distinct form: rather than simply adding another conventional sponge plant, some players are pursuing alternative production pathways and aligning with policy incentives to address supply security concerns. For companies evaluating the landscape, the most useful question is not who is largest, but which strategic logic is most resilient under shifting tariff, sourcing, and demand conditions.
Forward Outlook: Trends to Watch Through the Mid-2020s
Looking ahead three to five years, several trends are likely to shape both opportunity and risk. These trends are not speculative overlays; they follow directly from current demand patterns, policy signals, and supply chain dynamics.
Reshoring and Supply Security as Strategic Priorities
Supply security is moving from a compliance concern to a core competitive variable. The combination of high import reliance, tariff adjustments, and defense-oriented funding creates a clear incentive for domestic or near-domestic capacity where feasible. The practical outcome is likely to be a gradual shift in sourcing strategies, with more buyers pursuing diversified supply bases, longer-term agreements, and closer coordination with producers who can offer transparency and resilience. For producers, this trend opens the door to partnerships and contracts that reward reliability and strategic alignment, not just price. For investors, it suggests that assets and technologies aligned with supply security objectives may command greater attention and support, provided they can demonstrate credible cost and scale trajectories.
Premiumization in High-Value Applications
Demand in aerospace, defense, and medical applications is likely to continue favoring high-purity and performance-grade material. As end uses become more exacting and as qualification cycles remain long, buyers will increasingly value consistency, documentation, and process control. This trend favors producers that can deliver reproducible quality and support customer requirements across qualification, production, and delivery. It also creates a two-tier dynamic in which commercial-grade volumes must compete on efficiency and cost while premium grades capture stronger positioning. Companies that can manage both tiers effectively, or that deliberately focus on the higher-value tier with clear differentiation, are better placed to protect margins in a market where tariff and logistics costs can otherwise erode profitability.
PW Consulting Chemical & Energy Research Center
Policy-Linked Investment and the Risk of Overcorrectment
Government funding and policy alignment are accelerating investment in new capacity and alternative processes. That is a positive signal for supply diversification, but it also introduces uncertainty. The pace of commercialization, the realism of cost expectations, and the durability of policy support all matter. If alternative pathways underdeliver on scale or cost, the market may revert toward established suppliers faster than some forecasts imply. If policy support shifts with budget priorities or geopolitical developments, investment timing and capacity planning may need to be recalibrated. The strategic lesson is to treat policy-driven momentum as an enabler, not a guarantee. Opportunities should be evaluated against operational realism, including feedstock availability, processing readiness, qualification requirements, and the ability to serve demanding customers at scale.
Implications and Action Options for Decision-Makers
For manufacturers, the priority is to strengthen supply resilience without surrendering cost discipline. That means revisiting sourcing concentration, evaluating alternative suppliers and routes, and understanding how tariff and logistics assumptions affect total landed cost. It also means aligning internal quality and qualification capabilities with the increasing selectivity of high-value customers. Manufacturers that can offer dependable delivery, clear documentation, and consistent quality will be better positioned to retain demand in aerospace, defense, and medical segments, where switching costs and performance requirements limit casual re-sourcing.
For investors, the most interesting question is where value will accrue as the market rebalances. Scale incumbents with integration and established customer relationships still offer stability, but the most dynamic upside may come from companies that can credibly reduce supply risk, improve process economics, or capture premium positioning in high-purity applications. Investment theses should account for policy exposure, commercialization risk, and the degree to which a company's strategy depends on continued favorable conditions versus structural advantages that persist across scenarios. Diversification across traditional and emerging supply models can help balance stability with optionality.
For procurement and supply chain leaders, the practical mandate is to move beyond unit-price benchmarking. Total cost of ownership should incorporate tariff scenarios, freight exposure, lead-time variability, and the reliability of alternative sources. Developing a diversified supplier base, building buffer strategies for critical programs, and engaging earlier with producers on qualification and capacity planning can reduce vulnerability to shocks. In markets where import reliance is high and trade policy is active, procurement decisions increasingly have strategic as well as operational consequences.
The titanium sponge market is not simply expanding; it is being restructured around supply security, policy alignment, quality differentiation, and process innovation. That creates a wider set of strategic choices than in prior cycles. Companies that understand the interplay of these forces can position themselves to capture growth where it is most durable, while managing exposure where concentration and policy uncertainty create risk. For those seeking a more granular view of segment splits, regional dynamics, competitive benchmarks, and scenario-based guidance, deeper market research can provide the detailed data and tailored recommendations needed to refine strategy and execution plans.
For detailed analysis of this topic, please visit the official page: Titanium Sponge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rubber Sheet Market 2026: Decoding the True Drivers Behind 4.4% CAGR Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Rubber Sheet Market
The global rubber sheet market has entered a phase of steady, investment-grade expansion. Fueled by consistent demand across industrial, automotive, and specialty manufacturing sectors, the market has scaled from 3.94 billion USD in 2020 to an estimated 4.89 billion USD in 2025. Forward-looking projections indicate the market will reach 6.64 billion USD by 2032, underpinned by a compound annual growth rate of 4.4 percent between 2026 and 2032. This trajectory reflects more than cyclical recovery; it signals a structural recalibration driven by material innovation, evolving regulatory frameworks, and shifting end-user expectations. For executives navigating procurement, production, or capital allocation, understanding the forces reshaping this arena is no longer optional.
Market Size, Growth Trajectory, and Structural Positioning
The revenue expansion observed over the past five years has been relatively uniform, though the composition behind the headline figures reveals important nuances. The market is not growing through a single vertical or geography but through a combination of mature industrial demand, emerging applications in healthcare and clean energy, and deliberate premiumization in material specifications. Asia Pacific continues to account for the largest revenue share, reflecting both manufacturing density and infrastructure build-out, while North America and Europe maintain strong positions anchored in automotive, chemical processing, and regulated industrial environments. Growth is not purely volume-driven; higher-margin specialty grades and performance-enhanced synthetics are gradually capturing a larger slice of total revenue, indicating a market that is incrementally shifting from commodity substitution toward value-engineered solutions.
Beneath the steady growth curve lies a competitive structure that remains moderately fragmented at the top but increasingly polarized in capability. The top three participants collectively command roughly 35 percent of market revenue, while the top five reach approximately 50 percent. This concentration suggests that scale, technical service, and supply chain reliability still differentiate winners, but it also leaves meaningful room for regional specialists, custom fabricators, and technology-focused entrants to compete on specification intensity rather than sheer volume. The market is not consolidating into a handful of dominant players; rather, it is stratifying into tiers where leadership is defined by material expertise, certification readiness, and the ability to translate application requirements into repeatable production processes.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the industry is navigating several pressure points that are reshaping competitive dynamics and margin structures.
-
Raw material volatility and sourcing complexity. Natural rubber pricing has experienced sharp movements recently, with futures trading above 230 US cents per kilogram in early June 2026, marking the highest level since January 2017. In India, official data from June 2026 recorded RSS1 at INR 30,462 per 100 kilograms and RSS4 at INR 26,500 per 100 kilograms. These price signals reflect supply constraints and geographic imbalances that ripple through formulation decisions, inventory planning, and pricing strategies across the value chain. For sheet producers and converters, this volatility is not a transient issue; it is becoming a structural cost-management challenge that demands more sophisticated hedging, blending, and specification triage.
-
Regulatory traceability and compliance burdens. The EU Deforestation Regulation has moved from policy concept to operational reality, requiring plot-level traceability and auditable sourcing for natural rubber entering premium export channels. This requirement is reshaping who can access high-value European markets, forcing supply chains to document origin, verify land-use practices, and build audit-ready systems. While the regulation primarily targets deforestation-linked commodities, its practical effect on the rubber sheet sector is significant: it raises the barrier to entry for premium natural rubber grades, accelerates the shift toward certified or synthetic alternatives, and rewards suppliers with transparent, digitally traceable sourcing infrastructure.
-
Performance versus cost tension in end-use applications. Automotive, chemical processing, mining, pharmaceutical, and healthcare buyers increasingly demand sheets that meet stricter mechanical, chemical, and environmental criteria without a proportional increase in cost. Meeting these expectations requires more than incremental grade improvements; it calls for formulation innovation, tighter process control, and often a willingness to invest in application-specific validation. Companies that treat specification requirements as a compliance checkbox rather than a value-creation opportunity risk losing share to competitors who can demonstrate measurable performance gains, lower lifecycle cost, or faster qualification cycles.
Core Drivers Reshaping the Market
The growth and differentiation underway in the rubber sheet market are not accidental. They are being pulled by several reinforcing forces that are altering where value is created and how companies compete.
Technological Innovation and Material Breakthroughs
Material science is steadily expanding the boundary of what rubber sheets can deliver in demanding environments. Formulation advances are enabling better resistance to oils, solvents, temperature extremes, and abrasion while maintaining flexibility and ease of fabrication. Equally important, the push toward sustainability is becoming a technology driver rather than a compliance burden. Recent industry moves illustrate this shift clearly: in September 2024, ContiTech introduced a new line of eco-friendly rubber sheets incorporating bio-based fillers designed to reduce carbon footprint. That same direction continued into 2025, when Envire Flooring launched Envire® Rubber Sheet & Tile with VOC emissions compliant with CA Section 01350 and FloorScore/GreenGuard Gold certification. These developments are not isolated product launches; they signal a broader transition in which environmental performance, indoor air quality, and carbon-intensity reduction are becoming specification criteria alongside traditional mechanical properties.
For manufacturers, this means innovation is increasingly multi-dimensional. Success depends on the ability to combine performance attributes with sustainability credentials, certification readiness, and consistent batch-to-batch quality. Suppliers that can deliver these combinations in repeatable production environments are gaining leverage in negotiations, particularly with buyers facing their own scope 3 targets or procurement mandates tied to low-emission materials.
Ribbed Smoked Sheet Rubber Rss Market
Policy and Regulatory Environment
Policy is moving from a background constraint to a front-line strategic variable. Environmental and sourcing regulations are compelling buyers and suppliers to treat traceability, emissions, and material provenance as core purchasing criteria. The EU Deforestation Regulation's plot-level traceability and auditable sourcing requirements are already influencing premium export channel access for natural rubber. While the regulatory burden is real, it also creates a sorting mechanism: suppliers with robust documentation, verified sourcing, and transparent chain-of-custody systems are better positioned to maintain or expand access to high-value markets, while those without such infrastructure face mounting commercial friction.
Beyond environmental rules, broader industrial safety and chemical management standards continue to shape specification choices. In regulated sectors such as pharmaceuticals, healthcare, and certain chemical processing environments, certification and emissions compliance increasingly determine which products can be considered at all. Regulatory momentum therefore has a dual effect: it compresses the addressable market for non-compliant offerings while expanding the premium for suppliers that can demonstrate credible compliance and test-ready documentation.
Rubber Flooring Market
Demand-Side Shifts in Buyer Behavior
Purchasing behavior is evolving from transactional price comparison toward total cost and risk evaluation. Automotive OEMs and tier suppliers, chemical manufacturers, mining operators, and healthcare and pharma buyers are increasingly weighing factors such as material consistency, certification status, supplier technical support, and lifecycle durability alongside unit price. This shift is particularly pronounced where sheet rubber is integrated into safety-critical, regulated, or high-uptime applications, because failure or variability carries consequences that far outweigh marginal cost differences.
At the same time, demand is diversifying. Automotive remains the largest application segment by revenue, reflecting continuing needs in sealing, vibration damping, gasketing, and component fabrication. Chemicals and mining applications contribute substantial volume, driven by containment, abrasion resistance, and harsh-environment performance. Meanwhile, pharmaceutical and healthcare use is expanding as hygiene, cleanliness, and low-emission requirements become more stringent. The result is a market in which demand is not only growing but also fragmenting into more specification-intensive pockets, each with distinct performance and compliance expectations.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by raw material dynamics, energy considerations, logistics complexity, and the premium attached to reliability. The recent surge in natural rubber futures and the elevated domestic price levels observed in key producing regions underscore how quickly input costs can move when supply tightness coincides with steady demand. For sheet producers, the implication is clear: cost management is no longer a matter of negotiating a single resin or latex price. It requires portfolio-level decisions about natural versus synthetic blending, grade selection aligned to application needs, inventory buffering strategies, and the use of alternative fillers or reinforcements where performance permits.
Supply chain resilience is becoming a competitive asset in its own right. Buyers are increasingly sensitive to lead-time stability, minimum order flexibility, technical responsiveness, and the ability to support custom or specialty configurations. This favors companies that have invested in integrated production capabilities, predictable quality systems, and the operational discipline to handle both high-volume standard grades and lower-volume specialty orders without sacrificing service levels. In a market where top-five players already command about half of total revenue, differentiated service and supply reliability can be as decisive as product attributes when contracts are awarded.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of regional manufacturers, custom fabricators, specialty material suppliers, and global industrial players. Each cluster approaches the market with a distinct value proposition, and the most successful firms are aligning their capabilities with the segments where they can win on specification and reliability rather than competing broadly on price alone.
WARCO, based in Orange, California, has built its position around a broad natural and synthetic sheet portfolio, including nitrile, EPDM, neoprene, silicone, HNBR, Viton, and custom spec-grade rubber for industrial and specialty uses. This breadth allows the company to serve buyers who require multiple elastomer types under a single sourcing relationship, simplifying procurement while maintaining the ability to match material properties to application demands. Aero Rubber Company in Tinley Park, Illinois, competes on volume and customization, producing custom molded, extruded, and fabricated rubber components alongside custom sheets and slabs. Its strength lies in integrated fabrication capability, which can reduce downstream processing burden for customers that prefer a more complete component solution rather than bare sheet material.
Hanna Rubber Company focuses on calendered sheet rubber in extra-thick, super-thin, or double-wide options, including custom and specialty fabrics. This positioning targets buyers who need dimensional flexibility and fabric integration for specific manufacturing or installation requirements. American Biltrite, operating across Canada and the United States, emphasizes premium-quality sheet rubber across major elastomers in various gauges, widths, and sizes with fabric reinforcement, appealing to customers that prioritize consistent gauge control and reinforced performance. BRP Manufacturing in Lima, Ohio, serves military, automotive, aerospace, and industrial customers with high-quality sheet rubber and extruded rubber products, a mix that demands rigorous specification control and the ability to meet demanding end-use standards.
International players add further diversity. TOGAWA Rubber in Japan produces rubber sheets for industrial gaskets, floor mats, and extrusion applications, reflecting a focus on precision and application-specific patterning. Zenith Rubber in Mumbai, India, has manufactured rubber sheets, mats, flooring, and industrial rubber products since 1965, leveraging long experience and regional cost advantages while serving both domestic and export demand. Rubberteck International in Busan, South Korea, supplies anti-static and other rubber sheets for industrial applications, highlighting a niche where electrostatic control and specialized performance justify dedicated sourcing. ContiTech, a division of Continental based in Germany, produces high-performance rubber sheets and materials for industrial applications, combining global scale with engineering credibility and, increasingly, sustainability-forward product development.
What ties these leaders together is not identical product lines but strategic clarity. The strongest players are differentiating along one or more of the following axes: material breadth and spec-grade customization, integrated fabrication and component capability, dimensional and fabric-reinforcement specialization, sector-specific certification and compliance readiness, and sustainability-driven formulation. This is a market where generalists can survive, but specialists and clearly positioned players tend to capture more defensible margins.
Evolution of the Competitive Landscape
The market is not heading toward outright consolidation into a few dominant firms. Instead, it is evolving through capability layering and segmentation. Larger, multi-elastomer producers are expanding their technical service and sustainability portfolios to protect share in regulated and premium segments. Custom fabricators and molded-component manufacturers are gaining relevance as buyers seek to offload more processing steps and reduce integration risk. Regional specialists continue to compete effectively where local service, cost structure, and application knowledge matter more than global scale. Meanwhile, new entrants and niche players are finding openings in anti-static, low-emission, and bio-based or certified material segments where specification intensity creates room for focused offerings.
A practical implication is that competitive advantage is increasingly defined by the ability to operate across multiple value dimensions at once: consistent quality, traceable sourcing, certification readiness, technical support, and sustainable formulation options. Companies that only compete on volume or price are more exposed to raw material swings and regulatory sorting, while those that combine material expertise with service depth and compliance credibility are better positioned to defend margins and win specification decisions.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape where growth concentrates and how value is captured.
-
Sustainability performance becomes a default specification dimension. Low-emission products, bio-based fillers, and certified or traceable sourcing will move from differentiators to baseline expectations in a growing share of applications, particularly in Europe, North America, and regulated industrial sectors. Commercial opportunity lies with manufacturers that can offer credible, test-backed sustainability claims without sacrificing mechanical or chemical performance, and with procurement teams that can integrate these criteria into sourcing scorecards before specifications become locked in by competitors.
-
Premium natural rubber channels become more selective and compliance-dependent. As traceability and audit requirements reshape access to high-value export markets, suppliers with robust documentation and verified sourcing will enjoy preferential access, while others face narrowing options. This creates opportunity for companies that invest early in chain-of-custody systems, supplier documentation, and digital traceability, as well as for buyers that secure reliable, compliant supply ahead of broader market tightening.
-
Customization and application-specific engineering gain share over generic commodity sheets. Demand is increasingly oriented toward specific gauges, fabric reinforcements, anti-static properties, chemical resistance profiles, and low-VOC formulations. The opportunity is not simply to sell more sheet by weight but to sell solutions that reduce downstream processing, accelerate qualification, lower failure risk, and support total-cost objectives. For producers, this means building flexible production and technical-service capabilities; for investors, it means evaluating whether target companies can sustain premium positioning through engineering value rather than volume alone.
These trends carry risk as well as opportunity. Raw material volatility can compress margins if pricing power and formulation flexibility are limited. Regulatory requirements may raise compliance costs and exclude suppliers that cannot meet traceability or emissions thresholds. Demand-side expectations can shift faster than production capabilities, leaving slower-responding firms with mismatched inventories or obsolete grade mixes. The upside, however, belongs to organizations that treat these pressures as planning inputs and respond with deliberate investment in material capability, compliance infrastructure, and specification-level differentiation.
PW Consulting Chemical & Energy Research Center
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between material portfolio, application expertise, and compliance readiness. This means reviewing whether product lines map clearly to the highest-value segments, whether formulation flexibility allows intelligent blending or grade substitution in response to raw material movement, and whether sustainability and traceability capabilities are sufficiently developed to meet rising specification requirements. Companies should also assess whether their fabrication, custom-spec, or technical-service capabilities are strong enough to win on total solution value rather than competing only on sheet price.
For investors, the focus should be on structural positioning rather than headline growth alone. Evaluate whether target companies have defensible differentiation through material breadth, specialty grades, certification readiness, or integrated fabrication; whether their cost and sourcing strategies can withstand raw material volatility; and whether their sustainability roadmap is grounded in product reality and test-backed claims rather than marketing language. Preference should go to operators that can demonstrate a repeatable ability to win specification decisions in regulated or performance-critical segments, because those decisions tend to be stickier and more margin-protective over time.
For procurement and supply chain leaders, the strategic task is to broaden evaluation criteria beyond unit cost and to secure supply clarity ahead of regulatory and price pressures. Incorporate traceability, emissions compliance, batch consistency, technical support, and lifecycle performance into sourcing frameworks. Where natural rubber exposure is significant, consider supply diversification, certified or compliant channel planning, and formulation strategies that preserve performance while managing input risk. Early engagement with suppliers that already meet emerging traceability and low-emission expectations can reduce qualification delays and protect continuity in premium channels.
The market's direction is clear enough to warrant action, but the details that determine competitive success are highly segment-specific. Trim-level specification mixes, regional sourcing constraints, certification requirements, and application-level performance thresholds vary widely, and generic assumptions often lead to mispriced risk or missed openings. Decision makers who need granular segment data, company-level capability mapping, and tailored scenario analysis will find greater value in structured, deeper research than in broad market narratives. For those evaluating strategic moves, gathering detailed intelligence on segment growth drivers, competitive positioning, regulatory exposure, and material-cost sensitivity is a practical next step before committing capital, renegotiating supply, or redesigning product roadmaps.
For detailed analysis of this topic, please visit the official page: Rubber Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind the Epoxy Resin Active Toughening Agent Market 6.4% CAGR Link Up to 2032
By pmarketresearch, 2026-09-21
Active Toughening Agents for Epoxy Resins: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Critical Inflection Points
The global market for active toughening agents designed for epoxy resin systems has entered a phase of deliberate, structurally driven growth. Valued at 81.25 million USD in 2025, the market has expanded from 60.0 million USD in 2020, reflecting a compound annual growth rate of approximately 6.4 percent across the 2026 to 2032 forecast horizon. This trajectory is not defined by cyclical commodity swings, but by a steady recalibration of how epoxy formulations balance rigidity, thermal stability, and fracture resistance across demanding industrial and high-performance applications. As design engineers push composite laminates, structural adhesives, protective coatings, and electronic encapsulants into more severe service environments, the traditional compromise between mechanical toughness and baseline performance is being systematically redefined by chemistry, processing economics, and end-use requirements.
The market’s evolution carries a clear concentration profile. The top three participants capture roughly 55 percent of global revenue, while the leading five firms account for nearly 68 percent. This distribution signals a mature competitive arena where scale, intellectual property depth, and formulation expertise create meaningful barriers to entry. At the same time, it leaves sufficient fragmentation for specialized regional players and application-focused innovators to carve out defensible positions. Rather than a winner-take-all contest, the landscape favors organizations that can translate material science into consistent processing windows, application-specific performance, and supply reliability.
The Core Tensions Reshaping the Sector
Three interconnected challenges are redefining how manufacturers, formulators, and end-users approach epoxy toughening. The first is the persistent performance-efficiency paradox. Historically, introducing rubber or thermoplastic reinforcement into epoxy networks has improved impact resistance and crack tolerance, but often at the expense of viscosity control, glass transition temperature, or thermal stability. Bridging that gap increasingly demands nanoscale dispersion control, reactive compatibility strategies, and self-assembling architectures that deliver toughness without degrading the host matrix’s baseline characteristics.
The second tension stems from regulatory and sustainability acceleration. Industrial flooring, protective coatings, construction applications, and marine asset maintenance are moving toward formulations that reduce volatile organic compound exposure, lower lifecycle carbon intensity, and improve compatibility with circular-economy expectations. In parallel, downstream industries are asking for more transparent sourcing, lower toxicity footprints, and formulations that simplify end-of-life handling or enable higher recycled-content integration. Meeting these requirements without sacrificing mechanical reliability or shelf stability forces formulation teams to re-evaluate incumbent chemistries and evaluate bio-based, low-emission, or hybrid toughening strategies.
The third inflection point is the shifting center of gravity in demand intensity. Growth is no longer distributed evenly across legacy applications. Semiconductor packaging, battery enclosures, lightweight structural assemblies, and high-durability offshore and marine systems are placing disproportionate emphasis on materials that can withstand thermal cycling, vibration, moisture exposure, and mechanical fatigue while supporting weight reduction and extended maintenance intervals. This demand migration changes the economics of product design, because performance tolerances tighten and qualification cycles lengthen, which in turn raises the value of specialized toughening solutions relative to broad-line commodity additives.
For business leaders, these tensions translate into a straightforward but demanding strategic question: whether to compete on cost-and-volume scale, on differentiated performance architecture, or on application-specific formulation partnerships. The answer increasingly depends on how well an organization can anticipate end-use qualification requirements and manage the trade-offs between toughness, processability, and regulatory alignment.
Key Drivers of Market Change
Material Innovation and the Rise of Precision Toughening
The most consequential driver of market momentum is the shift from blunt toughening tactics to precision-engineered reinforcement architectures. Traditional rubber-modified and thermoplastic toughening approaches remain relevant, but they are increasingly complemented by pre-dispersed concentrates, nano-scale core-shell particles, reactive block copolymers, and hyper-branched structures that integrate more cleanly into epoxy networks. These architectures can improve fracture toughness, fatigue resistance, and damage tolerance while preserving heat resistance, rigidity, and thermal properties that high-performance applications require. In structural adhesives, composites, and electronics, that balance is not a luxury feature; it is often the difference between a viable solution and one that fails qualification testing under thermal shock, impact, or long-term load.
One practical indicator of this shift is the commercial emphasis on pre-dispersed concentrate systems that simplify handling and dispersion for epoxy formulators. Nano-sized core-shell rubber particles incorporated into liquid media, for example, reduce particle agglomeration risk and lower the burden on downstream processing, while offering enhancements in impact strength, adhesive performance, and heat shock resistance. Such systems illustrate why the toughening conversation is moving away from generic additive categories and toward engineered intermediates that solve real process and performance pain points. For epoxy processors, this means faster reformulation support, better repeatability, and a cleaner translation from lab-scale performance to production-scale reliability.
Regulatory and Sustainability Pressure as a Catalyst, Not Just a Constraint
Policy and regulatory dynamics are accelerating change rather than merely restricting it. In European construction and industrial coating contexts, tighter sustainability expectations are pushing formulators toward low-VOC and bio-based formulations that meet both performance and environmental criteria. Far from being a compliance tax, this evolution is spawning a new class of requirement-led innovation: bio-based toughening agents, low-emission epoxy systems, and formulations designed for industrial flooring and protective coatings that must satisfy durability standards while reducing environmental burden.
The commercial implication is that sustainability is becoming a design input at the start of product development rather than a retrofit target. Companies that can supply toughening agents and epoxy-compatible chemistries with credible sustainability attributes may gain access to higher-value programs where procurement teams must justify material choices across lifecycle, regulatory, and reputational dimensions. Conversely, formulations that lag on VOC profile, bio-based content, or transparency of supply may face growing friction in markets where specification approvals are subject to stricter evaluation.
Demand-Side Transformation in High-Performance End-Use Sectors
On the demand side, the most meaningful shift is the increasing need for epoxy systems that survive more demanding service conditions while supporting lighter, more efficient designs. In semiconductor and battery packaging contexts, lightweight composite requirements and tighter tolerance bands are driving higher interest in tailored toughening solutions that protect sensitive assemblies from stress, thermal mismatch, and cyclic loading. Similarly, in offshore and marine asset maintenance, epoxy coatings are being specified not only for protection but for extended maintenance intervals, which raises the premium on mechanical durability and chemical resistance under prolonged exposure.
These demand signals matter because they change the basis of competition. Applications that tolerate marginal performance can absorb cost-led substitution; applications where failure carries high operational, safety, or capital consequences do not. As a result, toughening agents are increasingly evaluated through the lens of end-use reliability, qualification support, and compatibility with specific processing routes. Formulators and end-users alike are pushing for materials that reduce risk in the field, which gives a structural advantage to suppliers that can document performance under realistic conditions rather than rely solely on generic benchmark data.
Supply Chain, Cost Structure, and Formulation Economics
The cost and supply side adds another layer of complexity. Toughening agents are rarely purchased as isolated commodities; they are integrated into broader formulation strategies where dispersion quality, shelf stability, viscosity control, and batch consistency influence total cost of ownership. When regulatory shifts, feedstock transitions, or regional sourcing constraints alter input economics, the impact is magnified because downstream processors must balance performance targets with manufacturability and cost predictability. At the same time, the move toward pre-dispersed and pre-engineered systems can reduce formulation complexity in production, potentially lowering labor, dispersion equipment burden, and process variability even if the per-unit material cost is higher.
Epoxy Active Diluent Market
This dynamic favors companies that can offer not just chemistry, but process-aligned solutions. For epoxy processors, the value proposition increasingly includes dispersibility, compatibility with target resin systems, and the ability to maintain performance without unacceptable trade-offs in modulus or glass transition behavior. In practical terms, that means supplier selection is becoming less about price-per-kilogram alone and more about whether the toughening agent helps the end formulation meet target properties within a stable, scalable process window.
Competitive Landscape and Leading Strategies
Differentiation Through Formulation Architecture and Application Focus
The market’s competitive frontier is defined less by sheer volume and more by how companies translate material science into application-specific advantage. Global specialty chemical players tend to emphasize high-performance architectures, proprietary toughening chemistries, and integration with advanced composite or adhesive systems. Their strategic positioning often centers on solving demanding end-use problems where toughness must coexist with elevated thermal performance, damage tolerance, or very tight mechanical specifications. For example, self-assembling block copolymer-based toughening systems and thermoplastic polyester sulfone micropowders are being positioned where epoxy composites and prepregs need improved toughness and damage resistance without sacrificing key structural properties.
These approaches create differentiation through performance architecture rather than price alone. When a toughening solution can demonstrably improve damage tolerance or toughness while maintaining modulus and glass transition behavior, it becomes easier to defend in specifications that are sensitive to both mechanical reliability and thermal stability. That is especially relevant in automotive structural adhesives, CFRP-related aerospace applications, and other settings where heat resistance, rigidity, and impact tolerance must all remain within acceptable bounds.
PW Consulting Chemical & Energy Research Center
Regional Strengths, Specialization, and Scale
Alongside global specialists, a broad set of regional and application-focused manufacturers contributes meaningful scale and breadth across rubber, thermoplastic, core-shell latex, hyper-branched, and reactive toughening variants. These players often compete by covering multiple application domains, maintaining responsive production and customization capabilities, and aligning product portfolios to coatings, adhesives, composites, and certain electronics uses. Their advantage frequently lies in breadth, localization, and the ability to serve customers who need a practical range of toughening options rather than a single high-end architecture.
Worldwide Epoxy Resin Curing Agents Market
The strategic relevance of this fragmentation should not be underestimated. In many industrial and regional markets, buyers prioritize availability, formulation flexibility, and cost-sensitive performance tuning over the most advanced but narrowly focused specialty option. That creates durable roles for suppliers that can balance product range with consistent quality and practical technical support. At the same time, the most specialized applications reward deep technical differentiation, which means competitive advantage is increasingly bifurcated: breadth for broad industrial demand, and performance depth for mission-critical applications.
Market Evolution: Consolidation Pressure and Entry Opportunities
Looking ahead, the competitive structure is likely to evolve through a mix of consolidation pressure and selective entry opportunities. The concentrated top tier suggests that scale, IP portfolios, and integrated application development provide meaningful defensive moats. Yet the fragmentation below the top tier indicates room for companies that can build defensible niches through application expertise, regional supply strength, or differentiated toughening chemistry.
Entry and expansion opportunities are particularly likely in areas where performance requirements are rising faster than incumbent portfolios can adapt cleanly: bio-based and low-emission toughening, pre-dispersed concentrate systems for easier processing, and specialized solutions for electronics and composite packaging where lightweighting and reliability converge. At the same time, consolidation pressures may intensify among mid-tier players seeking to expand application coverage, improve scale economics, or acquire technical capabilities that strengthen their position with specification-driven buyers. The market is thus moving toward a structure where the winners are those who can combine credible performance claims with process-compatible delivery and clear application alignment.
Forward Outlook: Three Strategic Trends to 2032
Trend One: Toughening as an Engineered System, Not a Commodity Additive
Over the next three to five years, active toughening agents are likely to be treated more like engineered formulation systems than generic performance additives. That means greater emphasis on dispersion control, reactive compatibility, rheology management, and the ability to preserve modulus and thermal properties while improving toughness and damage resistance. Buyers will increasingly evaluate toughening agents on the basis of total formulation impact rather than isolated mechanical metrics. The commercial opportunity lies in solutions that reduce reformulation friction, improve repeatability, and help epoxy systems meet demanding targets without requiring extensive process re-engineering.
Trend Two: Sustainability-Linked Performance Becomes a Specification Requirement
Sustainability-driven formulation requirements are expected to become more embedded in procurement and specification processes, especially in coatings, industrial flooring, protective systems, and construction-adjacent applications. Low-VOC profiles, bio-based content, and lifecycle considerations will increasingly influence which toughening chemistries are eligible for consideration. This trend does not simply reward “greener” products; it rewards products that can demonstrate credible performance under the same demanding conditions as conventional alternatives. The opportunity is for suppliers and formulators who can pair sustainability attributes with robust mechanical and durability performance, turning environmental compliance into a competitive entry point rather than a constraint.
Trend Three: High-Reliability Applications Drive Higher-Value Demand
A third trend is the continued rise of high-reliability applications where failure is expensive and specifications are tight. Semiconductor and battery packaging, lightweight structural assemblies, and durable marine or offshore coatings are expected to place disproportionate emphasis on toughness, thermal cycling resistance, and extended service life. In these settings, the value of a toughening agent is tied to its ability to reduce risk and support qualification, not merely to improve a single performance parameter. The commercial opportunity lies in capturing demand from applications that are willing to pay for reliability, consistency, and technical support, while managing the risk that qualification timelines and technical barriers can slow adoption.
These trends together suggest a market that is growing at a measured but meaningful pace, with the strongest value creation concentrated where performance, process compatibility, and sustainability converge. The upside is real, but so is the risk that over-indexing on any single dimension—cost, performance, or sustainability—without the others can limit commercial viability in specification-driven environments.
Strategic Actions for Decision-Makers
For Epoxy Manufacturers and Formulators
Evaluate toughening agents as part of a total formulation strategy rather than as interchangeable additives. Prioritize solutions that align with your processing constraints, target viscosity and modulus profiles, and end-use qualification requirements. Where sustainability or low-emission performance is becoming a purchasing requirement, treat it as a design input early, and validate that any bio-based or low-VOC toughening approach can still meet mechanical and durability benchmarks in the intended application.
For Investors and Corporate Development Teams
Focus on the intersection of application-driven demand and differentiated chemistry. The most resilient opportunities are likely to be in specialized toughening architectures that address concrete performance problems in composites, structural adhesives, protective coatings, and high-reliability electronics or battery-related uses. Monitor consolidation dynamics among mid-tier players, and assess whether a target’s advantage comes from genuine technical differentiation, application relationships, or regional scale. Where demand is concentrated in high-specification applications, valuation logic should reflect qualification barriers and technical moats, not just volume growth.
For Procurement and Specification Teams
Build sourcing decisions around total cost of ownership, application reliability, and supplier capability to support qualification and formulation tuning. Request performance data that reflects the conditions under which the epoxy system will actually operate, including thermal cycling, impact, adhesion, and long-term durability where relevant. In markets where regulatory and sustainability expectations are tightening, verify that the selected toughening approach supports compliance without undermining field performance, because specification risk in demanding applications can far outweigh modest initial material savings.
For teams seeking a more granular view of segmentation, regional dynamics, competitive positioning, and forward scenarios across coatings, adhesives, composites, electronics, and high-performance industrial applications, a deeper dive into detailed market data and tailored strategic analysis can sharpen planning assumptions and reduce the risk of poorly aligned decisions. The broader opportunity in the active toughening agent space for epoxy resins is clear, but the details—where value concentrates, which applications justify premium performance, and how sustainability requirements will reshape specifications—will determine which companies capture it and which merely watch it pass.
For detailed analysis of this topic, please visit the official page: Active Toughening Agent for Epoxy Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tetraethyl Orthosilicate Market 2026: Unpacking the 6.98% CAGR and Regional Shifts
By pmarketresearch, 2026-09-21
The Tetraethyl Orthosilicate Market: Strategic Shifts and Commercial Opportunities Through 2032
The tetraethyl orthosilicate market has entered a phase of sustained expansion, driven by converging demands across advanced materials, semiconductor manufacturing, and specialty chemical applications. With a projected compound annual growth rate of 6.98 percent from 2026 through 2032, the sector is transitioning from a niche chemical feedstock into a strategically important enabler of high-value industrial processes. The market reached 215.0 million USD in 2025 and is expected to climb to 344.8 million USD by 2032, reflecting steady demand acceleration rather than speculative volatility. Understanding the structural forces behind this trajectory requires looking beyond headline figures and examining the technological, regulatory, and competitive dynamics that will shape purchasing decisions, investment priorities, and manufacturing strategies over the next several years.
Market Landscape and Structural Challenges
The tetraethyl orthosilicate market is characterized by moderate fragmentation and a clear emphasis on product differentiation. High purity grades command a dominant share of revenue, underscoring how end-use requirements in electronics, advanced coatings, and precision chemical synthesis have elevated specification standards across the value chain. The global market size has expanded consistently over the past five years, with 2024 revenue reaching 196.06 million USD before accelerating into 2025. This growth pattern reflects a market that is maturing in terms of application breadth while simultaneously tightening in terms of quality expectations.
Several structural challenges are reshaping how producers and buyers navigate this environment. First, regulatory stringency around organosilicon handling and emission control has increased operational complexity, reducing production flexibility and raising compliance costs across multiple regions. Second, raw material volatility, particularly in silicon-based feedstocks and ethanol derivatives, has introduced greater cost uncertainty into manufacturing planning. Third, the market’s growing dependence on high purity specifications has widened the performance gap between standard-grade suppliers and specialized producers, intensifying the need for technical capabilities that go beyond basic chemical synthesis. These pressures are not merely operational inconveniences; they are redefining competitive barriers and influencing where value is captured within the supply chain.
Key Drivers Shaping Market Evolution
Technological Innovation and Application Expansion
Advances in sol-gel processing, thin-film deposition, and specialty coating formulations continue to expand the functional role of tetraethyl orthosilicate. In semiconductor and electronic materials, the shift toward more precise silica film formation has elevated demand for ultra high purity grades suitable for chemical vapor deposition and related precision applications. At the same time, sol-gel-based coatings and spin-on glass technologies are finding broader use in surface engineering, optical treatments, and advanced ceramics, creating cross-industry demand that is less dependent on any single end market. This technological broadening is important because it allows producers with strong quality control and application support to serve multiple downstream segments without cannibalizing their own positioning.
For commercial strategists, the implication is clear: product value is increasingly tied to performance consistency and application readiness rather than volume alone. Companies that can provide documented purity profiles, controlled particle or hydrolysis behavior, and technical guidance for process integration are better positioned to retain pricing power and customer loyalty, especially in electronics and high-specification coatings.
Regulatory and Compliance Pressure as a Competitive Filter
Chemical safety directives and emission control requirements are reshaping production practices across the organosilicon sector. Stringent handling standards have reduced operational flexibility while increasing the cost burden associated with hazardous material compliance. Rather than acting as a uniform headwind, however, these regulations are functioning as a competitive filter. Larger, better-capitalized producers with established environmental management systems and standardized handling protocols are absorbing compliance costs more efficiently than smaller operators with limited regulatory infrastructure.
This dynamic is creating a bifurcation in the supply base. Buyers in semiconductor, pharmaceutical synthesis, and high-performance coatings are increasingly favoring suppliers that can demonstrate robust compliance records, consistent documentation, and controlled logistics for sensitive materials. The result is a market where regulatory readiness is becoming a commercial differentiator, not just an operational requirement.
Demand-Side Shifts in End-Use Industries
Demand behavior is changing on two fronts. In industrial and construction-related applications, tetraethyl orthosilicate continues to serve as a coupling agent and silane diluent in consolidation treatments, primers, and sealant systems. These uses benefit from steady infrastructure and maintenance activity, but they are also sensitive to broader construction cycles and input cost fluctuations. In higher-value segments, demand is being shaped by more specification-driven procurement, where buyers prioritize purity, lot consistency, and supplier technical support over lowest-cost sourcing.
3-aminopropyltriethoxysilane Market
This shift matters because it alters the purchasing calculus. In specification-intensive applications, total cost of ownership considerations, including process yield, defect reduction, and supply reliability, often outweigh initial price differences. Producers that can align their product portfolios with these purchasing priorities are gaining an advantage in customer retention and qualification cycles.
Feedstock Dynamics and Cost Structure Sensitivity
Production economics remain closely linked to the availability and pricing of silicon tetrachloride, ethanol, and related alcohol-based inputs. Fluctuations in these feedstock markets directly affect manufacturing expenses and can compress margins when price movements are not matched by timely adjustments in product pricing or formulation strategies. At the same time, the growing premium on high purity grades is pushing some producers to invest in more controlled synthesis and purification steps, which changes the cost structure in favor of operators with stronger process engineering capabilities.
For procurement and planning teams, this means that short-term price considerations should be balanced against supply resilience and specification reliability. In an environment where feedstock volatility can shift production economics quickly, long-term agreements and supplier qualification based on process control can reduce exposure more effectively than periodic spot purchasing.
Competitive Landscape and Strategic Positioning
The competitive environment is led by a mix of global specialty chemical companies and regional suppliers with focused product portfolios. Evonik Industries AG has built a recognizable position around its Dynasylan and SILBOND offerings, particularly for sol-gel processes, spin-on glass, and high-purity silica applications. Its strategy emphasizes application-specific grades and technical support that align with demanding coating and materials-processing use cases. Wacker Chemie AG competes with ultra high purity tetraethyl orthosilicate variants aimed at electronics and industrial silane applications, reinforcing a focus on precision grades and process reliability.
In the Asian market, Shin-Etsu Chemical Co. Ltd. provides both standard and high-purity grades serving sol-gel processes, coatings, and semiconductor materials, leveraging a broad materials portfolio and established customer relationships. Entegris, Inc. has carved out a specialized position with ultra-pure tetraethyl orthosilicate supplied in controlled containers for chemical vapor deposition of silicon dioxide films, targeting semiconductor manufacturing where contamination control is critical. SoulBrain Co., Ltd. focuses on electronic-grade material for semiconductor CVD and related precision applications, reflecting the growing importance of localized high-specification supply in advanced electronics.
PW Consulting Chemical & Energy Research Center
Dow Chemical Company maintains relevance through silane diluent and additive forms used in construction consolidation, zinc-rich primers, and coupling agent applications, demonstrating how broader chemical portfolio strength can support steady demand in industrial use cases. At the same time, regional suppliers such as Siwin Silicone Materials Co., Ltd. and TNJ Chemical Industry Co., Ltd. serve pharmaceutical synthesis, reagent-grade, and general industrial applications with standardized purity offerings. These companies illustrate how smaller-scale or regional players can remain viable by serving price-sensitive, specification-modest, or locally concentrated demand segments.
How Leaders Differentiate
Across the market, differentiation is increasingly defined by three factors: purity control, application support, and supply-chain reliability. Leading producers invest in controlled manufacturing environments, consistent documentation, and technical service that helps downstream customers integrate the material into sensitive processes. This is especially important in electronics and high-performance coatings, where specification compliance and lot-to-lot consistency can determine whether a supplier is qualified for recurring use.
Another differentiating theme is portfolio alignment with end-use risk profiles. Companies that serve semiconductor and pharmaceutical-adjacent applications tend to emphasize containment, purity certification, and controlled logistics, while those focused on industrial coatings, adhesives, and construction-related uses prioritize cost efficiency, availability, and broad compositional reliability. The most strategically resilient players are those that can manage both ends of this spectrum without diluting their core positioning.
Market Evolution and Entry Dynamics
The market is likely to continue evolving through incremental consolidation among high-specification suppliers and parallel specialization among regional producers. High purity segments will probably attract continued investment because they offer better margin stability and stronger customer lock-in in electronics and advanced materials. At the same time, standard-grade supply may see more price competition, particularly where regional demand is served by multiple capable manufacturers.
New entry remains possible, but the barriers are shifting. Low-cost production alone is no longer enough for customers in specification-intensive applications. Prospective entrants need credible quality systems, application expertise, and the ability to meet compliance expectations without disrupting delivery reliability. As a result, successful expansion is more likely to come from producers that already have materials-science capabilities, established regulatory frameworks, or existing relationships in target end markets.
Forward-Looking Trends and Commercial Implications
Trend One: High Purity Demand Will Anchor Growth
Over the next three to five years, high purity tetraethyl orthosilicate is expected to remain the primary growth anchor, especially as semiconductor-related processes, advanced coatings, and precision chemical synthesis continue to demand tighter control over contaminating species and consistent hydrolysis behavior. This trend creates commercial opportunities for suppliers that can systematically deliver certified purity, controlled packaging, and documentation that supports customer qualification cycles. It also favors businesses that can invest in purification, analytical verification, and contamination-aware logistics.
The strategic upside is not limited to large-scale producers. Specialized suppliers with focused product lines, strong technical service, and reliable quality can capture meaningful share in high-value niches even if their overall volume is smaller than that of broad-line chemical companies.
Trend Two: Compliance Costs Will Reshape Sourcing Strategies
Regulatory pressure is likely to remain a defining feature of the market. As handling and emission control requirements become more embedded in procurement decisions, buyers will increasingly weigh supplier compliance maturity when evaluating risk. This trend benefits organized producers with established environmental and safety infrastructure and creates a longer qualification runway for smaller or less documented suppliers.
For commercial teams, the opportunity lies in turning compliance into a sourcing advantage. Suppliers that proactively provide compliance documentation, standardized handling guidance, and predictable logistics can reduce the administrative and operational burden on buyers. In regulated or specification-sensitive environments, that value often translates into longer contracts and stronger supplier preference.
Trend Three: Regional Demand Mixes Will Diversify Value Creation
Asia Pacific continues to represent the largest regional revenue base, reflecting broad activity across electronics, industrial chemicals, and coatings-related applications. North America and Europe remain important for high-specification demand, particularly in semiconductor-adjacent and specialty materials use cases. Latin America and the Middle East and Africa, while smaller in absolute terms, offer incremental growth as industrial activity and materials upgrading expand in selected markets.
Worldwide Ethyl Silicate 40 Market
The commercial implication is that regional strategies should be tailored to local application mixes rather than assuming uniform demand behavior. In markets where electronics and advanced materials dominate, purity, documentation, and technical support will likely drive purchasing decisions. In more industrial or construction-linked markets, availability, price stability, and broad compositional reliability may matter more. Suppliers that align their offerings with these regional priorities are better positioned to convert demand into sustainable share.
Risks and Uncertainties to Watch
Several uncertainties could alter the pace or shape of market development. Feedstock price volatility remains a persistent risk, particularly if silicon-based inputs or alcohol derivatives move sharply due to supply constraints or regional demand changes. Regulatory evolution could also accelerate compliance costs faster than producers can adjust, especially in regions where chemical safety enforcement becomes more stringent. In addition, demand concentration in high-purity electronics applications could increase exposure to semiconductor cycle variability, while broader industrial demand may be more sensitive to construction and infrastructure fluctuations.
These risks do not negate the market’s growth trajectory, but they underscore the importance of flexible sourcing strategies, diversified application exposure, and supplier qualification based on reliability rather than price alone. Companies that treat these uncertainties as planning variables rather than external shocks will be better equipped to maintain margin stability and supply continuity.
Strategic Recommendations for Decision Makers
For Manufacturers and Producers
- Prioritize purity control and documentation as core commercial assets, especially if targeting electronics, advanced coatings, or other specification-intensive applications.
- Evaluate cost-structure resilience against feedstock volatility by examining long-term input agreements, process efficiency improvements, and product-mix balance between premium and standard grades.
- Strengthen application support capabilities so that technical service becomes part of the value proposition rather than a back-office function.
For Investors
- Focus on companies with demonstrated ability to serve high purity demand and maintain compliance readiness, since these attributes are increasingly tied to margin stability and customer retention.
- Assess exposure to feedstock sensitivity and regional demand concentration, balancing growth potential against cycle volatility in electronics and construction-linked end markets.
- Look for businesses that combine product differentiation with scalable quality systems, as these are more likely to sustain competitive advantage as regulatory and specification demands rise.
For Procurement and Supply Chain Leaders
- Align sourcing criteria with total cost of ownership, including specification consistency, documentation quality, and logistics reliability, rather than relying solely on unit price comparisons.
- Diversify qualified suppliers across high-purity and standard-grade categories to reduce exposure to feedstock-driven price swings and compliance-related supply interruptions.
- Use supplier qualification to capture forward-looking information on production flexibility, regulatory preparedness, and application support, which can improve downstream process stability.
The tetraethyl orthosilicate market is moving toward a more specification-driven, compliance-aware, and application-diversified future. For organizations operating in or adjacent to this space, the most valuable insight is that competitive advantage will increasingly come from reliability, technical alignment, and supply-chain maturity rather than volume expansion alone. For decision makers who need deeper segmentation, regional nuance, and tailored scenario planning, the full research report offers a more granular view of demand patterns, competitive moves, and procurement implications across the forecast period.
For detailed analysis of this topic, please visit the official page: Tetraethyl Orthosilicate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polyimide Tubing Market: Why 8.1% CAGR and Medical Demand Redefine Growth By 2032
By pmarketresearch, 2026-09-21
Navigating the Polyimide Tubing Market: Strategic Trends and Commercial Opportunities
The polyimide tubing market has entered a phase of sustained expansion, driven by an increasingly demanding set of performance requirements across high-stakes industries. From 2020 through 2025, the market moved from a relatively modest base into a consistent double-digit growth trajectory, with the most recent annual figures signaling that demand is no longer cyclical but structurally reinforced. Looking ahead to the end of the decade, the expansion is expected to accelerate further, with a compound annual growth rate that places polyimide tubing among the more compelling specialty materials segments in advanced manufacturing and life sciences. The revenue scale now sits well into the triple-digit range, and the forward projection suggests the market will more than double its current size within the coming forecast window.
This trajectory is not merely a function of volume growth. It reflects a deeper shift in how engineers and procurement leaders think about tubing materials. Polyimide has transitioned from a niche solution for extreme thermal or chemical environments into a default consideration for applications where reliability, miniaturization, and regulatory compliance intersect. That shift has rewritten the competitive rules, forcing suppliers to compete on more than price or basic availability. The market is now rewarding precision, material innovation, and the ability to navigate an increasingly complex compliance landscape.
Market Current State and Core Challenges
The current market environment is defined by strong demand momentum, but that momentum is colliding with operational and structural constraints that will shape who wins in the next cycle. The first challenge is the widening gap between specification requirements and manufacturing capability. As applications move toward smaller diameters, tighter tolerances, and more complex reinforcement architectures, the bar for process control has risen sharply. Not every producer can consistently deliver the wall uniformity, surface finish, and mechanical predictability that advanced medical, electronics, and aerospace programs now demand. This has effectively raised the barrier to entry and concentrated value creation among suppliers with mature process engineering and robust quality systems.
A second challenge lies in cost volatility and input pressure. Polyimide is a performance material, and its production economics are sensitive to precursor availability, energy costs, and processing intensity. Recent producer price trends have shown upward pressure on input costs, which can compress margins for suppliers that lack pricing power or differentiated value propositions. In a market where many end-users are accustomed to treating tubing as a commoditized component, the ability to justify premium pricing increasingly depends on proving measurable performance gains rather than simply pointing to material grade.
The third challenge is regulatory and documentation intensity. As polyimide tubing penetrates more regulated end-use sectors, compliance has become a commercial prerequisite rather than a back-office function. Suppliers must demonstrate material traceability, biocompatibility support where relevant, and alignment with evolving regional requirements. This is especially true in European markets and in medical-adjacent applications, where the cost of noncompliance can be far greater than the cost of qualifying new materials. Companies that treat compliance as a strategic capability rather than a checkbox are gaining a structural advantage in customer evaluations.
Key Drivers Shaping Market Direction
Innovation in Material Performance and Processing Precision
Material innovation remains one of the most powerful demand catalysts. The latest wave of product development is not just about incremental refinement; it is about rethinking the performance envelope of polyimide tubing in ways that directly enable new applications. Recent announcements from leading suppliers point to formulations that significantly increase tensile and column strength compared with traditional grades, addressing long-standing tradeoffs between flexibility, pushability, and mechanical reliability. In parallel, tailored surface and lubrication variants are reducing friction and improving handling characteristics, which is especially valuable in interventional and micro-catheter applications where operator control and device navigation are critical.
These advances matter commercially because they expand the addressable use space. When tubing can withstand higher loads, maintain dimensional stability under stress, or offer more predictable lubricity, designers can adopt polyimide in configurations that were previously impractical. That creates a virtuous cycle: stronger performance justification supports broader specification, which increases volume, which in turn funds further process improvement. For suppliers, the strategic implication is clear. The winners will be those who connect material science improvements to measurable application outcomes rather than competing solely on catalog breadth.
Regulatory Alignment as a Commercial Accelerator
Regulatory and compliance dynamics have evolved from a constraint into a competitive differentiator. In the medical and certain industrial segments, buyers increasingly evaluate suppliers based on their ability to deliver materials aligned with REACH and EU MDR expectations, alongside robust documentation and traceability. This has shifted the procurement conversation. Technical compliance is now part of commercial credibility, and suppliers that can demonstrate a consistent compliance posture are often shortlisted more quickly than those that require extensive qualification support.
The market is also seeing a degree of positioning around this theme. Some suppliers have emphasized that their polyimide tubing portfolios are designed with these regulatory expectations in mind, signaling that compliance capability is being used as a trust signal in sensitive applications. Others have claimed distinctive compliance status within their product lines. Regardless of the specifics of any single claim, the broader pattern is that regulatory readiness is becoming a meaningful filter in customer selection, particularly for programs with long qualification cycles and high switching costs. For manufacturers, this means that compliance infrastructure, documentation practices, and material transparency are now part of the core commercialization strategy.
Demand-Side Shifts Toward Miniaturization and High-Reliability Systems
On the demand side, the most persistent driver is the continuing push toward smaller, more precise, and more reliable systems. In medical device development, the trend toward minimally invasive and endovascular procedures has increased the need for tubing that can navigate complex anatomy while maintaining delivery precision. In electronics and advanced assembly contexts, miniaturization and heat management requirements have elevated the value of materials that combine dimensional stability with thermal resilience. Aerospace and automotive applications, meanwhile, continue to prioritize weight reduction and durability in high-stress subsystems.
Polyimide Foam Market
What ties these demand shifts together is an expectation of consistency. As systems become more integrated and tolerances tighter, tubing is no longer evaluated in isolation. It is judged as part of a system-level reliability equation. This has made end-users more selective and more willing to engage with suppliers that can support application-specific engineering, co-development, and longer-term supply assurance. For suppliers, the commercial opportunity lies in moving up the value chain: from selling standard tubing to participating earlier in design cycles, where specification decisions are still fluid and switching costs are lower.
Supply Chain Dispersion and Cost Structure Evolution
Supply chain and cost dynamics are reshaping how value is captured across the market. Polyimide tubing production depends on specialized manufacturing know-how, controlled process environments, and increasingly on reliable access to qualified input streams. As input cost pressures have risen, the ability to manage cost structure without eroding performance has become a defining capability. Suppliers that can maintain quality at scale, optimize yield, and manage working capital effectively are better positioned to absorb cost variability and protect customer relationships.
At the same time, supply chain considerations are influencing sourcing behavior. Buyers in regulated and high-reliability applications often prioritize continuity and auditability over marginal price differences. This has strengthened the position of established manufacturers with documented processes and predictable capacity. It has also created incentives for strategic collaboration, where tubing suppliers work more closely with medical device manufacturers, electronics assemblers, and system integrators to align specifications, reduce rework, and stabilize delivery. The emerging pattern is a market in which cost competitiveness is increasingly tied to process discipline and customer integration rather than to simple scale arbitrage.
Competitive Landscape and Leading Strategies
The competitive field is concentrated enough that a relatively small set of established players accounts for a substantial share of revenue, yet diverse enough that specialization remains a viable path. Market concentration suggests that scale, reputation, and compliance capability matter, but it does not eliminate room for differentiated mid-tier suppliers that can serve demanding niches with high precision and responsive engineering support. The key strategic question is not simply who is largest, but who can most reliably convert technical capability into commercial trust.
Several manufacturers illustrate the strategic paths currently shaping the market. Some are leaning into ultra-precision medical tubing, building reputations around tight tolerances and application-specific customization for catheter and interventional use. Others emphasize reinforcement architectures and high-lubricity variants, targeting performance requirements that standard geometries cannot easily meet. A further group positions itself around industrial and medical versatility, offering broad ranges of dimensional control and heat-resistant performance for customers that need flexible specification options. Across these approaches, the common thread is a move away from generic supply toward solution-oriented engagement.
Recent product activity supports this interpretation. One prominent supplier expanded its material portfolio with a polyimide formulation engineered to deliver substantially higher tensile and column strength than traditional options, a move that directly targets applications where mechanical integrity and handling control are paramount. Shortly afterward, the same company broadened its product line to enable more tailored performance in PTFE and polyimide tubing configurations. These launches are not isolated innovations; they reflect a deliberate strategy of raising the performance floor and increasing configurational flexibility so that the supplier can address a wider range of demanding applications without diluting its technical positioning.
The competitive landscape appears to be evolving along two tracks. On one track, larger or more established players are consolidating their advantage through compliance readiness, process maturity, and broad application coverage. On the other, specialized entrants and focused product line extensions are carving out defensible positions by solving specific performance problems or serving highly specialized procedural needs. Full-scale horizontal consolidation is not inevitable in the near term, but selective consolidation in high-growth segments is likely as buyers prefer fewer, more capable partners. New entrants will need either a genuine process advantage, a compliance edge, or a clearly defined application niche to break through.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interlinked trends.
- Performance-driven specification will deepen. As new formulations and reinforced variants mature, polyimide tubing will be selected for more applications on the basis of measurable mechanical and handling benefits rather than thermal resistance alone. This will increase the importance of application-level validation and supplier-supported testing in winning new business.
- Compliance and qualification readiness will become table stakes in regulated segments. Buyers will continue to favor suppliers that can bring documentation, material transparency, and regulatory alignment into the conversation early. Suppliers that still treat these as after-the-fact requirements will face longer sales cycles and higher disqualification risk.
- Application-adjacent integration will grow in value. The commercial battleground will increasingly be at the design interface, where tubing suppliers are expected to contribute to configuration choices, tolerance planning, and reliability trade-offs. Companies that can engage earlier and reduce downstream iteration will capture more wallet share and more durable relationships.
These trends translate into concrete opportunities. Manufacturers that invest in differentiated material grades, precision processing, and documented compliance will be better placed to command value and reduce price sensitivity. Investors and strategic partners should look for suppliers with a clear link between product innovation and end-use adoption, especially where new formulations enable previously constrained procedures or device concepts. Procurement and engineering leaders should treat supplier selection as a long-term risk management decision, weighting validation support, documentation quality, and application engineering capability alongside unit economics.
PW Consulting Chemical & Energy Research Center
The primary uncertainties to monitor are cost trajectory, regulatory evolution, and the pace at which new performance claims translate into qualified adoption. Input cost pressure could narrow margins for suppliers that cannot pass through value or optimize cost structure. Regulatory expectations may continue to tighten or shift across regions, altering the compliance burden and the speed of qualification. Finally, not every technical enhancement will convert into commercial uptake; some advances will require lengthy validation or may prove over-specified for certain use cases. Market participants should track these variables as leading indicators of where share and margin will migrate.
Strategic Recommendations for Decision-Makers
Manufacturers and suppliers should prioritize the conversion of technical capability into reliable commercial outcomes. That means investing in process control that supports tight tolerances at scale, documenting compliance and material traceability in ways that simplify customer qualification, and designing product portfolios around real application pain points rather than catalog breadth alone. Where possible, moving earlier into the design process and offering co-development support can reduce the risk of late-stage redesign and strengthen customer lock-in without resorting to price competition.
Investors and corporate strategists should assess market opportunities through the lens of defensibility. The most attractive positions are likely to be those where a supplier can demonstrate a repeatable advantage in performance, compliance readiness, or application specialization. Volume growth is important, but durability of demand depends on whether the supplier is solving a hard problem that customers are willing to pay for and cannot easily replicate elsewhere. Track record in regulated environments, the ability to sustain process improvement, and evidence of growing specification share are all signals worth weighting heavily.
Procurement and engineering buyers should treat polyimide tubing sourcing as a strategic decision with long consequences. Evaluate suppliers on more than nominal material grade or lead-time promises. Ask how they handle tolerance control, how they support qualification and documentation, how they manage cost volatility, and whether they can engage constructively in application development. In high-reliability or regulated programs, the cheapest option today can become the most expensive option tomorrow if it introduces qualification delays, variability, or compliance gaps.
Worldwide Polyimide Engineering Plastics Market
For organizations that need a deeper, segment-specific view of where growth is concentrating, which application roads are widening fastest, and how supplier positioning is evolving at the subsegment level, a more detailed research synthesis can help translate these trends into targeted plans. The broader market signals are clear, but the actionable details often depend on how each segment is moving and which performance or compliance capabilities matter most in a given context.
For detailed analysis of this topic, please visit the official page: Polyimide Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
FCC Catalyst Market: Why Top Players’ 5.5% CAGR Strategy Reveals New Growth Paths
By pmarketresearch, 2026-09-21
FCC Catalyst Market: Strategic Trends and Commercial Opportunities in a Transforming Refining Landscape
The global Fluid Catalytic Cracking (FCC) catalyst market has entered a phase of measured but purposeful growth, driven by a complex interplay of refinery economics, feedstock evolution, and tightening environmental standards. From a base of approximately $2.45 billion in 2020, the market expanded to around $3.0 billion by 2025, reflecting an average compound annual growth rate of roughly 5.5 percent over the historical period. This trajectory is expected to continue through 2032, with the market crossing the $4.3 billion threshold by the end of the forecast horizon. The growth is not uniform, nor is it guaranteed by volume alone. It is being shaped by strategic decisions around catalyst selection, unit configuration, and the shifting economics of heavy feedstock conversion.
PW Consulting Chemical & Energy Research Center
For decision-makers operating in or adjacent to the refining and petrochemical value chains, the FCC catalyst segment represents both a critical operational input and a strategic lever. Catalyst performance directly influences yield structures, unit reliability, and compliance costs. At the same time, the market's underlying dynamics are evolving rapidly, introducing new risks and opportunities that demand a clear-eyed view of where the industry is headed.
The current market environment is characterized by three interconnected challenges that are reshaping how refiners and catalyst suppliers approach FCC operations. First, feedstock volatility and the increasing use of opportunity crudes are testing the limits of conventional catalyst formulations. As refineries pursue margin advantages by processing heavier, more complex feeds, they encounter contaminants such as iron that can degrade catalyst activity and accelerate deactivation. This reality is pushing the industry toward mitigation technologies and more resilient catalyst designs, but it also increases the operational and economic stakes of catalyst selection.
Second, the regulatory landscape is tightening at a pace that outstrips incremental process adjustments. Environmental standards are increasingly focused on sulfur reduction, product quality, and the overall emissions footprint of refining operations. These requirements are not merely compliance checkboxes; they are changing the economics of FCC unit design and catalyst performance optimization. Refiners are being compelled to adopt advanced catalysts and additive packages that can deliver cleaner product slates without sacrificing conversion efficiency or unit stability. The cost of non-compliance, including operational disruptions and potential penalties, is becoming a material factor in catalyst investment decisions.
Third, the end-of-life management of spent catalysts is emerging as a significant cost and sustainability pressure point. Landfilling restrictions, disposal fees, and rising environmental liabilities are adding to the total cost of ownership for FCC catalysts. In several regions, the disposal cost for spent catalyst has climbed substantially, turning what was once a backward-looking operational issue into a forward-looking strategic concern. Refiners are increasingly recognizing that catalyst lifecycle economics, including regeneration, recycling, and disposal, must be integrated into unit planning and vendor selection.
Technology Innovation as a Competitive Imperative
Technological advancement is no longer a nice-to-have in the FCC catalyst market; it is a core determinant of unit profitability and strategic flexibility. Recent product launches illustrate how suppliers are responding to the dual pressures of feedstock complexity and product quality requirements. One notable example is the introduction of a catalyst technology designed to address iron poisoning, a growing challenge as refiners process iron-rich opportunity crudes. Commercial trials have demonstrated significant improvements in accessibility and the ability to handle heavier, more problematic feedstocks without compromising unit performance. This type of innovation directly attacks a key operational risk, reducing unplanned downtime and extending effective catalyst life.
At the same time, other developments are targeting the yield side of the equation. New catalyst platforms are being engineered to maximize high-octane gasoline blending stocks from gasoil and mild resid feeds, aligning FCC output with downstream fuel specification demands. These solutions reflect a broader trend: catalyst suppliers are moving beyond generic performance improvements to deliver tailored responses to specific refinery configurations, feed characteristics, and product slate objectives. The competitive advantage increasingly lies in the ability to match catalyst chemistry with the precise operational and regulatory context of the end user.
FCC Catalyst Additive; FCC Catalyst and Additives Market
Regulatory and Environmental Pressures Reshaping Demand
Policy and regulatory developments are acting as both a constraint and a catalyst for innovation. Updated testing and evaluation standards are formalizing how catalyst activity and selectivity are measured, creating a more rigorous framework for performance comparison and compliance. These standards matter because they influence procurement decisions, unit optimization strategies, and the credibility of supplier claims. In parallel, broader environmental regulations are pushing refiners toward catalysts and processes that can more effectively convert heavy feeds into cleaner products, reducing sulfur and other emissions-linked components.
The regulatory trajectory also intersects with feedstock economics. As environmental rules become more stringent, the economic case for processing heavy feedstocks depends increasingly on the ability to manage contaminants, maintain catalyst activity, and achieve target product specifications. This creates a feedback loop: regulation raises the bar for performance, which in turn incentivizes technology development and more sophisticated catalyst selection. For refiners, the implication is clear. Compliance is not a separate function from catalyst strategy; it is a central input into how FCC units are configured, operated, and upgraded.
Feedstock Economics and Cost Structure Dynamics
The cost structure of FCC operations is being reshaped by both feedstock trends and catalyst procurement economics. Refiners are navigating a landscape where crude differentials, opportunity crude availability, and contaminant levels can shift rapidly, affecting unit behavior and catalyst consumption rates. At the same time, the average cost of catalyst material remains a significant line item in refinery operating budgets. Optimized catalyst selection and usage patterns can deliver substantial annual savings per unit, underscoring the fact that catalyst economics are not just about price per ton but about total lifecycle value.
Disposal and recycling costs further complicate the picture. In markets where spent catalyst landfilling has become more expensive, the total cost of ownership rises, and the economic incentive to extend catalyst life or improve regeneration and recycling pathways becomes stronger. This is pushing attention toward solutions that reduce waste generation, improve metal trapping efficiency, and support more sustainable end-of-life options. For suppliers, it opens a strategic avenue: value propositions that combine performance, longevity, and lifecycle cost reduction are increasingly compelling in a cost-conscious environment.
Competitive Landscape and Strategic Positioning
The FCC catalyst market remains concentrated, with a small group of leading players accounting for a dominant share of revenue and technology offerings. This concentration reflects the high barriers to entry associated with catalyst chemistry, process integration expertise, and long-term refinery relationships. The competitive field includes globally recognized specialists in FCC catalysis, major chemical and catalyst companies with broad refinery portfolios, and integrated producers with strong regional presence and supply chain advantages.
Leading suppliers are differentiating themselves along several axes. Some are emphasizing proprietary catalyst platforms that address specific operational challenges, such as heavy feed processing, iron poisoning mitigation, or high-octane gasoline maximization. Others are leveraging integrated technology offerings that combine catalyst products with process licensing, unit optimization services, and post-treatment solutions. This bundling reflects a strategic shift from product-centric competition to solution-centric engagement, where the value delivered is tied to overall refinery economics rather than catalyst performance in isolation.
Regional dynamics also shape competitive positioning. Suppliers with strong local presence, technical support networks, and understanding of regional feedstock and regulatory contexts can gain advantages in key markets. At the same time, integrated producers participating in national refining ecosystems often benefit from coordinated supply chains and captive demand, allowing them to scale rapidly and influence regional market structures. The result is a landscape where global technology leadership and regional execution capabilities both matter, and where competitive success depends on aligning product strategy with local market realities.
Recent developments underscore how quickly the competitive dynamics can shift. New product introductions targeting iron-rich feedstocks and high-octane gasoline production illustrate the pace of innovation and the willingness of established players to invest in differentiated solutions. These launches are not incremental; they respond directly to operational pain points and regulatory pressures that are reshaping refinery priorities. In this environment, incumbents that can translate technical capability into measurable unit-level benefits are well positioned, while slower-moving competitors risk erosion in segments where performance and reliability are becoming increasingly decisive.
Market Evolution: Consolidation Pressures and Emerging Entrants
The market's concentration profile suggests continued pressure toward consolidation among smaller or less differentiated players, particularly in segments where feedstock flexibility, environmental compliance, and lifecycle cost management are becoming table stakes. Suppliers that cannot articulate a clear technical or economic advantage may find it harder to compete for specification-driven contracts, especially as refiners become more sophisticated in evaluating total cost of ownership and performance risk.
Continuous Catalyst Regeneration (CCR) Catalyst Market
At the same time, there are pathways for differentiation that do not require blanket market leadership. Niche expertise in specific catalyst functions, regional service excellence, or innovative approaches to spent catalyst management can create defensible positions. New entrants and smaller specialists may find opportunity by targeting particular pain points, such as contaminant mitigation, additive optimization, or sustainability-linked lifecycle services, rather than attempting to compete head-to-head across the full product spectrum. The overall trend is toward a more segmented competitive environment in which broad scale and deep specialization coexist, and where partnerships, technical service, and integrated offerings increasingly determine market outcomes.
Near-Term Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to define the FCC catalyst market's trajectory. First, catalyst formulations that can reliably handle heavier, more contaminated feeds while maintaining activity and selectivity will become increasingly central to procurement decisions. Iron poisoning mitigation, metal trapping efficiency, and robust performance across feed variations will move from specialized concerns to mainstream requirements as opportunity crude usage persists and refinery margin strategies continue to favor flexible feedstock handling.
Second, the link between catalyst selection and environmental compliance will tighten further. As product specifications and emissions expectations evolve, catalysts and additive packages that support sulfur reduction, cleaner product slates, and efficient conversion of heavy feeds will command greater attention. This trend favors suppliers who can demonstrate measurable compliance benefits and help refiners navigate an increasingly complex regulatory environment without sacrificing unit economics.
Third, lifecycle economics will gain prominence in catalyst decision-making. Disposal costs, recycling pathways, and the total cost of catalyst ownership will be evaluated more holistically, especially in regions where landfilling expenses are rising. Solutions that extend catalyst life, improve regeneration outcomes, or reduce waste volumes will have a stronger commercial case. This shift creates opportunities for suppliers and service providers who can integrate performance, sustainability, and cost management into a coherent value proposition.
These trends translate into tangible commercial opportunities. For catalyst manufacturers and technology licensors, there is room to grow by targeting refineries that are reconfiguring units for heavier feeds or facing specific contaminant challenges. Differentiated technologies that deliver clear operational improvements can support premium positioning and stronger customer retention. For investors, the market's steady growth profile and the centrality of catalysts to refinery economics suggest durable demand, but success will depend on identifying players with genuine technical differentiation and the ability to execute in a concentrated, relationship-driven market. For refiners and procurement teams, the opportunity lies in moving beyond unit price to evaluate total lifecycle value, contaminant handling, compliance support, and service capabilities when selecting catalyst partners.
Risks and uncertainties remain. Feedstock availability and quality can shift quickly, altering the relative attractiveness of different catalyst strategies. Regulatory timelines and enforcement intensity may vary by region, creating uneven demand signals. Economic cycles, refining margin compression, and capital expenditure constraints can delay unit upgrades or catalyst transitions. In addition, the concentration of the market means that supply disruptions or strategic moves by a small number of key players can have outsized effects on pricing and availability. Decision-makers need to monitor these variables closely and maintain flexibility in catalyst strategy and supplier relationships.
Strategic Recommendations for Decision-Makers
For manufacturers and technology suppliers, the priority is to align innovation with the operational realities that refiners face today. This means investing in catalyst capabilities that address iron poisoning, heavy feed conversion, and product quality targets, while also building the service and technical support infrastructure needed to prove value in real-world units. Suppliers should also consider how lifecycle economics, including disposal and recycling considerations, can be integrated into their offerings to strengthen customer partnerships and differentiate from commodity-focused competitors.
For investors and strategic financiers, the market offers a growth profile supported by regulatory pressure, feedstock complexity, and the ongoing need for refinery yield optimization. The key diligence question is differentiation: which companies have proprietary technologies, credible performance data, and the service capacity to capture value in a concentrated market? Investment theses should account for regional demand patterns, the pace of regulatory change, and the extent to which a player's portfolio is tied to specific feedstock or product trends that may evolve over time.
For refiners, procurement leaders, and operations teams, the strategic imperative is to treat catalyst selection as a unit-level economic decision rather than a routine procurement exercise. Evaluating candidates through the lens of total cost of ownership, contaminant handling, compliance support, and lifecycle services can reveal opportunities to reduce operating costs and improve unit reliability. Building vendor relationships that include technical collaboration, performance monitoring, and continuous optimization can help refineries adapt more quickly to feedstock shifts and regulatory changes.
The breadth of factors shaping the FCC catalyst market makes it difficult to navigate with generic assumptions or high-level market summaries alone. Feedstock strategies, regulatory trajectories, catalyst chemistry, and lifecycle economics all interact in ways that vary by refinery configuration, region, and operational priorities. Detailed segmentation data, unit-level cost modeling, and tailored scenario analysis can help decision-makers translate broad trends into specific actions, whether that involves choosing a catalyst platform, prioritizing investment in mitigation technology, or evaluating supplier partnerships. For organizations seeking to move from market awareness to concrete planning, deeper research and customized analysis can provide the granularity needed to align catalyst strategy with commercial objectives and operational risk tolerance.
For detailed analysis of this topic, please visit the official page: FCC Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electronic Grade Hydrofluoric Acid Market: Why 6.98% CAGR Signals Strategic Shifts
By pmarketresearch, 2026-09-21
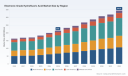
Electronic Grade Hydrofluoric Acid Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Snapshot: Scale, Trajectory, and Core Challenges
The electronic grade hydrofluoric acid sector has transitioned from a steady industrial chemical niche into a strategically critical supply chain component. Valued at approximately 163.15 million USD in 2020, the market reached 215.0 million USD by 2025 and is projected to expand to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98 percent across the 2026–2032 forecast horizon. This trajectory signals more than incremental demand growth; it reflects a structural realignment in how advanced electronics manufacturers secure ultra-pure wet processing chemicals amid tightening quality thresholds and shifting sourcing strategies.
By the close of 2025, revenue concentration had consolidated meaningfully among established producers, with the top three firms capturing roughly 62.5 percent of global sales and the top five reaching 78.3 percent. This concentration pattern underscores two realities: first, the technical and regulatory barriers to producing semiconductor-grade acids remain steep; second, end-users increasingly prefer suppliers with validated purity consistency, localized manufacturing footprints, and audit-ready compliance frameworks.
Key Challenges and Inflection Points
Despite the favorable long-term demand curve, several structural pressures are reshaping supply planning and margin dynamics.
Raw material volatility and upstream cost transmission have emerged as a persistent margin management challenge. In April 2026, the spot price for Electronic Grade G5 material reached 110,000 RMB per ton, marking a 40 percent increase from the start of the year, while the annual average price of anhydrous hydrofluoric acid in the United States climbed to 2,565 USD per metric ton by March 2026 following quarter-over-quarter increases. Fluorspar mining also encountered restrictions, environmental inspections, and holiday-related disruptions in early 2026, reinforcing a stable-to-firm global pricing environment. For buyers and producers alike, these shifts complicate long-term cost modeling and require more agile procurement architecture.
Geopolitical risk is now a first-order pricing variable rather than a peripheral concern. In early 2026, friction around the Strait of Hormuz curtailed marine traffic by more than 90 percent, pushing Brent crude to 88.87 USD per barrel and inflating Chinese HF spot offers by 12 percent month-over-month. This episode highlighted how energy logistics, freight routing, and regional supply concentration intersect with electronic chemical pricing in ways that traditional cost models often underestimate.
On the production side, regional output fluctuations add another layer of unpredictability. By April 2026, electronic grade hydrofluoric acid production output in China registered a modest year-on-year decline amid broader operating conditions, even as downstream demand from semiconductor and display supply chains continued to strengthen. Such episodic divergences between production capacity utilization and end-market demand emphasize the importance of visibility into regional operating environments, not just headline capacity figures.
Collectively, these dynamics point to an inflection point where cost resilience, geographic diversification, and purity assurance are becoming decisive competitive levers rather than operational afterthoughts.
Key Demand Drivers: What Is Really Propelling the Market
The expansion of the electronic grade hydrofluoric acid market is not simply a function of more devices being built; it is driven by specific technological, regulatory, and structural shifts that alter how and where ultra-pure acids are consumed.
Technology Innovation and Purity Thresholds
Semiconductor wafer manufacturing remains the dominant consumption arena, and the technical demands of advanced nodes are steadily redefining acceptable impurity thresholds. As patterning, etching, and cleaning steps become more sensitive to particulate and metallic contamination, the distinction between standard electronic grade and ultra-high-purity grades takes on commercial weight. Producers that can demonstrate repeatable control over trace contaminants, supported by robust analytical certification and lot-to-lot consistency, are positioned to secure longer-term supply agreements with leading fabs. This technical premium is also encouraging dual-track supply strategies, where manufacturers maintain both standard and ultra-high-purity sourcing channels to protect yield performance across different process steps.
Policy and Regulatory Environment
Regulatory scrutiny and sustainability expectations are reshaping sourcing decisions. Environmental inspections and operational restrictions across key fluorspar and HF supply regions have tightened availability windows and reinforced pricing firmness. At the same time, broader energy and logistics disruptions have accelerated the preference for suppliers with transparent compliance records and regionally balanced production capabilities. For procurement teams, regulatory visibility is now part of supplier qualification rather than a separate risk register item. Markets where producers can demonstrate environmental diligence, controlled emissions, and stable energy sourcing are gaining a structural advantage in qualification cycles.
Demand-Side Shifts Across Electronics End Markets
Beyond semiconductors, adjacent electronics applications continue to contribute to demand breadth. Solar cell fabrication and display panel manufacturing represent substantial consumption pathways, and each carries its own pace of process refinement and capacity cycles. In solar, improvements in cell architecture and throughput efficiency influence wet chemical consumption intensity, while display manufacturing continues to depend on high-purity etching and cleaning steps for large-format panels. These diversified demand streams reduce single-market dependency for suppliers and create opportunities for those able to manage multiple purity specifications and delivery formats without sacrificing consistency.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being reshaped by both input economics and regional capacity responses. Upstream price movements have been pronounced: PTFE prices from major producers rose 15–16 percent in March 2026, the steepest increase since 2024, reflecting how input cost pressure can propagate quickly into fluorine-based chemical value chains. Meanwhile, regional production expansions aim to improve supply assurance for local electronics clusters. One notable example is the expansion activity near a major rail line in Casa Grande, where an acquisition of additional land was announced to support scaled production and direct supply to nearby semiconductor manufacturers. Such localized capacity additions illustrate how logistics adjacency and regional customer proximity are increasingly integrated into supply strategy, not just production volume.
The net effect is a market in which cost leadership alone is no longer sufficient. Suppliers that combine disciplined input cost management with geographic flexibility, grade-specific capability, and transparent logistics planning are more likely to convert demand growth into durable contract wins.
Competitive Landscape and Leading Strategies
The competitive environment in electronic grade hydrofluoric acid reflects a blend of specialized fluorine chemistry manufacturers, diversified industrial suppliers, and regional players with strong local customer relationships. Leadership in this space is increasingly defined by grade coverage, supply reliability, and the ability to operate at the intersection of high-purity chemistry and regional demand clusters.
Strategic Positioning Among Key Players
Firms with deep fluorine chemistry heritage continue to anchor the market through specialized purification expertise and broad grade portfolios. Morita Chemical Industries and Stella Chemifa, both based in Osaka, Japan, maintain strong positions by focusing on high-purity fluoride chemicals and ultra-high-purity hydrofluoric acid for semiconductor etching and display applications. Their longstanding technical reputation provides a credibility advantage in qualification-heavy environments, where purity consistency and documentation rigor often outweigh short-term price differentials.
In the United States, supply strategies are increasingly oriented around regional security of supply and direct fab proximity. Honeywell International has reinforced its position with ultra-high-purity electronic grade solutions, including Puranal grades, for wafer cleaning and etching, alongside dedicated Texas production capacity. Sunlit Arizona, LLC, based in Phoenix, operates a facility capable of supplying up to 30 kilotons per year of electronic grade hydrofluoric acid directly to U.S. semiconductor fabs. Its April 2026 expansion move, involving the acquisition of additional acreage near a major rail line in Casa Grande, further demonstrates a logistics-integrated approach designed to support scaled production for local chip manufacturers. KMG Chemicals, headquartered in Dallas, contributes a distribution and supply footprint that broadens access to electronic grade material across semiconductor and electronics manufacturing channels.
European players preserve a strong specialty chemical orientation. Solvay, based in Brussels, produces high-purity hydrofluoric acid for semiconductor wafer etching and display panel applications, emphasizing integration into broader fluorochemical portfolios and established industrial reliability.
Chinese manufacturers represent a rapidly maturing segment with expanding technical capabilities and a growing emphasis on local electronics supply chains. Do-Fluoride Chemicals in Jiaozuo, Henan, produces high-purity electronic grade acid for microelectronics and semiconductor wet processing. Jiangyin Jianghua Microelectronics Materials, in Jiangsu, supplies ultra-clean electronic chemicals including high-purity hydrofluoric acid for semiconductor, LCD, and solar cell manufacturing. Zhejiang Juhua, operating as part of a broader fluorochemical portfolio in Zhejiang, has also expanded electronic grade hydrofluoric acid production for semiconductor applications. These players are increasingly relevant not only for cost-competitive supply but also for regional responsiveness and the ability to serve domestic electronics clusters at scale.
How the Landscape Is Evolving
The market structure is moving toward a hybrid model: concentration among proven high-purity suppliers continues, but regional capacity additions and localized supply relationships are creating more diversified sourcing pathways. This pattern favors suppliers that can offer credible purity credentials while also aligning with regional demand centers and logistics realities. It also encourages integration across production, distribution, and customer-facing technical support, since end-users are increasingly evaluating the full service package rather than the molecule alone.
At the same time, cost pressure and input volatility are testing margin discipline across the value chain. Producers that can manage upstream cost shocks, pass through pricing transparently where justified by specification and reliability, and maintain capacity utilization in the face of episodic regional output fluctuations are better positioned to protect profitability through the cycle.
Forward Outlook: Three Trends to Watch (2026–2031)
Looking ahead, the electronic grade hydrofluoric acid market is likely to be shaped by a small number of powerful forces that connect technology roadmaps, supply assurance priorities, and cost dynamics.
Electronic Grade Phosphoric Acid Market
Trend 1: Purity as a Standard Procurement Criterion, Not a Premium Feature
As advanced semiconductor processes and high-value display and solar processes continue to tighten contamination tolerance, the distinction between grades will increasingly become a baseline procurement requirement rather than a specialty upsell. Suppliers that invest in analytical rigor, lot traceability, and grade-specific process control are likely to capture a larger share of long-cycle agreements. The commercial opportunity lies in building qualification-ready documentation and consistency narratives that reduce buyer risk and accelerate source approval.
PW Consulting Chemical & Energy Research Center
Trend 2: Regionalization of Supply and Logistics-Advantaged Capacity
Demand for proximity, resilience, and predictable delivery is reinforcing regional capacity strategies. Expansion near customer clusters and major transport corridors is likely to remain a strategic priority, particularly where semiconductor manufacturing density is growing. The commercial opportunity is twofold: producers can secure stronger local contracts, and buyers can reduce exposure to long-haul logistics risk. However, regionalization also raises the importance of disciplined capacity planning, because localized supply advantages can be eroded if utilization or input availability becomes unstable.
Trend 3: Cost Volatility Becoming a Core Strategic Management Discipline
Input price movement, logistics shocks, and regulatory interruptions are likely to remain part of the operating environment. The recent pattern of sharp raw material price increases, energy-driven spot offer inflation, and episodic production output changes suggests that cost resilience will be judged as a strategic capability, not merely an accounting outcome. Companies that develop diversified sourcing, scenario-based pricing, and transparent cost communication will be better equipped to sustain customer trust during volatile periods. The associated risk is that firms without flexible cost structures may face margin compression or contract instability when input shocks recur.
Strategic Recommendations for Decision-Makers
Translating market dynamics into action requires differentiated approaches depending on the role a company plays in the value chain.
For Producers and Chemical Manufacturers
Invest in grade differentiation as a commercial moat. The ability to reliably deliver ultra-high-purity and VLSI-grade options, supported by strong quality documentation and stable lot performance, can create defensible positioning in qualification-heavy accounts. Pair this with regional capacity logic that aligns production with major electronics clusters and transport infrastructure, so that supply assurance becomes a visible customer benefit rather than an internal operational metric. Maintain disciplined cost management for upstream inputs and develop transparent pricing mechanisms that preserve trust when raw material conditions shift quickly.
Electronic Grade Nitric Acid Market
For Investors and Strategic Capital Allocators
Focus on business models that combine purity credibility with regional supply relevance and resilient input economics. Assets tied to high-purity electronics demand, especially where localized supply and logistics advantages can be demonstrated, are likely to capture more durable value than undifferentiated volume plays. Monitor the interplay between regional capacity additions, input cost trends such as fluorspar availability and anhydrous HF pricing, and episodic output changes in key production regions, because these factors will influence both top-line growth and margin stability. Prioritize visibility into operating conditions, not just announced capacity, when evaluating companies in this space.
For Procurement and Supply Chain Leaders
Treat purity assurance, regional availability, and cost volatility together rather than as separate sourcing variables. Diversify across proven high-purity suppliers and regionally responsive partners to reduce single-source exposure, and integrate logistics adjacency into supplier evaluation criteria where possible. Build scenario planning into procurement strategy so that rate negotiations and supply agreements can absorb raw material swings, energy-driven freight cost changes, and regulatory interruptions more effectively. In this environment, detailed intelligence on grade availability, regional operating conditions, and input cost direction can materially improve contract structure and risk allocation.
Closing Perspective
The electronic grade hydrofluoric acid market is expanding with a clear underlying logic: advanced electronics processing continues to demand cleaner, more reliable wet chemical supply, while cost, logistics, and regulatory pressures are forcing more sophisticated supply strategies. The combination of steady demand growth, rising purity expectations, and regional supply realignment is creating opportunities for companies that can deliver both technical reliability and supply resilience. At the same time, input volatility and geopolitical exposure remind the market that volume growth alone does not guarantee margin security.
For organizations making sourcing, production, or investment decisions in this space, the most valuable next step is to move from broad market direction to granular visibility: grade-level demand shifts, regional capacity and operating conditions, raw material cost trajectories, and the strategic positioning of key suppliers. Detailed segmentation data, supplier-level assessments, and customized scenario planning can turn these broad trends into actionable, risk-adjusted decisions.
For detailed analysis of this topic, please visit the official page: Electronic Grade Hydrofluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beyond 4.12% CAGR: Unpacking the Real Drivers of the Chlorinated Paraffin Market’s 2032 Trajectory
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Chlorinated Paraffin Market
Market Snapshot and Critical Inflection Points
The chlorinated paraffin market has demonstrated steady expansion over the 2020–2025 period, reaching approximately 2,075 million USD in 2025, up from 1,725 million USD five years earlier. The trajectory reflects consistent demand growth across downstream industrial sectors, supported by the material's versatile role as a secondary plasticizer, extreme-pressure additive, and flame retardant. Looking ahead to the forecast horizon through 2032, the market is projected to grow at a compound annual growth rate of 4.12 percent, rising toward 2,753 million USD by the final year of the outlook period. This expansion rate points to a market that is maturing but not stagnant, with growth increasingly dependent on selectivity in applications and regions rather than broad-based volume increases.
Several structural features of the current market warrant close attention from decision-makers. Market concentration data indicates that the top three players collectively command roughly 45 percent of global revenue, while the top five reach approximately 68 percent. This concentration level implies that a limited number of established producers hold significant sway over pricing dynamics, capacity allocation, and product standardization. At the same time, the long-tail presence of regional and specialty manufacturers creates a fragmented periphery where niche positioning remains viable. For new entrants or expanding players, this landscape presents a dual reality: barrier to scale are real, but fragmentation leaves room for targeted moves in specific value chains or geographies.
Beyond concentration patterns, the industry is navigating three critical inflection points that will define the next phase of growth. The first is the regulatory recalibration around chlorinated paraffin categories. Medium-chain chlorinated paraffins have been listed under Annex A of the Stockholm Convention for elimination from production and use in the European Union, marking a decisive shift in the treatment of this segment within one of the world's most influential chemical markets. Short-chain variants remain under restricted conditions in the United States, with the Environmental Protection Agency continuing risk management processes under TSCA. These regulatory developments are not uniformly global in timing or scope, but they create a patchwork of compliance obligations that complicate sourcing strategies, product specifications, and market access planning.
The second inflection point lies in raw material cost volatility and its transmission through the value chain. Feedstock costs for paraffin wax rose noticeably in the fourth quarter of 2025, pushing Northeast Asia chlorinated paraffin prices to approximately 0.66 USD per kilogram. The increase was supported by firmer upstream paraffin wax and chlorine feedstock costs that raised production expenses for manufacturers in the region. However, this cost pressure was followed by a reversal in early 2026, when heightened environmental scrutiny on chlorinated paraffins dampened downstream consumption activity in Northeast Asia, contributing to a price decline to roughly 0.60 USD per kilogram. This sequence illustrates how quickly the market can swing between cost-driven price increases and demand-driven corrections, especially in regions where regulatory sentiment and end-user confidence are closely intertwined.
The third inflection point is capacity expansion in response to perceived demand resilience. In June 2025, Lords Chloro Alkali Limited announced an expansion of its chlorinated paraffin wax production capacity from 50 tonnes per day to 100 tonnes per day at its Rajasthan facility. The move was positioned to meet rising demand from plastics, rubber, coatings, and metalworking industries. Such expansions signal that producers see durable application pull, particularly in markets where alternatives face performance or cost limitations. Yet, capacity additions also raise questions about whether incremental supply will outpace demand growth in certain segments, particularly if regulatory constraints or substitution dynamics narrower the addressable market faster than anticipated.
Core Drivers Shaping Market Trajectory
The market's direction is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces. Understanding how these drivers interact is essential for anticipating where growth will be most concentrated and where risk will accumulate.
Technological Innovation and Product Differentiation
Innovation in chlorinated paraffins is increasingly focused on performance stability, application specificity, and compatibility with evolving downstream formulations. Manufacturers are working to improve the consistency of chlorination levels, reduce impurity profiles, and develop stabilized or sulphochlorinated variants that perform reliably under the thermal and mechanical stresses of modern processing. These enhancements matter because downstream users in plastics compounding, rubber formulation, and metalworking fluids are under pressure to meet tighter performance specifications while managing material costs. Products that can deliver better dispersion, lower volatility, or improved resistance to degradation under processing conditions offer a tangible value proposition beyond price alone.
Paraffin Wax Market
At the same time, innovation is also occurring in the broader materials context, where alternatives such as non-chlorinated plasticizers, phosphate-based flame retardants, and bio-derived additives are gaining ground in certain applications. This dynamic pushes chlorinated paraffin producers to sharpen their technical positioning rather than compete solely on volume. Those that can demonstrate superior performance in specific use cases, such as extreme-pressure lubrication under high load or flame retardancy in PVC compounds where regulatory acceptance remains more favorable, are better equipped to defend share and command premium positioning.
Policy and Regulatory Environment
The regulatory environment is perhaps the most consequential driver shaping near-term strategy. The listing of medium-chain chlorinated paraffins under the Stockholm Convention's Annex A for elimination in the European Union represents a significant policy shift. It signals that jurisdictions with strong environmental governance are willing to target specific chlorinated paraffin categories even as other segments remain in use. This layered regulatory approach creates a complex operating environment where product classification, chain of custody, and end-use declaration become increasingly important for market access.
In parallel, short-chain chlorinated paraffins continue to face restrictions in the United States under TSCA, with the EPA maintaining ongoing risk management activities. While the regulatory treatment differs between regions and categories, the broader trajectory points toward greater scrutiny of chlorinated compounds, especially where persistence, bioaccumulation, or toxicological concerns are raised. For businesses, the implication is not that the entire market is under uniform threat, but that regulatory exposure varies by chain length, geography, and application. Companies that rely on a single product category or a narrow geographic footprint face heightened vulnerability if regulations shift in their core markets.
Demand-Side Shifts in End-Use Industries
Downstream demand is evolving as end-use industries balance performance requirements, cost pressures, and sustainability expectations. In plastics and rubber, chlorinated paraffins continue to serve as cost-effective secondary plasticizers and processing aids, particularly where PVC formulations require flexibility and flame retardancy without resorting to higher-cost alternatives. The metalworking fluids and lubricants segment remains important as well, given the material's established role as an extreme-pressure additive that reduces friction and wear under demanding operating conditions. These applications benefit from well-understood performance characteristics and long-standing formulation familiarity among end users.
However, demand patterns are also being influenced by end-users' increasing attention to regulatory compliance and supply chain transparency. Buyers in coatings, adhesives, and industrial lubricants are more likely to request documentation regarding product classification, regional compliance status, and handling requirements. This creates an advantage for suppliers that can provide clear technical data sheets, compliance statements, and application-specific guidance. Conversely, suppliers that cannot respond to these information demands risk losing visibility in customer qualification processes, particularly in regions where regulatory and procurement standards are tightening.
Chlorinated Polyolefin Market
Supply Chain and Cost Structure Dynamics
The cost structure of chlorinated paraffin production is closely linked to the availability and pricing of paraffin wax and chlorine feedstocks. When feedstock costs rise, producers face pressure to pass through increases or absorb them in margin compression. The late-2025 price movement in Northeast Asia, driven by firmer upstream costs, shows how quickly feedstock conditions can affect realized pricing. The subsequent early-2026 decline, tied to reduced downstream consumption under environmental scrutiny, illustrates that cost-side pressures do not automatically translate into sustained price gains if demand sentiment weakens.
Supply chain considerations also extend to logistics, regional production footprint, and the ability to serve customers with consistent quality and timing. Producers with integrated or proximate feedstock access, flexible operational setups, and well-distributed customer service networks are better positioned to manage cost volatility and maintain reliability. In contrast, producers that depend heavily on long-distance feedstock flows or operate in regions with pronounced regulatory uncertainty may find it harder to compete on both cost and availability. As capacity expansions come online, the balance between localized supply advantages and global price convergence will become an important strategic variable.
Competitive Landscape and Leading Strategies
The competitive environment in chlorinated paraffins is characterized by a mix of large established producers, regional specialists, and application-focused manufacturers. The leading companies have built their positions not simply on scale, but on product range breadth, application know-how, and the ability to serve specific verticals with tailored formulations.
Dover Chemical Corporation, based in Dover, Ohio, has focused on liquid chlorinated alkanes and other chlorinated paraffins under the Paroil® brand, with emphasis on medium- and long-chain products used as plasticizers, flame retardants, and extreme-pressure additives in metalworking fluids and lubricants. This application-oriented framing allows the company to align its offerings with the operational needs of lubricant and metalworking fluid formulators, where extreme-pressure performance and additive compatibility are critical. INEOS Chlor, operating from Runcorn in the United Kingdom, offers the Cereclor range of medium- and long-chain chlorinated paraffins for similar end uses, reinforcing the importance of long-standing product lines in lubricants, metalworking fluids, and polymer applications. The presence of multiple global players emphasizing medium- and long-chain variants reflects a strategic preference for segments where regulatory exposure and performance acceptance can be more manageable than in the short-chain category.
PW Consulting Chemical & Energy Research Center
Caffaro Industrie S.p.A., headquartered in Torviscosa, Italy, produces Cloparin®, Cloparol®, and Cloparten® chlorinated paraffins covering normal, stabilized, and sulphochlorinated variants for plastics, metalworking, and tanning applications. The breadth of product types and application coverage demonstrates a strategy centered on serving multiple industries with differentiated formulations. JSC Kaustik, one of the larger Russian producers, manufactures a wide portfolio of chlorinated paraffin waxes, including CP-30, CP-52, CP-250, CP-418, and CP-470A, used as secondary plasticizers in PVC compounds and other polymers. This scale and product range underscore the significance of regional production hubs that can serve polymer compounding markets with cost-competitive and specification-diverse offerings.
Aditya Birla Chemicals, based in Mumbai, India, operates as an integrated producer of chlorinated paraffins within a broader specialty chemicals portfolio, targeting plastics, rubber, and flame-retardant applications. Integration within a larger chemicals platform can provide feedstock linkages, financial scale, and market access advantages. LEUNA-Tenside GmbH, Altair Chimica SpA, and Química del Cinca S.A. add further regional depth, each supplying chlorinated paraffins and related chemistries for lubricants, metalworking fluids, polymer compounds, rubber, and plastics. Their presence highlights the role of European and Mediterranean-based manufacturers in meeting regional demand with application-specific products and technical support.
In Asia and other growth regions, KLJ Group in Mumbai and NCP Chlorchem (Pty) Ltd in Port Elizabeth, South Africa, illustrate the continued importance of producers positioned to serve industrial chemical markets with flame retardants, plasticizers, lubricants, and metalworking fluid applications. These companies benefit from proximity to end-use industries and the ability to respond to regional demand patterns, though they also face the same feedstock and regulatory considerations as larger global players.
The competitive landscape is evolving along several axes. First, consolidation pressure exists at the top of the market, where larger players with broader product portfolios and stronger technical service capabilities can capture share from smaller competitors that lack differentiation. Second, regional divergence is increasing, as regulatory differences and feedstock availability create distinct competitive conditions in Europe, North America, Asia Pacific, Latin America, and Africa. Third, new entrants and expanding producers, such as the capacity increase announced by Lords Chloro Alkali Limited, are betting on demand growth in plastics, rubber, coatings, and metalworking sectors. Whether such moves translate into durable share gains will depend on how well new capacity aligns with the segments that remain most commercially viable under evolving regulation.
Leading strategists in this market tend to focus on three differentiators. The first is application-specific value delivery, where products are positioned not as generic commodities but as solutions for extreme-pressure lubrication, PVC plasticization, or flame retardancy in specified formulations. The second is regulatory readiness, including the ability to classify products accurately, provide compliance documentation, and guide customers through regional requirements. The third is supply reliability and feedstock management, which becomes increasingly important as cost volatility and capacity changes reshape the competitive balance. Companies that combine these strengths are better placed to navigate a market where growth is uneven and regulatory interpretation varies by jurisdiction.
Forward-Looking Trends and Commercial Opportunities
Looking toward the next three to five years, several trends are likely to shape where opportunity concentrates and where risk accumulates. These trends are not independent; they interact with feedstock costs, regulatory developments, and end-use demand in ways that will determine which segments outperform.
Shift Toward Medium- and Long-Chain Positioning
The trend toward greater regulatory scrutiny of certain chlorinated paraffin categories is likely to reinforce a strategic shift toward medium- and long-chain products in markets where these variants retain clearer acceptance. This does not mean short-chain products will disappear across all geographies, but it does suggest that commercial emphasis will increasingly tilt toward segments with more favorable regulatory profiles and established performance roles in metalworking fluids, lubricants, and selected polymer applications. For producers and investors, the opportunity lies in strengthening product lines, technical documentation, and application support for these categories, while carefully managing exposure to categories facing elimination or restriction in key markets.
Regional Divergence and Market Fragmentation
Regulatory and cost conditions are unlikely to move uniformly across regions. Divergence between Europe, North America, Asia Pacific, and other regions will create pockets of opportunity where demand remains robust and regulatory pathways are clearer. Asia Pacific, as a large and diverse region, will continue to be significant, but the pace and direction of growth may vary by country and by application as environmental scrutiny and feedstock conditions evolve. This fragmentation rewards companies that build regional competencies, adapt formulations to local requirements, and maintain flexible sourcing and distribution networks. It also creates risks for businesses that assume a single global strategy will work across all markets without adjustment.
Performance-Led Differentiation Over Pure Volume Competition
As feedstock costs fluctuate and regulatory expectations rise, competition on price alone becomes riskier and less sustainable. The trend is toward performance-led differentiation, where suppliers compete on functional benefits such as extreme-pressure performance, stability under processing conditions, compatibility with complex formulations, and support for customer compliance needs. This shift opens commercial opportunities for companies that invest in technical service, application testing, and formulation guidance. It also suggests that customers will increasingly reward suppliers who reduce uncertainty in the qualification process, particularly in industries where downtime, rework, or compliance failures carry significant cost.
These trends carry potential risks. If capacity expansions outpace demand growth in specific segments, price competition could intensify and compress margins. If regulatory measures extend to additional categories or tighten in important end-use markets, demand could shift faster than producers can adapt. If alternative materials improve in cost-performance balance, substitution pressure could erode share in applications that have historically relied on chlorinated paraffins. Monitoring these risks requires close attention to feedstock pricing, regulatory timelines, and downstream formulation trends, rather than relying on aggregate market growth figures alone.
Actionable Guidance for Decision-Makers
Different roles within the market face distinct strategic priorities, but all benefit from clearer visibility into where growth is durable and where exposure is rising. The following recommendations are intended to help manufacturers, investors, and procurement teams orient their decisions in a market that is steady in aggregate but uneven in detail.
-
For manufacturers and producers, prioritize application-specific positioning and regulatory readiness. Develop clear documentation and technical support for medium- and long-chain products where regulatory acceptance is more favorable, and ensure that product classification and compliance statements are precise enough to support customer qualification in multiple regions. Evaluate whether capacity expansion plans align with segments that retain demand momentum under current regulatory trajectories, rather than relying on broad volume growth assumptions. Feedstock sourcing and regional production footprint should be reviewed for resilience against cost volatility and logistics disruption.
-
For investors and strategic planners, focus on differentiation quality rather than headline market size. The market's projected growth trajectory is positive, but value creation will likely accrue to players that can defend application niches, manage regulatory complexity, and maintain cost discipline. Assess exposure by chain length, geography, and end-use, and weigh the risk of substitution and regulatory tightening in specific segments. When evaluating expansion or consolidation moves, consider whether the target's competitive advantage rests on product range breadth, technical service capability, feedstock integration, or regional market access, because these factors will determine durability in a fragmented and evolving landscape.
-
For procurement and supply chain leaders, treat supplier selection as a risk-management decision as much as a cost decision. Request product classification clarity, regional compliance status, and application-specific performance data, especially for uses subject to tighter regulatory or quality requirements. Diversify sourcing where possible to reduce reliance on a single region or supplier type, and monitor feedstock-driven price movements and demand sentiment shifts that can affect availability and cost over short time horizons. Building stronger technical dialogue with suppliers can also improve formulation stability and reduce the risk of qualification delays.
The chlorinated paraffin market is at a point where aggregate growth is meaningful but not sufficient to guide detailed decisions. Chain-length dynamics, regulatory divergence, feedstock volatility, and application-specific demand are shaping a landscape in which strategic positioning matters more than ever. There is substantial value in accessing more granular data on regional demand patterns, segment-level revenue splits, competitive capacity moves, and regulatory timelines, particularly for teams making sourcing, expansion, or investment choices with multi-year consequences. For those seeking deeper segmentation, scenario analysis, and customized recommendations, a more detailed research resource can provide the level of specificity needed to move from broad market awareness to executable strategy.
For detailed analysis of this topic, please visit the official page: Chlorinated Paraffin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com