

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Beyond 4.12% CAGR: Unpacking the Real Drivers of the Chlorinated Paraffin Market’s 2032 Trajectory

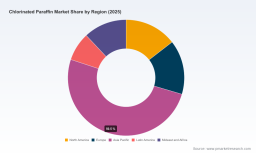
Strategic Trends and Commercial Opportunities in the Global Chlorinated Paraffin Market
Market Snapshot and Critical Inflection Points
The chlorinated paraffin market has demonstrated steady expansion over the 2020–2025 period, reaching approximately 2,075 million USD in 2025, up from 1,725 million USD five years earlier. The trajectory reflects consistent demand growth across downstream industrial sectors, supported by the material's versatile role as a secondary plasticizer, extreme-pressure additive, and flame retardant. Looking ahead to the forecast horizon through 2032, the market is projected to grow at a compound annual growth rate of 4.12 percent, rising toward 2,753 million USD by the final year of the outlook period. This expansion rate points to a market that is maturing but not stagnant, with growth increasingly dependent on selectivity in applications and regions rather than broad-based volume increases.
Several structural features of the current market warrant close attention from decision-makers. Market concentration data indicates that the top three players collectively command roughly 45 percent of global revenue, while the top five reach approximately 68 percent. This concentration level implies that a limited number of established producers hold significant sway over pricing dynamics, capacity allocation, and product standardization. At the same time, the long-tail presence of regional and specialty manufacturers creates a fragmented periphery where niche positioning remains viable. For new entrants or expanding players, this landscape presents a dual reality: barrier to scale are real, but fragmentation leaves room for targeted moves in specific value chains or geographies.
Beyond concentration patterns, the industry is navigating three critical inflection points that will define the next phase of growth. The first is the regulatory recalibration around chlorinated paraffin categories. Medium-chain chlorinated paraffins have been listed under Annex A of the Stockholm Convention for elimination from production and use in the European Union, marking a decisive shift in the treatment of this segment within one of the world's most influential chemical markets. Short-chain variants remain under restricted conditions in the United States, with the Environmental Protection Agency continuing risk management processes under TSCA. These regulatory developments are not uniformly global in timing or scope, but they create a patchwork of compliance obligations that complicate sourcing strategies, product specifications, and market access planning.
The second inflection point lies in raw material cost volatility and its transmission through the value chain. Feedstock costs for paraffin wax rose noticeably in the fourth quarter of 2025, pushing Northeast Asia chlorinated paraffin prices to approximately 0.66 USD per kilogram. The increase was supported by firmer upstream paraffin wax and chlorine feedstock costs that raised production expenses for manufacturers in the region. However, this cost pressure was followed by a reversal in early 2026, when heightened environmental scrutiny on chlorinated paraffins dampened downstream consumption activity in Northeast Asia, contributing to a price decline to roughly 0.60 USD per kilogram. This sequence illustrates how quickly the market can swing between cost-driven price increases and demand-driven corrections, especially in regions where regulatory sentiment and end-user confidence are closely intertwined.
The third inflection point is capacity expansion in response to perceived demand resilience. In June 2025, Lords Chloro Alkali Limited announced an expansion of its chlorinated paraffin wax production capacity from 50 tonnes per day to 100 tonnes per day at its Rajasthan facility. The move was positioned to meet rising demand from plastics, rubber, coatings, and metalworking industries. Such expansions signal that producers see durable application pull, particularly in markets where alternatives face performance or cost limitations. Yet, capacity additions also raise questions about whether incremental supply will outpace demand growth in certain segments, particularly if regulatory constraints or substitution dynamics narrower the addressable market faster than anticipated.
Core Drivers Shaping Market Trajectory
The market's direction is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces. Understanding how these drivers interact is essential for anticipating where growth will be most concentrated and where risk will accumulate.
Technological Innovation and Product Differentiation
Innovation in chlorinated paraffins is increasingly focused on performance stability, application specificity, and compatibility with evolving downstream formulations. Manufacturers are working to improve the consistency of chlorination levels, reduce impurity profiles, and develop stabilized or sulphochlorinated variants that perform reliably under the thermal and mechanical stresses of modern processing. These enhancements matter because downstream users in plastics compounding, rubber formulation, and metalworking fluids are under pressure to meet tighter performance specifications while managing material costs. Products that can deliver better dispersion, lower volatility, or improved resistance to degradation under processing conditions offer a tangible value proposition beyond price alone.
Paraffin Wax Market
At the same time, innovation is also occurring in the broader materials context, where alternatives such as non-chlorinated plasticizers, phosphate-based flame retardants, and bio-derived additives are gaining ground in certain applications. This dynamic pushes chlorinated paraffin producers to sharpen their technical positioning rather than compete solely on volume. Those that can demonstrate superior performance in specific use cases, such as extreme-pressure lubrication under high load or flame retardancy in PVC compounds where regulatory acceptance remains more favorable, are better equipped to defend share and command premium positioning.
Policy and Regulatory Environment
The regulatory environment is perhaps the most consequential driver shaping near-term strategy. The listing of medium-chain chlorinated paraffins under the Stockholm Convention's Annex A for elimination in the European Union represents a significant policy shift. It signals that jurisdictions with strong environmental governance are willing to target specific chlorinated paraffin categories even as other segments remain in use. This layered regulatory approach creates a complex operating environment where product classification, chain of custody, and end-use declaration become increasingly important for market access.
In parallel, short-chain chlorinated paraffins continue to face restrictions in the United States under TSCA, with the EPA maintaining ongoing risk management activities. While the regulatory treatment differs between regions and categories, the broader trajectory points toward greater scrutiny of chlorinated compounds, especially where persistence, bioaccumulation, or toxicological concerns are raised. For businesses, the implication is not that the entire market is under uniform threat, but that regulatory exposure varies by chain length, geography, and application. Companies that rely on a single product category or a narrow geographic footprint face heightened vulnerability if regulations shift in their core markets.
Demand-Side Shifts in End-Use Industries
Downstream demand is evolving as end-use industries balance performance requirements, cost pressures, and sustainability expectations. In plastics and rubber, chlorinated paraffins continue to serve as cost-effective secondary plasticizers and processing aids, particularly where PVC formulations require flexibility and flame retardancy without resorting to higher-cost alternatives. The metalworking fluids and lubricants segment remains important as well, given the material's established role as an extreme-pressure additive that reduces friction and wear under demanding operating conditions. These applications benefit from well-understood performance characteristics and long-standing formulation familiarity among end users.
However, demand patterns are also being influenced by end-users' increasing attention to regulatory compliance and supply chain transparency. Buyers in coatings, adhesives, and industrial lubricants are more likely to request documentation regarding product classification, regional compliance status, and handling requirements. This creates an advantage for suppliers that can provide clear technical data sheets, compliance statements, and application-specific guidance. Conversely, suppliers that cannot respond to these information demands risk losing visibility in customer qualification processes, particularly in regions where regulatory and procurement standards are tightening.
Chlorinated Polyolefin Market
Supply Chain and Cost Structure Dynamics
The cost structure of chlorinated paraffin production is closely linked to the availability and pricing of paraffin wax and chlorine feedstocks. When feedstock costs rise, producers face pressure to pass through increases or absorb them in margin compression. The late-2025 price movement in Northeast Asia, driven by firmer upstream costs, shows how quickly feedstock conditions can affect realized pricing. The subsequent early-2026 decline, tied to reduced downstream consumption under environmental scrutiny, illustrates that cost-side pressures do not automatically translate into sustained price gains if demand sentiment weakens.
Supply chain considerations also extend to logistics, regional production footprint, and the ability to serve customers with consistent quality and timing. Producers with integrated or proximate feedstock access, flexible operational setups, and well-distributed customer service networks are better positioned to manage cost volatility and maintain reliability. In contrast, producers that depend heavily on long-distance feedstock flows or operate in regions with pronounced regulatory uncertainty may find it harder to compete on both cost and availability. As capacity expansions come online, the balance between localized supply advantages and global price convergence will become an important strategic variable.
Competitive Landscape and Leading Strategies
The competitive environment in chlorinated paraffins is characterized by a mix of large established producers, regional specialists, and application-focused manufacturers. The leading companies have built their positions not simply on scale, but on product range breadth, application know-how, and the ability to serve specific verticals with tailored formulations.
Dover Chemical Corporation, based in Dover, Ohio, has focused on liquid chlorinated alkanes and other chlorinated paraffins under the Paroil® brand, with emphasis on medium- and long-chain products used as plasticizers, flame retardants, and extreme-pressure additives in metalworking fluids and lubricants. This application-oriented framing allows the company to align its offerings with the operational needs of lubricant and metalworking fluid formulators, where extreme-pressure performance and additive compatibility are critical. INEOS Chlor, operating from Runcorn in the United Kingdom, offers the Cereclor range of medium- and long-chain chlorinated paraffins for similar end uses, reinforcing the importance of long-standing product lines in lubricants, metalworking fluids, and polymer applications. The presence of multiple global players emphasizing medium- and long-chain variants reflects a strategic preference for segments where regulatory exposure and performance acceptance can be more manageable than in the short-chain category.
PW Consulting Chemical & Energy Research Center
Caffaro Industrie S.p.A., headquartered in Torviscosa, Italy, produces Cloparin®, Cloparol®, and Cloparten® chlorinated paraffins covering normal, stabilized, and sulphochlorinated variants for plastics, metalworking, and tanning applications. The breadth of product types and application coverage demonstrates a strategy centered on serving multiple industries with differentiated formulations. JSC Kaustik, one of the larger Russian producers, manufactures a wide portfolio of chlorinated paraffin waxes, including CP-30, CP-52, CP-250, CP-418, and CP-470A, used as secondary plasticizers in PVC compounds and other polymers. This scale and product range underscore the significance of regional production hubs that can serve polymer compounding markets with cost-competitive and specification-diverse offerings.
Aditya Birla Chemicals, based in Mumbai, India, operates as an integrated producer of chlorinated paraffins within a broader specialty chemicals portfolio, targeting plastics, rubber, and flame-retardant applications. Integration within a larger chemicals platform can provide feedstock linkages, financial scale, and market access advantages. LEUNA-Tenside GmbH, Altair Chimica SpA, and Química del Cinca S.A. add further regional depth, each supplying chlorinated paraffins and related chemistries for lubricants, metalworking fluids, polymer compounds, rubber, and plastics. Their presence highlights the role of European and Mediterranean-based manufacturers in meeting regional demand with application-specific products and technical support.
In Asia and other growth regions, KLJ Group in Mumbai and NCP Chlorchem (Pty) Ltd in Port Elizabeth, South Africa, illustrate the continued importance of producers positioned to serve industrial chemical markets with flame retardants, plasticizers, lubricants, and metalworking fluid applications. These companies benefit from proximity to end-use industries and the ability to respond to regional demand patterns, though they also face the same feedstock and regulatory considerations as larger global players.
The competitive landscape is evolving along several axes. First, consolidation pressure exists at the top of the market, where larger players with broader product portfolios and stronger technical service capabilities can capture share from smaller competitors that lack differentiation. Second, regional divergence is increasing, as regulatory differences and feedstock availability create distinct competitive conditions in Europe, North America, Asia Pacific, Latin America, and Africa. Third, new entrants and expanding producers, such as the capacity increase announced by Lords Chloro Alkali Limited, are betting on demand growth in plastics, rubber, coatings, and metalworking sectors. Whether such moves translate into durable share gains will depend on how well new capacity aligns with the segments that remain most commercially viable under evolving regulation.
Leading strategists in this market tend to focus on three differentiators. The first is application-specific value delivery, where products are positioned not as generic commodities but as solutions for extreme-pressure lubrication, PVC plasticization, or flame retardancy in specified formulations. The second is regulatory readiness, including the ability to classify products accurately, provide compliance documentation, and guide customers through regional requirements. The third is supply reliability and feedstock management, which becomes increasingly important as cost volatility and capacity changes reshape the competitive balance. Companies that combine these strengths are better placed to navigate a market where growth is uneven and regulatory interpretation varies by jurisdiction.
Forward-Looking Trends and Commercial Opportunities
Looking toward the next three to five years, several trends are likely to shape where opportunity concentrates and where risk accumulates. These trends are not independent; they interact with feedstock costs, regulatory developments, and end-use demand in ways that will determine which segments outperform.
Shift Toward Medium- and Long-Chain Positioning
The trend toward greater regulatory scrutiny of certain chlorinated paraffin categories is likely to reinforce a strategic shift toward medium- and long-chain products in markets where these variants retain clearer acceptance. This does not mean short-chain products will disappear across all geographies, but it does suggest that commercial emphasis will increasingly tilt toward segments with more favorable regulatory profiles and established performance roles in metalworking fluids, lubricants, and selected polymer applications. For producers and investors, the opportunity lies in strengthening product lines, technical documentation, and application support for these categories, while carefully managing exposure to categories facing elimination or restriction in key markets.
Regional Divergence and Market Fragmentation
Regulatory and cost conditions are unlikely to move uniformly across regions. Divergence between Europe, North America, Asia Pacific, and other regions will create pockets of opportunity where demand remains robust and regulatory pathways are clearer. Asia Pacific, as a large and diverse region, will continue to be significant, but the pace and direction of growth may vary by country and by application as environmental scrutiny and feedstock conditions evolve. This fragmentation rewards companies that build regional competencies, adapt formulations to local requirements, and maintain flexible sourcing and distribution networks. It also creates risks for businesses that assume a single global strategy will work across all markets without adjustment.
Performance-Led Differentiation Over Pure Volume Competition
As feedstock costs fluctuate and regulatory expectations rise, competition on price alone becomes riskier and less sustainable. The trend is toward performance-led differentiation, where suppliers compete on functional benefits such as extreme-pressure performance, stability under processing conditions, compatibility with complex formulations, and support for customer compliance needs. This shift opens commercial opportunities for companies that invest in technical service, application testing, and formulation guidance. It also suggests that customers will increasingly reward suppliers who reduce uncertainty in the qualification process, particularly in industries where downtime, rework, or compliance failures carry significant cost.
These trends carry potential risks. If capacity expansions outpace demand growth in specific segments, price competition could intensify and compress margins. If regulatory measures extend to additional categories or tighten in important end-use markets, demand could shift faster than producers can adapt. If alternative materials improve in cost-performance balance, substitution pressure could erode share in applications that have historically relied on chlorinated paraffins. Monitoring these risks requires close attention to feedstock pricing, regulatory timelines, and downstream formulation trends, rather than relying on aggregate market growth figures alone.
Actionable Guidance for Decision-Makers
Different roles within the market face distinct strategic priorities, but all benefit from clearer visibility into where growth is durable and where exposure is rising. The following recommendations are intended to help manufacturers, investors, and procurement teams orient their decisions in a market that is steady in aggregate but uneven in detail.
-
For manufacturers and producers, prioritize application-specific positioning and regulatory readiness. Develop clear documentation and technical support for medium- and long-chain products where regulatory acceptance is more favorable, and ensure that product classification and compliance statements are precise enough to support customer qualification in multiple regions. Evaluate whether capacity expansion plans align with segments that retain demand momentum under current regulatory trajectories, rather than relying on broad volume growth assumptions. Feedstock sourcing and regional production footprint should be reviewed for resilience against cost volatility and logistics disruption.
-
For investors and strategic planners, focus on differentiation quality rather than headline market size. The market's projected growth trajectory is positive, but value creation will likely accrue to players that can defend application niches, manage regulatory complexity, and maintain cost discipline. Assess exposure by chain length, geography, and end-use, and weigh the risk of substitution and regulatory tightening in specific segments. When evaluating expansion or consolidation moves, consider whether the target's competitive advantage rests on product range breadth, technical service capability, feedstock integration, or regional market access, because these factors will determine durability in a fragmented and evolving landscape.
-
For procurement and supply chain leaders, treat supplier selection as a risk-management decision as much as a cost decision. Request product classification clarity, regional compliance status, and application-specific performance data, especially for uses subject to tighter regulatory or quality requirements. Diversify sourcing where possible to reduce reliance on a single region or supplier type, and monitor feedstock-driven price movements and demand sentiment shifts that can affect availability and cost over short time horizons. Building stronger technical dialogue with suppliers can also improve formulation stability and reduce the risk of qualification delays.
The chlorinated paraffin market is at a point where aggregate growth is meaningful but not sufficient to guide detailed decisions. Chain-length dynamics, regulatory divergence, feedstock volatility, and application-specific demand are shaping a landscape in which strategic positioning matters more than ever. There is substantial value in accessing more granular data on regional demand patterns, segment-level revenue splits, competitive capacity moves, and regulatory timelines, particularly for teams making sourcing, expansion, or investment choices with multi-year consequences. For those seeking deeper segmentation, scenario analysis, and customized recommendations, a more detailed research resource can provide the level of specificity needed to move from broad market awareness to executable strategy.
For detailed analysis of this topic, please visit the official page: Chlorinated Paraffin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com