

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
FCC Catalyst Market: Why Top Players’ 5.5% CAGR Strategy Reveals New Growth Paths

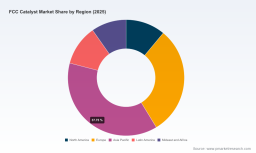
FCC Catalyst Market: Strategic Trends and Commercial Opportunities in a Transforming Refining Landscape
The global Fluid Catalytic Cracking (FCC) catalyst market has entered a phase of measured but purposeful growth, driven by a complex interplay of refinery economics, feedstock evolution, and tightening environmental standards. From a base of approximately $2.45 billion in 2020, the market expanded to around $3.0 billion by 2025, reflecting an average compound annual growth rate of roughly 5.5 percent over the historical period. This trajectory is expected to continue through 2032, with the market crossing the $4.3 billion threshold by the end of the forecast horizon. The growth is not uniform, nor is it guaranteed by volume alone. It is being shaped by strategic decisions around catalyst selection, unit configuration, and the shifting economics of heavy feedstock conversion.
PW Consulting Chemical & Energy Research Center
For decision-makers operating in or adjacent to the refining and petrochemical value chains, the FCC catalyst segment represents both a critical operational input and a strategic lever. Catalyst performance directly influences yield structures, unit reliability, and compliance costs. At the same time, the market's underlying dynamics are evolving rapidly, introducing new risks and opportunities that demand a clear-eyed view of where the industry is headed.
The current market environment is characterized by three interconnected challenges that are reshaping how refiners and catalyst suppliers approach FCC operations. First, feedstock volatility and the increasing use of opportunity crudes are testing the limits of conventional catalyst formulations. As refineries pursue margin advantages by processing heavier, more complex feeds, they encounter contaminants such as iron that can degrade catalyst activity and accelerate deactivation. This reality is pushing the industry toward mitigation technologies and more resilient catalyst designs, but it also increases the operational and economic stakes of catalyst selection.
Second, the regulatory landscape is tightening at a pace that outstrips incremental process adjustments. Environmental standards are increasingly focused on sulfur reduction, product quality, and the overall emissions footprint of refining operations. These requirements are not merely compliance checkboxes; they are changing the economics of FCC unit design and catalyst performance optimization. Refiners are being compelled to adopt advanced catalysts and additive packages that can deliver cleaner product slates without sacrificing conversion efficiency or unit stability. The cost of non-compliance, including operational disruptions and potential penalties, is becoming a material factor in catalyst investment decisions.
Third, the end-of-life management of spent catalysts is emerging as a significant cost and sustainability pressure point. Landfilling restrictions, disposal fees, and rising environmental liabilities are adding to the total cost of ownership for FCC catalysts. In several regions, the disposal cost for spent catalyst has climbed substantially, turning what was once a backward-looking operational issue into a forward-looking strategic concern. Refiners are increasingly recognizing that catalyst lifecycle economics, including regeneration, recycling, and disposal, must be integrated into unit planning and vendor selection.
Technology Innovation as a Competitive Imperative
Technological advancement is no longer a nice-to-have in the FCC catalyst market; it is a core determinant of unit profitability and strategic flexibility. Recent product launches illustrate how suppliers are responding to the dual pressures of feedstock complexity and product quality requirements. One notable example is the introduction of a catalyst technology designed to address iron poisoning, a growing challenge as refiners process iron-rich opportunity crudes. Commercial trials have demonstrated significant improvements in accessibility and the ability to handle heavier, more problematic feedstocks without compromising unit performance. This type of innovation directly attacks a key operational risk, reducing unplanned downtime and extending effective catalyst life.
At the same time, other developments are targeting the yield side of the equation. New catalyst platforms are being engineered to maximize high-octane gasoline blending stocks from gasoil and mild resid feeds, aligning FCC output with downstream fuel specification demands. These solutions reflect a broader trend: catalyst suppliers are moving beyond generic performance improvements to deliver tailored responses to specific refinery configurations, feed characteristics, and product slate objectives. The competitive advantage increasingly lies in the ability to match catalyst chemistry with the precise operational and regulatory context of the end user.
FCC Catalyst Additive; FCC Catalyst and Additives Market
Regulatory and Environmental Pressures Reshaping Demand
Policy and regulatory developments are acting as both a constraint and a catalyst for innovation. Updated testing and evaluation standards are formalizing how catalyst activity and selectivity are measured, creating a more rigorous framework for performance comparison and compliance. These standards matter because they influence procurement decisions, unit optimization strategies, and the credibility of supplier claims. In parallel, broader environmental regulations are pushing refiners toward catalysts and processes that can more effectively convert heavy feeds into cleaner products, reducing sulfur and other emissions-linked components.
The regulatory trajectory also intersects with feedstock economics. As environmental rules become more stringent, the economic case for processing heavy feedstocks depends increasingly on the ability to manage contaminants, maintain catalyst activity, and achieve target product specifications. This creates a feedback loop: regulation raises the bar for performance, which in turn incentivizes technology development and more sophisticated catalyst selection. For refiners, the implication is clear. Compliance is not a separate function from catalyst strategy; it is a central input into how FCC units are configured, operated, and upgraded.
Feedstock Economics and Cost Structure Dynamics
The cost structure of FCC operations is being reshaped by both feedstock trends and catalyst procurement economics. Refiners are navigating a landscape where crude differentials, opportunity crude availability, and contaminant levels can shift rapidly, affecting unit behavior and catalyst consumption rates. At the same time, the average cost of catalyst material remains a significant line item in refinery operating budgets. Optimized catalyst selection and usage patterns can deliver substantial annual savings per unit, underscoring the fact that catalyst economics are not just about price per ton but about total lifecycle value.
Disposal and recycling costs further complicate the picture. In markets where spent catalyst landfilling has become more expensive, the total cost of ownership rises, and the economic incentive to extend catalyst life or improve regeneration and recycling pathways becomes stronger. This is pushing attention toward solutions that reduce waste generation, improve metal trapping efficiency, and support more sustainable end-of-life options. For suppliers, it opens a strategic avenue: value propositions that combine performance, longevity, and lifecycle cost reduction are increasingly compelling in a cost-conscious environment.
Competitive Landscape and Strategic Positioning
The FCC catalyst market remains concentrated, with a small group of leading players accounting for a dominant share of revenue and technology offerings. This concentration reflects the high barriers to entry associated with catalyst chemistry, process integration expertise, and long-term refinery relationships. The competitive field includes globally recognized specialists in FCC catalysis, major chemical and catalyst companies with broad refinery portfolios, and integrated producers with strong regional presence and supply chain advantages.
Leading suppliers are differentiating themselves along several axes. Some are emphasizing proprietary catalyst platforms that address specific operational challenges, such as heavy feed processing, iron poisoning mitigation, or high-octane gasoline maximization. Others are leveraging integrated technology offerings that combine catalyst products with process licensing, unit optimization services, and post-treatment solutions. This bundling reflects a strategic shift from product-centric competition to solution-centric engagement, where the value delivered is tied to overall refinery economics rather than catalyst performance in isolation.
Regional dynamics also shape competitive positioning. Suppliers with strong local presence, technical support networks, and understanding of regional feedstock and regulatory contexts can gain advantages in key markets. At the same time, integrated producers participating in national refining ecosystems often benefit from coordinated supply chains and captive demand, allowing them to scale rapidly and influence regional market structures. The result is a landscape where global technology leadership and regional execution capabilities both matter, and where competitive success depends on aligning product strategy with local market realities.
Recent developments underscore how quickly the competitive dynamics can shift. New product introductions targeting iron-rich feedstocks and high-octane gasoline production illustrate the pace of innovation and the willingness of established players to invest in differentiated solutions. These launches are not incremental; they respond directly to operational pain points and regulatory pressures that are reshaping refinery priorities. In this environment, incumbents that can translate technical capability into measurable unit-level benefits are well positioned, while slower-moving competitors risk erosion in segments where performance and reliability are becoming increasingly decisive.
Market Evolution: Consolidation Pressures and Emerging Entrants
The market's concentration profile suggests continued pressure toward consolidation among smaller or less differentiated players, particularly in segments where feedstock flexibility, environmental compliance, and lifecycle cost management are becoming table stakes. Suppliers that cannot articulate a clear technical or economic advantage may find it harder to compete for specification-driven contracts, especially as refiners become more sophisticated in evaluating total cost of ownership and performance risk.
Continuous Catalyst Regeneration (CCR) Catalyst Market
At the same time, there are pathways for differentiation that do not require blanket market leadership. Niche expertise in specific catalyst functions, regional service excellence, or innovative approaches to spent catalyst management can create defensible positions. New entrants and smaller specialists may find opportunity by targeting particular pain points, such as contaminant mitigation, additive optimization, or sustainability-linked lifecycle services, rather than attempting to compete head-to-head across the full product spectrum. The overall trend is toward a more segmented competitive environment in which broad scale and deep specialization coexist, and where partnerships, technical service, and integrated offerings increasingly determine market outcomes.
Near-Term Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to define the FCC catalyst market's trajectory. First, catalyst formulations that can reliably handle heavier, more contaminated feeds while maintaining activity and selectivity will become increasingly central to procurement decisions. Iron poisoning mitigation, metal trapping efficiency, and robust performance across feed variations will move from specialized concerns to mainstream requirements as opportunity crude usage persists and refinery margin strategies continue to favor flexible feedstock handling.
Second, the link between catalyst selection and environmental compliance will tighten further. As product specifications and emissions expectations evolve, catalysts and additive packages that support sulfur reduction, cleaner product slates, and efficient conversion of heavy feeds will command greater attention. This trend favors suppliers who can demonstrate measurable compliance benefits and help refiners navigate an increasingly complex regulatory environment without sacrificing unit economics.
Third, lifecycle economics will gain prominence in catalyst decision-making. Disposal costs, recycling pathways, and the total cost of catalyst ownership will be evaluated more holistically, especially in regions where landfilling expenses are rising. Solutions that extend catalyst life, improve regeneration outcomes, or reduce waste volumes will have a stronger commercial case. This shift creates opportunities for suppliers and service providers who can integrate performance, sustainability, and cost management into a coherent value proposition.
These trends translate into tangible commercial opportunities. For catalyst manufacturers and technology licensors, there is room to grow by targeting refineries that are reconfiguring units for heavier feeds or facing specific contaminant challenges. Differentiated technologies that deliver clear operational improvements can support premium positioning and stronger customer retention. For investors, the market's steady growth profile and the centrality of catalysts to refinery economics suggest durable demand, but success will depend on identifying players with genuine technical differentiation and the ability to execute in a concentrated, relationship-driven market. For refiners and procurement teams, the opportunity lies in moving beyond unit price to evaluate total lifecycle value, contaminant handling, compliance support, and service capabilities when selecting catalyst partners.
Risks and uncertainties remain. Feedstock availability and quality can shift quickly, altering the relative attractiveness of different catalyst strategies. Regulatory timelines and enforcement intensity may vary by region, creating uneven demand signals. Economic cycles, refining margin compression, and capital expenditure constraints can delay unit upgrades or catalyst transitions. In addition, the concentration of the market means that supply disruptions or strategic moves by a small number of key players can have outsized effects on pricing and availability. Decision-makers need to monitor these variables closely and maintain flexibility in catalyst strategy and supplier relationships.
Strategic Recommendations for Decision-Makers
For manufacturers and technology suppliers, the priority is to align innovation with the operational realities that refiners face today. This means investing in catalyst capabilities that address iron poisoning, heavy feed conversion, and product quality targets, while also building the service and technical support infrastructure needed to prove value in real-world units. Suppliers should also consider how lifecycle economics, including disposal and recycling considerations, can be integrated into their offerings to strengthen customer partnerships and differentiate from commodity-focused competitors.
For investors and strategic financiers, the market offers a growth profile supported by regulatory pressure, feedstock complexity, and the ongoing need for refinery yield optimization. The key diligence question is differentiation: which companies have proprietary technologies, credible performance data, and the service capacity to capture value in a concentrated market? Investment theses should account for regional demand patterns, the pace of regulatory change, and the extent to which a player's portfolio is tied to specific feedstock or product trends that may evolve over time.
For refiners, procurement leaders, and operations teams, the strategic imperative is to treat catalyst selection as a unit-level economic decision rather than a routine procurement exercise. Evaluating candidates through the lens of total cost of ownership, contaminant handling, compliance support, and lifecycle services can reveal opportunities to reduce operating costs and improve unit reliability. Building vendor relationships that include technical collaboration, performance monitoring, and continuous optimization can help refineries adapt more quickly to feedstock shifts and regulatory changes.
The breadth of factors shaping the FCC catalyst market makes it difficult to navigate with generic assumptions or high-level market summaries alone. Feedstock strategies, regulatory trajectories, catalyst chemistry, and lifecycle economics all interact in ways that vary by refinery configuration, region, and operational priorities. Detailed segmentation data, unit-level cost modeling, and tailored scenario analysis can help decision-makers translate broad trends into specific actions, whether that involves choosing a catalyst platform, prioritizing investment in mitigation technology, or evaluating supplier partnerships. For organizations seeking to move from market awareness to concrete planning, deeper research and customized analysis can provide the granularity needed to align catalyst strategy with commercial objectives and operational risk tolerance.
For detailed analysis of this topic, please visit the official page: FCC Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com