

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Tetraethyl Orthosilicate Market 2026: Unpacking the 6.98% CAGR and Regional Shifts

The Tetraethyl Orthosilicate Market: Strategic Shifts and Commercial Opportunities Through 2032
The tetraethyl orthosilicate market has entered a phase of sustained expansion, driven by converging demands across advanced materials, semiconductor manufacturing, and specialty chemical applications. With a projected compound annual growth rate of 6.98 percent from 2026 through 2032, the sector is transitioning from a niche chemical feedstock into a strategically important enabler of high-value industrial processes. The market reached 215.0 million USD in 2025 and is expected to climb to 344.8 million USD by 2032, reflecting steady demand acceleration rather than speculative volatility. Understanding the structural forces behind this trajectory requires looking beyond headline figures and examining the technological, regulatory, and competitive dynamics that will shape purchasing decisions, investment priorities, and manufacturing strategies over the next several years.
Market Landscape and Structural Challenges
The tetraethyl orthosilicate market is characterized by moderate fragmentation and a clear emphasis on product differentiation. High purity grades command a dominant share of revenue, underscoring how end-use requirements in electronics, advanced coatings, and precision chemical synthesis have elevated specification standards across the value chain. The global market size has expanded consistently over the past five years, with 2024 revenue reaching 196.06 million USD before accelerating into 2025. This growth pattern reflects a market that is maturing in terms of application breadth while simultaneously tightening in terms of quality expectations.
Several structural challenges are reshaping how producers and buyers navigate this environment. First, regulatory stringency around organosilicon handling and emission control has increased operational complexity, reducing production flexibility and raising compliance costs across multiple regions. Second, raw material volatility, particularly in silicon-based feedstocks and ethanol derivatives, has introduced greater cost uncertainty into manufacturing planning. Third, the market’s growing dependence on high purity specifications has widened the performance gap between standard-grade suppliers and specialized producers, intensifying the need for technical capabilities that go beyond basic chemical synthesis. These pressures are not merely operational inconveniences; they are redefining competitive barriers and influencing where value is captured within the supply chain.
Key Drivers Shaping Market Evolution
Technological Innovation and Application Expansion
Advances in sol-gel processing, thin-film deposition, and specialty coating formulations continue to expand the functional role of tetraethyl orthosilicate. In semiconductor and electronic materials, the shift toward more precise silica film formation has elevated demand for ultra high purity grades suitable for chemical vapor deposition and related precision applications. At the same time, sol-gel-based coatings and spin-on glass technologies are finding broader use in surface engineering, optical treatments, and advanced ceramics, creating cross-industry demand that is less dependent on any single end market. This technological broadening is important because it allows producers with strong quality control and application support to serve multiple downstream segments without cannibalizing their own positioning.
For commercial strategists, the implication is clear: product value is increasingly tied to performance consistency and application readiness rather than volume alone. Companies that can provide documented purity profiles, controlled particle or hydrolysis behavior, and technical guidance for process integration are better positioned to retain pricing power and customer loyalty, especially in electronics and high-specification coatings.
Regulatory and Compliance Pressure as a Competitive Filter
Chemical safety directives and emission control requirements are reshaping production practices across the organosilicon sector. Stringent handling standards have reduced operational flexibility while increasing the cost burden associated with hazardous material compliance. Rather than acting as a uniform headwind, however, these regulations are functioning as a competitive filter. Larger, better-capitalized producers with established environmental management systems and standardized handling protocols are absorbing compliance costs more efficiently than smaller operators with limited regulatory infrastructure.
This dynamic is creating a bifurcation in the supply base. Buyers in semiconductor, pharmaceutical synthesis, and high-performance coatings are increasingly favoring suppliers that can demonstrate robust compliance records, consistent documentation, and controlled logistics for sensitive materials. The result is a market where regulatory readiness is becoming a commercial differentiator, not just an operational requirement.
Demand-Side Shifts in End-Use Industries
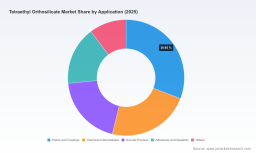
Demand behavior is changing on two fronts. In industrial and construction-related applications, tetraethyl orthosilicate continues to serve as a coupling agent and silane diluent in consolidation treatments, primers, and sealant systems. These uses benefit from steady infrastructure and maintenance activity, but they are also sensitive to broader construction cycles and input cost fluctuations. In higher-value segments, demand is being shaped by more specification-driven procurement, where buyers prioritize purity, lot consistency, and supplier technical support over lowest-cost sourcing.
3-aminopropyltriethoxysilane Market
This shift matters because it alters the purchasing calculus. In specification-intensive applications, total cost of ownership considerations, including process yield, defect reduction, and supply reliability, often outweigh initial price differences. Producers that can align their product portfolios with these purchasing priorities are gaining an advantage in customer retention and qualification cycles.
Feedstock Dynamics and Cost Structure Sensitivity
Production economics remain closely linked to the availability and pricing of silicon tetrachloride, ethanol, and related alcohol-based inputs. Fluctuations in these feedstock markets directly affect manufacturing expenses and can compress margins when price movements are not matched by timely adjustments in product pricing or formulation strategies. At the same time, the growing premium on high purity grades is pushing some producers to invest in more controlled synthesis and purification steps, which changes the cost structure in favor of operators with stronger process engineering capabilities.
For procurement and planning teams, this means that short-term price considerations should be balanced against supply resilience and specification reliability. In an environment where feedstock volatility can shift production economics quickly, long-term agreements and supplier qualification based on process control can reduce exposure more effectively than periodic spot purchasing.
Competitive Landscape and Strategic Positioning
The competitive environment is led by a mix of global specialty chemical companies and regional suppliers with focused product portfolios. Evonik Industries AG has built a recognizable position around its Dynasylan and SILBOND offerings, particularly for sol-gel processes, spin-on glass, and high-purity silica applications. Its strategy emphasizes application-specific grades and technical support that align with demanding coating and materials-processing use cases. Wacker Chemie AG competes with ultra high purity tetraethyl orthosilicate variants aimed at electronics and industrial silane applications, reinforcing a focus on precision grades and process reliability.
In the Asian market, Shin-Etsu Chemical Co. Ltd. provides both standard and high-purity grades serving sol-gel processes, coatings, and semiconductor materials, leveraging a broad materials portfolio and established customer relationships. Entegris, Inc. has carved out a specialized position with ultra-pure tetraethyl orthosilicate supplied in controlled containers for chemical vapor deposition of silicon dioxide films, targeting semiconductor manufacturing where contamination control is critical. SoulBrain Co., Ltd. focuses on electronic-grade material for semiconductor CVD and related precision applications, reflecting the growing importance of localized high-specification supply in advanced electronics.
PW Consulting Chemical & Energy Research Center
Dow Chemical Company maintains relevance through silane diluent and additive forms used in construction consolidation, zinc-rich primers, and coupling agent applications, demonstrating how broader chemical portfolio strength can support steady demand in industrial use cases. At the same time, regional suppliers such as Siwin Silicone Materials Co., Ltd. and TNJ Chemical Industry Co., Ltd. serve pharmaceutical synthesis, reagent-grade, and general industrial applications with standardized purity offerings. These companies illustrate how smaller-scale or regional players can remain viable by serving price-sensitive, specification-modest, or locally concentrated demand segments.
How Leaders Differentiate
Across the market, differentiation is increasingly defined by three factors: purity control, application support, and supply-chain reliability. Leading producers invest in controlled manufacturing environments, consistent documentation, and technical service that helps downstream customers integrate the material into sensitive processes. This is especially important in electronics and high-performance coatings, where specification compliance and lot-to-lot consistency can determine whether a supplier is qualified for recurring use.
Another differentiating theme is portfolio alignment with end-use risk profiles. Companies that serve semiconductor and pharmaceutical-adjacent applications tend to emphasize containment, purity certification, and controlled logistics, while those focused on industrial coatings, adhesives, and construction-related uses prioritize cost efficiency, availability, and broad compositional reliability. The most strategically resilient players are those that can manage both ends of this spectrum without diluting their core positioning.
Market Evolution and Entry Dynamics
The market is likely to continue evolving through incremental consolidation among high-specification suppliers and parallel specialization among regional producers. High purity segments will probably attract continued investment because they offer better margin stability and stronger customer lock-in in electronics and advanced materials. At the same time, standard-grade supply may see more price competition, particularly where regional demand is served by multiple capable manufacturers.
New entry remains possible, but the barriers are shifting. Low-cost production alone is no longer enough for customers in specification-intensive applications. Prospective entrants need credible quality systems, application expertise, and the ability to meet compliance expectations without disrupting delivery reliability. As a result, successful expansion is more likely to come from producers that already have materials-science capabilities, established regulatory frameworks, or existing relationships in target end markets.
Forward-Looking Trends and Commercial Implications
Trend One: High Purity Demand Will Anchor Growth
Over the next three to five years, high purity tetraethyl orthosilicate is expected to remain the primary growth anchor, especially as semiconductor-related processes, advanced coatings, and precision chemical synthesis continue to demand tighter control over contaminating species and consistent hydrolysis behavior. This trend creates commercial opportunities for suppliers that can systematically deliver certified purity, controlled packaging, and documentation that supports customer qualification cycles. It also favors businesses that can invest in purification, analytical verification, and contamination-aware logistics.
The strategic upside is not limited to large-scale producers. Specialized suppliers with focused product lines, strong technical service, and reliable quality can capture meaningful share in high-value niches even if their overall volume is smaller than that of broad-line chemical companies.
Trend Two: Compliance Costs Will Reshape Sourcing Strategies
Regulatory pressure is likely to remain a defining feature of the market. As handling and emission control requirements become more embedded in procurement decisions, buyers will increasingly weigh supplier compliance maturity when evaluating risk. This trend benefits organized producers with established environmental and safety infrastructure and creates a longer qualification runway for smaller or less documented suppliers.
For commercial teams, the opportunity lies in turning compliance into a sourcing advantage. Suppliers that proactively provide compliance documentation, standardized handling guidance, and predictable logistics can reduce the administrative and operational burden on buyers. In regulated or specification-sensitive environments, that value often translates into longer contracts and stronger supplier preference.
Trend Three: Regional Demand Mixes Will Diversify Value Creation
Asia Pacific continues to represent the largest regional revenue base, reflecting broad activity across electronics, industrial chemicals, and coatings-related applications. North America and Europe remain important for high-specification demand, particularly in semiconductor-adjacent and specialty materials use cases. Latin America and the Middle East and Africa, while smaller in absolute terms, offer incremental growth as industrial activity and materials upgrading expand in selected markets.
Worldwide Ethyl Silicate 40 Market
The commercial implication is that regional strategies should be tailored to local application mixes rather than assuming uniform demand behavior. In markets where electronics and advanced materials dominate, purity, documentation, and technical support will likely drive purchasing decisions. In more industrial or construction-linked markets, availability, price stability, and broad compositional reliability may matter more. Suppliers that align their offerings with these regional priorities are better positioned to convert demand into sustainable share.
Risks and Uncertainties to Watch
Several uncertainties could alter the pace or shape of market development. Feedstock price volatility remains a persistent risk, particularly if silicon-based inputs or alcohol derivatives move sharply due to supply constraints or regional demand changes. Regulatory evolution could also accelerate compliance costs faster than producers can adjust, especially in regions where chemical safety enforcement becomes more stringent. In addition, demand concentration in high-purity electronics applications could increase exposure to semiconductor cycle variability, while broader industrial demand may be more sensitive to construction and infrastructure fluctuations.
These risks do not negate the market’s growth trajectory, but they underscore the importance of flexible sourcing strategies, diversified application exposure, and supplier qualification based on reliability rather than price alone. Companies that treat these uncertainties as planning variables rather than external shocks will be better equipped to maintain margin stability and supply continuity.
Strategic Recommendations for Decision Makers
For Manufacturers and Producers
- Prioritize purity control and documentation as core commercial assets, especially if targeting electronics, advanced coatings, or other specification-intensive applications.
- Evaluate cost-structure resilience against feedstock volatility by examining long-term input agreements, process efficiency improvements, and product-mix balance between premium and standard grades.
- Strengthen application support capabilities so that technical service becomes part of the value proposition rather than a back-office function.
For Investors
- Focus on companies with demonstrated ability to serve high purity demand and maintain compliance readiness, since these attributes are increasingly tied to margin stability and customer retention.
- Assess exposure to feedstock sensitivity and regional demand concentration, balancing growth potential against cycle volatility in electronics and construction-linked end markets.
- Look for businesses that combine product differentiation with scalable quality systems, as these are more likely to sustain competitive advantage as regulatory and specification demands rise.
For Procurement and Supply Chain Leaders
- Align sourcing criteria with total cost of ownership, including specification consistency, documentation quality, and logistics reliability, rather than relying solely on unit price comparisons.
- Diversify qualified suppliers across high-purity and standard-grade categories to reduce exposure to feedstock-driven price swings and compliance-related supply interruptions.
- Use supplier qualification to capture forward-looking information on production flexibility, regulatory preparedness, and application support, which can improve downstream process stability.
The tetraethyl orthosilicate market is moving toward a more specification-driven, compliance-aware, and application-diversified future. For organizations operating in or adjacent to this space, the most valuable insight is that competitive advantage will increasingly come from reliability, technical alignment, and supply-chain maturity rather than volume expansion alone. For decision makers who need deeper segmentation, regional nuance, and tailored scenario planning, the full research report offers a more granular view of demand patterns, competitive moves, and procurement implications across the forecast period.
For detailed analysis of this topic, please visit the official page: Tetraethyl Orthosilicate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com