

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
The Real Drivers Behind the Epoxy Resin Active Toughening Agent Market 6.4% CAGR Link Up to 2032

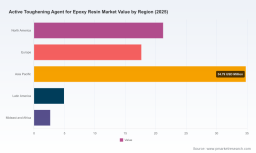
Active Toughening Agents for Epoxy Resins: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Critical Inflection Points
The global market for active toughening agents designed for epoxy resin systems has entered a phase of deliberate, structurally driven growth. Valued at 81.25 million USD in 2025, the market has expanded from 60.0 million USD in 2020, reflecting a compound annual growth rate of approximately 6.4 percent across the 2026 to 2032 forecast horizon. This trajectory is not defined by cyclical commodity swings, but by a steady recalibration of how epoxy formulations balance rigidity, thermal stability, and fracture resistance across demanding industrial and high-performance applications. As design engineers push composite laminates, structural adhesives, protective coatings, and electronic encapsulants into more severe service environments, the traditional compromise between mechanical toughness and baseline performance is being systematically redefined by chemistry, processing economics, and end-use requirements.
The market’s evolution carries a clear concentration profile. The top three participants capture roughly 55 percent of global revenue, while the leading five firms account for nearly 68 percent. This distribution signals a mature competitive arena where scale, intellectual property depth, and formulation expertise create meaningful barriers to entry. At the same time, it leaves sufficient fragmentation for specialized regional players and application-focused innovators to carve out defensible positions. Rather than a winner-take-all contest, the landscape favors organizations that can translate material science into consistent processing windows, application-specific performance, and supply reliability.
The Core Tensions Reshaping the Sector
Three interconnected challenges are redefining how manufacturers, formulators, and end-users approach epoxy toughening. The first is the persistent performance-efficiency paradox. Historically, introducing rubber or thermoplastic reinforcement into epoxy networks has improved impact resistance and crack tolerance, but often at the expense of viscosity control, glass transition temperature, or thermal stability. Bridging that gap increasingly demands nanoscale dispersion control, reactive compatibility strategies, and self-assembling architectures that deliver toughness without degrading the host matrix’s baseline characteristics.
The second tension stems from regulatory and sustainability acceleration. Industrial flooring, protective coatings, construction applications, and marine asset maintenance are moving toward formulations that reduce volatile organic compound exposure, lower lifecycle carbon intensity, and improve compatibility with circular-economy expectations. In parallel, downstream industries are asking for more transparent sourcing, lower toxicity footprints, and formulations that simplify end-of-life handling or enable higher recycled-content integration. Meeting these requirements without sacrificing mechanical reliability or shelf stability forces formulation teams to re-evaluate incumbent chemistries and evaluate bio-based, low-emission, or hybrid toughening strategies.
The third inflection point is the shifting center of gravity in demand intensity. Growth is no longer distributed evenly across legacy applications. Semiconductor packaging, battery enclosures, lightweight structural assemblies, and high-durability offshore and marine systems are placing disproportionate emphasis on materials that can withstand thermal cycling, vibration, moisture exposure, and mechanical fatigue while supporting weight reduction and extended maintenance intervals. This demand migration changes the economics of product design, because performance tolerances tighten and qualification cycles lengthen, which in turn raises the value of specialized toughening solutions relative to broad-line commodity additives.
For business leaders, these tensions translate into a straightforward but demanding strategic question: whether to compete on cost-and-volume scale, on differentiated performance architecture, or on application-specific formulation partnerships. The answer increasingly depends on how well an organization can anticipate end-use qualification requirements and manage the trade-offs between toughness, processability, and regulatory alignment.
Key Drivers of Market Change
Material Innovation and the Rise of Precision Toughening
The most consequential driver of market momentum is the shift from blunt toughening tactics to precision-engineered reinforcement architectures. Traditional rubber-modified and thermoplastic toughening approaches remain relevant, but they are increasingly complemented by pre-dispersed concentrates, nano-scale core-shell particles, reactive block copolymers, and hyper-branched structures that integrate more cleanly into epoxy networks. These architectures can improve fracture toughness, fatigue resistance, and damage tolerance while preserving heat resistance, rigidity, and thermal properties that high-performance applications require. In structural adhesives, composites, and electronics, that balance is not a luxury feature; it is often the difference between a viable solution and one that fails qualification testing under thermal shock, impact, or long-term load.
One practical indicator of this shift is the commercial emphasis on pre-dispersed concentrate systems that simplify handling and dispersion for epoxy formulators. Nano-sized core-shell rubber particles incorporated into liquid media, for example, reduce particle agglomeration risk and lower the burden on downstream processing, while offering enhancements in impact strength, adhesive performance, and heat shock resistance. Such systems illustrate why the toughening conversation is moving away from generic additive categories and toward engineered intermediates that solve real process and performance pain points. For epoxy processors, this means faster reformulation support, better repeatability, and a cleaner translation from lab-scale performance to production-scale reliability.
Regulatory and Sustainability Pressure as a Catalyst, Not Just a Constraint
Policy and regulatory dynamics are accelerating change rather than merely restricting it. In European construction and industrial coating contexts, tighter sustainability expectations are pushing formulators toward low-VOC and bio-based formulations that meet both performance and environmental criteria. Far from being a compliance tax, this evolution is spawning a new class of requirement-led innovation: bio-based toughening agents, low-emission epoxy systems, and formulations designed for industrial flooring and protective coatings that must satisfy durability standards while reducing environmental burden.
The commercial implication is that sustainability is becoming a design input at the start of product development rather than a retrofit target. Companies that can supply toughening agents and epoxy-compatible chemistries with credible sustainability attributes may gain access to higher-value programs where procurement teams must justify material choices across lifecycle, regulatory, and reputational dimensions. Conversely, formulations that lag on VOC profile, bio-based content, or transparency of supply may face growing friction in markets where specification approvals are subject to stricter evaluation.
Demand-Side Transformation in High-Performance End-Use Sectors
On the demand side, the most meaningful shift is the increasing need for epoxy systems that survive more demanding service conditions while supporting lighter, more efficient designs. In semiconductor and battery packaging contexts, lightweight composite requirements and tighter tolerance bands are driving higher interest in tailored toughening solutions that protect sensitive assemblies from stress, thermal mismatch, and cyclic loading. Similarly, in offshore and marine asset maintenance, epoxy coatings are being specified not only for protection but for extended maintenance intervals, which raises the premium on mechanical durability and chemical resistance under prolonged exposure.
These demand signals matter because they change the basis of competition. Applications that tolerate marginal performance can absorb cost-led substitution; applications where failure carries high operational, safety, or capital consequences do not. As a result, toughening agents are increasingly evaluated through the lens of end-use reliability, qualification support, and compatibility with specific processing routes. Formulators and end-users alike are pushing for materials that reduce risk in the field, which gives a structural advantage to suppliers that can document performance under realistic conditions rather than rely solely on generic benchmark data.
Supply Chain, Cost Structure, and Formulation Economics
The cost and supply side adds another layer of complexity. Toughening agents are rarely purchased as isolated commodities; they are integrated into broader formulation strategies where dispersion quality, shelf stability, viscosity control, and batch consistency influence total cost of ownership. When regulatory shifts, feedstock transitions, or regional sourcing constraints alter input economics, the impact is magnified because downstream processors must balance performance targets with manufacturability and cost predictability. At the same time, the move toward pre-dispersed and pre-engineered systems can reduce formulation complexity in production, potentially lowering labor, dispersion equipment burden, and process variability even if the per-unit material cost is higher.
Epoxy Active Diluent Market
This dynamic favors companies that can offer not just chemistry, but process-aligned solutions. For epoxy processors, the value proposition increasingly includes dispersibility, compatibility with target resin systems, and the ability to maintain performance without unacceptable trade-offs in modulus or glass transition behavior. In practical terms, that means supplier selection is becoming less about price-per-kilogram alone and more about whether the toughening agent helps the end formulation meet target properties within a stable, scalable process window.
Competitive Landscape and Leading Strategies
Differentiation Through Formulation Architecture and Application Focus
The market’s competitive frontier is defined less by sheer volume and more by how companies translate material science into application-specific advantage. Global specialty chemical players tend to emphasize high-performance architectures, proprietary toughening chemistries, and integration with advanced composite or adhesive systems. Their strategic positioning often centers on solving demanding end-use problems where toughness must coexist with elevated thermal performance, damage tolerance, or very tight mechanical specifications. For example, self-assembling block copolymer-based toughening systems and thermoplastic polyester sulfone micropowders are being positioned where epoxy composites and prepregs need improved toughness and damage resistance without sacrificing key structural properties.
These approaches create differentiation through performance architecture rather than price alone. When a toughening solution can demonstrably improve damage tolerance or toughness while maintaining modulus and glass transition behavior, it becomes easier to defend in specifications that are sensitive to both mechanical reliability and thermal stability. That is especially relevant in automotive structural adhesives, CFRP-related aerospace applications, and other settings where heat resistance, rigidity, and impact tolerance must all remain within acceptable bounds.
PW Consulting Chemical & Energy Research Center
Regional Strengths, Specialization, and Scale
Alongside global specialists, a broad set of regional and application-focused manufacturers contributes meaningful scale and breadth across rubber, thermoplastic, core-shell latex, hyper-branched, and reactive toughening variants. These players often compete by covering multiple application domains, maintaining responsive production and customization capabilities, and aligning product portfolios to coatings, adhesives, composites, and certain electronics uses. Their advantage frequently lies in breadth, localization, and the ability to serve customers who need a practical range of toughening options rather than a single high-end architecture.
Worldwide Epoxy Resin Curing Agents Market
The strategic relevance of this fragmentation should not be underestimated. In many industrial and regional markets, buyers prioritize availability, formulation flexibility, and cost-sensitive performance tuning over the most advanced but narrowly focused specialty option. That creates durable roles for suppliers that can balance product range with consistent quality and practical technical support. At the same time, the most specialized applications reward deep technical differentiation, which means competitive advantage is increasingly bifurcated: breadth for broad industrial demand, and performance depth for mission-critical applications.
Market Evolution: Consolidation Pressure and Entry Opportunities
Looking ahead, the competitive structure is likely to evolve through a mix of consolidation pressure and selective entry opportunities. The concentrated top tier suggests that scale, IP portfolios, and integrated application development provide meaningful defensive moats. Yet the fragmentation below the top tier indicates room for companies that can build defensible niches through application expertise, regional supply strength, or differentiated toughening chemistry.
Entry and expansion opportunities are particularly likely in areas where performance requirements are rising faster than incumbent portfolios can adapt cleanly: bio-based and low-emission toughening, pre-dispersed concentrate systems for easier processing, and specialized solutions for electronics and composite packaging where lightweighting and reliability converge. At the same time, consolidation pressures may intensify among mid-tier players seeking to expand application coverage, improve scale economics, or acquire technical capabilities that strengthen their position with specification-driven buyers. The market is thus moving toward a structure where the winners are those who can combine credible performance claims with process-compatible delivery and clear application alignment.
Forward Outlook: Three Strategic Trends to 2032
Trend One: Toughening as an Engineered System, Not a Commodity Additive
Over the next three to five years, active toughening agents are likely to be treated more like engineered formulation systems than generic performance additives. That means greater emphasis on dispersion control, reactive compatibility, rheology management, and the ability to preserve modulus and thermal properties while improving toughness and damage resistance. Buyers will increasingly evaluate toughening agents on the basis of total formulation impact rather than isolated mechanical metrics. The commercial opportunity lies in solutions that reduce reformulation friction, improve repeatability, and help epoxy systems meet demanding targets without requiring extensive process re-engineering.
Trend Two: Sustainability-Linked Performance Becomes a Specification Requirement
Sustainability-driven formulation requirements are expected to become more embedded in procurement and specification processes, especially in coatings, industrial flooring, protective systems, and construction-adjacent applications. Low-VOC profiles, bio-based content, and lifecycle considerations will increasingly influence which toughening chemistries are eligible for consideration. This trend does not simply reward “greener” products; it rewards products that can demonstrate credible performance under the same demanding conditions as conventional alternatives. The opportunity is for suppliers and formulators who can pair sustainability attributes with robust mechanical and durability performance, turning environmental compliance into a competitive entry point rather than a constraint.
Trend Three: High-Reliability Applications Drive Higher-Value Demand
A third trend is the continued rise of high-reliability applications where failure is expensive and specifications are tight. Semiconductor and battery packaging, lightweight structural assemblies, and durable marine or offshore coatings are expected to place disproportionate emphasis on toughness, thermal cycling resistance, and extended service life. In these settings, the value of a toughening agent is tied to its ability to reduce risk and support qualification, not merely to improve a single performance parameter. The commercial opportunity lies in capturing demand from applications that are willing to pay for reliability, consistency, and technical support, while managing the risk that qualification timelines and technical barriers can slow adoption.
These trends together suggest a market that is growing at a measured but meaningful pace, with the strongest value creation concentrated where performance, process compatibility, and sustainability converge. The upside is real, but so is the risk that over-indexing on any single dimension—cost, performance, or sustainability—without the others can limit commercial viability in specification-driven environments.
Strategic Actions for Decision-Makers
For Epoxy Manufacturers and Formulators
Evaluate toughening agents as part of a total formulation strategy rather than as interchangeable additives. Prioritize solutions that align with your processing constraints, target viscosity and modulus profiles, and end-use qualification requirements. Where sustainability or low-emission performance is becoming a purchasing requirement, treat it as a design input early, and validate that any bio-based or low-VOC toughening approach can still meet mechanical and durability benchmarks in the intended application.
For Investors and Corporate Development Teams
Focus on the intersection of application-driven demand and differentiated chemistry. The most resilient opportunities are likely to be in specialized toughening architectures that address concrete performance problems in composites, structural adhesives, protective coatings, and high-reliability electronics or battery-related uses. Monitor consolidation dynamics among mid-tier players, and assess whether a target’s advantage comes from genuine technical differentiation, application relationships, or regional scale. Where demand is concentrated in high-specification applications, valuation logic should reflect qualification barriers and technical moats, not just volume growth.
For Procurement and Specification Teams
Build sourcing decisions around total cost of ownership, application reliability, and supplier capability to support qualification and formulation tuning. Request performance data that reflects the conditions under which the epoxy system will actually operate, including thermal cycling, impact, adhesion, and long-term durability where relevant. In markets where regulatory and sustainability expectations are tightening, verify that the selected toughening approach supports compliance without undermining field performance, because specification risk in demanding applications can far outweigh modest initial material savings.
For teams seeking a more granular view of segmentation, regional dynamics, competitive positioning, and forward scenarios across coatings, adhesives, composites, electronics, and high-performance industrial applications, a deeper dive into detailed market data and tailored strategic analysis can sharpen planning assumptions and reduce the risk of poorly aligned decisions. The broader opportunity in the active toughening agent space for epoxy resins is clear, but the details—where value concentrates, which applications justify premium performance, and how sustainability requirements will reshape specifications—will determine which companies capture it and which merely watch it pass.
For detailed analysis of this topic, please visit the official page: Active Toughening Agent for Epoxy Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com