

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Titanium Sponge Market 2026: Beyond the 5.25% CAGR to High Purity & Aerospace Drivers

Titanium Sponge Market: Strategic Shifts and Commercial Opportunities Through 2032
The titanium sponge market has entered a decisive phase. Between 2020 and 2025, the sector moved from a post-pandemic recovery trajectory to a period of sustained expansion, reaching an estimated 236.8 million USD in 2025. Over the following seven years, the market is projected to grow at a compound annual rate of 5.25 percent, crossing the 338 million USD threshold by 2032. These figures reflect more than steady demand. They point to a structural realignment in how titanium sponge is produced, traded, and deployed across aerospace, medical, and industrial applications. For executives and investors, the opportunity lies not in the headline growth alone, but in understanding where value is being created, where supply vulnerabilities are concentrated, and which strategic moves will separate winners from the rest of the pack.
Worldwide Ferro Titanium Market
The current landscape is defined by a tension between robust end-use demand and persistent structural constraints. Production remains concentrated, with the top three players controlling roughly 45.6 percent of the market and the top five capturing about 68.2 percent. That concentration provides stability in normal conditions, but it also means that disruptions at a single facility or in a single trade corridor can ripple quickly through global procurement channels. At the same time, the market is navigating a pivotal transition: traditional sponge-dependent supply chains are being questioned by new domestic production initiatives, while trade policy is reshaping cost structures and routing decisions. The result is a market that is growing, but growing unevenly, with the most attractive opportunities concentrated in segments that can secure reliable feedstock, navigate regulatory shifts, and align with high-value downstream applications.
Several challenges stand out as defining issues for the next cycle. First, import dependency remains a strategic exposure for key consuming markets. The United States, for example, relies almost entirely on imports for titanium sponge, and import volumes reached a historical high in 2025. That level of reliance creates pricing sensitivity and supply continuity risk, particularly when geopolitical tensions or logistical bottlenecks intersect with concentrated sourcing patterns. Second, the industry is facing a policy-driven inflection point. Tariff adjustments and defense-oriented funding initiatives are altering the economics of domestic versus imported feedstock, forcing producers and buyers to reconsider long-standing procurement assumptions. Third, the market must balance quality and cost pressures. High-purity grades continue to command strong demand in aerospace, defense, and specialized industrial applications, while commercial-grade volumes must compete on scale and efficiency. Companies that cannot manage this dual dynamic risk margin compression or customer migration.
Key Drivers Reshaping the Market
The growth trajectory is being pulled forward by a cluster of interrelated forces. None of these drivers act in isolation; each reinforces or constrains the others, which is why strategic planning must look across technology, policy, demand behavior, and supply chain economics simultaneously.
Technology Innovation and Process Breakthroughs
One of the most consequential developments is the push to bypass or reduce reliance on traditional sponge production. New domestic initiatives are targeting a mineral-to-metal pathway that could change the cost and sourcing architecture of titanium supply. In early 2025, a U.S.-based innovator received an award of up to 47.1 million USD from the Department of Defense to accelerate an integrated domestic mineral-to-metal titanium supply chain. A subsequent 12.5 million USD in additional government funding followed later in the year to expand production operations. These moves matter because they signal a shift from incremental efficiency gains to a more fundamental rethinking of how titanium reaches end users. If successful, such approaches could reduce exposure to imported sponge, shorten lead times for critical applications, and create new competitive dynamics for established producers. The strategic implication is clear: process innovation is no longer a back-office concern. It is becoming a source of competitive advantage and a potential differentiator in procurement decisions, especially where supply security and performance specifications intersect.
Policy and Regulatory Environment
Trade policy is reshaping the market with real financial consequences. Unwrought titanium metal now faces a 15 percent ad valorem tariff under normal trade relations, a change that directly affects landed cost and sourcing calculus. At the same time, broader industrial and defense policy is encouraging domestic capacity and supply chain resilience. The combination creates a more complex decision environment for buyers and producers alike. Companies that previously optimized purely for price must now weigh tariff exposure, shipping routing, and the reliability of alternative sources. Producers outside the United States must factor in how tariff structures influence demand elasticity and whether they can maintain share through quality, service, or localized partnerships. For market participants, the regulatory shift is not a one-time adjustment; it is a persistent variable that will shape contract structures, inventory strategies, and investment timing.
Demand-Side Evolution
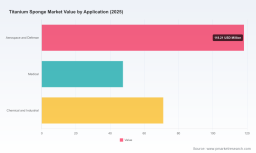
Demand is being driven by applications where titanium's performance characteristics are difficult to substitute. Aerospace and defense remain the dominant demand centers, reflecting the material's strength-to-weight ratio, corrosion resistance, and proven track record in critical systems. Medical applications continue to expand as implant and device manufacturers seek biocompatible materials with long-term reliability. Industrial and chemical processing applications add a further layer of demand stability, particularly where equipment longevity and resistance to harsh environments justify the material cost. Importantly, demand is not simply rising in aggregate. It is becoming more selective. Buyers in high-stakes segments increasingly prioritize supply assurance, traceability, and consistent quality over marginal price differences. That shift rewards producers with strong process control and dependable delivery records, while exposing those that compete mainly on volume without differentiated quality or service.
Supply Chain and Cost Structure Dynamics
Cost structures are being recalibrated by a mix of tariff effects, logistics exposure, and feedstock concentration. Recent trade flow data underscores how concentrated sourcing patterns can become: in the first quarter of 2025, U.S. titanium sponge imports were estimated at roughly 10,500 metric tons, with a significant share coming from Japan, and smaller portions from Kazakhstan and Saudi Arabia. Full-year import volumes reached a historical high in 2025. These patterns illustrate both the scale of reliance and the geographic concentration that underlies it. For buyers, the practical consequence is that cost planning must account for more than unit price. It must include freight variability, tariff assumptions, supplier diversification options, and the potential for policy changes to alter the relative attractiveness of different source countries. For producers, the implication is that competitive positioning increasingly depends on reliability, transparency, and the ability to help customers manage supply risk, not just on production cost alone.
Competitive Landscape and Leading Strategies
The market's competitive structure is shaped by a mix of integrated incumbents, specialized high-purity producers, and newer entrants pursuing alternative supply chain models. The incumbents bring scale, established customer relationships, and deep process expertise. The specialists differentiate through purity, consistency, and application-specific expertise. The emerging challengers are attempting to redefine the pathway from raw material to finished metal, often with a focus on domestic production and reduced dependence on conventional sponge routes.
In the United States, TIMET stands out as a fully integrated producer with a long-standing facility and a direct connection to aerospace and defense demand through internal melt operations and mill products. Its strategic positioning rests on integration and proximity to end-use customers, which supports quality control and supply continuity. IperionX represents a different strategic play. Rather than competing along the same sponge-centric axis, it is developing a mineral-to-metal supply chain aimed at domestic production for defense and advanced manufacturing. This approach is designed to address import reliance directly and align with government priorities around supply security. The recent defense award and additional funding underscore how policy alignment can accelerate capital deployment and market entry for players with a complementary technological and strategic profile.
In Russia, VSMPO-AVISMA Corporation operates as a major producer of titanium sponge and ingot for aerospace, space, and shipbuilding, and is recognized as a global leader in high-volume titanium metal supply. Its scale and breadth of product offerings make it a significant force in global supply, particularly where large-volume commitments and established aerospace relationships matter. In Japan, Toho Titanium and Osaka Titanium Technologies both occupy important positions. Toho Titanium focuses on specialized titanium sponge and high-purity titanium for semiconductors and aerospace, emphasizing stable, high-quality metals. Osaka Titanium Technologies is among the world's largest producers of titanium sponge and ingot, supplying aerospace with diversified high-performance materials. Together, these Japanese producers illustrate how quality, specialization, and scale can coexist in a market where high-purity grades and reliable delivery are valued by demanding downstream sectors.
Titanium Powder Market
In China, Baoji Titanium Industry and Zunyi Titanium add further depth to the global landscape. Baoji Titanium is a state-controlled manufacturer of titanium sponge and mill products serving aerospace, military, and industrial use, reflecting the strategic importance of titanium within domestic industrial policy and defense-related supply chains. Zunyi Titanium specializes in high-purity titanium sponge and associated materials for aerospace, industrial, and chemical processing applications. These players highlight how regional industrial strategies and application-specific focus can reinforce market presence, particularly when aligned with local demand growth and government-supported capacity development.
The competitive landscape is evolving along three axes. Consolidation remains relevant where scale, integration, and customer lock-in create durable advantages. Differentiation is becoming more important in high-value segments, where purity, traceability, and reliability can command preference even when pricing is not the lowest. And new entry is taking a distinct form: rather than simply adding another conventional sponge plant, some players are pursuing alternative production pathways and aligning with policy incentives to address supply security concerns. For companies evaluating the landscape, the most useful question is not who is largest, but which strategic logic is most resilient under shifting tariff, sourcing, and demand conditions.
Forward Outlook: Trends to Watch Through the Mid-2020s
Looking ahead three to five years, several trends are likely to shape both opportunity and risk. These trends are not speculative overlays; they follow directly from current demand patterns, policy signals, and supply chain dynamics.
Reshoring and Supply Security as Strategic Priorities
Supply security is moving from a compliance concern to a core competitive variable. The combination of high import reliance, tariff adjustments, and defense-oriented funding creates a clear incentive for domestic or near-domestic capacity where feasible. The practical outcome is likely to be a gradual shift in sourcing strategies, with more buyers pursuing diversified supply bases, longer-term agreements, and closer coordination with producers who can offer transparency and resilience. For producers, this trend opens the door to partnerships and contracts that reward reliability and strategic alignment, not just price. For investors, it suggests that assets and technologies aligned with supply security objectives may command greater attention and support, provided they can demonstrate credible cost and scale trajectories.
Premiumization in High-Value Applications
Demand in aerospace, defense, and medical applications is likely to continue favoring high-purity and performance-grade material. As end uses become more exacting and as qualification cycles remain long, buyers will increasingly value consistency, documentation, and process control. This trend favors producers that can deliver reproducible quality and support customer requirements across qualification, production, and delivery. It also creates a two-tier dynamic in which commercial-grade volumes must compete on efficiency and cost while premium grades capture stronger positioning. Companies that can manage both tiers effectively, or that deliberately focus on the higher-value tier with clear differentiation, are better placed to protect margins in a market where tariff and logistics costs can otherwise erode profitability.
PW Consulting Chemical & Energy Research Center
Policy-Linked Investment and the Risk of Overcorrectment
Government funding and policy alignment are accelerating investment in new capacity and alternative processes. That is a positive signal for supply diversification, but it also introduces uncertainty. The pace of commercialization, the realism of cost expectations, and the durability of policy support all matter. If alternative pathways underdeliver on scale or cost, the market may revert toward established suppliers faster than some forecasts imply. If policy support shifts with budget priorities or geopolitical developments, investment timing and capacity planning may need to be recalibrated. The strategic lesson is to treat policy-driven momentum as an enabler, not a guarantee. Opportunities should be evaluated against operational realism, including feedstock availability, processing readiness, qualification requirements, and the ability to serve demanding customers at scale.
Implications and Action Options for Decision-Makers
For manufacturers, the priority is to strengthen supply resilience without surrendering cost discipline. That means revisiting sourcing concentration, evaluating alternative suppliers and routes, and understanding how tariff and logistics assumptions affect total landed cost. It also means aligning internal quality and qualification capabilities with the increasing selectivity of high-value customers. Manufacturers that can offer dependable delivery, clear documentation, and consistent quality will be better positioned to retain demand in aerospace, defense, and medical segments, where switching costs and performance requirements limit casual re-sourcing.
For investors, the most interesting question is where value will accrue as the market rebalances. Scale incumbents with integration and established customer relationships still offer stability, but the most dynamic upside may come from companies that can credibly reduce supply risk, improve process economics, or capture premium positioning in high-purity applications. Investment theses should account for policy exposure, commercialization risk, and the degree to which a company's strategy depends on continued favorable conditions versus structural advantages that persist across scenarios. Diversification across traditional and emerging supply models can help balance stability with optionality.
For procurement and supply chain leaders, the practical mandate is to move beyond unit-price benchmarking. Total cost of ownership should incorporate tariff scenarios, freight exposure, lead-time variability, and the reliability of alternative sources. Developing a diversified supplier base, building buffer strategies for critical programs, and engaging earlier with producers on qualification and capacity planning can reduce vulnerability to shocks. In markets where import reliance is high and trade policy is active, procurement decisions increasingly have strategic as well as operational consequences.
The titanium sponge market is not simply expanding; it is being restructured around supply security, policy alignment, quality differentiation, and process innovation. That creates a wider set of strategic choices than in prior cycles. Companies that understand the interplay of these forces can position themselves to capture growth where it is most durable, while managing exposure where concentration and policy uncertainty create risk. For those seeking a more granular view of segment splits, regional dynamics, competitive benchmarks, and scenario-based guidance, deeper market research can provide the detailed data and tailored recommendations needed to refine strategy and execution plans.
For detailed analysis of this topic, please visit the official page: Titanium Sponge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com