

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Polyimide Tubing Market: Why 8.1% CAGR and Medical Demand Redefine Growth By 2032

Navigating the Polyimide Tubing Market: Strategic Trends and Commercial Opportunities
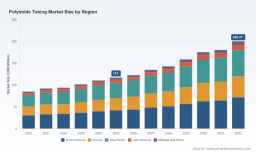
The polyimide tubing market has entered a phase of sustained expansion, driven by an increasingly demanding set of performance requirements across high-stakes industries. From 2020 through 2025, the market moved from a relatively modest base into a consistent double-digit growth trajectory, with the most recent annual figures signaling that demand is no longer cyclical but structurally reinforced. Looking ahead to the end of the decade, the expansion is expected to accelerate further, with a compound annual growth rate that places polyimide tubing among the more compelling specialty materials segments in advanced manufacturing and life sciences. The revenue scale now sits well into the triple-digit range, and the forward projection suggests the market will more than double its current size within the coming forecast window.
This trajectory is not merely a function of volume growth. It reflects a deeper shift in how engineers and procurement leaders think about tubing materials. Polyimide has transitioned from a niche solution for extreme thermal or chemical environments into a default consideration for applications where reliability, miniaturization, and regulatory compliance intersect. That shift has rewritten the competitive rules, forcing suppliers to compete on more than price or basic availability. The market is now rewarding precision, material innovation, and the ability to navigate an increasingly complex compliance landscape.
Market Current State and Core Challenges
The current market environment is defined by strong demand momentum, but that momentum is colliding with operational and structural constraints that will shape who wins in the next cycle. The first challenge is the widening gap between specification requirements and manufacturing capability. As applications move toward smaller diameters, tighter tolerances, and more complex reinforcement architectures, the bar for process control has risen sharply. Not every producer can consistently deliver the wall uniformity, surface finish, and mechanical predictability that advanced medical, electronics, and aerospace programs now demand. This has effectively raised the barrier to entry and concentrated value creation among suppliers with mature process engineering and robust quality systems.
A second challenge lies in cost volatility and input pressure. Polyimide is a performance material, and its production economics are sensitive to precursor availability, energy costs, and processing intensity. Recent producer price trends have shown upward pressure on input costs, which can compress margins for suppliers that lack pricing power or differentiated value propositions. In a market where many end-users are accustomed to treating tubing as a commoditized component, the ability to justify premium pricing increasingly depends on proving measurable performance gains rather than simply pointing to material grade.
The third challenge is regulatory and documentation intensity. As polyimide tubing penetrates more regulated end-use sectors, compliance has become a commercial prerequisite rather than a back-office function. Suppliers must demonstrate material traceability, biocompatibility support where relevant, and alignment with evolving regional requirements. This is especially true in European markets and in medical-adjacent applications, where the cost of noncompliance can be far greater than the cost of qualifying new materials. Companies that treat compliance as a strategic capability rather than a checkbox are gaining a structural advantage in customer evaluations.
Key Drivers Shaping Market Direction
Innovation in Material Performance and Processing Precision
Material innovation remains one of the most powerful demand catalysts. The latest wave of product development is not just about incremental refinement; it is about rethinking the performance envelope of polyimide tubing in ways that directly enable new applications. Recent announcements from leading suppliers point to formulations that significantly increase tensile and column strength compared with traditional grades, addressing long-standing tradeoffs between flexibility, pushability, and mechanical reliability. In parallel, tailored surface and lubrication variants are reducing friction and improving handling characteristics, which is especially valuable in interventional and micro-catheter applications where operator control and device navigation are critical.
These advances matter commercially because they expand the addressable use space. When tubing can withstand higher loads, maintain dimensional stability under stress, or offer more predictable lubricity, designers can adopt polyimide in configurations that were previously impractical. That creates a virtuous cycle: stronger performance justification supports broader specification, which increases volume, which in turn funds further process improvement. For suppliers, the strategic implication is clear. The winners will be those who connect material science improvements to measurable application outcomes rather than competing solely on catalog breadth.
Regulatory Alignment as a Commercial Accelerator
Regulatory and compliance dynamics have evolved from a constraint into a competitive differentiator. In the medical and certain industrial segments, buyers increasingly evaluate suppliers based on their ability to deliver materials aligned with REACH and EU MDR expectations, alongside robust documentation and traceability. This has shifted the procurement conversation. Technical compliance is now part of commercial credibility, and suppliers that can demonstrate a consistent compliance posture are often shortlisted more quickly than those that require extensive qualification support.
The market is also seeing a degree of positioning around this theme. Some suppliers have emphasized that their polyimide tubing portfolios are designed with these regulatory expectations in mind, signaling that compliance capability is being used as a trust signal in sensitive applications. Others have claimed distinctive compliance status within their product lines. Regardless of the specifics of any single claim, the broader pattern is that regulatory readiness is becoming a meaningful filter in customer selection, particularly for programs with long qualification cycles and high switching costs. For manufacturers, this means that compliance infrastructure, documentation practices, and material transparency are now part of the core commercialization strategy.
Demand-Side Shifts Toward Miniaturization and High-Reliability Systems
On the demand side, the most persistent driver is the continuing push toward smaller, more precise, and more reliable systems. In medical device development, the trend toward minimally invasive and endovascular procedures has increased the need for tubing that can navigate complex anatomy while maintaining delivery precision. In electronics and advanced assembly contexts, miniaturization and heat management requirements have elevated the value of materials that combine dimensional stability with thermal resilience. Aerospace and automotive applications, meanwhile, continue to prioritize weight reduction and durability in high-stress subsystems.
Polyimide Foam Market
What ties these demand shifts together is an expectation of consistency. As systems become more integrated and tolerances tighter, tubing is no longer evaluated in isolation. It is judged as part of a system-level reliability equation. This has made end-users more selective and more willing to engage with suppliers that can support application-specific engineering, co-development, and longer-term supply assurance. For suppliers, the commercial opportunity lies in moving up the value chain: from selling standard tubing to participating earlier in design cycles, where specification decisions are still fluid and switching costs are lower.
Supply Chain Dispersion and Cost Structure Evolution
Supply chain and cost dynamics are reshaping how value is captured across the market. Polyimide tubing production depends on specialized manufacturing know-how, controlled process environments, and increasingly on reliable access to qualified input streams. As input cost pressures have risen, the ability to manage cost structure without eroding performance has become a defining capability. Suppliers that can maintain quality at scale, optimize yield, and manage working capital effectively are better positioned to absorb cost variability and protect customer relationships.
At the same time, supply chain considerations are influencing sourcing behavior. Buyers in regulated and high-reliability applications often prioritize continuity and auditability over marginal price differences. This has strengthened the position of established manufacturers with documented processes and predictable capacity. It has also created incentives for strategic collaboration, where tubing suppliers work more closely with medical device manufacturers, electronics assemblers, and system integrators to align specifications, reduce rework, and stabilize delivery. The emerging pattern is a market in which cost competitiveness is increasingly tied to process discipline and customer integration rather than to simple scale arbitrage.
Competitive Landscape and Leading Strategies
The competitive field is concentrated enough that a relatively small set of established players accounts for a substantial share of revenue, yet diverse enough that specialization remains a viable path. Market concentration suggests that scale, reputation, and compliance capability matter, but it does not eliminate room for differentiated mid-tier suppliers that can serve demanding niches with high precision and responsive engineering support. The key strategic question is not simply who is largest, but who can most reliably convert technical capability into commercial trust.
Several manufacturers illustrate the strategic paths currently shaping the market. Some are leaning into ultra-precision medical tubing, building reputations around tight tolerances and application-specific customization for catheter and interventional use. Others emphasize reinforcement architectures and high-lubricity variants, targeting performance requirements that standard geometries cannot easily meet. A further group positions itself around industrial and medical versatility, offering broad ranges of dimensional control and heat-resistant performance for customers that need flexible specification options. Across these approaches, the common thread is a move away from generic supply toward solution-oriented engagement.
Recent product activity supports this interpretation. One prominent supplier expanded its material portfolio with a polyimide formulation engineered to deliver substantially higher tensile and column strength than traditional options, a move that directly targets applications where mechanical integrity and handling control are paramount. Shortly afterward, the same company broadened its product line to enable more tailored performance in PTFE and polyimide tubing configurations. These launches are not isolated innovations; they reflect a deliberate strategy of raising the performance floor and increasing configurational flexibility so that the supplier can address a wider range of demanding applications without diluting its technical positioning.
The competitive landscape appears to be evolving along two tracks. On one track, larger or more established players are consolidating their advantage through compliance readiness, process maturity, and broad application coverage. On the other, specialized entrants and focused product line extensions are carving out defensible positions by solving specific performance problems or serving highly specialized procedural needs. Full-scale horizontal consolidation is not inevitable in the near term, but selective consolidation in high-growth segments is likely as buyers prefer fewer, more capable partners. New entrants will need either a genuine process advantage, a compliance edge, or a clearly defined application niche to break through.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interlinked trends.
- Performance-driven specification will deepen. As new formulations and reinforced variants mature, polyimide tubing will be selected for more applications on the basis of measurable mechanical and handling benefits rather than thermal resistance alone. This will increase the importance of application-level validation and supplier-supported testing in winning new business.
- Compliance and qualification readiness will become table stakes in regulated segments. Buyers will continue to favor suppliers that can bring documentation, material transparency, and regulatory alignment into the conversation early. Suppliers that still treat these as after-the-fact requirements will face longer sales cycles and higher disqualification risk.
- Application-adjacent integration will grow in value. The commercial battleground will increasingly be at the design interface, where tubing suppliers are expected to contribute to configuration choices, tolerance planning, and reliability trade-offs. Companies that can engage earlier and reduce downstream iteration will capture more wallet share and more durable relationships.
These trends translate into concrete opportunities. Manufacturers that invest in differentiated material grades, precision processing, and documented compliance will be better placed to command value and reduce price sensitivity. Investors and strategic partners should look for suppliers with a clear link between product innovation and end-use adoption, especially where new formulations enable previously constrained procedures or device concepts. Procurement and engineering leaders should treat supplier selection as a long-term risk management decision, weighting validation support, documentation quality, and application engineering capability alongside unit economics.
PW Consulting Chemical & Energy Research Center
The primary uncertainties to monitor are cost trajectory, regulatory evolution, and the pace at which new performance claims translate into qualified adoption. Input cost pressure could narrow margins for suppliers that cannot pass through value or optimize cost structure. Regulatory expectations may continue to tighten or shift across regions, altering the compliance burden and the speed of qualification. Finally, not every technical enhancement will convert into commercial uptake; some advances will require lengthy validation or may prove over-specified for certain use cases. Market participants should track these variables as leading indicators of where share and margin will migrate.
Strategic Recommendations for Decision-Makers
Manufacturers and suppliers should prioritize the conversion of technical capability into reliable commercial outcomes. That means investing in process control that supports tight tolerances at scale, documenting compliance and material traceability in ways that simplify customer qualification, and designing product portfolios around real application pain points rather than catalog breadth alone. Where possible, moving earlier into the design process and offering co-development support can reduce the risk of late-stage redesign and strengthen customer lock-in without resorting to price competition.
Investors and corporate strategists should assess market opportunities through the lens of defensibility. The most attractive positions are likely to be those where a supplier can demonstrate a repeatable advantage in performance, compliance readiness, or application specialization. Volume growth is important, but durability of demand depends on whether the supplier is solving a hard problem that customers are willing to pay for and cannot easily replicate elsewhere. Track record in regulated environments, the ability to sustain process improvement, and evidence of growing specification share are all signals worth weighting heavily.
Procurement and engineering buyers should treat polyimide tubing sourcing as a strategic decision with long consequences. Evaluate suppliers on more than nominal material grade or lead-time promises. Ask how they handle tolerance control, how they support qualification and documentation, how they manage cost volatility, and whether they can engage constructively in application development. In high-reliability or regulated programs, the cheapest option today can become the most expensive option tomorrow if it introduces qualification delays, variability, or compliance gaps.
Worldwide Polyimide Engineering Plastics Market
For organizations that need a deeper, segment-specific view of where growth is concentrating, which application roads are widening fastest, and how supplier positioning is evolving at the subsegment level, a more detailed research synthesis can help translate these trends into targeted plans. The broader market signals are clear, but the actionable details often depend on how each segment is moving and which performance or compliance capabilities matter most in a given context.
For detailed analysis of this topic, please visit the official page: Polyimide Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com