

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
5-Aminolevulinic Acid Market: Why 9.8% CAGR and Pharma’s Dominance Reshape 2032

Strategic Trends and Commercial Opportunities in the 5-Aminolevulinic Acid Market: A 2032 Outlook
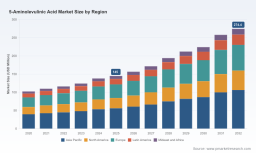
The global 5-Aminolevulinic Acid (5-ALA) market has transitioned from a specialized biochemical niche to a multi-sectoral growth engine, driven by converging advances in photodynamic therapies, agricultural biotechnology, and cosmetic formulations. With a compound annual growth rate of 9.8% through 2032, the sector reflects a disciplined expansion pattern rather than speculative hype. The trajectory from 2020 to 2032 demonstrates consistent value creation, with revenue rising steadily as clinical validation, manufacturing scale-up, and cross-industry adoption reinforce each other. Yet beneath the headline growth metrics lies a more nuanced reality: regulatory fragmentation, formulation bottlenecks, and an evolving competitive map are reshaping how value is captured. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where capital, R&D, and commercial execution will yield the highest risk-adjusted returns.
This analysis examines the structural drivers, competitive dynamics, and forward-looking inflection points that will define the 5-ALA landscape over the next three to five years. The goal is to translate macroeconomic momentum into actionable strategic positioning, highlighting where operational excellence, regulatory navigation, and application diversification intersect.
Market Snapshot and Core Challenges
The market has demonstrated resilient upward momentum, expanding from a baseline in 2020 to an estimated valuation in 2025, with projections pointing toward a multi-hundred-million-dollar scale by 2032. The growth profile is characterized by sustained, double-digit compounding that reflects both volume expansion and value migration toward higher-margin applications. Rather than a single breakthrough driving this trajectory, the expansion is the product of incremental clinical adoption, agricultural pilot scaling, and formulation optimization across multiple end-use sectors.
Despite this momentum, three structural challenges are redefining the commercial playbook.
Regulatory Uncertainty and Classification Gaps
The regulatory landscape for 5-ALA remains uneven across major markets. In pharmaceutical and medical device contexts, approvals have progressed through established clinical pathways, enabling commercialization in specific diagnostic and therapeutic applications. Outside these narrow indications, however, classification remains unresolved. In the United States, the absence of definitive guidance on whether 5-ALA qualifies as a New Dietary Ingredient has created ambiguity for supplement and functional nutrition ventures. Similarly, in the European Union, the compound continues to navigate Novel Food review processes, with no final determination enabling broad dietary supplement deployment. This regulatory lag is not merely a compliance issue; it dictates which business models can scale, which distribution channels remain accessible, and how quickly new formulations can reach consumers or enterprise buyers.
PW Consulting Chemical & Energy Research Center
Formulation and Delivery Optimization Constraints
While 5-ALA’s biochemical properties are well understood, translating laboratory efficacy into consistent clinical or agricultural outcomes remains a non-trivial engineering challenge. Photodynamic applications require precise timing, concentration control, and tissue-specific uptake, while agricultural and cosmetic use cases demand stability, dermal or foliar compatibility, and shelf-life reliability. Recent clinical data has demonstrated that extending the administration window for oral 5-ALA can improve procedural flexibility in diagnostic settings, underscoring that delivery protocols—not just molecule availability—are critical value drivers. Companies that treat formulation and dosing protocols as afterthoughts risk ceding margin and differentiation to competitors who integrate pharmacokinetics, user experience, and application-specific optimization into their core product architecture.
Supply Chain Concentration and Quality Standardization
The market exhibits moderate concentration among established suppliers, with a meaningful share of high-purity material flowing through a limited set of manufacturers and regional production hubs. This structure offers efficiency advantages but introduces vulnerability: batch consistency, regulatory documentation, and specialty-grade purification remain bottlenecks for downstream formulators. Moreover, as demand expands beyond research-grade supply into commercial-scale pharmaceutical, agricultural, and cosmetic volumes, the industry faces pressure to standardize quality frameworks while managing cost structures. Firms that rely on fragmented sourcing or lack robust analytical validation risk delays, compliance friction, and margin erosion as end-market specifications tighten.
Key Growth Drivers Reshaping the Landscape
The 5-ALA market’s expansion is not uniform; it is being pulled forward by a set of interlocking drivers that reward companies capable of aligning technical, regulatory, and commercial execution.
Clinical Validation and Fotodynamic Therapy Evolution
The most consequential driver is the maturation of photodynamic diagnosis and therapy applications. Clinical evidence continues to reinforce the utility of 5-ALA as a photosensitizing precursor in tumor visualization and targeted treatment protocols. Recent regulatory acknowledgments that extend oral administration windows for specific diagnostic procedures illustrate how clinical data can directly translate into procedural flexibility and broader adoption. As hospitals and specialty clinics integrate these protocols into routine workflows, demand shifts from experimental or pilot-scale use toward standardized, repeatable procurement. This transition elevates the importance of product reliability, regulatory documentation, and clinician training support, turning commercial success into a function of ecosystem enablement rather than molecule supply alone.
Policy and Regulatory Pathway Clarification
While regulatory uncertainty remains a challenge, incremental policy progress is also a growth catalyst. Where health authorities provide clearer indications for medical use, downstream investment becomes more predictable. In parallel, agricultural and cosmetic applications are shaping their own compliance trajectories, often leveraging existing biostimulant, cosmetic ingredient, or research-grade frameworks to accelerate go-to-market timelines while broader dietary classifications remain unresolved. The companies that navigate this environment effectively do not wait for a single global ruling; they design application-specific regulatory strategies that align with the fastest available pathways, using clinical or agronomic data packages to support targeted approvals and market access.
Demand-Side Shifts in Agriculture and Personal Care
Beyond the clinic, demand-side behavior is evolving rapidly. In agriculture, the push for yield optimization, stress tolerance, and reduced dependency on conventional inputs has elevated interest in biochemical biostimulants. 5-ALA’s role in chlorophyll synthesis and plant metabolic pathways positions it as a candidate for precision agricultural programs, particularly in markets where sustainability mandates and input cost pressures coincide. In cosmetics and personal care, consumer interest in biologically derived actives and skin-health benefits has spurred formulation exploration, with brands seeking ingredients that can anchor marketing narratives in mechanistic plausibility rather than purely cosmetic claims. These demand shifts expand the addressable base for 5-ALA beyond traditional medical channels, but they also require differentiated value propositions, safety data packages, and supply reliability tailored to each sector’s procurement standards.
Manufacturing and Cost Structure Improvements
Scaling production of high-purity 5-ALA and its salt forms has become a strategic priority as multi-sector demand intensifies. Advances in synthesis routes, purification processes, and quality control analytics are gradually improving cost structures and batch-to-batch consistency. The effect is twofold: it lowers barriers for formulators seeking dependable supply, and it enables incumbents to expand margins while investing in application-specific development. However, cost leadership alone is unlikely to secure durable advantage. The more durable moats are emerging around integrated quality systems, regulatory-ready documentation, and partnerships that link manufacturing capability with formulation science and end-market technical support.
Competitive Landscape and Strategic Positioning
The competitive field spans specialty pharmaceutical developers, chemical suppliers, research-grade distributors, and regional manufacturers pursuing agricultural and cosmetic applications. Rather than competing solely on price, leading players are carving out positions based on application focus, regulatory readiness, and technical service capabilities.
Differentiated Playbooks Across the Value Chain
Several companies have built recognizable identities around specific use cases. In the medical and diagnostic segment, firms with approved 5-ALA-based products for photodynamic visualization have leveraged clinical evidence, procedural training, and regulatory approvals to anchor their positions. Their advantage lies not simply in supplying the molecule, but in enabling clinical adoption through protocol clarity, product consistency, and medical affairs support.
In the research and reagent space, established chemical suppliers compete on purity certification, documentation reliability, and breadth of catalog support. Their customers prioritize batch traceability and analytical validation, which makes quality systems and supplier credibility central to retention. In the industrial and specialty chemical segment, manufacturers that can provide high-purity intermediates and customized synthesis options gain relevance among formulators who need flexibility in specifications and scale. Meanwhile, regional players in Asia have expanded their footprint by addressing both pharmaceutical and agricultural biostimulant demand, often combining API production with formulation exploration tailored to local crop and market conditions.
Strategic Advantages and Ecosystem Positioning
The most defensible positions emerge where molecule supply intersects with application expertise. Companies that combine reliable purification and manufacturing with regulatory documentation, stability data, and end-use technical support create friction for customers considering multi-sourcing or switching to lower-cost alternatives. In diagnostic and therapeutic niches, approval status and clinical protocol alignment function as strong barriers to entry. In agricultural and cosmetic channels, success increasingly depends on demonstrating consistent performance, safety profiles, and supply continuity rather than competing on commodity pricing alone.
This landscape is also being shaped by selective external collaboration. Major pharmaceutical and biotechnology players have shown interest in exploring enhanced 5-ALA formulations for photodynamic applications, signaling that formulation innovation and partnership-driven development can accelerate value creation even when internal R&D capacity is constrained. Such collaborations often focus on improving efficacy, expanding treatment or diagnostic windows, or tailoring delivery characteristics, which reinforces the broader industry shift toward formulation-led differentiation.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The market is neither fully consolidated nor highly fragmented; it is evolving through a combination of specialization and selective consolidation. In research-grade and reagent segments, brand trust and analytical reliability support stable positioning, while in commercial-scale pharmaceutical and agricultural segments, scale, regulatory readiness, and application support increasingly matter. New entrants are likely to appear where application gaps remain: niche cosmetic actives, regional agricultural biostimulant programs, and next-generation formulation concepts that improve stability, targeting, or ease of use. The strategic implication is clear: competitive advantage will belong to firms that define a precise application focus, build the corresponding regulatory and technical evidence base, and align supply chain capabilities with that focus rather than pursuing undifferentiated volume expansion.
5-Aminolevulinic Acid Hydrochloride Market
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, three trends are likely to shape how value is created and captured in the 5-ALA market.
Application-Specific Formulation as a Core Differentiator
The next phase of growth will increasingly reward companies that tailor 5-ALA products to specific end-use requirements rather than selling a uniform molecule across all channels. In medical and diagnostic settings, this means optimizing administration timing, concentration ranges, and procedural compatibility. In agriculture, it means developing formulations aligned with foliar application, stress resilience, and compatibility with existing crop management programs. In cosmetics, it means prioritizing stability, sensory attributes, and claim-supportive safety data. The commercial opportunity lies in building a portfolio architecture where each product variant is backed by the right evidence package, regulatory positioning, and technical support for its intended market.
Levulinic Acid Market
Regulatory Clarity as a Market Access Accelerator
As regulatory frameworks continue to mature, segments that secure clearer pathways will experience faster scaling, while ambiguous segments will remain dependent on workaround strategies or narrower use cases. Companies that proactively invest in data generation, dossier preparation, and early engagement with health authorities will be better positioned to convert scientific potential into commercial reach. Conversely, businesses that rely on regulatory ambiguity as a temporary advantage may face increasing scrutiny as standards tighten and downstream customers demand demonstrated compliance. The strategic lesson is to treat regulatory preparation as a growth investment rather than a compliance cost.
Supply Chain Integration and Regional Capacity Expansion
Demand diversification across regions and applications will pressure the industry to build more resilient, regionally balanced supply capability. Where production remains overly concentrated, downstream buyers will seek redundancy, quality guarantees, and localized technical support. The likely response is a mix of expanded regional manufacturing, strengthened analytical and quality frameworks, and closer integration between suppliers and formulators. This shift creates opportunities for players that can offer dependable supply, transparent documentation, and the flexibility to support application-specific requirements. It also raises the stakes for firms that cannot meet increasing quality and consistency expectations as commercial volumes grow.
These trends carry inherent uncertainty. Regulatory timelines can shift, clinical adoption can plateau if procedural barriers persist, and agricultural or cosmetic adoption can be sensitive to economic cycles and input-cost dynamics. Competitive entry may compress margins in certain segments, and formulation claims will face higher scrutiny as markets mature. The businesses that navigate these risks most effectively will be those that combine disciplined application focus with credible data, robust quality systems, and flexible commercial models.
Strategic Recommendations for Decision-Makers
For executives and investors evaluating exposure to 5-ALA, the opportunity is real but increasingly segmented. Value creation will depend less on broad commodity positioning and more on targeted application strategies, regulatory alignment, and supply chain reliability.
For Manufacturers and Product Developers
- Define a clear primary application focus and build the supporting evidence package, quality documentation, and technical support around it. A molecule-centric strategy without application-specific differentiation is increasingly vulnerable to competition and margin pressure.
- Treat formulation science and delivery protocols as core IP. Improvements in stability, timing flexibility, compatibility, and ease of use can create defensible positioning, especially in medical and diagnostic channels where procedural fit matters.
- Invest in regulatory readiness early. Proactive data generation, dossier preparation, and engagement with relevant authorities reduce time-to-access and improve customer confidence, particularly when downstream buyers are risk-averse.
For Investors and Strategic Capital Allocators
- Evaluate exposure by application pathway rather than by aggregate market growth alone. Segments with clearer regulatory status, established clinical or agronomic use, and repeatable procurement cycles tend to offer more predictable value capture than ambiguous or early-stage segments.
- Look for combination value: manufacturing reliability plus formulation capability plus application-specific support. Companies that only compete on volume or price may face structural margin risk as quality and compliance expectations rise.
- Monitor partnership activity and selective collaborations that signal formulation innovation or expanded indications. Such moves often preview where the next wave of differentiation will emerge.
For Procurement and Commercial Buyers
- Prioritize supplier consistency, analytical validation, and documentation completeness over lowest-unit-cost options, especially when formulations are integrated into regulated or performance-sensitive workflows.
- Align sourcing strategies with end-use requirements. A supplier strong in research-grade reliability may not be the best fit for commercial-scale agricultural or cosmetic programs, and vice versa.
- Build contingency planning into supply agreements. As demand grows across multiple sectors, multi-source strategies, clear quality specifications, and contractual clarity on documentation and batch traceability can reduce operational risk.
Moving from Insight to Execution
The 5-Aminolevulinic Acid market is entering a phase where breadth of opportunity is giving way to the need for precision in execution. Growth will continue, but the distribution of value will increasingly favor companies that combine scientific credibility, application-specific product design, regulatory preparedness, and dependable supply. For decision-makers, the strategic task is to identify which segment aligns with organizational capabilities, which evidence and compliance gaps must be closed, and how supply partnerships should be structured to support growth without exposing the business to unnecessary quality or continuity risk.
Detailed segmentation data, company-level profiling, and scenario-based forecasts can materially improve the quality of strategic planning in this environment. For organizations seeking a deeper, data-rich view of regional dynamics, application breakdown, competitive positioning, and tailored commercial options, the full PW Consulting market research report provides the structured detail and customized analytical support needed to translate these trends into concrete execution plans.
For detailed analysis of this topic, please visit the official page: 5-Aminolevulinic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com