

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Rubber Sheet Market 2026: Decoding the True Drivers Behind 4.4% CAGR Growth

Strategic Trends and Commercial Opportunities in the Rubber Sheet Market
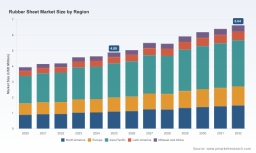
The global rubber sheet market has entered a phase of steady, investment-grade expansion. Fueled by consistent demand across industrial, automotive, and specialty manufacturing sectors, the market has scaled from 3.94 billion USD in 2020 to an estimated 4.89 billion USD in 2025. Forward-looking projections indicate the market will reach 6.64 billion USD by 2032, underpinned by a compound annual growth rate of 4.4 percent between 2026 and 2032. This trajectory reflects more than cyclical recovery; it signals a structural recalibration driven by material innovation, evolving regulatory frameworks, and shifting end-user expectations. For executives navigating procurement, production, or capital allocation, understanding the forces reshaping this arena is no longer optional.
Market Size, Growth Trajectory, and Structural Positioning
The revenue expansion observed over the past five years has been relatively uniform, though the composition behind the headline figures reveals important nuances. The market is not growing through a single vertical or geography but through a combination of mature industrial demand, emerging applications in healthcare and clean energy, and deliberate premiumization in material specifications. Asia Pacific continues to account for the largest revenue share, reflecting both manufacturing density and infrastructure build-out, while North America and Europe maintain strong positions anchored in automotive, chemical processing, and regulated industrial environments. Growth is not purely volume-driven; higher-margin specialty grades and performance-enhanced synthetics are gradually capturing a larger slice of total revenue, indicating a market that is incrementally shifting from commodity substitution toward value-engineered solutions.
Beneath the steady growth curve lies a competitive structure that remains moderately fragmented at the top but increasingly polarized in capability. The top three participants collectively command roughly 35 percent of market revenue, while the top five reach approximately 50 percent. This concentration suggests that scale, technical service, and supply chain reliability still differentiate winners, but it also leaves meaningful room for regional specialists, custom fabricators, and technology-focused entrants to compete on specification intensity rather than sheer volume. The market is not consolidating into a handful of dominant players; rather, it is stratifying into tiers where leadership is defined by material expertise, certification readiness, and the ability to translate application requirements into repeatable production processes.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the industry is navigating several pressure points that are reshaping competitive dynamics and margin structures.
-
Raw material volatility and sourcing complexity. Natural rubber pricing has experienced sharp movements recently, with futures trading above 230 US cents per kilogram in early June 2026, marking the highest level since January 2017. In India, official data from June 2026 recorded RSS1 at INR 30,462 per 100 kilograms and RSS4 at INR 26,500 per 100 kilograms. These price signals reflect supply constraints and geographic imbalances that ripple through formulation decisions, inventory planning, and pricing strategies across the value chain. For sheet producers and converters, this volatility is not a transient issue; it is becoming a structural cost-management challenge that demands more sophisticated hedging, blending, and specification triage.
-
Regulatory traceability and compliance burdens. The EU Deforestation Regulation has moved from policy concept to operational reality, requiring plot-level traceability and auditable sourcing for natural rubber entering premium export channels. This requirement is reshaping who can access high-value European markets, forcing supply chains to document origin, verify land-use practices, and build audit-ready systems. While the regulation primarily targets deforestation-linked commodities, its practical effect on the rubber sheet sector is significant: it raises the barrier to entry for premium natural rubber grades, accelerates the shift toward certified or synthetic alternatives, and rewards suppliers with transparent, digitally traceable sourcing infrastructure.
-
Performance versus cost tension in end-use applications. Automotive, chemical processing, mining, pharmaceutical, and healthcare buyers increasingly demand sheets that meet stricter mechanical, chemical, and environmental criteria without a proportional increase in cost. Meeting these expectations requires more than incremental grade improvements; it calls for formulation innovation, tighter process control, and often a willingness to invest in application-specific validation. Companies that treat specification requirements as a compliance checkbox rather than a value-creation opportunity risk losing share to competitors who can demonstrate measurable performance gains, lower lifecycle cost, or faster qualification cycles.
Core Drivers Reshaping the Market
The growth and differentiation underway in the rubber sheet market are not accidental. They are being pulled by several reinforcing forces that are altering where value is created and how companies compete.
Technological Innovation and Material Breakthroughs
Material science is steadily expanding the boundary of what rubber sheets can deliver in demanding environments. Formulation advances are enabling better resistance to oils, solvents, temperature extremes, and abrasion while maintaining flexibility and ease of fabrication. Equally important, the push toward sustainability is becoming a technology driver rather than a compliance burden. Recent industry moves illustrate this shift clearly: in September 2024, ContiTech introduced a new line of eco-friendly rubber sheets incorporating bio-based fillers designed to reduce carbon footprint. That same direction continued into 2025, when Envire Flooring launched Envire® Rubber Sheet & Tile with VOC emissions compliant with CA Section 01350 and FloorScore/GreenGuard Gold certification. These developments are not isolated product launches; they signal a broader transition in which environmental performance, indoor air quality, and carbon-intensity reduction are becoming specification criteria alongside traditional mechanical properties.
For manufacturers, this means innovation is increasingly multi-dimensional. Success depends on the ability to combine performance attributes with sustainability credentials, certification readiness, and consistent batch-to-batch quality. Suppliers that can deliver these combinations in repeatable production environments are gaining leverage in negotiations, particularly with buyers facing their own scope 3 targets or procurement mandates tied to low-emission materials.
Ribbed Smoked Sheet Rubber Rss Market
Policy and Regulatory Environment
Policy is moving from a background constraint to a front-line strategic variable. Environmental and sourcing regulations are compelling buyers and suppliers to treat traceability, emissions, and material provenance as core purchasing criteria. The EU Deforestation Regulation's plot-level traceability and auditable sourcing requirements are already influencing premium export channel access for natural rubber. While the regulatory burden is real, it also creates a sorting mechanism: suppliers with robust documentation, verified sourcing, and transparent chain-of-custody systems are better positioned to maintain or expand access to high-value markets, while those without such infrastructure face mounting commercial friction.
Beyond environmental rules, broader industrial safety and chemical management standards continue to shape specification choices. In regulated sectors such as pharmaceuticals, healthcare, and certain chemical processing environments, certification and emissions compliance increasingly determine which products can be considered at all. Regulatory momentum therefore has a dual effect: it compresses the addressable market for non-compliant offerings while expanding the premium for suppliers that can demonstrate credible compliance and test-ready documentation.
Rubber Flooring Market
Demand-Side Shifts in Buyer Behavior
Purchasing behavior is evolving from transactional price comparison toward total cost and risk evaluation. Automotive OEMs and tier suppliers, chemical manufacturers, mining operators, and healthcare and pharma buyers are increasingly weighing factors such as material consistency, certification status, supplier technical support, and lifecycle durability alongside unit price. This shift is particularly pronounced where sheet rubber is integrated into safety-critical, regulated, or high-uptime applications, because failure or variability carries consequences that far outweigh marginal cost differences.
At the same time, demand is diversifying. Automotive remains the largest application segment by revenue, reflecting continuing needs in sealing, vibration damping, gasketing, and component fabrication. Chemicals and mining applications contribute substantial volume, driven by containment, abrasion resistance, and harsh-environment performance. Meanwhile, pharmaceutical and healthcare use is expanding as hygiene, cleanliness, and low-emission requirements become more stringent. The result is a market in which demand is not only growing but also fragmenting into more specification-intensive pockets, each with distinct performance and compliance expectations.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by raw material dynamics, energy considerations, logistics complexity, and the premium attached to reliability. The recent surge in natural rubber futures and the elevated domestic price levels observed in key producing regions underscore how quickly input costs can move when supply tightness coincides with steady demand. For sheet producers, the implication is clear: cost management is no longer a matter of negotiating a single resin or latex price. It requires portfolio-level decisions about natural versus synthetic blending, grade selection aligned to application needs, inventory buffering strategies, and the use of alternative fillers or reinforcements where performance permits.
Supply chain resilience is becoming a competitive asset in its own right. Buyers are increasingly sensitive to lead-time stability, minimum order flexibility, technical responsiveness, and the ability to support custom or specialty configurations. This favors companies that have invested in integrated production capabilities, predictable quality systems, and the operational discipline to handle both high-volume standard grades and lower-volume specialty orders without sacrificing service levels. In a market where top-five players already command about half of total revenue, differentiated service and supply reliability can be as decisive as product attributes when contracts are awarded.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of regional manufacturers, custom fabricators, specialty material suppliers, and global industrial players. Each cluster approaches the market with a distinct value proposition, and the most successful firms are aligning their capabilities with the segments where they can win on specification and reliability rather than competing broadly on price alone.
WARCO, based in Orange, California, has built its position around a broad natural and synthetic sheet portfolio, including nitrile, EPDM, neoprene, silicone, HNBR, Viton, and custom spec-grade rubber for industrial and specialty uses. This breadth allows the company to serve buyers who require multiple elastomer types under a single sourcing relationship, simplifying procurement while maintaining the ability to match material properties to application demands. Aero Rubber Company in Tinley Park, Illinois, competes on volume and customization, producing custom molded, extruded, and fabricated rubber components alongside custom sheets and slabs. Its strength lies in integrated fabrication capability, which can reduce downstream processing burden for customers that prefer a more complete component solution rather than bare sheet material.
Hanna Rubber Company focuses on calendered sheet rubber in extra-thick, super-thin, or double-wide options, including custom and specialty fabrics. This positioning targets buyers who need dimensional flexibility and fabric integration for specific manufacturing or installation requirements. American Biltrite, operating across Canada and the United States, emphasizes premium-quality sheet rubber across major elastomers in various gauges, widths, and sizes with fabric reinforcement, appealing to customers that prioritize consistent gauge control and reinforced performance. BRP Manufacturing in Lima, Ohio, serves military, automotive, aerospace, and industrial customers with high-quality sheet rubber and extruded rubber products, a mix that demands rigorous specification control and the ability to meet demanding end-use standards.
International players add further diversity. TOGAWA Rubber in Japan produces rubber sheets for industrial gaskets, floor mats, and extrusion applications, reflecting a focus on precision and application-specific patterning. Zenith Rubber in Mumbai, India, has manufactured rubber sheets, mats, flooring, and industrial rubber products since 1965, leveraging long experience and regional cost advantages while serving both domestic and export demand. Rubberteck International in Busan, South Korea, supplies anti-static and other rubber sheets for industrial applications, highlighting a niche where electrostatic control and specialized performance justify dedicated sourcing. ContiTech, a division of Continental based in Germany, produces high-performance rubber sheets and materials for industrial applications, combining global scale with engineering credibility and, increasingly, sustainability-forward product development.
What ties these leaders together is not identical product lines but strategic clarity. The strongest players are differentiating along one or more of the following axes: material breadth and spec-grade customization, integrated fabrication and component capability, dimensional and fabric-reinforcement specialization, sector-specific certification and compliance readiness, and sustainability-driven formulation. This is a market where generalists can survive, but specialists and clearly positioned players tend to capture more defensible margins.
Evolution of the Competitive Landscape
The market is not heading toward outright consolidation into a few dominant firms. Instead, it is evolving through capability layering and segmentation. Larger, multi-elastomer producers are expanding their technical service and sustainability portfolios to protect share in regulated and premium segments. Custom fabricators and molded-component manufacturers are gaining relevance as buyers seek to offload more processing steps and reduce integration risk. Regional specialists continue to compete effectively where local service, cost structure, and application knowledge matter more than global scale. Meanwhile, new entrants and niche players are finding openings in anti-static, low-emission, and bio-based or certified material segments where specification intensity creates room for focused offerings.
A practical implication is that competitive advantage is increasingly defined by the ability to operate across multiple value dimensions at once: consistent quality, traceable sourcing, certification readiness, technical support, and sustainable formulation options. Companies that only compete on volume or price are more exposed to raw material swings and regulatory sorting, while those that combine material expertise with service depth and compliance credibility are better positioned to defend margins and win specification decisions.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape where growth concentrates and how value is captured.
-
Sustainability performance becomes a default specification dimension. Low-emission products, bio-based fillers, and certified or traceable sourcing will move from differentiators to baseline expectations in a growing share of applications, particularly in Europe, North America, and regulated industrial sectors. Commercial opportunity lies with manufacturers that can offer credible, test-backed sustainability claims without sacrificing mechanical or chemical performance, and with procurement teams that can integrate these criteria into sourcing scorecards before specifications become locked in by competitors.
-
Premium natural rubber channels become more selective and compliance-dependent. As traceability and audit requirements reshape access to high-value export markets, suppliers with robust documentation and verified sourcing will enjoy preferential access, while others face narrowing options. This creates opportunity for companies that invest early in chain-of-custody systems, supplier documentation, and digital traceability, as well as for buyers that secure reliable, compliant supply ahead of broader market tightening.
-
Customization and application-specific engineering gain share over generic commodity sheets. Demand is increasingly oriented toward specific gauges, fabric reinforcements, anti-static properties, chemical resistance profiles, and low-VOC formulations. The opportunity is not simply to sell more sheet by weight but to sell solutions that reduce downstream processing, accelerate qualification, lower failure risk, and support total-cost objectives. For producers, this means building flexible production and technical-service capabilities; for investors, it means evaluating whether target companies can sustain premium positioning through engineering value rather than volume alone.
These trends carry risk as well as opportunity. Raw material volatility can compress margins if pricing power and formulation flexibility are limited. Regulatory requirements may raise compliance costs and exclude suppliers that cannot meet traceability or emissions thresholds. Demand-side expectations can shift faster than production capabilities, leaving slower-responding firms with mismatched inventories or obsolete grade mixes. The upside, however, belongs to organizations that treat these pressures as planning inputs and respond with deliberate investment in material capability, compliance infrastructure, and specification-level differentiation.
PW Consulting Chemical & Energy Research Center
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen the link between material portfolio, application expertise, and compliance readiness. This means reviewing whether product lines map clearly to the highest-value segments, whether formulation flexibility allows intelligent blending or grade substitution in response to raw material movement, and whether sustainability and traceability capabilities are sufficiently developed to meet rising specification requirements. Companies should also assess whether their fabrication, custom-spec, or technical-service capabilities are strong enough to win on total solution value rather than competing only on sheet price.
For investors, the focus should be on structural positioning rather than headline growth alone. Evaluate whether target companies have defensible differentiation through material breadth, specialty grades, certification readiness, or integrated fabrication; whether their cost and sourcing strategies can withstand raw material volatility; and whether their sustainability roadmap is grounded in product reality and test-backed claims rather than marketing language. Preference should go to operators that can demonstrate a repeatable ability to win specification decisions in regulated or performance-critical segments, because those decisions tend to be stickier and more margin-protective over time.
For procurement and supply chain leaders, the strategic task is to broaden evaluation criteria beyond unit cost and to secure supply clarity ahead of regulatory and price pressures. Incorporate traceability, emissions compliance, batch consistency, technical support, and lifecycle performance into sourcing frameworks. Where natural rubber exposure is significant, consider supply diversification, certified or compliant channel planning, and formulation strategies that preserve performance while managing input risk. Early engagement with suppliers that already meet emerging traceability and low-emission expectations can reduce qualification delays and protect continuity in premium channels.
The market's direction is clear enough to warrant action, but the details that determine competitive success are highly segment-specific. Trim-level specification mixes, regional sourcing constraints, certification requirements, and application-level performance thresholds vary widely, and generic assumptions often lead to mispriced risk or missed openings. Decision makers who need granular segment data, company-level capability mapping, and tailored scenario analysis will find greater value in structured, deeper research than in broad market narratives. For those evaluating strategic moves, gathering detailed intelligence on segment growth drivers, competitive positioning, regulatory exposure, and material-cost sensitivity is a practical next step before committing capital, renegotiating supply, or redesigning product roadmaps.
For detailed analysis of this topic, please visit the official page: Rubber Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com