

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electronic Grade Hydrofluoric Acid Market: Why 6.98% CAGR Signals Strategic Shifts

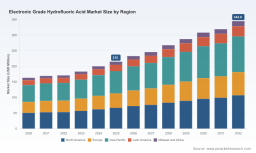
Electronic Grade Hydrofluoric Acid Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Snapshot: Scale, Trajectory, and Core Challenges
The electronic grade hydrofluoric acid sector has transitioned from a steady industrial chemical niche into a strategically critical supply chain component. Valued at approximately 163.15 million USD in 2020, the market reached 215.0 million USD by 2025 and is projected to expand to 344.8 million USD by 2032, reflecting a compound annual growth rate of 6.98 percent across the 2026–2032 forecast horizon. This trajectory signals more than incremental demand growth; it reflects a structural realignment in how advanced electronics manufacturers secure ultra-pure wet processing chemicals amid tightening quality thresholds and shifting sourcing strategies.
By the close of 2025, revenue concentration had consolidated meaningfully among established producers, with the top three firms capturing roughly 62.5 percent of global sales and the top five reaching 78.3 percent. This concentration pattern underscores two realities: first, the technical and regulatory barriers to producing semiconductor-grade acids remain steep; second, end-users increasingly prefer suppliers with validated purity consistency, localized manufacturing footprints, and audit-ready compliance frameworks.
Key Challenges and Inflection Points
Despite the favorable long-term demand curve, several structural pressures are reshaping supply planning and margin dynamics.
Raw material volatility and upstream cost transmission have emerged as a persistent margin management challenge. In April 2026, the spot price for Electronic Grade G5 material reached 110,000 RMB per ton, marking a 40 percent increase from the start of the year, while the annual average price of anhydrous hydrofluoric acid in the United States climbed to 2,565 USD per metric ton by March 2026 following quarter-over-quarter increases. Fluorspar mining also encountered restrictions, environmental inspections, and holiday-related disruptions in early 2026, reinforcing a stable-to-firm global pricing environment. For buyers and producers alike, these shifts complicate long-term cost modeling and require more agile procurement architecture.
Geopolitical risk is now a first-order pricing variable rather than a peripheral concern. In early 2026, friction around the Strait of Hormuz curtailed marine traffic by more than 90 percent, pushing Brent crude to 88.87 USD per barrel and inflating Chinese HF spot offers by 12 percent month-over-month. This episode highlighted how energy logistics, freight routing, and regional supply concentration intersect with electronic chemical pricing in ways that traditional cost models often underestimate.
On the production side, regional output fluctuations add another layer of unpredictability. By April 2026, electronic grade hydrofluoric acid production output in China registered a modest year-on-year decline amid broader operating conditions, even as downstream demand from semiconductor and display supply chains continued to strengthen. Such episodic divergences between production capacity utilization and end-market demand emphasize the importance of visibility into regional operating environments, not just headline capacity figures.
Collectively, these dynamics point to an inflection point where cost resilience, geographic diversification, and purity assurance are becoming decisive competitive levers rather than operational afterthoughts.
Key Demand Drivers: What Is Really Propelling the Market
The expansion of the electronic grade hydrofluoric acid market is not simply a function of more devices being built; it is driven by specific technological, regulatory, and structural shifts that alter how and where ultra-pure acids are consumed.
Technology Innovation and Purity Thresholds
Semiconductor wafer manufacturing remains the dominant consumption arena, and the technical demands of advanced nodes are steadily redefining acceptable impurity thresholds. As patterning, etching, and cleaning steps become more sensitive to particulate and metallic contamination, the distinction between standard electronic grade and ultra-high-purity grades takes on commercial weight. Producers that can demonstrate repeatable control over trace contaminants, supported by robust analytical certification and lot-to-lot consistency, are positioned to secure longer-term supply agreements with leading fabs. This technical premium is also encouraging dual-track supply strategies, where manufacturers maintain both standard and ultra-high-purity sourcing channels to protect yield performance across different process steps.
Policy and Regulatory Environment
Regulatory scrutiny and sustainability expectations are reshaping sourcing decisions. Environmental inspections and operational restrictions across key fluorspar and HF supply regions have tightened availability windows and reinforced pricing firmness. At the same time, broader energy and logistics disruptions have accelerated the preference for suppliers with transparent compliance records and regionally balanced production capabilities. For procurement teams, regulatory visibility is now part of supplier qualification rather than a separate risk register item. Markets where producers can demonstrate environmental diligence, controlled emissions, and stable energy sourcing are gaining a structural advantage in qualification cycles.
Demand-Side Shifts Across Electronics End Markets
Beyond semiconductors, adjacent electronics applications continue to contribute to demand breadth. Solar cell fabrication and display panel manufacturing represent substantial consumption pathways, and each carries its own pace of process refinement and capacity cycles. In solar, improvements in cell architecture and throughput efficiency influence wet chemical consumption intensity, while display manufacturing continues to depend on high-purity etching and cleaning steps for large-format panels. These diversified demand streams reduce single-market dependency for suppliers and create opportunities for those able to manage multiple purity specifications and delivery formats without sacrificing consistency.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being reshaped by both input economics and regional capacity responses. Upstream price movements have been pronounced: PTFE prices from major producers rose 15–16 percent in March 2026, the steepest increase since 2024, reflecting how input cost pressure can propagate quickly into fluorine-based chemical value chains. Meanwhile, regional production expansions aim to improve supply assurance for local electronics clusters. One notable example is the expansion activity near a major rail line in Casa Grande, where an acquisition of additional land was announced to support scaled production and direct supply to nearby semiconductor manufacturers. Such localized capacity additions illustrate how logistics adjacency and regional customer proximity are increasingly integrated into supply strategy, not just production volume.
The net effect is a market in which cost leadership alone is no longer sufficient. Suppliers that combine disciplined input cost management with geographic flexibility, grade-specific capability, and transparent logistics planning are more likely to convert demand growth into durable contract wins.
Competitive Landscape and Leading Strategies
The competitive environment in electronic grade hydrofluoric acid reflects a blend of specialized fluorine chemistry manufacturers, diversified industrial suppliers, and regional players with strong local customer relationships. Leadership in this space is increasingly defined by grade coverage, supply reliability, and the ability to operate at the intersection of high-purity chemistry and regional demand clusters.
Strategic Positioning Among Key Players
Firms with deep fluorine chemistry heritage continue to anchor the market through specialized purification expertise and broad grade portfolios. Morita Chemical Industries and Stella Chemifa, both based in Osaka, Japan, maintain strong positions by focusing on high-purity fluoride chemicals and ultra-high-purity hydrofluoric acid for semiconductor etching and display applications. Their longstanding technical reputation provides a credibility advantage in qualification-heavy environments, where purity consistency and documentation rigor often outweigh short-term price differentials.
In the United States, supply strategies are increasingly oriented around regional security of supply and direct fab proximity. Honeywell International has reinforced its position with ultra-high-purity electronic grade solutions, including Puranal grades, for wafer cleaning and etching, alongside dedicated Texas production capacity. Sunlit Arizona, LLC, based in Phoenix, operates a facility capable of supplying up to 30 kilotons per year of electronic grade hydrofluoric acid directly to U.S. semiconductor fabs. Its April 2026 expansion move, involving the acquisition of additional acreage near a major rail line in Casa Grande, further demonstrates a logistics-integrated approach designed to support scaled production for local chip manufacturers. KMG Chemicals, headquartered in Dallas, contributes a distribution and supply footprint that broadens access to electronic grade material across semiconductor and electronics manufacturing channels.
European players preserve a strong specialty chemical orientation. Solvay, based in Brussels, produces high-purity hydrofluoric acid for semiconductor wafer etching and display panel applications, emphasizing integration into broader fluorochemical portfolios and established industrial reliability.
Chinese manufacturers represent a rapidly maturing segment with expanding technical capabilities and a growing emphasis on local electronics supply chains. Do-Fluoride Chemicals in Jiaozuo, Henan, produces high-purity electronic grade acid for microelectronics and semiconductor wet processing. Jiangyin Jianghua Microelectronics Materials, in Jiangsu, supplies ultra-clean electronic chemicals including high-purity hydrofluoric acid for semiconductor, LCD, and solar cell manufacturing. Zhejiang Juhua, operating as part of a broader fluorochemical portfolio in Zhejiang, has also expanded electronic grade hydrofluoric acid production for semiconductor applications. These players are increasingly relevant not only for cost-competitive supply but also for regional responsiveness and the ability to serve domestic electronics clusters at scale.
How the Landscape Is Evolving
The market structure is moving toward a hybrid model: concentration among proven high-purity suppliers continues, but regional capacity additions and localized supply relationships are creating more diversified sourcing pathways. This pattern favors suppliers that can offer credible purity credentials while also aligning with regional demand centers and logistics realities. It also encourages integration across production, distribution, and customer-facing technical support, since end-users are increasingly evaluating the full service package rather than the molecule alone.
At the same time, cost pressure and input volatility are testing margin discipline across the value chain. Producers that can manage upstream cost shocks, pass through pricing transparently where justified by specification and reliability, and maintain capacity utilization in the face of episodic regional output fluctuations are better positioned to protect profitability through the cycle.
Forward Outlook: Three Trends to Watch (2026–2031)
Looking ahead, the electronic grade hydrofluoric acid market is likely to be shaped by a small number of powerful forces that connect technology roadmaps, supply assurance priorities, and cost dynamics.
Electronic Grade Phosphoric Acid Market
Trend 1: Purity as a Standard Procurement Criterion, Not a Premium Feature
As advanced semiconductor processes and high-value display and solar processes continue to tighten contamination tolerance, the distinction between grades will increasingly become a baseline procurement requirement rather than a specialty upsell. Suppliers that invest in analytical rigor, lot traceability, and grade-specific process control are likely to capture a larger share of long-cycle agreements. The commercial opportunity lies in building qualification-ready documentation and consistency narratives that reduce buyer risk and accelerate source approval.
PW Consulting Chemical & Energy Research Center
Trend 2: Regionalization of Supply and Logistics-Advantaged Capacity
Demand for proximity, resilience, and predictable delivery is reinforcing regional capacity strategies. Expansion near customer clusters and major transport corridors is likely to remain a strategic priority, particularly where semiconductor manufacturing density is growing. The commercial opportunity is twofold: producers can secure stronger local contracts, and buyers can reduce exposure to long-haul logistics risk. However, regionalization also raises the importance of disciplined capacity planning, because localized supply advantages can be eroded if utilization or input availability becomes unstable.
Trend 3: Cost Volatility Becoming a Core Strategic Management Discipline
Input price movement, logistics shocks, and regulatory interruptions are likely to remain part of the operating environment. The recent pattern of sharp raw material price increases, energy-driven spot offer inflation, and episodic production output changes suggests that cost resilience will be judged as a strategic capability, not merely an accounting outcome. Companies that develop diversified sourcing, scenario-based pricing, and transparent cost communication will be better equipped to sustain customer trust during volatile periods. The associated risk is that firms without flexible cost structures may face margin compression or contract instability when input shocks recur.
Strategic Recommendations for Decision-Makers
Translating market dynamics into action requires differentiated approaches depending on the role a company plays in the value chain.
For Producers and Chemical Manufacturers
Invest in grade differentiation as a commercial moat. The ability to reliably deliver ultra-high-purity and VLSI-grade options, supported by strong quality documentation and stable lot performance, can create defensible positioning in qualification-heavy accounts. Pair this with regional capacity logic that aligns production with major electronics clusters and transport infrastructure, so that supply assurance becomes a visible customer benefit rather than an internal operational metric. Maintain disciplined cost management for upstream inputs and develop transparent pricing mechanisms that preserve trust when raw material conditions shift quickly.
Electronic Grade Nitric Acid Market
For Investors and Strategic Capital Allocators
Focus on business models that combine purity credibility with regional supply relevance and resilient input economics. Assets tied to high-purity electronics demand, especially where localized supply and logistics advantages can be demonstrated, are likely to capture more durable value than undifferentiated volume plays. Monitor the interplay between regional capacity additions, input cost trends such as fluorspar availability and anhydrous HF pricing, and episodic output changes in key production regions, because these factors will influence both top-line growth and margin stability. Prioritize visibility into operating conditions, not just announced capacity, when evaluating companies in this space.
For Procurement and Supply Chain Leaders
Treat purity assurance, regional availability, and cost volatility together rather than as separate sourcing variables. Diversify across proven high-purity suppliers and regionally responsive partners to reduce single-source exposure, and integrate logistics adjacency into supplier evaluation criteria where possible. Build scenario planning into procurement strategy so that rate negotiations and supply agreements can absorb raw material swings, energy-driven freight cost changes, and regulatory interruptions more effectively. In this environment, detailed intelligence on grade availability, regional operating conditions, and input cost direction can materially improve contract structure and risk allocation.
Closing Perspective
The electronic grade hydrofluoric acid market is expanding with a clear underlying logic: advanced electronics processing continues to demand cleaner, more reliable wet chemical supply, while cost, logistics, and regulatory pressures are forcing more sophisticated supply strategies. The combination of steady demand growth, rising purity expectations, and regional supply realignment is creating opportunities for companies that can deliver both technical reliability and supply resilience. At the same time, input volatility and geopolitical exposure remind the market that volume growth alone does not guarantee margin security.
For organizations making sourcing, production, or investment decisions in this space, the most valuable next step is to move from broad market direction to granular visibility: grade-level demand shifts, regional capacity and operating conditions, raw material cost trajectories, and the strategic positioning of key suppliers. Detailed segmentation data, supplier-level assessments, and customized scenario planning can turn these broad trends into actionable, risk-adjusted decisions.
For detailed analysis of this topic, please visit the official page: Electronic Grade Hydrofluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com