

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electrical Insulation Paper Market: 3.9% CAGR Growth and Strategic Shifts Through 2032

The Electrical Insulation Paper Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
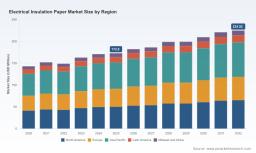
The electrical insulation paper market operates at the intersection of grid modernization, materials science, and industrial infrastructure. Valued at approximately 172.8 million USD in 2025, the sector has demonstrated a measured but steady trajectory over the past five years, recovering from a temporary contraction in 2022 before expanding to its current baseline. Looking ahead to 2032, the market is projected to reach roughly 224.9 million USD, reflecting a compound annual growth rate of 3.9 percent. This expansion is not merely a function of incremental demand; it signals a structural realignment in how electrical assets are designed, maintained, and decommissioned across mature and emerging economies alike. For executives and investors, the growth story masks a more nuanced reality: value creation will increasingly depend on technological differentiation, supply-chain resilience, and alignment with evolving regulatory frameworks.
The regional distribution of demand underscores this complexity. North America, Europe, and the Asia Pacific region collectively account for the largest share of consumption, with Asia Pacific standing out as both a volume driver and an innovation incubator. Latin America and the Middle East and Africa contribute smaller but growing portions, often tied to localized grid expansion, renewable integration, and aging asset replacement programs. Rather than treating geography as a static backdrop, it is more useful to view regional dynamics as distinct demand engines with different pacing, procurement cycles, and compliance requirements.
Market Snapshot and Core Challenges
The market's five-year arc from 2020 to 2025 reveals resilience in the face of supply disruptions and shifting project timelines. After reaching 142.8 million USD in 2020, the sector expanded to 152.1 million USD in 2021, experienced a brief pullback to 148.9 million USD in 2022, and then accelerated through 2023 and 2024 before stabilizing near 170.8 million USD and settling at 172.8 million USD in 2025. This pattern reflects the interplay of delayed infrastructure orders, inventory normalization, and the gradual ramp-up of high-voltage and distribution projects. The forward trajectory through 2032 suggests that growth will be incremental rather than explosive, with annual gains becoming more pronounced as capital expenditure cycles mature and replacement demand gains momentum.
Within this macro framework, several challenges and inflection points are reshaping how participants position themselves:
- Raw-material volatility and cost asymmetry : Cellulose-based insulation materials remain highly sensitive to pulp pricing and processing inputs. Recent cycles have shown cellulose pulp costs rising by 9–14 percent in certain production periods, contributing to roughly 28 percent fluctuation in overall production costs for insulation paper manufacturers. This volatility compresses margins for suppliers that lack long-term contract structures or value-added differentiation, while simultaneously creating pricing power for manufacturers that can secure stable feedstock or offer performance-guaranteed specifications.
- Regulatory and compliance pressure on processing : Environmental regulations governing emissions, wastewater, and chemical handling during paper processing are tightening across multiple jurisdictions. Producers operating in regulated regions face compliance costs estimated at 6–11 percent of operational expenditure. These requirements are not merely cost centers; they increasingly function as market-access gatekeepers, influencing procurement decisions for utilities and OEMs that must document the sustainability and compliance profile of their supply chains.
- Technology transition and specification shifts : The insulation paper segment is undergoing a quiet but meaningful shift in performance expectations. End users are demanding better thermal stability, longer service life, and more predictable behavior under load cycling and high-voltage stress. This creates a bifurcated market: commoditized grades compete primarily on price and availability, while engineered grades with thermal upgrading, controlled creping, and specialized coatings command premium positioning and longer-term contracts.
These challenges are not isolated. They interact with one another in ways that determine which players can scale profitably and which are forced into cyclical pricing battles. The organizations that navigate this environment effectively treat raw-material strategy, regulatory readiness, and product engineering as a single integrated capability rather than separate functional concerns.
Key Demand Drivers Behind Market Evolution
Understanding why the electrical insulation paper market is moving requires looking beyond top-line growth to the forces shaping procurement behavior, product design, and supply economics. Four drivers stand out as particularly decisive over the next several years.
Technological Innovation and Material Performance
Innovation in insulation paper is shifting from incremental grade improvements to system-level performance optimization. Manufacturers are investing in thermal upgrading technologies, controlled creping, and coating processes that enhance dielectric strength, reduce moisture absorption, and improve mechanical integrity under prolonged thermal stress. A notable example of this direction appeared in March 2026, when Weidmann Electrical Technology AG published technical guidance focused on optimizing transformer insulation systems for improved performance, cost efficiency, and supply reliability. Rather than presenting a single product launch, the release reflected a broader industry pivot toward helping customers design insulation systems that balance longevity, operational flexibility, and total cost of ownership.
This matters because insulation paper is increasingly evaluated not as a standalone material but as part of a transformer or cable insulation architecture. Buyers are more willing to pay for grades that reduce maintenance intervals, support higher loading conditions, and provide more consistent behavior across temperature and humidity ranges. For producers, the implication is clear: value is migrating toward engineered solutions and technical services, while undifferentiated commodity grades face persistent margin pressure.
Policy and Regulatory Environment
Policy frameworks are playing a larger role in shaping demand timing, product eligibility, and supplier qualification. Environmental regulations are raising the bar for emissions and processing standards, while grid policy in many regions is accelerating modernization programs that indirectly increase demand for reliable insulation materials. Utilities and equipment manufacturers are incorporating supplier compliance records into their procurement criteria, especially where public funding, environmental disclosures, or long-term service agreements are involved.
The compliance dimension also affects innovation pathways. Materials and processes that can demonstrate lower environmental impact, recyclable or sustainably sourced fiber inputs, and reduced processing emissions are becoming more relevant in bids and specification documents. This does not mean that regulation is a pure constraint; it also creates a qualification barrier that can protect established players with robust compliance infrastructure and penalize smaller competitors that struggle to absorb the operational expenditure associated with emissions control and documentation.
Electrical Insulation Tape Market
Demand-Side Behavior and Infrastructure Priorities
On the demand side, procurement behavior is being reshaped by asset age profiles, load growth, and the need to reduce outage risk. Power transformers and distribution transformers remain central to the insulation paper market, reflecting the continued reliance on transformer-based grid architecture even as alternative equipment formats evolve. At the same time, cable and wire applications, motors and generators, and capacitor-related uses contribute meaningful demand, each with its own specification requirements and replacement cycles.
A broader shift is also underway in how end users evaluate reliability. Rather than focus exclusively on lowest initial material cost, many buyers are weighing insulation performance against the financial and operational consequences of failure, especially in networks where outage costs are high or where renewable integration increases loading variability. This behavioral change favors suppliers that can provide consistency, traceability, and technical support, and it encourages longer-term purchasing relationships rather than spot-market procurement.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure Dynamics
The cost structure of insulation paper production is tightly linked to kraft pulp availability, processing complexity, and logistics. Kraft pulp remains the primary raw material for cellulose-based electrical insulation paper, and its properties directly influence dielectric performance and mechanical durability. Sustainability perceptions around fiber sourcing can also influence buyer preferences, particularly where utilities or OEMs emphasize responsible procurement in their public commitments.
Recent pricing dynamics illustrate the sensitivity of the sector. Kraft pulp serves as the foundational input, and price movements can ripple quickly through producer cost models. For example, kraft pulp prices were recorded at 4,824 CNY/T on June 5, 2026, down 0.25 percent from the prior day and 23 percent over the preceding month, highlighting how quickly input costs can shift within a single production cycle. When combined with the broader pattern of cellulose-pulp price increases of 9–14 percent in recent cycles and the associated 28 percent fluctuation in production costs, the message is unambiguous: cost management is now a strategic capability, not a tactical accounting task.
Insulating Oil Market
Suppliers are responding by combining feedstock security, product mix optimization, and engineering differentiation. The most resilient operators are those that can maintain stable input access while directing more of their manufacturing capability toward grades that carry higher performance value and more defensible pricing.
Competitive Landscape and Leading Strategies
The competitive structure of the electrical insulation paper market is moderately concentrated, with the top three players accounting for roughly 35 percent of market share and the top five reaching about 42 percent. This concentration level suggests that while established manufacturers hold significant influence, there is still room for regional specialists, niche grade providers, and technology-focused entrants to compete on specification, service, or local responsiveness.
Strategic Positioning of Key Players
The market's leading participants differentiate themselves through a combination of material heritage, processing capability, product range, and technical engagement with customers.
- Weidmann Electrical Technology AG , headquartered in Rapperswil, Switzerland, is positioned around high-quality kraft flat paper and presspaper made from 100 percent electrical-grade kraft wood pulp. Its processing capabilities, including creping, coating, slitting, and transformer-focused processing, support a product portfolio aimed at performance-sensitive applications. The company's March 2026 technical guidance on optimizing transformer insulation systems highlights an approach that extends beyond material supply into system-level optimization, cost efficiency, and supply reliability. This kind of technical engagement helps anchor long-term relationships with customers that value engineering support as much as material consistency.
- Ahlstrom-Munksjö Oyj , based in Espoo, Finland, offers electrotechnical kraft insulation paper under the Elektro-Tek brand, serving power transformers, instrument transformers, and high-voltage cables. Its portfolio spans plain and creped grades, with thermal upgrading capabilities under Thermotrans. The breadth of its electrotechnical offering, combined with brand recognition in engineered paper solutions, gives the company a strong platform in segments where specification accuracy and thermal performance are critical. Its scale and material expertise also support consistent supply and documentation practices that are increasingly important to regulated buyers.
- Krempel GmbH , located in Vaihingen/Enz, Germany, leads in electrical insulation materials including kraft papers and composites for energy-sector transformers and components. Its positioning emphasizes an integrated view of insulation materials beyond paper alone, which can be attractive to customers seeking coordinated solutions across transformer and component applications. In a market where material interaction and system reliability matter, a composite-aware portfolio can support stronger specification influence and deeper engineering partnerships.
- Cottrell Paper Company, Inc. , a family-owned manufacturer in Rock City Falls, New York, has produced high-grade electrical insulating papers and specialty materials since 1926, including copaco and glazed variants for transformers and motors. Its long operational history and family-owned structure contribute to a positioning centered on continuity, specialty grade depth, and relationship-based service. For certain regional and application-specific buyers, this profile can be a meaningful differentiator, particularly where supply continuity and product familiarity are valued alongside technical performance.
How the Competitive Landscape Is Evolving
The market is not static. Several patterns are shaping its evolution:
- Consolidation pressure on scale and compliance : Larger producers benefit from broader product portfolios, stronger compliance infrastructure, and greater ability to absorb raw-material volatility. This encourages gradual consolidation or partnership activity, especially where feedstock access, technical service capacity, or regional distribution networks need reinforcement.
- Differentiation through engineered grades : As commoditized segments face pricing pressure, competition increasingly centers on thermal upgrading, grade consistency, coating technology, and technical support. Players that can validate performance claims and reduce customer risk are better positioned to maintain margins and win specification decisions.
- Regional and specialty niches remain viable : Despite concentration at the top, the market still rewards localized responsiveness, long-standing customer relationships, and specialized grades for motors, capacitors, and cable applications. New entrants and smaller manufacturers can compete by serving underserved specifications or by offering flexible service models that larger players may not prioritize in every region.
Forward-Looking Trends and Commercial Implications
If current dynamics persist, three trends are likely to shape the market over the next three to five years.
Trend One: Performance Specifications Will Become More System-Centric
Insulation paper will increasingly be evaluated in the context of complete insulation systems rather than as a standalone commodity. Thermal upgrading, controlled processing, and application-specific grading will matter more as utilities and OEMs seek to manage load cycling, extend asset life, and reduce failure risk. The commercial opportunity lies in helping customers match material grades to actual operating conditions, which can justify premium pricing and create stickier relationships. The risk is that suppliers who cannot demonstrate measurable performance benefits may be forced into price competition or replaced by alternatives that offer clearer technical value.
Trend Two: Cost and Compliance Will Function as Strategic Filters
Raw-material volatility and regulatory compliance costs will continue to influence both supplier survival and buyer selection. Producers that can stabilize input exposure, optimize product mix, and document compliance with confidence will be better placed to protect margins and win long-term contracts. The opportunity is to treat these factors as part of a broader value proposition rather than as overhead. The risk is that short-term pricing pressure leads to underinvestment in compliance and quality systems, which can erode trust and restrict access to regulated or quality-sensitive markets over time.
Trend Three: Regional Demand Will Diverge in Pace and Preference
Growth will not be uniform across regions. Some markets will be driven by grid expansion and new asset installation, while others will be shaped by replacement cycles, load growth, and selective modernization. Procurement preferences will also diverge, with some regions emphasizing price competitiveness and others prioritizing reliability, traceability, and compliance documentation. This creates opportunities for suppliers that can tailor product offerings, service models, and commercial terms to regional realities. The risk is that a one-size-fits-all strategy leaves a company over-exposed in slower-growing markets while under-serving faster-growing ones.
Strategic Recommendations for Decision Makers
For manufacturers, investors, and procurement leaders, the practical question is how to translate these dynamics into action. A few strategic priorities stand out.
For Manufacturers and Suppliers
- Shift value capture toward engineered solutions : Reduce reliance on undifferentiated commodity grades by expanding thermal upgrading, coating, and custom processing capabilities. Pair product innovation with technical support that helps customers optimize insulation system design, because performance validation is becoming a key determinant of specification wins.
- Build feedstock and cost resilience : Lock in stable input access where possible, hedge exposure to pulp price swings, and use product mix to balance margin variability. Cost volatility is large enough that manufacturers without a clear feedstock and pricing strategy will find it difficult to sustain profitability through cyclical swings.
- Invest in compliance as market access, not just cost control : Treat emissions, processing, and documentation requirements as part of the competitive moat. Buyers in regulated environments increasingly use compliance status as a qualification filter, so robust compliance capability can open doors even when price alone is not the deciding factor.
For Investors
- Focus on differentiation and system-level capability : Evaluate companies not only on volume and footprint but also on technical engagement, engineered product depth, and the ability to reduce customer risk. In a market where performance expectations are rising, these qualities are more likely to support durable pricing than pure scale alone.
- Monitor feedstock exposure and margin structure : Because production costs can fluctuate significantly with cellulose pulp pricing, investor diligence should include how a company manages input volatility, whether it has contract structures that stabilize costs, and how much of its revenue comes from premium grades versus commoditized segments.
- Watch regulatory-driven consolidation signals : Compliance costs and qualification requirements can advantage larger, better-resourced players. Investment theses should consider whether a target is positioned to gain from consolidation or whether it depends on a niche that remains defensible despite increasing scale and regulatory pressure.
For Procurement and End-User Decision Makers
- Evaluate total cost of ownership rather than material price alone : Insulation paper choices affect maintenance intervals, thermal behavior, and asset reliability. Procurement processes that weigh lifecycle risk, specification accuracy, and supplier technical support are better aligned with long-term operational goals than those focused narrowly on initial purchase cost.
- Require documentation and traceability : Given tightening compliance expectations and the importance of responsible sourcing, buyers should seek clear documentation on material origin, processing standards, and performance validation. This not only supports regulatory and sustainability objectives but also reduces uncertainty in storage, handling, and application.
- Plan for specification evolution : As insulation requirements become more system-centric, procurement teams should anticipate changes in grade selection, thermal upgrading needs, and supplier collaboration. Early engagement with suppliers on performance targets and operating conditions can prevent mismatches and improve long-term supply reliability.
The electrical insulation paper market is entering a phase where growth, competition, and value creation are increasingly determined by technical differentiation, cost resilience, and regulatory readiness. The broad trajectory through 2032 points to steady expansion, but the real strategic prize will go to organizations that can align product engineering, supply-chain planning, and compliance capability with the evolving expectations of utilities, OEMs, and regional project markets. For decision makers seeking a more granular view of segmentations, regional dynamics, and actionable commercial scenarios, the full PW Consulting study provides deeper quantitative breakdowns and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrical Insulation Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com