

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Eco-Friendly Beneficiation Reagents Market: Why Biodegradable Isolation From 2020–2032 Forecasts a 6.5% Growth Path

Navigating the Green Shift: Strategic Insights for the Eco-friendly Beneficiation Reagents Market
Market Landscape and Core Challenges
The global market for eco-friendly beneficiation reagents has entered a phase of sustained expansion, reflecting the mining sector’s broader transition toward lower-impact processing. Over the 2020–2025 period, the industry experienced consistent revenue growth, propelled by incremental adoption of bio-based collectors, non-toxic frothers, and organic depressants. Current trajectories project steady compounding growth well into the early 2030s, signaling that sustainability is no longer a peripheral consideration but a structural requirement for mineral processing operations. The market’s evolution mirrors a broader industrial pivot: rather than treating environmental compliance as a cost center, leading operators increasingly view green reagents as enablers of process efficiency, tailings reduction, and long-term operational license continuity.
Despite this momentum, the industry faces a tightly coupled set of challenges that will shape competitive outcomes over the next decade. First, performance parity remains a persistent tension. Traditional reagents such as xanthates and fossil-derived collectors have decades of operational history, well-understood kinetics, and predictable cost structures. Replacing them with biodegradable collectors or bio-based pH modifiers often requires re-engineering flotation circuits, recalibrating dosage regimes, and retraining plant personnel. For many mid-tier and junior mining companies, the perceived operational risk of switching formulations outweighs the environmental benefits, especially when ore bodies are complex or recovery margins are thin.
Second, the regulatory environment is accelerating adoption but fragmenting demand signals across jurisdictions. Environmental discharge limits, aquatic toxicity standards, and corporate sustainability commitments are pushing procurement teams toward lower-toxicity alternatives. However, regulatory timelines, testing protocols, and compliance expectations differ markedly between established mining regions and emerging resource frontiers. This creates a dual challenge for reagent manufacturers: products must satisfy stringent European and North American chemical safety expectations while remaining cost-competitive and operationally practical in markets where processing infrastructure and waste management capacity vary widely.
General Reagents Market
Third, the supply chain for bio-based feedstocks introduces a new dimension of volatility. Renewable raw materials, including plant-derived oils, lignin-based intermediates, and fermentation-derived biosurfactants, offer compelling environmental profiles. Yet their availability, batch consistency, and pricing are subject to agricultural cycles, logistics constraints, and competing demand from other industrial sectors. For flotation chemical producers, building reliable bio-feedstock pipelines is as critical as formulation innovation. Companies that fail to secure scalable, traceable, and cost-stable inputs risk losing ground to competitors who can deliver consistently performing green reagents without supply disruptions.
Together, these dynamics suggest that the market is moving from early experimentation toward commercial validation. The question is no longer whether eco-friendly reagents will gain share, but which players can deliver the right combination of performance, regulatory alignment, supply reliability, and total cost of ownership.
Key Drivers Reshaping the Market
The expansion of eco-friendly beneficiation reagents is not being driven by a single force. It is the result of overlapping technological, regulatory, demand-side, and supply-side shifts that reinforce one another. Understanding these drivers is essential for companies deciding where to invest, what capabilities to build, and how to position products for different mining segments and geographies.
Technology Innovation and Formulation Breakthroughs
Advancements in green flotation chemistry are steadily narrowing the performance gap with conventional reagents. Research and commercial development increasingly focus on bio-based collectors, safer frothers, and organic depressants that can operate effectively in complex ore environments. Recent academic and industry reviews have introduced classification frameworks for green reagents based on biobased origin, biodegradability, and safer chemical profiles, providing a common language for evaluating alternatives beyond simple toxicity comparisons. This kind of structured assessment is helping procurement teams and process engineers move from qualitative sustainability claims to more rigorous performance benchmarking.
On the commercial side, major reagent developers are showcasing products aimed at both environmental improvement and process efficiency. Advanced collectors and energy-efficient coarse particle flotation formulations are being positioned to improve recovery while reducing energy intensity, particularly for base metals, lithium, nickel, and other minerals tied to the energy transition. At the same time, manufacturers are launching high-performance reagents for industrial minerals and phosphate processing that target higher recovery rates and lower dose requirements. These innovations matter because they reframe green reagents as dual-purpose tools: they address compliance and ESG objectives while also supporting recovery, throughput, and reagent economics.
Policy, Regulation, and the Compliance Accelerator
Regulatory pressure continues to be one of the most powerful catalysts for adoption. Stricter environmental rules and corporate sustainability targets are driving interest in biodegradable, low-toxicity, and bio-based flotation chemicals designed to reduce aquatic toxicity and meet discharge limits. In parallel, evolving chemical safety frameworks and regulatory support for low-toxicity alternatives are encouraging innovation in froth flotation chemistry. The practical effect is that compliance is increasingly shaping formulation priorities, not merely end-of-pipe waste management.
For mining companies, this regulatory momentum translates into procurement shifts and process redesign decisions. Reagents with improved toxicological profiles can reduce permitting friction, simplify wastewater handling, and support broader corporate decarbonization and biodiversity commitments. For reagent suppliers, the regulatory direction rewards products that can demonstrate measurable safety and environmental advantages while maintaining process reliability. The companies that benefit most are those able to align their innovation pipelines with emerging compliance expectations without over-indexing on regional regulatory niches that may not scale.
Demand-Side Shifts Across Mining Business Models
Demand for sustainable beneficiation reagents is being shaped by changing mining business models, ore quality trends, and investor expectations. Lower-grade resources and more complex ore bodies are prompting operators to seek reagents that improve selectivity and recovery without escalating chemical consumption or environmental burden. At the same time, precious metals and base metals mining operations face mounting scrutiny from investors, off-takers, and community stakeholders, all of whom are paying closer attention to water use, chemical discharge, and tailings footprints.
PW Consulting Chemical & Energy Research Center
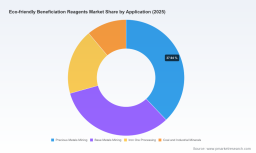
This demand-side evolution is especially visible in application areas where processing efficiency and environmental risk intersect. Precious metals processing has long been a focus for non-toxic leaching alternatives, while base metals flotation continues to attract interest in collector and frother innovations that can improve recovery and reduce reliance on higher-impact chemistry. Iron ore processing and industrial minerals operations are also part of the equation, particularly where beneficiation decisions influence downstream competitiveness, residue management, and reputational exposure. The overarching trend is that buyers are increasingly evaluating reagents through a total-cost lens that includes compliance risk, operational flexibility, and ESG alignment rather than short-term price alone.
Supply Chain, Cost Structure, and Feedstock Realism
The commercial viability of eco-friendly reagents depends heavily on supply chain maturity and cost structure. Bio-based feedstocks and renewable intermediates can offer strong environmental credentials, but they also introduce variables that traditional chemical supply chains were not designed to manage. Feedstock availability, conversion yields, transportation costs, and supplier concentration can all affect final pricing and consistency. Lignin-based reagents derived from forest biomass and other renewable inputs illustrate both the promise and the complexity of this transition: they can provide biodegradable, non-toxic alternatives for sulfide ore flotation, but scaling them into routine plant use requires dependable sourcing and process validation.
Cost dynamics are further complicated by the need to justify switch-over expenses. Even when a green reagent offers attractive environmental attributes, mines will assess whether it can match recovery, reduce downtime, or lower downstream treatment costs. If the total operating impact is favorable, adoption accelerates. If the switch creates uncertainty in recovery or increases reagent consumption, adoption slows. This reality means that supply chain strategy and product design must advance together. Manufacturers that can stabilize feedstock access, control formulation variability, and demonstrate reliable plant performance are better positioned to convert regulatory and ESG interest into durable demand.
Competitive Landscape and Leading Strategies
The competitive picture in eco-friendly beneficiation reagents is defined by a mix of established chemical leaders, specialized innovators, and regional players targeting specific processing pain points. The market remains moderately concentrated, which gives larger players advantages in formulation scale, application support, and global distribution, while also leaving room for focused entrants with strong technical differentiation. The strategic question for incumbents is how to convert broad portfolios into credible green alternatives; for newer entrants, the challenge is how to prove performance and secure long-term supply commitments.
Worldwide Eco-Friendly Bitumen Market
Incumbents Building on Portfolio Breadth
Large diversified chemical companies are leveraging existing mining solutions portfolios to develop more sustainable flotation products. Nouryon, for example, offers a wide range of flotation collectors for minerals such as phosphate, iron ore, potash, and calcite, with an emphasis on reducing environmental impacts through product reformulation, including efforts to remove certain legacy surfactants and develop lower-impact options. Clariant has similarly built a mining solutions platform around collectors and frothers for sulfide ores, iron ore, phosphate, potash, and a growing set of transition minerals, with a focus on safer alternatives to conventional chemistry, coarse particle flotation, and reduced environmental footprint.
BASF and Syensqo reflect a comparable approach from complementary angles. BASF develops collectors, frothers, and modifiers designed to improve recovery and reduce dose rates while improving safety profiles and incorporating biodegradable options where feasible. Syensqo supports base and precious metals processing with flotation collectors, promoters, and frothers intended to improve sustainability profiles relative to more traditional chemistries while enabling more efficient mineral processing. Arkema, including its associated mineral processing assets, emphasizes enhanced selectivity and recovery through tailored depressants, collectors, frothers, and related products for phosphate, silica sand, iron beneficiation, and industrial minerals.
What distinguishes these players is not simply product volume, but the ability to pair formulation development with application engineering, testing support, and global reach. Their strategies typically center on offering multiple pathways for customers: improving existing circuits with better-performing variants, reducing chemical intensity, and transitioning to greener chemistries without abandoning process reliability. This breadth is a meaningful advantage when mines want to trial alternatives gradually rather than undertake full-scale re-engineering.
Specialized Players Targeting High-Value Problems
At the other end of the competitive spectrum, specialized companies are focusing on discrete but commercially important challenges. Several firms are developing cyanide-replacement leaching reagents for precious metals processing, aiming to provide low-toxicity, non-polluting alternatives with comparable or improved recovery in heap leaching, CIP, and CIL operations. This segment has attracted sustained attention because it directly addresses both environmental risk and process continuity in gold ore beneficiation.
Other innovators are pursuing more fundamental chemistry shifts. Biosurfactant-based additives and fermentation-derived solutions are being explored as ESG-friendly reagents to improve recovery from low-grade ores and tailings. These approaches can offer a different value proposition from conventional chemical formulations: rather than simply substituting one collector or frother for another, they may help unlock recovery from materials that are economically marginal under traditional processing conditions. If scaled effectively, such technologies could expand the economic horizon for both primary extraction and tailings reprocessing.
Market Evolution: Integration, Differentiation, and New Entrants
The competitive landscape appears to be evolving along several lines. First, incumbents with broad reagent portfolios are likely to continue consolidating technical services and application data, using their scale to reduce customer switching costs and accelerate trial-to-commercial pathways. Second, differentiation will increasingly depend on demonstrable attributes: biodegradability, safer chemical handling, reduced dose rates, improved recovery at lower energy intensity, and stronger environmental profiles. Products that can make these claims credible, backed by consistent supply and application evidence, will gain an edge over those competing primarily on price or general sustainability language.
Third, regional specialization remains important. Asia Pacific continues to represent a substantial revenue base, reflecting the scale and diversity of mining and mineral processing activity in the region. Latin America also represents a significant share of market value, driven by active mining economies and expanding mineral processing demand. North America, the Middle East and Africa, and Europe contribute additional, more varied demand profiles shaped by local mineral mixes, regulatory conditions, and processing infrastructure. Companies operating across these regions must navigate different ore types, operating practices, and compliance expectations, which makes localized technical support and flexible product design increasingly valuable.
Finally, the sector is likely to see continued entry by firms targeting specific gaps, such as cyanide alternatives, lignin-based collectors, or biosurfactant additives. Some of these entrants may remain niche players; others may become acquisition targets if their technologies prove scalable and align with the strategic priorities of larger chemical suppliers. The broader trajectory points toward a market where credibility, repeatability, and supply resilience matter as much as formulation novelty.
Future Trends and Commercial Implications
Looking ahead, three interconnected trends are likely to shape the eco-friendly beneficiation reagents market over the next three to five years.
The first trend is the gradual mainstreaming of green reagents in selective applications rather than blanket substitution. Adoption will likely accelerate where the value case is clearest: precious metals leaching substitutions, flotation circuits facing stringent discharge constraints, and processing routes where improved selectivity can reduce downstream costs or tailings burden. In other settings, adoption may proceed more slowly, especially where ore complexity or circuit design makes reformulation riskier. The commercial opportunity lies in targeting the right applications first and building proven performance records that can later be extended to adjacent use cases.
The second trend is deeper integration between formulation innovation and process optimization. Green reagents will increasingly be evaluated not only for their chemical profile, but also for how they interact with recovery targets, energy consumption, water management, and tailings behavior. Coarse particle flotation, lower dose regimes, and improved selectivity are all examples of directions that can blur the line between sustainability and operational efficiency. Companies that position products as part of a broader process improvement strategy, rather than as stand-alone chemical purchases, are likely to win stronger customer commitment.
The third trend is the growing importance of feedstock strategy and lifecycle credibility. As bio-based and biodegradable options become more prominent, procurement and technical teams will pay closer attention to raw material origins, supply consistency, and end-of-life behavior. This creates an opportunity for suppliers that can document renewable sourcing, maintain reliable production, and provide transparent performance data. It also introduces risk for players that depend on volatile feedstocks or cannot guarantee consistent quality across batches.
These trends collectively point to a market that will reward differentiation grounded in real operating value. The upside is significant for suppliers that can demonstrably improve recovery, reduce environmental exposure, and stabilize supply. The downside risk lies in over-promising on sustainability without delivering consistent performance, or in building business models around feedstocks and regulations that may shift faster than commercialization timelines.
Action Priorities for Decision Makers
For manufacturers and product developers, the immediate priority is to align formulation roadmaps with the applications where performance, compliance, and economics reinforce each other. Investment should favor chemistries and delivery models that reduce dose requirements, support safer handling, and can be validated in real flotation or leaching conditions. Equally important is securing supply chains for renewable or lower-impact feedstocks so that product claims can be sustained at commercial scale.
For investors, the most relevant signal is differentiation backed by repeatable customer outcomes. Opportunity exists in companies with strong application data, credible feedstock strategies, and clear relevance to high-stakes segments such as precious metals leaching, base metals flotation, and processing of ores tied to the energy transition. Caution is warranted where growth narratives rely primarily on regulatory optimism or broad sustainability messaging without evidence of process-level benefit and supply resilience.
For procurement and operations leaders in mining and mineral processing, the strategic task is to move beyond simple product substitution and evaluate green reagents within the context of circuit performance, water and tailings management, and long-term permitting exposure. Piloting should be structured to measure recovery, reagent consumption, handling safety, and downstream implications, not just environmental attributes. A disciplined evaluation framework can reduce switching risk while identifying reagent strategies that support both operational and sustainability goals.
Organizations seeking a more granular view of segmentation, regional demand patterns, application-level dynamics, and competitive positioning can benefit from a deeper benchmarking exercise. Detailed market data and customized strategic support are valuable for translating these high-level trends into concrete sourcing, investment, and product decisions. Readers looking for a fuller breakdown of market sizing, segmentation splits, and leading-company strategies are encouraged to consult the comprehensive PW Consulting research report for additional detail and tailored guidance.
For detailed analysis of this topic, please visit the official page: Eco-friendly Beneficiation Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com