

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Antioxidants Market 2026: Why 6.8% CAGR and Natural Shifts Change Everything

The Antioxidants Market at a Crossroads: Strategic Shifts and Commercial Opportunities Through 2032
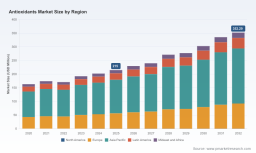
The global antioxidants market has matured into a structurally complex industry where growth is no longer a simple function of volume expansion. Historical performance from 2020 through 2025 shows a market that navigated pandemic-era disruptions, supply chain recalibrations, and shifting downstream demand, while forecasted trajectory from 2026 through 2032 points to a steady but uneven expansion at a CAGR of 6.8 percent. Revenue is projected to move from the 215 million USD range in the base year toward the mid-300 million USD mark by the end of the forecast horizon, reflecting incremental gains rather than explosive jumps. This growth profile underscores an industry transitioning from broad-scale proliferation to targeted, value-driven deployment across polymers, personal care, food systems, and industrial additives.
Yet the headline trajectory masks several friction points that executives and investors must weigh carefully. Input cost volatility, particularly in petrochemical-linked feedstocks, continues to compress margins for manufacturers that rely on fixed-price contracts or thin operational buffers. Geopolitical instability, logistics bottlenecks, and energy market fluctuations have repeatedly forced portfolio-wide pricing adjustments, signaling that cost pass-through mechanisms are becoming a permanent feature of the operating environment rather than a cyclical anomaly. Regulatory divergence across regions adds another layer of complexity, as food-contact approvals, safety profiles for specific polymer applications, and stabilizer classifications vary widely, forcing companies to navigate fragmented compliance pathways while maintaining consistent quality standards. A third challenge lies in the tension between synthetic and natural formulations. While synthetic antioxidants continue to dominate in performance-critical industrial and polymer applications, natural alternatives are gaining traction in consumer-facing segments, creating a dual-track market where formulation strategy, sourcing resilience, and certification readiness determine competitive positioning.
For strategic decision-makers, these dynamics translate into a clear operational imperative: growth must be engineered through supply chain agility, formulation differentiation, and regulatory foresight rather than assumed from macro expansion alone. Companies that treat antioxidant procurement and production as a static cost line will face margin erosion and supply risk, while those that embed flexibility into sourcing, pricing, and application development will be better positioned to capture the relatively modest but durable expansion projected over the next several years.
Worldwide Polyolefin Antioxidants Market
Key Drivers Reshaping the Antioxidants Landscape
Technological Innovation and Formulation Breakthroughs
Product innovation remains one of the strongest levers for market evolution, particularly where performance requirements intersect with safety and regulatory constraints. Recent introductions of hindered phenolic and phosphite antioxidants with enhanced safety profiles demonstrate how formulation science is moving beyond basic stabilization toward application-specific risk mitigation. In spandex and rubber segments, for example, newer phenolic variants are being designed to balance oxidative protection with handling safety and processing compatibility, enabling formulators to meet stricter workplace and end-use standards without sacrificing material longevity. Phosphite antioxidants approved for food contact across dozens of countries illustrate a parallel trend: regulatory acceptance is expanding the addressable market for high-purity stabilizers that can bridge industrial performance with consumer safety expectations.
From a commercial standpoint, these breakthroughs reward companies that invest in application engineering and technical service capabilities. Antioxidants are increasingly evaluated not only by oxidation inhibition metrics but also by compatibility with complex polymer blends, processing temperatures, and downstream regulatory regimes. Businesses that embed formulation expertise into customer engagements can command stronger positioning, reduce substitution risk, and unlock premium segments where reliability and compliance justify differentiated pricing.
Policy and Regulatory Environment as a Market Shaper
Regulatory dynamics are no longer a background compliance function; they are actively reshaping capacity deployment, product roadmaps, and geographic allocation. Expanded production capacity for specialized stabilizers in China reflects how regulatory and market access considerations influence manufacturing footprint decisions. At the same time, approvals that allow specific antioxidants to be used in food-contact contexts across a broad set of countries create new commercial pathways, but only for suppliers that can document purity, traceability, and consistent quality under rigorous audit conditions.
The regulatory environment also amplifies the importance of regional differentiation. Markets with stringent food-contact, cosmetic, and industrial chemical regulations tend to reward manufacturers with established documentation practices and localized technical support, while faster-growing regions may prioritize cost efficiency and supply reliability. Executives should therefore view regulatory strategy as a core component of market entry and expansion planning, not merely a legal checklist. Companies that align product portfolios with the most demanding standards early often gain a durable advantage when those standards become reference points elsewhere.
Demand-Side Shifts Across Consumer and Industrial Channels
Demand patterns are being shaped by both consumer behavior and industrial engineering requirements, creating divergent growth vectors within the same market. In food and beverage applications, consumer preferences for cleaner labels and longer shelf stability continue to drive interest in antioxidants that can deliver protection without complicating ingredient declarations. In personal care and pharmaceutical contexts, the emphasis shifts toward safety, stability, and compatibility with sensitive formulations, encouraging adoption of antioxidants that meet stringent handling and purity expectations. Meanwhile, industrial demand in plastics, rubber, and lubricant applications remains anchored by durability, processing efficiency, and total cost of ownership rather than label appeal alone.
This dual demand structure means that market growth is unlikely to be uniform across segments. Consumer-facing categories may experience more visible enthusiasm for natural or low-risk alternatives, while industrial categories will continue to prioritize performance consistency and supply security. For producers and buyers alike, the strategic lesson is to avoid treating the antioxidants market as a monolith. Segment-level positioning, technical validation, and customer engagement models must be calibrated to the decision criteria that matter most in each channel.
Supply Chain Reconfiguration and Cost Structure Pressure
Cost structures in the antioxidants market are increasingly influenced by feedstock dynamics, energy pricing, and logistics exposure. Phenol and acetone price trends in early 2026 highlighted how upstream benzene and propylene-linked feedstocks can transmit cost pressure quickly through antioxidant production pathways. When combined with energy and freight volatility, these input dynamics create an environment where cost management becomes a strategic capability rather than a back-office function.
Recent pricing adjustments across major portfolios underscore how suppliers are responding to these pressures. Price actions have been framed not as opportunistic increases but as responses to cumulative cost escalation in raw materials, energy, and logistics. For downstream buyers, this reality necessitates more resilient procurement strategies: diversified sourcing, longer-term contractual flexibility, and closer alignment with suppliers that can demonstrate transparent cost pass-through logic and reliable production continuity. For manufacturers, the opportunity lies in improving operational efficiency, optimizing feedstock integration, and pursuing geographic diversification that reduces exposure to single-region disruptions.
PW Consulting Chemical & Energy Research Center
Competitive Landscape and Leader Strategies
Strategic Positioning Among Established Players
The market features a concentrated group of multi-application suppliers with global manufacturing footprints, technical service depth, and broad antioxidant portfolios. Leading companies are positioned around several differentiating strengths: portfolio breadth spanning phenolic, aminic, and phosphite chemistries; geographic manufacturing diversity that supports supply resilience; and application-specific expertise that connects stabilization performance to end-use requirements. In plastics, lubricants, polymers, rubber, and specialty coatings, the most effective competitors are those that can pair chemical capability with practical processing knowledge, enabling customers to integrate antioxidants into complex formulations with minimal trial-and-error.
Geographic diversification is particularly significant. Manufacturing expansion in regions such as Mexico and Antwerp, alongside specialized capacity additions in Asia, reflects a deliberate effort to balance proximity to key demand centers with supply chain redundancy. This footprint strategy matters because antioxidants are often needed in consistent quality and reliable volume by downstream manufacturers who cannot afford extended downtime or formulation variability. Suppliers that can offer both technical credibility and logistical reliability tend to secure more defensible relationships in performance-driven applications.
Differentiation Through Portfolio and Compliance Depth
Competitive advantage is increasingly defined by how well companies align chemistry, compliance, and commercial execution. Some suppliers emphasize higher-purity, food-contact-ready stabilizers that unlock consumer-adjacent applications. Others focus on robust industrial-grade portfolios designed for rubber, fuels, and lubricants, where oxidative stability under demanding conditions is paramount. A third group differentiates through specialty formulations that address narrow but valuable use cases, such as spandex-compatible phenolic systems or phosphite antioxidants with enhanced safety characteristics.
This segmentation of differentiation suggests that scale alone is insufficient. The most resilient players combine portfolio breadth with targeted specialization, enabling them to serve both high-volume industrial accounts and niche performance markets. For decision-makers evaluating supplier relationships or competitive threats, the relevant question is not only who offers the widest range of antioxidants, but who can credibly support the regulatory, safety, and processing requirements of the specific applications in scope.
Market Structure Evolution: Consolidation, Diversification, and Entry Risk
Market concentration indicates that a relatively small group of major suppliers commands a significant share of revenue, which tends to reinforce pricing influence and technical standardization within core applications. At the same time, the presence of regional manufacturers and specialty producers ensures that competition remains active, particularly where local service, formulation customization, or cost positioning creates room for differentiated offers. New entry is possible, but it is most viable where a company can bring a clear technical advantage, regulatory readiness, or supply advantage rather than attempting to compete purely on commodity terms.
The evolving structure also points toward selective consolidation in areas where scale, feedstock integration, and compliance infrastructure provide durable advantages. In contrast, specialty niches may remain fragmented as companies compete on application performance and customer proximity. For executives, this means that competitive strategy should be tailored to the layer of the market in question: large-scale industrial supply may reward scale and reliability, while performance-sensitive applications may reward technical differentiation and regulatory readiness.
Forward Outlook: Trends and Commercial Implications for 2026-2032
Trend One: Cost Resilience Becomes a Competitive Moat
Over the next several years, volatility in feedstocks, energy, and logistics is expected to remain a defining feature of the market. Companies that build stronger cost resilience through feedstock integration, manufacturing efficiency, and supply diversification will be better equipped to manage pricing without sacrificing customer trust. Commercial opportunities will accrue to suppliers that can offer transparent cost logic, reliable continuity, and flexible contracting models, while buyers that establish multi-source strategies and application-level cost optimization will be less exposed to abrupt portfolio-wide adjustments.
Worldwide Phenolic Antioxidant Market
Trend Two: Regulation-Led Market Access Will Separate Winners from Followers
As approvals, safety expectations, and compliance documentation become more central to commercial access, regulatory capability will increasingly function as a market-entry filter. Products that achieve broad food-contact or application-specific safety acceptance can open new demand pools, but only when supported by rigorous quality systems and traceable manufacturing practices. Businesses that proactively align development pipelines with the most demanding regulatory environments are likely to gain first-mover advantages that translate into broader geographic and segment expansion later.
Trend Three: Application-Specific Formulation Will Outpace Generic Growth
The market’s growth trajectory will be supported less by uniform volume increases than by tailored solutions that match antioxidant properties to specific polymers, processing conditions, and end-use requirements. This favors suppliers and buyers that invest in technical collaboration, formulation testing, and application engineering. The commercial upside lies in moving from transactional supply to solution-based relationships, where antioxidant selection is integrated into broader material design and quality strategies.
Risks and Uncertainties to Monitor
Despite a constructive growth outlook, several uncertainties could alter the path. Feedstock price spikes or prolonged energy cost pressure could compress margins and delay investment. Regulatory changes in key regions could shift acceptable chemistries or documentation requirements unexpectedly. Demand patterns in consumer-facing segments may evolve faster than industrial categories, creating portfolio mismatches for suppliers that over-index on one track. Supply chain disruptions affecting logistics or regional manufacturing could also create temporary dislocations, particularly if concentration leaves limited fallback options in certain applications.
Strategic Actions for Decision-Makers
For Manufacturers and Suppliers
Priority should be placed on strengthening the intersection of formulation capability, regulatory readiness, and supply resilience. Investment in application-specific development can create defensible differentiation, especially where safety profiles, food-contact readiness, or processing compatibility unlock higher-value segments. At the same time, operational efficiency and geographic diversification should be treated as strategic assets that reduce exposure to input and logistics volatility. Companies that can communicate clear value logic to downstream customers, rather than competing primarily on price, will be better positioned to preserve margins through cost cycles.
For Investors and Strategic Partners
The market opportunity is not in broad-based assumptions of rapid expansion, but in identifying companies and segments where differentiation, compliance depth, and supply reliability can translate growth into durable profitability. Due diligence should focus on feedstock exposure, manufacturing footprint flexibility, regulatory track record, and the extent to which a business serves application-specific demand rather than undifferentiated commodity volume. In this environment, value creation is likely to come from businesses that can navigate cost pressure while expanding into regulated or performance-sensitive applications.
For Buyers and Procurement Leaders
Procurement strategy should move beyond spot purchasing toward structured resilience. Diversifying suppliers, securing contractual flexibility, and aligning antioxidant selection with application requirements can reduce exposure to pricing shocks and supply disruptions. Technical evaluation should include regulatory status, safety documentation, and processing compatibility, especially when substituting materials or expanding into new end-use categories. Close coordination between procurement, R&D, and quality functions will be essential to balance cost objectives with performance and compliance needs.
The antioxidants market is entering a phase where strategic advantage depends on how well organizations integrate technical, regulatory, and supply-chain capabilities into their commercial approach. For readers seeking deeper segmentation detail, regional breakdowns, and customized scenario planning for specific applications or buyer-supplier configurations, the full PW Consulting research report provides extended data and tailored analysis to support more granular decision-making.
For detailed analysis of this topic, please visit the official page: Antioxidants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com