

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Urea Formaldehyde Resin Market: Why the 2% CAGR Trajectory Signals Real Growth Drivers

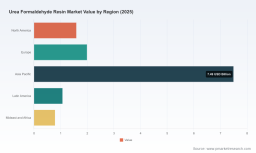
Urea Formaldehyde Resin Market: Navigating the Crossroads of Compliance, Cost, and Innovation
The global urea formaldehyde resin market stands at a strategic inflection point, where established demand patterns intersect with tightening regulatory frameworks and evolving supply chain dynamics. Valued at approximately $11.71 billion in 2020, the market expanded steadily through 2023, reaching $12.47 billion, before experiencing a modest contraction to $12.93 billion in 2025. Looking ahead, the trajectory projects growth to $14.85 billion by 2032, reflecting a compound annual growth rate of roughly 2.0% over the forecast horizon. This measured expansion masks significant underlying volatility, as the market navigates structural shifts in end-use demand, raw material pricing pressures, and regulatory mandates that are fundamentally reshaping product specifications and competitive positioning. For executives and investors operating in downstream manufacturing, chemical distribution, or advanced materials, understanding these dynamics is no longer optional; it is a prerequisite for capital allocation, product roadmap planning, and supplier diversification strategies.
Market Landscape and Structural Headwinds
A Moderating Growth Curve with Regional Asymmetry
The market’s historical progression from $11.79 billion in 2021 to $13.08 billion in 2024 illustrates a period of steady adoption, primarily fueled by construction activity, furniture manufacturing, and panelboard production across key industrial corridors. However, the slight pullback in 2025 to $12.93 billion signals a transitional phase rather than a cyclical downturn. Demand composition remains heavily anchored in traditional adhesive applications, with powder and liquid formulations splitting the revenue base in ways that reflect both application engineering preferences and logistical constraints. Liquid grades continue to dominate environments requiring on-site mixing flexibility or continuous processing lines, while powder variants maintain relevance in settings where shelf stability, transportation efficiency, and controlled inventory management outweigh handling complexity.
PW Consulting Chemical & Energy Research Center
Three Critical Challenges Shaping the Next Cycle
First, regulatory tightening around volatile organic compound emissions has moved from a compliance checkbox to a product architecture constraint. Standards such as CARB Phase-III and EPA TSCA Title VI now require composite wood products to limit formaldehyde emissions to 0.05 ppm, effectively mandating reformulation across legacy adhesive portfolios. The operational implication extends beyond chemistry; it touches manufacturing line validation, certification timelines, and customer acceptance cycles, creating a compliance burden that disproportionately affects mid-tier producers without dedicated R&D or regulatory affairs capacity.
Second, raw material cost volatility has introduced margin compression risks that are difficult to hedge through conventional procurement strategies. Formaldehyde pricing in Europe reached 370 euros per ton in early 2025, marking a historical high, while urea formaldehyde resin prices in the United States climbed to 908 USD per metric ton in September 2025, closely tracking feedstock urea movements. These cost pressures are not isolated to a single region or feedstock; they reflect broader energy, logistics, and agricultural input dynamics that ripple through the value chain and challenge the economics of both conventional and low-emission formulations.
Third, the cost differential between conventional and low-emission resin variants introduces a strategic dilemma for downstream buyers. Industry analysis indicates that meeting EU and global low-emission requirements can add 10–15% to production costs for standard UF resins compared with compliant low-emission grades. This premium is not uniformly absorbed across end markets; cost-sensitive applications face pricing resistance, while premium wood bonding and construction panel segments increasingly treat low-emission compliance as a baseline entry requirement rather than a differentiated feature.
Paraformaldehyde Market
Key Drivers Reshaping the Market Trajectory
Regulatory Architecture as a Catalyst for Product Innovation
Regulatory pressure is no longer a static compliance backdrop; it is actively steering formulation pathways and competitive differentiation. The requirement for a 40% reduction in VOC emissions by 2026 under CARB Phase-III has accelerated reformulation programs across the adhesive and panelboard ecosystem. This regulatory trajectory is pushing producers to invest in low-emission UF grades that meet E0, CARB, and LEF/ULEF standards without sacrificing bond strength, cure speed, or process compatibility. The practical outcome is a market where regulatory conformity becomes a gatekeeper for market access, particularly in North American and European composite wood segments, while simultaneously creating a technical moat for suppliers that can deliver compliant formulations at scale.
Green Chemistry and Low-Emission Formulation as Competitive Levers
The push toward reduced formaldehyde emissions has coincided with broader sustainability mandates across the chemical and manufacturing sectors, creating a convergence of compliance and corporate ESG objectives. Leading producers are responding by developing resin lines that lower formaldehyde output while maintaining performance benchmarks for plywood, particleboard, fibreboard, and impregnation applications. Some offerings now emphasize emission reductions of up to 90% relative to conventional benchmarks, positioning low-emission grades as enablers for downstream manufacturers seeking to satisfy both regulatory standards and customer-facing sustainability claims. This trend is not merely a technical adjustment; it is reshaping procurement criteria, as panel producers and wood product manufacturers increasingly evaluate resin suppliers on emission profiles, certification support, and formulation flexibility alongside price and delivery reliability.
Demand-Side Shifts in Construction, Furniture, and Panel Manufacturing
Downstream demand patterns are evolving in response to housing market dynamics, interior fit-out cycles, and the expansion of engineered wood solutions in both developed and emerging economies. Wood adhesives remain the dominant application driver, reflecting the continued reliance on UF resins in panelboard production and furniture assembly. At the same time, demand for molding compounds, surface coatings, and textile finishing applications introduces segments with distinct performance requirements and growth profiles. The practical implication for resin producers is that volume growth is increasingly tied to application-specific engineering rather than broad commodity displacement. Customers are looking for formulations that balance cure compatibility, moisture resistance, emission compliance, and total cost of ownership, which elevates the importance of technical service, application testing, and co-development arrangements.
Supply Chain Reconfiguration and Cost Structure Dynamics
Feedstock pricing, energy costs, and logistics constraints are collectively reshaping the cost structure of UF resin production. The convergence of elevated formaldehyde prices in Europe and urea-linked resin pricing movements in the United States underscores the vulnerability of input cost pass-through strategies, particularly in markets where downstream price sensitivity limits aggressive adjustments. In response, some producers are exploring formulation optimization, regional sourcing adjustments, and inventory positioning strategies to mitigate exposure. For downstream manufacturers, this environment heightens the importance of supplier diversification, contractual flexibility, and scenario planning around input cost trajectories. It also reinforces the strategic value of long-term supply agreements that incorporate transparency on feedstock indices and formulation change timelines.
Urea Formaldehyde Concentrate (UFC) Market
Competitive Landscape and Strategic Positioning
Fragmented Leadership with Clear Differentiation Paths
The market exhibits a moderate concentration profile, with a handful of large players commanding a significant share of revenue while a broader base of specialty and regional suppliers competes on formulation, service, and application expertise. This structure supports both scale-driven efficiency and differentiation-driven premium positioning, depending on the segment and geography. Leading companies are pursuing distinct strategic paths that reflect their product portfolios, geographic footprints, and sustainability commitments.
Ercros has focused on low-emission UF resin offerings designed to meet stringent formaldehyde standards across plywood, particleboard, fibreboard, and impregnation applications. Its resin range emphasizes compatibility with LEF, ULEF, CARB, and E0 requirements, positioning the company as a solution provider for downstream manufacturers navigating emission compliance without sacrificing processing performance. Prefere Resins has pursued a sustainability-forward strategy, integrating green chemistry principles into its amino resin portfolio for wood adhesives, insulation, and construction panels. The company’s emphasis on CO2-neutral and bio-based resin innovations, reinforced by recent sustainability certifications and reporting, signals a strategic alignment between regulatory compliance and corporate ESG positioning.
Hexion Inc. continues to leverage established methylated UF grades and resin platforms tailored for wood panel adhesives and particleboard production, emphasizing performance consistency and application familiarity in mature markets. BASF SE maintains a broad specialty chemicals footprint, with urea formaldehyde resin grades positioned for wood bonding and adjacent applications, benefiting from integrated supply chain capabilities and cross-market formulation expertise. Dynea Oy and Advachem contribute through specialized resin technology and niche chemical portfolios, respectively, serving panel adhesives and wood product manufacturing with focused application support. Kronospan Limited’s in-house UF resin production for particleboard, MDF, and plywood illustrates a vertical integration model that prioritizes supply control and formulation alignment with internal panel specifications. Metadynea International GmbH complements this landscape with targeted UF resin offerings for wood panel and adhesive applications, reinforcing the diversity of strategic approaches across the competitive field.
Strategic Takeaways from Recent Industry Moves
Recent developments underscore how sustainability credentials and transparency are becoming embedded in competitive positioning. Prefere Resins’ achievement of an EcoVadis Gold rating for ESG performance, alongside the publication of its first Group Sustainability Report covering 2023–2024, reflects a broader trend in which ESG performance is increasingly treated as a procurement consideration rather than a peripheral corporate initiative. The company’s earlier emphasis on Mission Zero 2050 CO2-neutral bio-based resin innovations further illustrates how long-term decarbonization targets are being translated into product strategy. For buyers and investors, these moves signal that supplier selection is increasingly influenced by verifiable sustainability performance, formulation roadmaps, and the ability to support downstream compliance narratives.
Market Evolution: Integration, Specialization, and New Entrant Dynamics
The competitive landscape is evolving along two complementary paths. On one hand, scale-oriented players continue to pursue integration and portfolio breadth to capture efficiency advantages, support multi-application supply, and reinforce regional distribution reach. On the other hand, specialization is intensifying around low-emission formulations, application-specific engineering, and sustainability-linked product attributes. This dual dynamic creates opportunities for incumbents to defend share through performance and compliance leadership, while also opening space for new entrants or expanding specialists that can address underserved application niches or regional compliance requirements. The likely outcome over the next several years is a market where broad-scale suppliers coexist with highly differentiated formulation specialists, and where downstream buyers increasingly manage a dual-sourcing strategy that balances cost, compliance, and technical support.
Forward Outlook: Three Trends Shaping the 2026–2032 Window
Low-Emission Compliance as a Baseline, Not a Premium
As regulatory mandates mature and enforcement intensifies, low-emission UF grades are likely to transition from differentiated offerings to market-entry requirements in key regions. This shift will compress the commercial advantage of early compliance while simultaneously raising the cost of late adaptation. Manufacturers that have already validated low-emission formulations, secured certification pathways, and aligned production lines with compliant grades will be better positioned to manage transition risk. Conversely, suppliers and downstream buyers that delay reformulation or certification readiness may face margin erosion, supply disruption, or exclusion from regulated procurement channels.
Formulation Engineering and Application-Specific Value Creation
Volume growth is expected to increasingly depend on application-specific value creation rather than broad-based resin displacement. Wood adhesives will remain the core demand anchor, but opportunities in molding compounds, surface coatings, and textile finishing will require tailored performance profiles, processing compatibility, and technical service. This trend favors suppliers that can combine formulation flexibility with application engineering, testing support, and regional responsiveness. For downstream manufacturers, it creates an incentive to deepen technical collaboration with resin partners, particularly where product performance, emission profile, and total cost of ownership must be optimized simultaneously.
Cost Volatility and Supply Chain Resilience as Strategic Priorities
Input cost volatility, particularly around formaldehyde and urea-linked feedstocks, is likely to remain a defining feature of the market environment. While long-term contracts, index-linked pricing, and regional sourcing adjustments can mitigate some exposure, the broader reality is that cost resilience will become a strategic priority for both producers and buyers. This includes evaluating supplier diversity, inventory positioning, formulation flexibility, and scenario planning around feedstock price trajectories. For investors, this environment rewards companies that demonstrate disciplined cost management, transparent input exposure, and the ability to adapt formulations without compromising compliance or performance.
Strategic Actions for Decision-Makers
For Manufacturers and Panel Producers
- Validate low-emission resin compatibility across existing and planned production lines before regulatory deadlines tighten further, prioritizing formulations that meet CARB, EPA TSCA, and E0/EU expectations without disrupting cure profiles or bond performance.
- Diversify resin sourcing to balance cost, compliance, and technical support, while establishing clear criteria for supplier evaluation that include emission data, certification support, formulation adaptability, and supply continuity.
- Invest in application testing and co-development with resin suppliers where performance or emission targets require custom formulation, reducing the risk of line stoppages, rework, or certification delays.
For Investors and Strategic Capital Allocators
- Prioritize companies that demonstrate verifiable progress on low-emission formulation roadmaps, ESG transparency, and cost discipline, as these attributes are increasingly correlated with market access and procurement preference in regulated segments.
- Monitor feedstock exposure and pricing pass-through capabilities, recognizing that margin resilience will depend on formulation optimization, regional sourcing flexibility, and contract structures that align input costs with downstream pricing reality.
- Evaluate consolidation and specialization dynamics as indicators of where value is being created, particularly in segments where low-emission compliance, application engineering, and sustainability credentials are reshaping buyer selection criteria.
For Procurement and Supply Chain Leaders
- Integrate emission compliance, certification support, and sustainability reporting into supplier scorecards alongside price, lead time, and quality metrics, ensuring that procurement decisions reflect both regulatory readiness and corporate ESG objectives.
- Establish scenario planning for raw material cost movements, including index-linked contracting, alternative supplier qualification, and inventory strategies that reduce exposure to sudden feedstock price spikes.
- Engage early with resin suppliers on formulation change timelines and certification requirements, aligning procurement calendars with technical validation cycles to avoid disruption during regulatory transitions.
Closing Perspective
The urea formaldehyde resin market is not defined by a single growth driver or a uniform competitive narrative. It is a market in which regulatory compliance, feedstock economics, application-specific performance, and sustainability positioning intersect to shape buyer behavior and supplier strategy. The modest headline growth projection conceals a more nuanced reality: value creation is shifting toward compliance readiness, formulation flexibility, and supply chain resilience, while cost volatility and certification complexity reward companies that act early and coordinate across technical, commercial, and procurement functions. For executives, investors, and supply chain leaders, the practical imperative is to treat resin selection and supplier relationships as strategic variables rather than transactional inputs, and to align product roadmaps, sourcing decisions, and investment priorities with the regulatory and cost realities that will define the next cycle.
For detailed segmentation data, regional demand profiles, application-level revenue splits, and tailored scenario analysis, the full research report provides the granular data and customized recommendations needed to translate these market dynamics into concrete planning parameters.
For detailed analysis of this topic, please visit the official page: Urea Formaldehyde Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com