

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydrazine Hydrate Market: Why the 5.5% CAGR Shift Reshapes 2032 Forecasts

Hydrazine Hydrate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global hydrazine hydrate market has demonstrated steady expansion over the 2020–2025 period, driven by consistent demand across industrial, agricultural, and specialty chemical applications. Valued at approximately USD 215.0 million in 2020, the market grew to an estimated USD 280.6 million by 2025. Forward-looking projections indicate a compound annual growth rate of 5.5 percent through 2032, with revenues expected to approach USD 408.8 million by the end of the forecast horizon. This trajectory reflects a maturing but still dynamic market where volume growth is increasingly intertwined with regulatory adaptation and technological refinement rather than raw demand expansion alone.
While the aggregate figures point to resilience, the underlying structure reveals a market navigating several inflection points. First, regulatory scrutiny has intensified significantly across major jurisdictions. Hydrazine is classified as a substance of very high concern under the European Union REACH framework, placing producers and downstream users under continuous pressure to maintain authorization dossiers and justify continued use. This regulatory posture does not eliminate demand, but it raises compliance costs and compresses margins for operators with weaker regulatory infrastructure. Second, logistics and handling constraints remain a persistent bottleneck. Transporting hydrazine hydrate requires insulated, pressure-rated containers and certified handlers under United Nations Model Regulations, which limits supply chain flexibility and increases operational overhead for regional distributors and end-users alike. Third, feedstock cost volatility has emerged as a structural challenge. Recent periods have seen upstream raw material costs for hydrazine hydrate production rise by roughly 15 percent, squeezing profitability and forcing manufacturers to recalibrate pricing strategies without alienating price-sensitive industrial customers.
These challenges are not merely operational friction points; they are reshaping competitive boundaries. Companies that can absorb compliance costs, secure reliable feedstock contracts, and maintain rigorous handling standards are gradually separating themselves from smaller or less integrated players. The market is therefore transitioning from a capacity-driven growth phase to one where operational sophistication, regulatory readiness, and supply chain resilience determine long-term positioning. For decision-makers, the practical implication is clear: market entry or expansion now requires a holistic view of compliance, logistics, and input cost management rather than a narrow focus on production volume or end-market demand alone.
Key Drivers Shaping Market Direction
Technological Innovation and Product Specialization
Technological advancement in hydrazine hydrate is less about breakthrough chemistry and more about precision, purity, and application-specific differentiation. Industry participants have increasingly moved toward high-purity formulations tailored for demanding sectors such as aerospace and specialty synthesis. In February 2024, LANXESS AG introduced a high-purity 100 percent hydrazine hydrate variant specifically developed for aerospace applications, signaling a deliberate shift toward niche, performance-driven segments where tolerance for impurities is extremely low and customers are willing to pay for reliability. Alongside product refinement, trade platforms have become conduits for showcasing integrated value propositions. In May 2025, Arkema S.A. and LANXESS AG both participated in Chemspec Europe 2025, highlighting hydrazine hydrate alongside complementary chemicals such as thionyl chloride for crop protection agent synthesis. These engagements underscore a broader trend: manufacturers are positioning hydrazine hydrate not as a standalone commodity but as a critical input within larger synthetic and formulation workflows. For businesses, this implies that competitive advantage increasingly comes from offering application-ready specifications, technical support, and integrated chemical solutions rather than competing solely on base grade volume.
Regulatory and Policy Environment as a Market Filter
Regulatory dynamics are functioning as a market filter rather than a blanket constraint. In the United States, domestic rules were harmonized with updated international standards in 2024, prompting relabeling requirements and additional training across the supply chain. While such measures raise short-term operational burdens, they also formalize handling expectations and reduce variability in compliance practices. In parallel, EU REACH continues to require producers and users to prepare costly authorization dossiers, which disproportionately affects operators with limited regulatory resources or fragmented application portfolios. The practical effect is a consolidation of compliant supply bases and a higher barrier for new entrants who lack established regulatory track records. For procurement and sourcing leaders, this environment rewards long-term partnerships with manufacturers that can demonstrate consistent authorization status, transparent documentation, and robust safety protocols. For producers, the strategic imperative is to invest in regulatory capacity early, since compliance credentials are becoming as commercially relevant as technical specifications.
Demand-Side Evolution in End-Use Industries
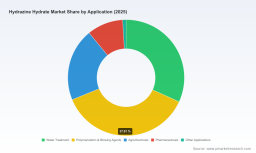
Demand for hydrazine hydrate is being shaped by evolving priorities within core application sectors. Water treatment continues to be a substantial demand center, supported by ongoing infrastructure maintenance and chemical dosing requirements in industrial and municipal systems. At the same time, polymerization and blowing agent applications represent a significant share of consumption, reflecting the material’s role in foam generation and specialty polymer processing. Agrochemical synthesis remains another critical driver, where hydrazine hydrate serves as a key inorganic input for crop protection agents and related intermediates. Pharmaceutical manufacturing, while smaller in absolute terms, demands higher specifications and more controlled supply conditions. The common thread across these segments is a growing preference for suppliers who can provide grade consistency, technical documentation, and reliable delivery schedules. End-users are increasingly less willing to accept variability in feedstock quality or unpredictable lead times, particularly when production downtime or formulation failures carry high costs. This behavioral shift is pushing manufacturers to strengthen quality assurance systems, expand technical service capabilities, and align production planning more closely with downstream consumption patterns.
Supply Chain and Cost Structure Realignment
The cost structure of hydrazine hydrate production is undergoing noticeable realignment. Upstream feedstock costs have risen by approximately 15 percent in recent periods, placing pressure on conversion economics and prompting manufacturers to explore procurement optimization, energy efficiency improvements, and strategic inventory management. At the same time, shipping and handling requirements continue to add layered costs, particularly for long-distance distribution and cross-border transactions. These factors are encouraging a re-evaluation of network design, with some operators consolidating regional supply points, investing in specialized packaging, and pursuing long-term feedstock agreements to reduce exposure to spot price swings. For commercial teams, the implication is that cost competitiveness is increasingly determined by supply chain architecture as much as by production efficiency. Businesses that can stabilize input costs, optimize logistics, and maintain buffer capacity for demand fluctuations are better positioned to protect margins while preserving customer relationships in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The competitive structure of the hydrazine hydrate market is moderately concentrated, with the top three companies accounting for approximately 26.8 percent of market revenue and the top five collectively representing about 29.4 percent. This concentration level indicates a landscape where established players hold meaningful share but where fragmentation still exists, particularly across regional distribution and specialty grades. The presence of multiple Japanese manufacturers alongside European incumbents reflects a geographically diverse supply base, with each group emphasizing different strengths in product specification, application focus, and regional service networks.
Arkema S.A., headquartered in France, offers hydrazine hydrate at 100 percent concentration along with a full range of dilutions and derivatives, positioning itself as a flexible supplier for polymer foam blowing agent applications and active ingredient synthesis. This breadth allows Arkema to serve customers who require customized dilution levels or derivative formats rather than a one-size-fits-all product. LANXESS AG, based in Germany, supplies hydrazine hydrate as a key inorganic input for the synthesis of crop protection agents and other agrochemical applications. Its emphasis on agrochemical synthesis aligns with one of the market’s most consistent demand streams, and its February 2024 launch of a high-purity 100 percent variant for aerospace applications demonstrates a willingness to extend into highly specification-sensitive segments. Otsuka-MGC Chemical Company, Inc., based in Japan, is recognized as the largest global maker of hydrazine hydrate and the only manufacturer based in Japan, giving it a distinctive domestic production advantage and a broad industrial application footprint. Nippon Carbide Industries Co., Inc., also in Japan, focuses on hydrazine hydrate as a synthetic raw material for pharmaceutical and agrochemical fields, while also supplying boiler cleaning chemicals, which diversifies its end-use exposure. Japan Finechem Co., Inc. produces hydrazine hydrate through its Sakaide plant operations, adding further capacity and regional depth within the Japanese supply base. Kanto Chemical Co., Inc. supplies hydrazine hydrate in technical and analytical grades, catering to customers who require precise grade differentiation for laboratory, quality control, and specialized industrial use.
Sodium Borohydride Market
The strategic positioning of these leaders reveals several differentiating advantages. First, product range flexibility matters. Companies that can supply both concentrated and diluted formats, plus relevant derivatives, reduce the need for customers to manage multiple suppliers for related grades and applications. Second, application specialization is increasingly valuable. Firms that align their capabilities with high-priority end-use areas such as agrochemicals, aerospace-grade purity, or pharmaceutical synthesis can command stronger customer loyalty and more resilient demand. Third, regional manufacturing presence can serve as a strategic asset, particularly where handling regulations, logistics complexity, and customer service expectations vary by market. Japanese manufacturers, for example, benefit from domestic production capabilities that support stable supply and localized technical support, while European players leverage integrated chemical portfolios and established regulatory infrastructure.
Looking ahead, the market structure is likely to continue evolving through a combination of consolidation, specialization, and selective new entry. Regulatory compliance costs and feedstock volatility will make it harder for under-resourced entrants to compete on undifferentiated volume, which may encourage 인수합병 activity or strategic partnerships among mid-tier players seeking scale and compliance capacity. At the same time, the growing importance of specialized grades and application-specific support creates space for focused competitors who can outperform on quality, documentation, and technical service rather than on price alone. New entrants that bring differentiated capabilities—such as advanced purification processes, specialized packaging, or strong regional regulatory readiness—could capture niche positions, but broad-based commodity competition is likely to intensify only where regulatory and logistics barriers are lower. For incumbents, the strategic task is to defend share in core applications while selectively expanding into higher-value specifications where customer willingness to pay is stronger and switching costs are higher.
Worldwide Potassium Carbonate Hydrate Market
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the hydrazine hydrate market evolves and where commercial opportunities emerge. The first trend is the continued elevation of regulatory and safety compliance as a core competitive dimension. As authorization requirements, labeling standards, and handling protocols become more entrenched, suppliers with mature compliance systems will gain an advantage in securing long-term contracts with risk-averse end-users. This creates an opportunity for companies to differentiate through documented safety performance, transparent regulatory status, and robust technical support, particularly in regions where compliance expectations are tightening. Businesses that treat compliance as a strategic capability rather than a cost center are better positioned to retain customers and defend pricing during periods of input cost pressure.
The second trend is the gradual shift toward higher-value, application-specific grades and integrated chemical solutions. Demand from sectors such as aerospace, pharmaceutical synthesis, and advanced agrochemical manufacturing is likely to sustain interest in high-purity and precisely specified products. This trend opens commercial pathways for suppliers that can offer tailored concentrations, reliable analytical certification, and close technical collaboration with downstream formulators. It also suggests that pure commoditization pressure may be partially offset by segmentation, where customers in specification-sensitive applications place greater weight on consistency and support than on marginal price differences. Companies that can clearly articulate grade performance, handle documentation efficiently, and align production with customer qualification requirements are more likely to capture these higher-margin positions.
PW Consulting Chemical & Energy Research Center
The third trend is supply chain resilience and cost management becoming central to market competitiveness. With feedstock costs elevated and logistics requirements demanding specialized handling, businesses will continue to optimize procurement, inventory, and distribution strategies. This may lead to more long-term feedstock agreements, regional supply consolidation, and investment in packaging and transport capabilities that reduce downtime and compliance risk. The commercial opportunity here lies in building supply arrangements that provide predictability for both suppliers and customers, especially in applications where production continuity is critical. At the same time, potential risks remain. Regulatory decisions could further constrain certain uses or increase documentation burdens, feedstock cost spikes could compress margins if unable to be passed through, and logistics disruptions could affect delivery reliability in tight markets. Decision-makers should therefore monitor regulatory calendar developments, input cost trends, and regional handling requirements as part of ongoing strategic planning.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to strengthen regulatory readiness, product differentiation, and supply chain stability in tandem. Building and maintaining rigorous authorization documentation, expanding high-purity or application-specific offerings, and securing more stable feedstock arrangements can help protect margins while improving customer retention. Companies should also evaluate whether their current grade portfolio matches the direction of end-use demand, particularly where aerospace, agrochemical, and pharmaceutical customers increasingly expect precise specifications and reliable technical support. Investing in handling and packaging capabilities that reduce logistics friction can further enhance competitiveness, especially in markets where certified transport and storage are limiting factors.
For investors, the key is to assess exposure not only to top-line demand growth but also to the regulatory and cost-structure dynamics that determine profitability. Businesses with strong compliance infrastructure, diversified application bases, and resilient logistics are better positioned to withstand feedstock volatility and regulatory pressure. Evaluation should consider whether a company’s product mix is shifting toward higher-value specifications, whether its regional presence supports stable service and compliance, and whether its cost management practices can absorb input price fluctuations without eroding competitive position. In a market where concentration is moderate and differentiation is increasing, long-term value is likely to accrue to operators that can combine scale with specialized capabilities rather than those competing purely on volume.
For procurement and sourcing leaders, the practical focus should be on supplier qualification, grade consistency, and supply continuity. Given the handling complexity and regulatory sensitivity of hydrazine hydrate, sourcing decisions should weigh documented authorization status, safety protocols, packaging standards, and delivery reliability alongside price. Building longer-term relationships with suppliers that can demonstrate stable compliance and technical support can reduce the risk of disruptions and specification mismatches, particularly in applications where production downtime or formulation issues are costly. Procurement teams should also monitor regional regulatory updates and logistics requirements, since changes in labeling, training, or transport standards can affect total landed cost and operational readiness.
As the hydrazine hydrate market continues to evolve through regulatory refinement, product specialization, and supply chain recalibration, the businesses that succeed will be those that treat these dynamics as strategic levers rather than external constraints. Detailed segmentation data, company-level assessments, and application-specific forecasts can provide the granularity needed to convert these trends into concrete sourcing, investment, and production decisions. For a more comprehensive view of regional breakdowns, application splits, competitive benchmarks, and forward-looking scenarios, the full PW Consulting research report offers a deeper evidence base and tailored guidance for specific strategic contexts.
For detailed analysis of this topic, please visit the official page: Hydrazine Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com