

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
Bulk Continuous Filament Carpet Fiber Market: Why 4.51% CAGR. Reshapes Global Dynamics Beyond 2032
By pmarketresearch, 2026-09-18
Navigating Growth and Transformation in the Bulk Continuous Filament Carpet Fiber Market
Market Overview: Scale, Trajectory, and Core Pressures
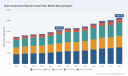
The Bulk Continuous Filament (BCF) carpet fiber market has entered a phase of steady, measured expansion, driven by the widespread adoption of synthetic fibers in both residential and commercial flooring. Valued at approximately $15.63 billion in 2025, the market is projected to reach $21.29 billion by 2032, growing at a compound annual growth rate of 4.51% over the forecast period. This trajectory reflects a broader structural shift away from spun yarns and natural fibers toward continuous filament solutions that deliver superior durability, consistent texture, and enhanced stain resistance. The market’s expansion is underpinned by consistent demand across building construction, renovation cycles, and interior fit-out programs, though the pace of growth varies significantly by region and application segment.
Polyester Fiber Market
Despite the positive medium-term outlook, the industry is navigating several structural pressures that are reshaping competitive dynamics and investment priorities. First, raw material volatility continues to exert margin pressure across key polymer feedstocks. Nylon 6 BCF production relies heavily on caprolactam pricing, while nylon 6,6 depends on adipic acid and hexamethylenediamine supply chains. In 2025, global nylon fiber and feedstock markets experienced profitability headwinds driven by caprolactam oversupply and soft demand for PA6 and PA66 in several key regions. These conditions have forced producers to balance volume commitments against pricing flexibility, particularly in cost-sensitive commercial segments.
Second, the regulatory and sustainability agenda is accelerating material substitution and formulation changes. The industry is witnessing a pronounced shift toward recycled content in BCF yarns, including 100% recycled nylon 6 and post-consumer recycled PET. This transition is being reinforced by circular economy mandates in automotive interiors and commercial flooring, where brand owners and building specifications increasingly demand traceable recycled content and lower lifecycle emissions. While this creates differentiation opportunities, it also raises technical and supply chain complexity, particularly around consistency, dyeability, and performance validation across recycled feedstocks.
Third, the market is being reshaped by shifting demand patterns and competitive intensity across regions. Asia Pacific continues to represent a substantial share of global volume, supported by domestic carpet manufacturing, infrastructure-linked interior demand, and expanding production capacity. North America and Europe remain important markets, but growth is increasingly tied to premiumization, performance specifications, and sustainability requirements rather than raw volume expansion. In this environment, manufacturers are being forced to choose between cost leadership, performance differentiation, and sustainability positioning, with few players able to dominate all three simultaneously.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
Technology innovation is acting as a primary catalyst for market evolution, particularly in fiber engineering, spinning efficiency, and solution-dyeing capabilities. Advanced BCF architectures are enabling manufacturers to improve bulk, resilience, and stain resistance without sacrificing processing speed or yarn uniformity. Solution-dyed nylon and polyester BCF fibers, in particular, are gaining traction because they offer superior colorfastness, reduced water consumption, and better alignment with commercial warranty requirements. These technical advantages are especially valuable in high-traffic commercial environments and automotive interiors, where durability and appearance retention directly influence specification decisions.
The regulatory environment is reinforcing the importance of sustainable fiber portfolios. As circular economy expectations become embedded in procurement standards, producers are investing in recycled feedstocks and mono-material architectures that simplify end-of-life processing. This shift is not merely compliance-driven; it is increasingly tied to customer preference and brand positioning. Automotive and commercial flooring buyers are integrating recycled content targets into their supply chain criteria, which is pushing BCF manufacturers to expand recycled nylon and recycled PET capabilities while maintaining performance parity with virgin materials.
On the demand side, consumer and enterprise behavior is shifting toward flooring solutions that combine aesthetics, longevity, and environmental credentials. Residential demand continues to be supported by renovation activity and a preference for low-maintenance, durable carpet fibers in both new builds and retrofit projects. Commercial demand is being shaped by workplace reconfiguration, hygiene expectations, and the need for materials that can withstand frequent cleaning cycles. Automotive and transport applications add another layer of demand stability, with interior weight reduction, noise control, and recycled content targets influencing material selection.
PW Consulting Chemical & Energy Research Center
Supply chain and cost structures remain a critical driver of competitive outcomes. Polyest er BCF yarns have gained significant global market share in carpet yarns, largely due to cost advantages over polypropylene and nylon in many applications. This cost dynamic has encouraged capacity expansion and product diversification among polyester-focused producers, while nylon players have concentrated on performance niches and recycled differentiation. At the same time, feedstock interdependence means that polymer pricing cycles can quickly translate into margin variability. Producers with integrated feedstock access, flexible production lines, and diversified material portfolios are better positioned to absorb price swings and reallocate output according to demand signals.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive environment in the BCF carpet fiber market is characterized by a mix of established multinational producers, regional specialists, and expanding Asian capacity. Market concentration remains meaningful, with the top three players holding roughly 38% of the market and the top five approaching 52%. This level of concentration indicates that scale, technology access, and customer relationships still matter, but it also leaves meaningful room for regional players and niche specialists to compete on customization, speed, and local service.
Leading companies are pursuing distinct strategic positions rather than competing on a single dimension. Aquafil has built a strong identity around recycled nylon 6 BCF, using ECONYL as a platform for residential, commercial, and automotive applications with an explicit circular economy focus. Universal Fibers has emphasized solution-dyed nylon BCF with recycled content, targeting commercial and residential buyers who value color consistency and sustainability in tandem. Ascend Performance Materials has concentrated on premium nylon 6,6 BCF for commercial applications, differentiating on durability, color retention, and performance under demanding use conditions. B.I.G. Yarns has diversified across nylon PA6, polypropylene, and virgin polyester BCF, recently completing industrial production runs of virgin PET BCF for automotive carpet applications to enable mono-polymer solutions alongside its existing lines.
Concrete Fiber Market
Asian producers are playing an increasingly important role in shaping supply dynamics. Toray Industries continues to offer nylon and polyester BCF yarns with advanced fiber technology for carpet and textile flooring markets. Hyosung Advanced Materials manufactures nylon BCF yarns, including recycled options for automotive floor carpets, aligning with regional demand and sustainability incentives. In India, AYM Syntex and Beekaylon Synthetics are expanding specialty BCF offerings across polyester, nylon 6, and polypropylene, with Beekaylon leveraging advanced Neumag technology for tri-color and standard yarn production. Shanthi Industries adds further regional depth with polypropylene, polyester, and nylon BCF yarns focused on carpet manufacturing applications. In China, Zhejiang Sitong New Material Technology has moved to strengthen its position as one of Asia’s largest BCF yarn producers by commissioning additional Oerlikon Neumag BCF S+ positions for polyester yarn, supporting a more balanced production mix across polyester, polyamide, and polypropylene. Zhejiang Hengyuan Chemical Fiber Group has similarly emphasized strength, resilience, and durability in heavy-duty flooring-grade BCF yarns.
Polymer suppliers and mid-stream players also influence competitive outcomes. Nylene supplies multiple-dye-level nylon 6 polymers specifically for BCF and solution-dyed carpet fibers, enabling downstream customization. RadiciGroup contributes nylon BCF yarns within its broader synthetic fibers portfolio, while Gülsan Holding maintains significant polypropylene and synthetic capacity for the carpet industry. Collectively, these players illustrate how the market is structured not only by yarn producers but also by feedstock specialization and processing technology access.
The strategic trend across the landscape is one of selective differentiation rather than undifferentiated capacity expansion. Companies are investing where they can command a clearer value proposition: recycled content credentials, solution-dyeing performance, mono-material design for automotive, or cost-efficient polyester scale. At the same time, capacity additions in Asia are increasing competitive pressure on pricing and availability, particularly in polyester. This suggests a market that is simultaneously consolidating around leading technology and sustainability capabilities while fragmenting in cost-driven segments where regional producers can win on speed, service, and local demand knowledge.
Forward Outlook: Trends Shaping the Next Three to Five Years
Over the next three to five years, one of the most consequential trends will be the continued escalation of recycled and mono-material fiber architectures. As automotive and commercial flooring specifications tighten around circularity, BCF producers that can deliver consistent recycled nylon and recycled PET yarns with verified performance will gain preferential access to high-value contracts. This trend favors players with established recycling feedstocks, polymer engineering expertise, and the ability to maintain dye and performance consistency across batches.
A second trend is the widening performance gap between standard and premium BCF solutions. Demand in commercial and automotive applications is likely to reward fibers that combine solution-dyeing, improved bulk, and stronger color retention with lower maintenance requirements. In residential markets, premiumization may be more uneven, but there is clear opportunity in fibers that offer better durability and easier care without a disproportionate price premium. This creates a two-tier market dynamic in which volume growth is available across segments, but margin expansion will depend on technical differentiation and specification wins.
A third trend is regional realignment in production and sourcing. Capacity expansion in Asia, especially in polyester BCF, is likely to keep cost pressure elevated while also improving supply resilience for downstream carpet manufacturers. North American and European producers will increasingly compete on sustainability credentials, specialty formulations, and proximity to end-market specification channels. For buyers and investors, this means that sourcing strategies and capacity planning will need to account for both cost efficiency and the risk of regulatory or customer-driven material shifts.
These trends carry meaningful opportunity, but also uncertainty. Feedstock pricing volatility, especially in nylon-related polymers, can quickly alter profitability assumptions. Recycled content mandates may accelerate in some markets faster than supply chains can scale consistent quality. In addition, macroeconomic cycles affecting construction, renovation, and auto production can shift demand timing and intensity. Companies that treat sustainability, performance, and cost as an integrated strategy rather than separate initiatives will be best positioned to navigate these uncertainties.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product portfolios with the durability, colorfastness, and recycled-content requirements that are becoming baseline expectations in commercial and automotive specifications. Investing in solution-dyeing capability, flexible BCF lines, and reliable recycled feedstock access can create defensible differentiation. At the same time, cost discipline remains essential, particularly in polyester-heavy segments where price competition is intensifying. Manufacturers should also consider mono-material approaches where they can simplify downstream processing and improve circularity claims without compromising performance.
For investors, the market offers attractive but uneven exposure. The strongest near-term value creation is likely to come from companies with clear sustainability differentiation, strong commercial specification relationships, and the ability to manage feedstock volatility. Capacity expansion alone is unlikely to guarantee outsized returns unless it is tied to a specific application advantage or regional demand opportunity. Due diligence should focus on feedstock positioning, recycled content readiness, technology access, and the durability of customer relationships in high-specification segments.
For procurement and sourcing leaders, diversification and specification clarity are critical. Relying on a single material type or supplier increases exposure to feedstock cycles and regulatory shifts. Building a sourcing strategy that balances cost, performance, and recycled content across nylon, polyester, and polypropylene can improve resilience while meeting evolving customer requirements. It is equally important to validate performance claims early in the specification process, especially when introducing recycled yarns into demanding commercial or automotive applications. For organizations that need detailed segmentation data, regional supply mappings, and customized scenario planning, the full PW Consulting research report provides deeper granularity and tailored recommendations for specific portfolio and market decisions.
For detailed analysis of this topic, please visit the official page: Bulk Continuous Filament Carpet Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Indoor Wall Decoration Paint Market: Why 5.45% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Indoor Wall Decoration Paint Market
Market Landscape and Core Challenges
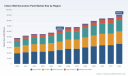
The indoor wall decoration paint market is undergoing a period of measured but consistent expansion, driven by sustained construction activity, evolving consumer expectations, and tightening environmental standards. From 2020 to 2025, the industry demonstrated resilience through cycles of economic fluctuation, with total revenue climbing steadily to surpass sixty-two billion dollars by the 2025 base year. Looking ahead, the market is projected to grow at a compound annual rate of approximately 5.45 percent through 2032, reaching an estimated valuation of over ninety billion dollars by the close of the forecast horizon. This trajectory reflects a mature yet evolving sector where growth is increasingly tied to product innovation, regulatory compliance, and regional demand shifts rather than volume expansion alone.
Several structural challenges are reshaping how manufacturers, distributors, and end-users navigate this space. First, the regulatory landscape has become increasingly complex and fragmented across major markets. New mandatory standards governing volatile organic compound limits, hazardous substance restrictions, and compulsory certification requirements are forcing manufacturers to reformulate products, adjust production processes, and invest in compliance infrastructure. While these measures align with broader sustainability goals, they introduce short-term cost pressures and create barriers for smaller players lacking the technical and financial resources to adapt quickly. Second, the industry continues to grapple with raw material volatility. Key inputs such as titanium dioxide, a critical pigment for coverage and finish quality, have experienced notable price fluctuations in recent periods, directly impacting margin stability and pricing strategies for formulators. Third, shifting demand patterns are compelling companies to balance volume-driven residential construction cycles with higher-margin specialty and commercial applications, requiring more agile portfolio management and channel strategies.
PW Consulting Chemical & Energy Research Center
Competitive Concentration and Market Dynamics
The market remains moderately concentrated, with the top three players capturing a significant share of total revenue and the top five collectively accounting for just over half of industry sales. This concentration level suggests that scale advantages, brand recognition, and distribution networks continue to provide meaningful competitive insulation. However, the structure also indicates room for targeted disruption, particularly in segments where performance differentiation, localized formulation capabilities, or direct-to-consumer engagement models can unlock value outside the dominant incumbents. Companies that can align product innovation with regulatory readiness and cost discipline are best positioned to convert market growth into sustained profitability.
Core Drivers Shaping Market Evolution
Technological Innovation and Formulation Advances
Product innovation remains one of the most powerful levers for differentiation in this market. Leading manufacturers have progressively shifted their R&D focus toward water-based systems that deliver superior coverage, improved scrub resistance, and enhanced color retention without compromising environmental performance. One-coat application capabilities, stain-blocking formulations, and low-odor emulsions have moved from premium niche offerings to mainstream expectations, particularly in residential and light commercial settings. Advanced additive technologies are also enabling functional benefits such as anti-fungal properties, air-purifying characteristics, and moisture resistance, which resonate strongly with end-users concerned about indoor air quality and long-term maintenance costs. Companies that integrate these performance attributes with consistent finish quality and ease of application are capturing incremental share, especially in markets where renovation and upgrade cycles are accelerating.
The emphasis on low-VOC and eco-friendly formulations has evolved from a compliance exercise into a competitive necessity. Formulators are leveraging advanced resin technologies and pigment dispersion methods to achieve high opacity and washability while meeting stringent emissions thresholds. This technical progress is particularly relevant as regulatory bodies across multiple regions tighten allowable limits on volatile organic compounds, semi-volatile compounds, formaldehyde, benzene, and heavy metals. Manufacturers that have invested early in reformulation pipelines and testing infrastructure are converting compliance requirements into market-facing advantages, positioning their products as safer, cleaner, and more future-proof options for both professional applicators and DIY consumers.
Policy and Regulatory Environment
Regulatory developments are exerting a decisive influence on product architecture, market access, and competitive positioning. In China, new mandatory national standards governing hazardous substance limits in architectural coatings are set to take effect, replacing earlier frameworks with stricter thresholds across multiple chemical categories. This shift is complemented by compulsory certification requirements for water-based interior wall paints, adding an additional layer of scrutiny to product approvals and supply chain documentation. These measures are accelerating the phase-out of older solvent-heavy formulations and pushing both domestic and international players to localize their compliance strategies.
Across Europe, decorative paint and varnish regulations cap VOC content within defined ranges to reduce ozone-forming emissions, reinforcing demand for low-emission interior wall coatings and encouraging cross-border alignment on sustainability benchmarks. In the United States, stringent VOC limits for architectural coatings, particularly in leading states such as California, continue to shape formulation trends nationwide. Flat interior paints face tighter ceilings than non-flat products, compelling manufacturers to balance performance expectations with regulatory constraints. Collectively, these regulatory trajectories are narrowing the window for legacy formulations and rewarding companies that can demonstrate consistent compliance, transparent ingredient disclosure, and verifiable environmental benefits.
Demand-Side Shifts and Consumer Behavior
Demand patterns are increasingly shaped by a combination of housing market dynamics, renovation activity, and heightened awareness of indoor environmental quality. Residential construction continues to represent the largest application segment, with homeowners and renters prioritizing finishes that combine aesthetic appeal, durability, and ease of maintenance. At the same time, commercial building operators are seeking wall decoration solutions that support tenant retention, reduce lifecycle maintenance costs, and align with green building certifications. Educational and healthcare facilities represent a growing niche where hygiene, low odor, and washability are non-negotiable requirements, creating steady demand for specialized interior coatings.
Consumer expectations are also shifting toward premiumization in key demographics. Buyers are increasingly willing to pay a premium for paints that deliver richer color depth, superior stain resistance, and one-coat coverage, particularly in high-visibility areas such as living rooms, entryways, and commercial interiors. This trend is encouraging manufacturers to expand their premium and super-premium portfolios, while simultaneously pushing value-tier offerings to emphasize functional clarity, reliable performance, and accessible pricing. The result is a more segmented demand landscape where product positioning, channel strategy, and technical communication all play critical roles in capturing the right audience.
Supply Chain and Cost Structure Dynamics
Cost structures in the indoor wall decoration paint market are being reshaped by upstream input volatility and evolving logistics realities. Titanium dioxide, the primary pigment responsible for opacity and coverage, experienced a notable price decline in China during 2025, ending the year at a level that provided some relief to formulators after earlier periods of pressure. While such movements can improve short-term margin flexibility, they also introduce planning complexity, as pricing can reverse quickly in response to supply disruptions, energy costs, and regional demand shifts. Companies that maintain diversified supplier networks, implement strategic inventory buffers, and incorporate flexible pricing mechanisms are better equipped to manage these fluctuations without eroding customer confidence.
Beyond raw materials, supply chain resilience has become a strategic priority. Regulatory changes, certification requirements, and regional compliance standards are forcing manufacturers to strengthen documentation, quality control, and production traceability. At the same time, the growing importance of both professional and retail channels is driving investments in packaging, color matching systems, and application support tools that reduce waste and improve end-user outcomes. Firms that integrate cost discipline with channel-specific value propositions are gaining an edge in a market where price competition alone is rarely sufficient to sustain long-term advantage.
Competitive Landscape and Leading Strategies
Strategic Positioning of Key Players
The competitive field is defined by a mix of global incumbents and regionally dominant specialists, each pursuing distinct pathways to differentiation. Large multinational players are leveraging broad product portfolios, extensive distribution networks, and brand equity to maintain presence across residential, commercial, and specialty segments. Several of these companies have built reputations around premium acrylic latex systems that emphasize superior coverage, scrubbability, and low-VOC formulations, often supported by one-coat application claims and professional-grade color matching services. Their scale enables continued investment in formulation technology, compliance infrastructure, and marketing reach, reinforcing their position in both developed and high-growth markets.
Regional leaders are competing with a different playbook, focusing on localized market knowledge, tailored product lines, and deep relationships with contractors, retailers, and end-users. In Asia, for example, dominant players have built strong associations with luxury finishes, stain repellency, and water-beading technologies, while also expanding low-VOC and washable emulsion offerings to meet evolving sustainability expectations. Other regional specialists have differentiated through functional coatings that address specific pain points such as anti-fungal performance, odor reduction, and easy-clean surfaces, making their products particularly attractive in humid climates and high-traffic environments. Specialist and value-oriented brands, meanwhile, are carving out share through retail-focused formulations that balance one-coat coverage, stain-blocking, and accessible pricing, appealing to DIY consumers and budget-conscious professional buyers alike.
Differentiation Advantages and Capability Gaps
Across the competitive set, companies that consistently outperform tend to share several capability advantages. Strong formulation expertise enables them to deliver high opacity, color depth, and durability while meeting regulatory thresholds. Robust quality assurance and certification readiness allow faster market access in jurisdictions with strict compliance requirements. Effective channel management ensures that products reach both professional applicators and retail consumers with appropriate technical support, color selection tools, and application guidance. Brand trust and consistent finish quality further reinforce repeat purchases and professional recommendations, which remain influential in a category where visual results and long-term performance matter deeply to end-users.
Conversely, gaps in these areas create vulnerability. Manufacturers that lag in low-VOC reformulation, lack transparent certification pathways, or rely too heavily on legacy solvent-based systems face increasing risk as regulations tighten and buyer preferences shift. Companies that fail to invest in application support, color consistency, or retail experience may struggle to justify premium pricing or defend against competitors offering comparable performance at lower cost. In a market with moderate concentration, such gaps can be exploited by rivals with more agile product development cycles or stronger regional execution.
Evolving Market Structure and Entry Dynamics
The market structure is gradually evolving along two parallel tracks: consolidation among scale players seeking broader geographic and segment coverage, and fragmentation in niche or high-growth regions where localized expertise and functional specialization create openings for focused competitors. M&A activity, brand portfolio optimization, and distribution partnerships are likely to shape the next phase of industry evolution, particularly as companies look to strengthen their presence in high-growth regions and expand into premium or specialty decorative coatings. At the same time, new entrants and smaller regional brands can still gain traction by targeting underserved application needs, leveraging digital color visualization tools, or building direct engagement models that resonate with modern consumers. The result is a dynamic landscape where scale provides advantages, but execution quality, regulatory readiness, and customer-centric innovation determine who captures disproportionate value.
Future Trends and Forward Outlook
Accelerated Adoption of Low-Emission and Functional Coatings
Over the next three to five years, low-emission interior wall coatings are expected to move from a compliance-driven requirement to a baseline market expectation. As regulatory thresholds tighten across major regions and buyer awareness of indoor air quality continues to rise, formulators will increasingly prioritize water-based systems that combine high performance with reduced environmental impact. Functional benefits such as stain resistance, anti-fungal protection, odor control, and air-purifying properties will become more common across premium and mid-tier portfolios, not just specialty lines. This trend creates opportunities for companies that can communicate verifiable performance benefits, maintain consistent finish quality, and align product claims with recognized certification or testing standards.
Premiumization and Segment-Specific Portfolio Strategies
Demand segmentation is likely to deepen, with residential, commercial, and institutional applications drawing increasingly distinct product requirements and purchasing criteria. In residential settings, homeowners and renovators will continue to seek finishes that deliver visual richness, easy maintenance, and application convenience, supporting continued premiumization in color depth, coverage, and durability. Commercial and institutional buyers will place greater weight on lifecycle costs, hygiene performance, and alignment with green building standards, favoring coatings that reduce repainting frequency and support indoor environmental quality goals. Manufacturers that develop segment-specific portfolios rather than relying on one-size-fits-all offerings will be better positioned to capture margin and defend share in a maturing market.
Cost Volatility, Compliance Investment, and Strategic Risk
Despite the favorable growth outlook, several uncertainty factors warrant attention. Raw material pricing can shift quickly, particularly for key pigments and resins, creating margin volatility that requires disciplined procurement and pricing strategies. Regulatory complexity is likely to increase rather than stabilize, with more jurisdictions introducing stricter VOC limits, hazardous substance restrictions, and mandatory certification processes. Companies that delay compliance investments or depend on outdated formulations risk lost market access, reputational exposure, and higher reformulation costs later. Additionally, macroeconomic fluctuations in construction and renovation activity can create uneven demand cycles, making portfolio flexibility and channel diversification important risk mitigation tools. The central strategic question for leaders will be how to balance cost efficiency, compliance readiness, and product differentiation in a market where all three dimensions interact continuously.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
Invest early in low-VOC and water-based formulation capabilities, and treat compliance as a competitive advantage rather than a cost center. Prioritize product lines that combine high coverage, durability, and functional benefits with clear, verifiable environmental claims. Strengthen quality assurance and certification readiness to accelerate market access in regions with tightening standards, and consider portfolio segmentation that aligns premium, mid-tier, and value offerings with distinct use cases and channels. Finally, review supplier diversification and inventory planning for critical inputs to reduce exposure to raw material price swings.
Interior Stain Market
For Investors and Strategic Buyers
Evaluate companies based on their formulation pipeline, regulatory readiness, regional execution strength, and ability to capture premiumization trends without overrelying on price competition. Look for players with strong brand positioning in water-borne and specialty decorative coatings, as well as those demonstrating disciplined cost management and channel flexibility. In consolidation scenarios, assess whether target companies bring complementary geographic reach, technical capabilities, or segment expertise that can accelerate growth in high-value applications. Pay close attention to compliance infrastructure and certification status, since these factors increasingly influence market access and brand trust.
For Procurement and Channel Decision-Makers
Prioritize suppliers that can demonstrate consistent color performance, low-emission compliance, and application reliability across residential, commercial, and institutional projects. Request clear documentation on VOC limits, certification status, and product performance claims, especially when specifying finishes for healthcare, education, or green building projects. Balance premium options for high-visibility areas with value-tier solutions for routine refresh cycles, and work with partners who offer robust color matching, technical support, and waste-reducing application guidance. Building a diversified supplier base can also help mitigate pricing volatility and ensure continuity as regulatory requirements evolve.
The indoor wall decoration paint market is entering a phase where growth is increasingly tied to product performance, regulatory alignment, and segment-specific execution. Companies and investors that maintain disciplined focus on formulation quality, compliance readiness, and customer-centric innovation will be best positioned to navigate the next wave of market change. For decision-makers seeking deeper segmentation data, regional dynamics, and tailored scenario planning, the full research report provides expanded detail and actionable frameworks to support strategic planning.
Paint Market
For detailed analysis of this topic, please visit the official page: Indoor Wall Decoration Paint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Germacrene D Market 5.02% CAGR: Why Fragrance Demand Drives $29.3M Growth by 2032
By pmarketresearch, 2026-09-18
Germacrene D Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for Germacrene D has demonstrated consistent expansion over the past five years, moving from approximately $16.5 million in 2020 to an estimated $20.8 million in 2025. This trajectory reflects a compound annual growth rate of 5.02 percent, with projections indicating the market will reach $29.3 million by 2032. The steady upward curve underscores growing industrial reliance on specialized sesquiterpenes across multiple application verticals. However, beneath these aggregate figures lies a complex landscape shaped by supply chain vulnerabilities, regulatory evolution, and shifting consumer expectations.
One of the most pressing challenges facing market participants is the convergence of raw material volatility and sustainability mandates. Germacrene D is primarily sourced as a sesquiterpene from essential oils of plants such as Solidago canadensis or produced via microbial fermentation from renewable sugar-based feedstocks. Both pathways carry distinct risk profiles. Botanical extraction is subject to agricultural yield fluctuations, climate variability, and land-use constraints, while fermentation-based routes demand capital-intensive bioreactor infrastructure and face scaling bottlenecks. Companies must navigate these dual supply realities while maintaining cost competitiveness and meeting increasingly stringent environmental standards.
A second critical inflection point involves the tightening regulatory framework governing fragrance and flavor ingredients. Recent safety assessments have clarified the risk profile of Germacrene D, with a 2024 evaluation concluding no genotoxicity or skin sensitization concerns at current declared fragrance use levels. While this provides regulatory certainty, it also raises the bar for documentation, traceability, and compliance verification. Suppliers must invest in robust quality management systems and maintain alignment with evolving standards such as EU Regulation (EC) No 1334/2008 and US CFR 101.22 for natural flavor use. The burden of compliance disproportionately affects smaller manufacturers, potentially accelerating market consolidation.
A third structural challenge lies in balancing purity requirements across divergent application segments. The market spans natural extract grades with specified purity levels alongside high-purity reagent grades used in research and specialized formulations. Each grade demands distinct production protocols, validation procedures, and customer engagement models. Manufacturers that attempt to serve both segments without clear operational segmentation risk margin erosion, quality inconsistencies, or brand positioning conflicts. The ability to cleanly separate production streams and communicate value propositions to different buyer personas has become a decisive competitive factor.
Key Drivers of Market Evolution
Technological Innovation and Fermentation Breakthroughs
Advancements in microbial fermentation have fundamentally altered the supply dynamics of Germacrene D. Fermentation-based production enables consistent output independent of seasonal agricultural cycles, reduces reliance on land-intensive crop cultivation, and aligns with circular economy principles when paired with renewable sugar feedstocks. Several industry participants have demonstrated that carefully optimized bioprocesses can achieve purity levels suitable for flavor and fragrance applications while maintaining certifications such as kosher, halal, and pesticide-free status. These capabilities expand the addressable market by offering formulators a reliable, scalable alternative to botanical extraction, particularly in regions where agricultural supply chains face disruption or where traceability requirements are intensifying.
Beyond production methods, downstream formulation technologies are also shaping demand. The integration of Germacrene D into complex fragrance architectures requires precise understanding of its olfactory profile, stability characteristics, and interaction with other aroma chemicals. Suppliers that invest in application labs, sensory evaluation capabilities, and technical support services create stickier customer relationships and command premium positioning. This shift from commoditized molecule supply to integrated solution provision represents a meaningful margin opportunity for organizations willing to build technical depth.
Regulatory Clarity and Certification Momentum
Regulatory developments have moved from ambiguous risk discussions to more definitive safety conclusions, providing a foundation for confident commercialization. The affirmation of a FEMA GRAS number and compliance with major food and fragrance regulations reduce barriers to adoption in end-use products. Concurrently, certification renewals and expansions, such as the renewal of kosher certification for fermentation-derived Germacrene D through early 2026, signal ongoing commitment to dietary and religious compliance standards that matter to global brand owners.
These regulatory and certification dynamics are not merely compliance exercises; they function as market access enablers. Multinational consumer goods companies require ingredient suppliers to demonstrate harmonized compliance across multiple jurisdictions. Suppliers that proactively maintain and document certifications across EU, US, and international frameworks reduce friction in the procurement process and become preferred partners for large-scale formulation projects. The regulatory environment thus rewards completeness and transparency over speed-to-market alone.
Demand-Side Shifts Toward Natural and Sustainable Ingredients
Consumer and brand preferences continue to gravitate toward natural-origin and sustainably sourced ingredients. In the fragrance and personal care sectors, this trend drives formulators to seek sesquiterpenes that can deliver characteristic woody-spicy, minty, or herbal notes while meeting clean-label expectations. The commercial appeal extends beyond marketing narratives; it influences procurement specifications, supplier qualification criteria, and long-term contract structures. Brands are increasingly willing to pay a premium for ingredients that combine verified natural status with reliable supply and consistent sensory performance.
Parallel demand is emerging from agricultural pheromone applications, where Germacrene D serves as a component in insect attractant and mating disruption formulations. This segment benefits from broader agricultural trends emphasizing reduced synthetic pesticide reliance and integrated pest management strategies. While smaller in absolute terms compared to fragrance and cosmetics, the agricultural pheromone segment offers diversification benefits and growth potential tied to regulatory pressure on conventional agrochemicals and expanding adoption of biocontrol methods.
Supply Chain Restructuring and Cost Dynamics
Cost structures in the Germacrene D market are being reshaped by logistics complexity, energy input requirements, and the economics of scale. Fermentation-based routes, while offering supply stability, involve significant upfront capital expenditure and operational expertise in bioprocess engineering. Botanical extraction pathways face fluctuating input costs tied to crop yields and geographic sourcing constraints. In both cases, organizations that achieve scale, optimize yield per unit of input, and streamline downstream purification can establish meaningful cost advantages.
Farnesene Market
Supply chain resilience has also become a strategic priority. Buyers are increasingly evaluating suppliers not only on price and purity but on geographic diversification, inventory buffering capabilities, and contingency planning. The market concentration, with the top three participants holding a modest share and the top five capturing a slightly larger portion, indicates room for both specialized niche players and larger diversified ingredient companies. This fragmentation creates opportunities for regional suppliers to secure local partnerships while inviting larger entities to pursue selective acquisitions that broaden geographic reach and technical portfolios.
Competitive Landscape and Leading Strategies
Differentiation Through Positioning and Technical Capability
Market participants have adopted distinct strategic postures that reflect their organizational capabilities and target customer segments. Some companies emphasize fermentation-derived natural Germacrene D with comprehensive dietary and regulatory certifications, positioning themselves as reliable partners for flavor and fragrance formulators who require clean-label compliance and consistent supply. This approach combines biotechnological manufacturing with rigorous quality documentation, appealing to brand owners who prioritize transparency and auditability.
Other organizations focus on high-purity reagent and fragrance-grade products packaged for industrial and research use. These suppliers cater to application development, analytical testing, and specialized formulation work, where purity specifications and packaging integrity take precedence over natural-origin claims. By maintaining strict quality controls and offering flexible packaging options, these participants serve a different buyer persona that values technical precision and rapid availability over certification breadth.
Large flavor and fragrance houses with diversified botanical extraction capabilities include Germacrene D within broader portfolios of natural-origin ingredients. Their strategic advantage lies in integrated supply chains, established customer relationships, and the ability to offer formulation guidance alongside raw material supply. For these organizations, Germacrene D is one element of a larger sustainable sourcing narrative, supported by eco-friendly extraction practices and long-standing botanical expertise. Their scale and brand recognition provide credibility with multinational clients, while their portfolio breadth allows cross-selling and formulation synergy.
Recent Strategic Moves and Market Signals
Recent industry activity highlights how participants are sharpening their competitive positioning. A fermentation-based supplier renewed kosher certification for its natural Germacrene D product, reinforcing its commitment to dietary compliance and maintaining eligibility for markets where such certification is a procurement prerequisite. This type of certification maintenance may appear routine, but it signals ongoing operational discipline and protects market access in segments where religious and dietary standards influence purchasing decisions.
A major global fragrance and flavor company introduced a Germacrene D-based fragrance ingredient as part of an expanded natural-origin portfolio. This launch illustrates the use of targeted molecule development to refresh ingredient offerings, respond to formulator demand for specific olfactory profiles, and reinforce sustainability messaging. By embedding Germacrene D within a broader portfolio narrative, the company leverages the molecule's sensory characteristics while aligning with brand-level commitments to natural sourcing.
Another significant move involved a strategic partnership between two ingredient companies to co-develop sustainable fragrance ingredients, including Germacrene D, with an emphasis on resilient natural sourcing. Collaborative development arrangements allow participants to share technical risk, pool botanical or bioprocess expertise, and accelerate time-to-market for improved ingredients. Such partnerships also reflect an industry-wide recognition that sustainability and supply resilience are not easily achieved in isolation; they often require joint investment in sourcing relationships, process optimization, and certification alignment.
Sclareolide Market
Market Structure Evolution
The competitive landscape is undergoing gradual transformation rather than abrupt disruption. Market concentration remains moderate, indicating that no single entity dominates supply and that differentiated positioning can still yield viable market share. Over the forecast horizon, several dynamics are likely to shape structure. Larger ingredient companies may pursue selective acquisitions to fill technical gaps, expand geographic coverage, or bring fermentation capabilities in-house. Specialized manufacturers with unique purity profiles, certification portfolios, or regional sourcing advantages can maintain strong niche positions by serving customers who value specificity over breadth. New entrants with novel bioprocess technologies or alternative feedstock strategies may emerge if they can demonstrate cost parity, regulatory compliance, and scalable production.
The overall trend points toward a market where value creation shifts from volume-only competition to capability-based differentiation. Suppliers that combine reliable production, regulatory completeness, technical support, and sustainability credentials will be better positioned to command favorable terms and build long-term partnerships. Conversely, participants that compete solely on price without clear quality or compliance differentiation may face margin pressure as buyers increasingly weigh total cost of ownership and supply risk.
PW Consulting Chemical & Energy Research Center
Future Trends and Commercial Implications
Convergence of Natural Certification and Biotechnological Scale
Over the next three to five years, the intersection of natural-certification requirements and fermentation scalability will likely become a central theme. As formulators seek ingredients that satisfy both sensory expectations and sustainability mandates, suppliers capable of delivering certified natural-status molecules through reproducible bioprocesses will capture growing demand. The commercial opportunity lies in offering a credible alternative to botanically sourced sesquiterpenes while maintaining documentation that satisfies global regulatory and consumer expectations. Organizations that invest early in process optimization, certification breadth, and supply transparency can establish defensible positions before the segment becomes crowded.
Expansion of Application Diversification
Application diversification represents another meaningful trend. While fragrance and cosmetics continue to anchor demand, agricultural pheromone formulations and specialized research uses provide adjacent growth avenues. The agricultural segment, in particular, benefits from structural shifts toward reduced synthetic pesticide reliance and increased adoption of behavioral pest control methods. Suppliers that develop technical expertise in pheromone formulation requirements, stability testing, and field-performance considerations can extend their reach beyond traditional aroma chemical markets. This diversification also serves as a hedge against cyclicality in consumer-facing fragrance spending, smoothing revenue profiles across economic cycles.
Regulatory and Compliance Sophistication as Competitive Moat
Regulatory sophistication will increasingly function as a competitive moat rather than a baseline requirement. As safety assessments solidify and certification frameworks mature, the ability to maintain harmonized compliance across jurisdictions becomes a differentiator. Buyers will favor suppliers that provide clear documentation, predictable audit outcomes, and proactive engagement with evolving standards. The risk side of this trend involves the possibility of regulatory divergence across regions or the emergence of new substance-specific requirements that challenge existing production or labeling practices. Companies that monitor regulatory developments closely and maintain flexible quality systems will be better prepared to adapt without disrupting customer supply.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient suppliers, the priority is to clarify segment focus and align operational capabilities with the value propositions that matter most to target customers. Companies serving fragrance and flavor formulators should invest in certification maintenance, application support, and supply transparency. Those focused on high-purity reagent or research-grade markets should emphasize quality control rigor, packaging integrity, and technical documentation. In both cases, building a clear narrative around sourcing, production method, and compliance status helps reduce customer uncertainty and supports pricing discipline.
Investors evaluating opportunities in this space should weigh the balance between scale advantages and specialization premiums. Larger diversified ingredient platforms offer portfolio breadth and customer relationships that can absorbGermacrene D within broader sustainable sourcing strategies. Specialized participants with differentiated fermentation capabilities, certification portfolios, or regional sourcing strengths may offer attractive growth profiles if they can demonstrate reproducible quality and market access. Due diligence should examine production scalability, regulatory standing, customer concentration, and the durability of any purity or certification advantages.
For procurement leaders and formulation teams, supplier selection should extend beyond unit price to encompass compliance documentation, supply resilience, technical support, and long-term sourcing strategy. Engaging suppliers that can articulate their production method, certification status, and continuity planning reduces downstream risk and facilitates smoother product development cycles. Early involvement of ingredient suppliers in formulation projects can also surface technical considerations before they become costly redesigns.
Market participants and investors seeking detailed segmentation data, competitive benchmarking, and customized scenario analysis will find value in consulting the complete research report, which provides deeper breakdowns of regional dynamics, purity-grade trends, application-specific demand patterns, and firm-level strategic profiles.
For detailed analysis of this topic, please visit the official page: Germacrene D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
FAI Market: Why 28.42% CAGR and Perovskite Solar Cells Redefine Growth
By pmarketresearch, 2026-09-18
Strategic Horizons: Decoding the Formamidinium Iodide (FAI) Market Dynamics and Opportunities
Market Overview: A Sector in Rapid Transition
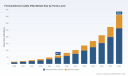
The Formamidinium Iodide (FAI) market has evolved from a niche material supply chain into a critical enabler of next-generation opto-electronic and photovoltaic technologies. Over the historical review period, the sector demonstrated consistent expansion, reflecting the accelerating adoption of perovskite-based architectures across energy and electronics applications. Current market valuation stands at a significant milestone, with trajectory models projecting sustained growth through the end of the forecast horizon. The compounding annual growth rate underscores a structural shift rather than a cyclical upturn, driven by the material's unique position as a high-performance precursor for formamidinium lead iodide perovskites.
PW Consulting Chemical & Energy Research Center
From an industry standpoint, this expansion is not uniform. Demand is concentrated among segments requiring stringent material specifications, particularly ultra-high purity grades that meet the exacting tolerances of advanced device fabrication. The market's value distribution reflects a clear hierarchy where premium-grade materials command disproportionate share, signaling that performance differentiation and reliability are becoming primary commercial differentiators. This concentration also indicates that early movers who established production capabilities for specialized grades have secured defensible positions, while late entrants face higher barriers to achieving comparable quality benchmarks.
Despite the favorable trajectory, the sector faces structural headwinds that will shape competitive outcomes. First, the pharmaceutical and electronic-grade classification frameworks are tightening around iodine-containing compounds, introducing compliance complexity and cost escalation that vary sharply by jurisdiction. Second, the transition from laboratory-scale synthesis to industrial-grade consistency remains a friction point; maintaining ultra-low moisture content and batch-to-batch reproducibility at scale requires capital-intensive process controls that not all manufacturers have mastered. Third, the raw material base for high-purity production carries inherent cost premiums, with advanced purification techniques adding meaningful expense layers compared to standard-grade output. These challenges are not insurmountable, but they demand strategic foresight in capacity planning, regulatory navigation, and vertical integration decisions.
Key Drivers Reshaping the FAI Landscape
Several interdependent forces are accelerating market evolution, each carrying distinct implications for production strategies, pricing dynamics, and demand forecasting.
Worldwide Rhodium(III) Iodide Market
Technological Innovation and Performance Gradients
The core technological driver lies in the material science advantages that FAI enables. When integrated into perovskite architectures, formamidinium-based compounds exhibit narrower bandgaps compared to earlier methylammonium analogs, translating into improved solar conversion efficiencies and broader spectral absorption. This performance gradient has made FAI a preferred precursor for high-efficiency photovoltaic research and commercialization pathways. Simultaneously, advances in deposition techniques and encapsulation strategies are reducing historical degradation concerns, expanding the viable application envelope. Manufacturers are responding by refining synthesis protocols that minimize impurity profiles and moisture ingress, recognizing that even trace deviations can compromise device longevity and performance consistency.
Regulatory and Classification Dynamics
Regulatory frameworks are reshaping supply chain economics in measurable ways. Several jurisdictions have introduced stricter oversight of iodine-containing compounds, with certain precursor classifications triggering additional handling, documentation, and compliance requirements. These measures add meaningful expense layers to production in affected regions, influencing where capacity is sited and how materials are routed to end users. Companies that proactively align manufacturing processes with evolving classification standards, invest in transparent supply chain traceability, and maintain robust regulatory affairs capabilities are better positioned to absorb compliance costs without sacrificing competitive pricing. Conversely, operators treating regulatory adaptation as reactive face margin compression and potential supply disruptions.
Demand-Side Shifts and Application Diversification
Demand patterns are broadening beyond early research channels into pilot production and early commercial deployments. The perovskite solar cell segment remains the dominant consumption driver, reflecting sustained investment in tandem cell architectures and efficiency roadmaps that target commercial viability milestones. Alongside this, perovskite light-emitting diodes and photodetector applications are cultivating additional demand nodes, though at smaller absolute scales. End users are increasingly prioritizing material consistency, technical documentation, and supply reliability over pure price competition, recognizing that material variability can cascade into yield losses and performance inconsistencies at integrated manufacturing levels.
Cost Structure Evolution and Supply Chain Adjustments
The cost architecture of FAI production is undergoing recalibration. Achieving ultra-high purity grades demands specialized techniques that elevate manufacturing expenses relative to standard grades, creating a clear value gradient that informed buyers are willing to pay for. At the same time, supply chain participants are exploring vertical integration, localized sourcing of iodine derivatives, and process intensification to mitigate cost volatility. The interplay between raw material availability, purification complexity, and scale economies is producing a bifurcated market where premium-grade producers capture stronger margins, while standard-grade segments face intensifying price competition. Strategic capacity allocation, therefore, hinges on aligning production grades with target customer segments and securing reliable input streams that can sustain quality at volume.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field spans a diverse set of players, from specialized material manufacturers focusing exclusively on perovskite precursors to broader chemical and electronics suppliers offering FAI as part of wider product portfolios. This diversity shapes how competition unfolds and where strategic advantages crystallize.
Leading manufacturers have carved distinct positioning strategies. Specialized producers emphasize ultra-high purity thresholds, extremely low moisture content, and in-house production capabilities that allow them to control quality from synthesis through packaging. These operators often market directly to research institutions and early-stage device manufacturers, building reputation through consistent material performance and technical support. Their differentiation rests on reproducibility, documentation rigor, and the ability to supply quantities ranging from grams for R&D to kilogram-scale batches for pilot lines.
Dye Sensitized Solar Cell Market
Larger or multinational suppliers leverage complementary strengths. Some bring established distribution networks, flexible packaging options spanning bench-scale to industrial volumes, and the capacity to support customers across development stages. Others integrate FAI into broader portfolios of electronic and photovoltaic precursors, offering procurement convenience and cross-material sourcing advantages. These players benefit from brand recognition, logistical infrastructure, and the ability to bundle materials for complex device fabrication workflows. Their competitive edge often lies in service breadth, global reach, and the perceptions of reliability that come with established institutional presence.
Regional manufacturers, particularly in China and across Asia Pacific, contribute significant volume and are increasingly investing in purification technologies and quality certifications. Their participation has expanded accessible supply and introduced competitive pressure on pricing, especially in standard and high-purity tiers. This dynamic encourages broader industry maturation, but it also raises the importance of verification, certification, and technical specification alignment for end users seeking consistent performance.
Market structure is evolving along several axes. Consolidation pressures are emerging as larger entities seek to secure reliable precursor supply chains and as specialized producers explore partnerships or acquisitions to scale capacity and broaden technical capabilities. At the same time, fragmentation persists at the research-grade level, where numerous suppliers serve niche demand with varying specification sets. New entrants are assessing opportunities where existing supply falls short of ultra-high purity, moisture control, or regulatory compliance expectations. The net effect is a market that rewards clarity of positioning: operators that define their grade focus, customer segment, and compliance posture with precision are better equipped to sustain margins and defend against commoditization.
Future Outlook: Trends and Commercial Implications (2026-2032)
Looking ahead, three trends are likely to define the next phase of market development and shape where commercial value accrues.
Premium-grade specialization will deepen. As device architectures push efficiency and stability targets, the premium attached to ultra-high purity and ultra-low moisture specifications will intensify. Suppliers that can reliably deliver these grades at scale, backed by verifiable quality documentation and process control, will capture disproportionate demand from high-value applications. The cost premium associated with advanced purification is unlikely to erode; instead, it will become a recognized and accepted component of total device economics, reinforcing segmentation between premium and standard tiers.
Regulatory alignment will become a competitive lever. Classification and handling requirements for iodine-related compounds will continue to influence sourcing decisions. Companies that proactively integrate compliance into their operational design, maintain transparent audit trails, and offer regionally compliant supply routes will reduce friction for downstream customers. This creates an operational advantage that extends beyond cost, affecting procurement confidence, risk management, and long-term partnership stability.
Application diversification will broaden demand nodes while solar remains central. Perovskite solar cells will continue to anchor volume growth, but light-emitting diodes, photodetectors, and specialized opto-electronic uses will add incremental demand streams. This diversification does not diminish the centrality of photovoltaic demand; rather, it creates multiple growth vectors that can buffer sector volatility and open cross-selling opportunities for suppliers with broad capability sets. End users will increasingly seek partners who can support varied application requirements without compromising material consistency.
These trends carry commercial opportunities, but also uncertainties. Scale-up challenges, raw material availability, and the pace at which regulatory frameworks settle across regions will influence how quickly new capacity translates into reliable supply. Buyers should anticipate continued differentiation in specification quality and service models, while suppliers should plan for a landscape where technical performance, compliance readiness, and supply reliability matter as much as price.
Strategic Actions for Decision-Makers
For manufacturers, the priority is aligning production capacity with the grade segments that command durable demand. Investing in purification consistency, moisture control, and verifiable quality documentation will strengthen positioning in premium tiers where differentiation translates into margin resilience. At the same time, maintaining flexible packaging and scale options allows suppliers to serve both research and pilot-commercial customers without compromising quality standards.
For investors, the opportunity lies in identifying operators with clear technical differentiation, robust compliance capabilities, and credible pathways to scale. Evaluate production processes, certification status, customer concentration, and regional risk exposure rather than relying solely on top-line growth narratives. Companies that can demonstrate reproducible ultra-high purity output and navigate regulatory complexity are better positioned to capture sustained demand as the market matures.
For procurement and sourcing teams, the focus should shift from unit price toward total value, including specification reliability, documentation quality, supply continuity, and compliance alignment. Establishing clear material requirements, verifying batch consistency, and engaging suppliers with transparent quality systems will reduce downstream risk and support manufacturing yield stability. As the market expands and segmentation sharpens, sourcing strategies that prioritize performance assurance and regulatory readiness will deliver stronger long-term outcomes.
For stakeholders seeking granular segmentation data, regional supply dynamics, pricing benchmarks across purity tiers, and customized scenario analysis, the full research report provides detailed breakdowns and actionable frameworks to inform planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Formamidinium Iodide (FAI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
POE Synthetic Materials Market: Why 9.5% CAGR Reshapes Global Competition Through 2032
By pmarketresearch, 2026-09-18
Navigating the Polyolefin Elastomer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global polyolefin elastomer (POE) market has entered a phase of accelerated structural growth, with total revenue climbing from approximately $2.75 billion in 2020 to a projected $4.2 billion in 2025. This upward trajectory is expected to sustain a compound annual growth rate of 9.5 percent through 2032, pushing the market toward the $7.9 billion mark. The expansion reflects a broader industrial shift toward high-performance, lightweight, and durable polymeric materials that can replace heavier or less versatile alternatives across demanding applications.
Despite the favorable momentum, three structural challenges are reshaping how manufacturers, converters, and downstream buyers approach the POE value chain. First, feedstock volatility remains a persistent earnings and pricing risk. Production costs are heavily influenced by ethylene, propylene, and alpha-olefin derivatives, with pricing swings tied to crude oil movements, refinery maintenance cycles, and regional demand imbalances. A notable example occurred in mid-2025, when U.S. ethylene prices rose sharply amid scheduled refinery maintenance and strong Asian demand, creating upward pressure on extrusion-grade material costs and squeezing margins for price-sensitive converters.
Worldwide Propylene Based POE Market
Second, regional capacity dynamics are altering trade flows and competitive intensity. Significant expansion projects in China, driven by domestic producers, have brought total POE capacity to substantial scale by late 2025. Import volumes of ethylene alpha-olefin copolymers declined markedly year-on-year during the first ten months of the year as localized supply began to displace imported grades, particularly for photovoltaic encapsulant applications. This localization wave is compressing premiums for imported specialty grades and forcing global suppliers to recalibrate regional pricing, service models, and value proposition positioning.
Third, the market exhibits high concentration, with a small group of incumbent producers controlling the majority of global supply. This concentration provides scale advantages in catalyst technology, grade development, and customer qualification, but it also creates vulnerability for converters and end-users who depend on a limited supplier base for critical grades. Supply disruptions, grade transitions, or shifts in producer priority can quickly cascade into production bottlenecks or qualification delays for downstream manufacturers.
For decision-makers, these challenges translate into a clear mandate: pricing resilience, supply diversification, and grade-level differentiation are no longer optional. Businesses that treat feedstock exposure, regional capacity shifts, and supplier concentration as strategic variables, rather than operational noise, will be better positioned to protect margins and secure reliable access to performance-critical elastomer grades.
Key Demand Drivers
The 9.5 percent growth trajectory is not accidental; it is anchored in a convergence of technology, regulation, demand-side behavior, and supply chain evolution that is reinforcing POE adoption across multiple end-use sectors.
Catalyst and Polymer Architecture Innovation
POE production relies on the copolymerization of ethylene with octene or butene, typically using metallocene catalysts that deliver precise control over molecular architecture. Advances in catalyst design and process control have expanded the performance envelope of POE grades, enabling superior impact resistance, elasticity, thermal sealing behavior, and compatibility with polyethylene and polypropylene blends. These technical improvements allow formulators to replace multiple SKUs with single, multifunctional grades, simplifying compounding operations while meeting tighter performance specs for automotive components, wire and cable, and packaging.
Recent commercial milestones illustrate how innovation is translating into market share. Dow introduced bio-attributed ENGAGE REN polyolefin elastomers for flooring applications, leveraging bio-circular feedstocks such as used cooking oil and ISCC PLUS mass-balance certification. This launch signals a broader shift toward integrating sustainability attributes directly into high-performance elastomer portfolios, rather than treating environmental credentials as an afterthought. ExxonMobil’s unification of its polyolefin products under the Signature Polymers brand reinforces a service and partnership model designed to streamline customer engagement across elastomer and broader polyolefin offerings.
Regulatory and Environmental Pressures Accelerating Adoption
Tighter environmental regulations for automobiles are a powerful catalyst for POE demand. Lightweighting initiatives aimed at improving fuel efficiency, controlling emissions, and reducing fuel permeation are driving formulators toward elastomers that deliver strength and flexibility at lower part weight. POE’s ability to enhance impact performance in thermoplastic olefins and to improve processability in blends makes it a preferred modifier in automotive bumpers, interior components, and sealing systems. Concurrently, renewable energy deployment is expanding the addressable market for POE in photovoltaic encapsulant films, where clarity, durability, and long-term weatherability are critical to module lifetime and energy yield.
Demand-Side Shifts in Automotive, PV, and Industrial Applications
On the demand side, two macro trends are reshaping purchasing behavior. In automotive, the push toward electrification and stricter emissions frameworks is accelerating material substitution programs, with engineers prioritizing components that reduce mass without compromising crash performance or noise, vibration, and harshness characteristics. In parallel, the photovoltaic sector continues to scale module production globally, and encapsulant film demand is growing in lockstep with capacity additions and the transition to higher-efficiency cell architectures. Industrial and consumer applications, including wire and cable, hygiene products, and easy-peel packaging, are also benefiting from POE’s versatility in improving flexibility, sealability, and surface properties.
Supply Chain Realignment and Cost Structure Evolution
Supply chain dynamics are undergoing a structural realignment. Feedstock price volatility, refinery maintenance schedules, and regional demand imbalances are prompting producers and converters to rethink sourcing strategies. At the same time, capacity additions in key Asian markets are reducing reliance on imported grades for certain applications, while global incumbents are investing in differentiated portfolios and sustainability-certified offerings to preserve pricing power. The combined effect is a market where cost leadership alone is increasingly insufficient; competitors must pair operational efficiency with grade-level performance, sustainability credentials, and reliable regional service to win and retain share.
Competitive Landscape and Leading Strategies
The POE market is defined by a concentrated set of global producers, each pursuing distinct positioning strategies that reflect their catalyst capabilities, application focus, and regional footprint. Understanding these strategies is essential for buyers evaluating supply security and for competitors assessing where differentiation is still achievable.
Incumbent Positioning and Differentiation Levers
Dow remains the largest global producer of POE, with a comprehensive portfolio spanning ethylene-octene and ethylene-butene copolymers for automotive TPO compounds, wire and cable, packaging, and photovoltaic encapsulants. Its differentiation rests on breadth of grades, application-specific performance tuning, and a growing sustainability narrative through bio-attributed offerings. ExxonMobil Chemical leverages its Exact and Vistamaxx performance polymer families to serve impact modification, flexible packaging, and compounding applications, emphasizing product unification and customer service through its Signature Polymers brand initiative.
Mitsui Chemicals, alongside partners such as Idemitsu Kosan and Sumitomo Chemical, is consolidating polypropylene and LLDPE businesses into Prime Polymer Co., Ltd., with integration effective in 2026 and targeted synergies exceeding 8 billion yen through facility consolidation and enhanced high-performance polyolefin capabilities. This move underscores a regional strategy of scale and integration to strengthen competitiveness in high-value polyolefin segments. LG Chem differentiates with LUCENE POE, produced using proprietary metallocene catalysts to deliver impact resistance, elasticity, low thermal sealing, and applications in automotive sound insulation and shock-absorbing parts. SABIC, through its joint venture structure, supplies Fortify POE grades focused on impact modification, processability, and durability for automotive and packaging uses.
Borealis, LyondellBasell, Braskem, Arkema, Sumitomo Chemical, Chevron Phillips, and INEOS each occupy specialized niches. Borealis emphasizes Queo POE for wire and cable, solar, and automotive sealing applications, with a focus on compounding performance. LyondellBasell tailors grades for automotive and packaging impact and flexibility enhancement. Braskem highlights sustainable and bio-based POE solutions. Arkema, Sumitomo Chemical, Chevron Phillips, and INEOS round out the field with specialty material support, high-quality elastomer R&D, and industrial compounding grades. Collectively, these players illustrate a market where differentiation increasingly hinges on application engineering, sustainability certification, and regional service reliability rather than commodity pricing alone.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive landscape is evolving along three axes. First, consolidation is accelerating in regions where scale and feedstock integration can unlock cost and capability advantages, as evidenced by the Mitsui-Idemitsu-Sumitomo integration effort and similar facility rationalization discussions across the industry. Second, fragmentation persists at the grade and application level, where specialty formulations for photovoltaic encapsulants, automotive lightweighting, and medical or industrial uses require dedicated development and qualification pathways. Third, new entrants and capacity expansions in Asia are reshaping regional supply-demand balances, intensifying competition for import-substituted grades while creating opportunities for global suppliers that can offer differentiated performance or sustainability attributes not easily replicated at scale.
PW Consulting Chemical & Energy Research Center
For buyers, the implication is clear: supplier selection should weigh not only price and availability, but also grade-level technical support, qualification risk, sustainability certification, and regional service density. For producers, the path to durable share gains lies in pairing scale with application-specific innovation and credible sustainability claims that resonate with regulated end markets.
Future Outlook and Strategic Opportunities
Looking ahead to the 2026–2032 window, three trends are likely to define the POE market and create actionable opportunities for well-positioned stakeholders.
First, sustainability-integrated POE will move from niche to mainstream in selected applications. Bio-attributed and mass-balance-certified grades are already entering commercial portfolios, and as automotive emissions rules tighten and consumer goods brands pursue circular material goals, demand for verified sustainable elastomers is expected to rise. The opportunity lies in securing qualified sustainable grades early, building traceability and certification capabilities, and aligning product development with downstream brand and regulatory requirements. The risk is that certification complexity and feedstock availability could constrain supply or create premium volatility if not managed proactively.
Polyolefin Elastomers (POE) Market
Second, regional capacity localization will continue to compress import dependence in key markets, particularly for photovoltaic encapsulant grades and certain automotive and packaging applications. This trend creates both threat and opportunity. Converters and end-users can benefit from shorter supply chains and reduced import exposure, but global suppliers must adapt by offering grades or services that are not easily duplicated locally, such as advanced impact modification, high-clarity encapsulant formulations, or tightly controlled compounding performance. The uncertainty lies in the pace and scale of localization, which could accelerate further if trade dynamics or feedstock advantages shift.
Third, feedstock cost volatility will remain a central margin driver, with ethylene and propylene pricing sensitive to crude trends, refinery maintenance, and regional demand swings. Businesses that build hedging strategies, flexible sourcing frameworks, and grade-level cost transparency will be better equipped to navigate price spikes and protect competitiveness. The upside opportunity is for producers and converters that can pass through value-based differentiation—performance, sustainability, or service—rather than competing solely on commodity price.
These trends converge on a central theme: the POE market is transitioning from a volume-driven expansion to a value-driven competition where differentiation, resilience, and sustainability determine long-term winners. Companies that anticipate grade-level demand shifts, invest in qualification-ready sustainable portfolios, and design sourcing strategies around regional capacity dynamics will capture disproportionate value as the market matures.
Actionable Recommendations for Decision-Makers
For manufacturers and compounders, the priority is to reduce qualification risk while expanding grade flexibility. Map critical POE grades to application requirements, secure secondary sources for high-impact or encapsulant-critical grades, and align product development with sustainability-certified options where end-market regulations or customer pledges demand verified attributes. Build technical service partnerships that can accelerate grade transitions and troubleshooting, especially as regional capacity shifts alter availability patterns.
For investors, focus on value-chain positions that benefit from differentiation rather than pure volume. Favor producers and converters with strong application engineering, catalyst or grade-level IP, credible sustainability certification, and regional service density. Monitor consolidation moves and capacity additions that could reshape regional pricing power, and assess exposure to feedstock volatility relative to pricing flexibility and value-based differentiation.
For procurement and supply chain leaders, treat POE sourcing as a strategic function rather than a transactional purchase. Diversify by grade and region, quantify feedstock exposure in cost models, and embed sustainability and certification requirements into supplier selection criteria. Align inventory and qualification plans with expected localization trends to balance cost efficiency against supply resilience.
Detailed segment-level data, regional capacity trajectories, and customized sourcing and investment recommendations are available in the full PW Consulting research report on the PolyOlefin Elastomer market.
For detailed analysis of this topic, please visit the official page: PolyOlefin Elastomer (POE) Synthetic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
p.p'-Dibromobiphenyl Market Outlook: Why 4.12% CAGR Masks SKU-Level Value Shifts Through 2032
By pmarketresearch, 2026-09-18
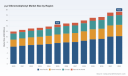
Strategic Trends and Commercial Opportunities in the p.p'-Dibromobiphenyl Market
Market Overview and Core Challenges
The p.p'-Dibromobiphenyl market has demonstrated steady, incremental growth over the past half-decade, transitioning from a niche specialty chemical segment to a recognized component in advanced materials supply chains. Valued at approximately USD 11.95 million in 2020, the overall market expanded to an estimated USD 14.5 million in 2025, reflecting a compound annual growth rate of roughly 4.12% projected through 2032. This trajectory underscores a maturing but still evolving ecosystem where demand is increasingly tied to high-performance electronic materials and specialty polymer applications. The market structure remains moderately concentrated, with the top three players accounting for approximately 64% of total revenue and the top five representing over 81%. Such concentration suggests established relationships between key manufacturers and end-users, yet also leaves room for agile entrants and regional specialists to capture value through differentiation in purity, logistics, or service integration.
Despite the positive growth trajectory, the segment faces several structural challenges that are reshaping how participants navigate pricing, compliance, and capacity allocation. First, raw material volatility has become a persistent pressure point. Bromine pricing has experienced sharp fluctuations in recent months, with Chinese supply experiencing a notable 46% surge between mid-2025 and early 2026, while Northeast Asian and European markets have seen more moderate but still upward movements. These swings cascade into synthesis costs, affecting margin resilience for producers who lack hedging strategies or diversified sourcing arrangements. Second, regulatory scrutiny around polybrominated biphenyl compounds continues to tighten across major jurisdictions. Substances falling within this chemical family are subject to monitoring frameworks that emphasize environmental persistence and aquatic toxicity, prompting stricter documentation requirements, supply chain transparency, and end-of-life considerations for downstream users. While p.p'-Dibromobiphenyl itself is not broadly restricted, its regulatory adjacency introduces compliance overhead and can influence procurement preferences toward fully traceable, audited supply lines. Third, the market is experiencing a divergence in purity expectations across application tiers. Certain end-use segments prioritize cost-efficient intermediate grades, while advanced electronic and pharmaceutical-adjacent applications demand consistent high-purity specifications with rigorous batch-to-batch validation. Balancing these competing requirements without compromising operational efficiency or qualification timelines remains a central challenge for producers and buyers alike.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Advancements
Progress in electronic materials and specialty polymers continues to anchor demand for brominated biphenyl derivatives. The compound serves as a building block in the synthesis of organic semiconductors and small-molecule materials, where precise substitution patterns and controlled purity levels directly influence device performance. Concurrently, liquid crystal polymer formulations increasingly rely on specialized intermediates to achieve targeted thermal stability, mechanical strength, and processing characteristics. These applications reward suppliers that can provide consistent specifications, robust technical data packages, and responsive support during product qualification cycles. The trend is not merely about volume; it is about reliability and technical compatibility. Manufacturers able to standardize production protocols, reduce impurity profiles, and streamline documentation are gaining an edge in applications where development timelines are compressed and failure costs are high.
Worldwide Bromobenzene Market
Regulatory and Compliance Evolution
The regulatory landscape is reinforcing a preference for transparent, documented supply chains. Monitoring frameworks for brominated compounds place additional emphasis on environmental fate, aquatic toxicity, and responsible handling across the value chain. In practice, this translates into more rigorous batch testing, clearer safety data alignment, and enhanced traceability from feedstock to finished intermediate. Companies that proactively align with these expectations are better positioned to serve multinational end-users who must satisfy internal audit requirements and downstream compliance obligations. The regulatory environment also encourages regional diversification of supply, as procurement teams seek to reduce exposure to concentrations that could be disrupted by policy shifts or inspection regimes. Over time, compliance capability is becoming a competitive differentiator rather than a baseline cost of doing business.
Demand-Side Shifts in Electronics and Specialty Chemicals
Demand patterns are being shaped by the expansion of high-value applications that require controlled molecular architectures. Organic light-emitting diode material intermediates represent one of the larger demand pools, driven by continued development in display technologies and related optoelectronic components. At the same time, liquid crystal polymer uses are supported by sectors that value dimensional stability, chemical resistance, and performance under demanding operating conditions. Beyond these core uses, laboratory and analytical applications sustain a steady baseline of demand, particularly among organizations that require certified reference materials or high-purity samples for method development and quality assurance. Across these segments, buyers are increasingly balancing cost considerations against the need for consistency, lead-time reliability, and technical support. This shift favors suppliers that can present clear value propositions beyond unit price alone, including packaging flexibility, inventory availability in key regions, and documented purity verification.
Supply Chain and Cost Structure Dynamics
Cost structures are being influenced by feedstock dynamics and regional capacity configurations. Bromine pricing has been notably volatile, with significant increases observed in China and upward pressure recorded across Northeast Asia and Europe. These movements affect not only direct input costs but also the economics of transportation, warehousing, and inventory planning for intermediaries and end-users. At the same time, the broader biphenyl feedstock environment remains sensitive to benzene-related volatility, adding another layer of uncertainty to upstream economics. In response, many participants are reevaluating sourcing strategies, exploring longer-term supply agreements, and considering regional production footprints that reduce exposure to single-market shocks. Capacity expansion in certain locales has also introduced a more tiered supply environment, where scale players compete on volume and cost while specialty suppliers compete on purity, certification, and application-focused service. This bifurcation is gradually redefining negotiation dynamics and encouraging more segmented procurement strategies.
Competitive Landscape and Leading Strategies
The competitive field blends established specialty chemical suppliers with regional manufacturers that have expanded their footprint through targeted product positioning. Tokyo Chemical Industry Co., Ltd. (TCI) exemplifies a reagent-focused model, offering p.p'-Dibromobiphenyl as a building block for organic semiconductors and small-molecule materials, with packaging options tailored to laboratory and pilot-scale needs and inventory positioned in Japanese warehouses. This orientation emphasizes availability, specification clarity, and support for research and early-stage development workflows. On the pharmaceutical-adjacent side, Simson Pharma Limited and Pharmaffiliates approach the material as a reference standard and analytical/reuse-grade intermediate, aligning their offerings with documentation rigor and traceability that appeal to regulated environments. Deep Pharm Chem further reinforces this angle through certified quality systems and assay specifications suited to analytical applications. In the manufacturing segment, several China-based producers, including Alfa Chem, Zhejiang Free Trade Zone Violet Trade Co., Ltd., Nantong Reform Petro-Chemical Co., Ltd., Henan Violet Technology Co., Ltd., Mascot Chem, and Ruifu Chem, demonstrate a spectrum of capabilities ranging from cost-efficient bulk supply to higher-purity pharmaceutical-grade output. Ruifu Chem’s export-oriented presence across multiple regions highlights how certain suppliers leverage scale and logistics to serve diverse downstream markets, while others differentiate through purity tiers and melting-point specifications that cater to particular application tolerances.
Leading players are pursuing differentiation along three primary axes: purity and specification control, application-specific packaging and service, and geographic availability. Suppliers that can demonstrate tight control over assay, impurity profiles, and batch consistency are gaining preference in segments where downstream processing is sensitive to variability. Packaging flexibility, from small-scale trial quantities to multi-ton batches, allows manufacturers to serve both early-stage qualification and larger production campaigns without forcing customers into suboptimal inventory commitments. Geographic positioning also matters; having stock or production capacity near key demand centers reduces lead times and improves responsiveness during qualification windows or supply disruptions. These strategic choices are especially relevant given the market’s moderate concentration, where incumbents hold meaningful share but do not fully lock out competitors that offer compelling technical or commercial combinations.
4,4-Biphenol Market
The landscape is evolving through a blend of consolidation pressure and niche expansion. On one hand, larger entities benefit from established supplier qualifications, broader distribution networks, and the ability to absorb raw material fluctuations more effectively. On the other hand, regional manufacturers and specialized suppliers continue to enter or expand by focusing on purity grades, certification depth, or application-aligned technical support. New entrants that can deliver consistent quality, transparent documentation, and reliable logistics are finding pathways into procurement considerations, particularly where incumbent supply is constrained or where end-users seek to diversify risk. The result is a market that is neither fully commoditized nor tightly controlled, but rather segmented by value drivers that reward capabilities beyond simple volume pricing.
Forecasting the Next Three to Five Years
Several interconnected trends are likely to shape the market through the end of the decade. First, purity segmentation will become more pronounced as downstream applications continue to differentiate. Higher-purity offerings will remain critical for electronic materials and regulated environments, while intermediate grades will continue to serve cost-sensitive polymer and specialty synthesis uses. Suppliers that can efficiently manage multiple purity tiers within streamlined operations will be better positioned to capture demand across segments without diluting margin quality. Second, supply chain resilience will move from a procurement preference to a strategic requirement. Given the observed volatility in bromine pricing and the sensitivity of feedstock economics, buyers and producers alike will increasingly favor arrangements that reduce exposure to abrupt cost shocks and regional disruptions. This may include longer-term agreements, diversified sourcing, inventory buffering in strategic locations, and closer collaboration between suppliers and end-users on demand forecasting. Third, regulatory and documentation expectations will continue to intensify, reinforcing the value of traceability, certified quality systems, and clear safety and handling information. Companies that treat compliance as part of their value proposition, rather than a back-office function, will find it easier to qualify in multinational supply chains and to maintain preferred-supplier status over time.
These trends create clear commercial opportunities for participants willing to invest in differentiation and operational discipline. Producers that align capacity with application-specific purity needs, strengthen documentation, and secure reliable feedstock access can command more stable negotiations and improve customer retention. For buyers, the opportunity lies in building multi-source strategies that balance cost, quality, and continuity, while avoiding overreliance on a single region or supplier tier. At the same time, uncertainty persists. Raw material pricing could continue to fluctuate, regulatory definitions and monitoring expectations may evolve, and demand from electronic materials applications remains linked to broader technology adoption cycles. Navigating these variables will require continuous monitoring of pricing signals, feedstock conditions, and policy developments, as well as the flexibility to adjust sourcing and production strategies as the landscape changes.
Actionable Recommendations for Decision-Makers
For manufacturers, the priority is to align product portfolios with the purity and documentation expectations of the most value-intensive applications while maintaining efficient pathways for intermediate-grade demand. Investing in batch consistency, certification readiness, and technical support capabilities can improve positioning with end-users who prioritize reliability in qualification and scale-up. Exploring feedstock hedging or diversified sourcing arrangements may also help cushion the impact of bromine price volatility and improve margin predictability.
PW Consulting Chemical & Energy Research Center
For investors, the market’s moderate concentration and segmentation by purity, application, and geography suggest selective opportunities rather than broad-based exposure. Due diligence should focus on suppliers with demonstrated quality systems, credible export capabilities, and supply chain practices that reduce regulatory and operational risk. Tracking feedstock economics and regional pricing trends will be essential for assessing cost resilience and long-term competitiveness.
For procurement teams, a balanced sourcing strategy that combines primary suppliers with qualified alternates can mitigate disruption risk while preserving cost discipline. Prioritizing partners that offer transparent documentation, consistent specifications, and flexible packaging can shorten qualification cycles and improve supply continuity. As regulatory expectations and raw material dynamics continue to evolve, maintaining access to current market intelligence will be valuable for timing contracts, evaluating regional sourcing options, and anticipating shifts in supplier capability.
For organizations seeking a more granular view of regional demand patterns, purity-grade economics, application-level volume trajectories, and competitive positioning, a comprehensive market study can provide the detailed segmentation and scenario context needed for planning. Deeper data on pricing structures, capacity developments, and compliance-related purchasing behavior can support more precise sourcing decisions, investment prioritization, and product strategy refinement.
For detailed analysis of this topic, please visit the official page: p.p'-Dibromobiphenyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Modified Phenolic Resins Market: Why Asia Pacific’s 5.29% CAGR Drives Strategic Shifts
By pmarketresearch, 2026-09-18
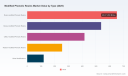
Navigating the Modified Phenolic Resins Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The modified phenolic resins market has demonstrated steady expansion over the past five years, evolving from a mature specialty chemical segment into a strategically important enabler for higher-performance industrial applications. Total market revenue reached approximately $1,980.5 million in 2025, reflecting a compound annual growth rate of 5.29 percent across the forecast horizon extending through 2032. This trajectory signals more than incremental volume growth; it indicates a structural shift toward formulations that balance thermal resistance, adhesion strength, and environmental compliance across multiple downstream sectors. The expansion is particularly visible in application categories such as printing inks, coatings and varnishes, adhesives and sealants, friction materials, and foundry and abrasives, where end-users increasingly demand tailored resin architectures rather than commodity-grade alternatives.
Despite this positive momentum, the market is navigating several structural pressures that will define competitive positioning in the coming years. First, formulation complexity is rising as performance specifications tighten across automotive, electronics, and construction sectors. Traditional novolac and resol systems are being pushed to their limits in terms of curing speed, moisture resistance, and volatile organic compound management, forcing manufacturers to invest in modification chemistries that add technical and operational overhead. Second, feedstock volatility remains a persistent margin pressure point. Phenol pricing dynamics are closely tied to benzene and propylene fundamentals, and while recent price movements have provided temporary relief, regional cost disparities and logistics constraints continue to influence production economics. Third, regulatory and customer-driven sustainability mandates are reshaping procurement criteria. Lower formaldehyde emissions, biomass-derived inputs, and measurable carbon footprint reductions are transitioning from optional differentiators to baseline expectations in many end markets.
Together, these pressures create a clear inflection point: companies that treat modification as a cost center will face margin compression and customer attrition, while those that embed formulation agility, feedstock flexibility, and sustainability credentials into their operating models can capture premium positioning. The market is no longer rewarding scale alone; it is rewarding the ability to deliver modified systems that solve specific performance and compliance problems without disrupting downstream processing conditions.
Key Drivers of Market Evolution
Technical Innovation and Formulation Breakthroughs
Innovation in modification chemistry is one of the most meaningful value-creation levers in this market. Rather than relying on standard phenolic backbones, leading developers are integrating rosin, epoxy, cashew nut shell liquid, rubber-based modifiers, and lignin-derived inputs to tune rheology, heat resistance, and curing behavior. These modifications are not incremental tweaks; they enable resins to perform in environments where conventional systems struggle, such as high-temperature friction applications, moisture-exposed coatings, and bonding interfaces that require low emission profiles. The commercialization of lignin-modified resol-type resins illustrates how biomass substitution can reduce fossil resource dependence while maintaining structural integrity. When a lignin-modified formulation achieves a lower carbon footprint and meets recognized industrial standards for plywood and laminated wood products, it demonstrates that sustainability and performance can be aligned rather than traded off.
PW Consulting Chemical & Energy Research Center
Policy, Regulation, and Compliance Pressure
Regulatory environments and customer sustainability programs are accelerating adoption of modified resins that address emission limits and material sourcing expectations. Formaldehyde management remains a central focus across construction, wood products, and consumer-facing applications, while broader decarbonization goals are influencing procurement decisions in automotive and industrial supply chains. Compliance is increasingly viewed as a design parameter rather than a post-production checkpoint. Manufacturers that proactively develop low-emission and biomass-integrated formulations gain a smoother path through certification requirements and a stronger narrative for downstream customers facing their own reporting obligations. This dynamic is particularly impactful in regions where construction and wood composite standards are tightening, as modified resins that satisfy those specifications can secure longer-term qualification status and reduce the risk of formulation swaps.
Rosin Modified Phenolic Resin Market
Demand-Side Shifts in End-Use Sectors
Demand behavior is changing as end-users look for resins that do more than bind or coat. Printing ink formulators seek modifiers that improve gloss, adhesion, and drying consistency on diverse substrates. Coatings and varnishes customers require enhanced weatherability and chemical resistance without sacrificing application properties. Adhesive and sealant producers need systems that cure predictably across varying humidity and temperature conditions while maintaining bond strength. Meanwhile, friction material and foundry applications continue to demand heat stability, wear resistance, and reliable performance under mechanical stress. This multifaceted demand profile pushes suppliers to offer more granular product portfolios and to engage earlier in customer development cycles. The practical implication is that revenue growth is increasingly tied to solution-level engagement, not just volume sales of standard grades.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by feedstock behavior, regional production economics, and the operational footprint required for modified formulations. Phenol pricing has shown downward movement through 2025, and near-term outlooks suggest a range that remains sensitive to benzene supply, demand recovery in downstream derivatives, and regional differentials. At the same time, Northeast Asia and other key production zones exhibit their own cost baselines, meaning that competitiveness is partly determined by location, logistics, and feedstock access. For modified resins specifically, the cost equation also includes additional processing steps, quality control for consistency, and the ability to handle solvent-based, water-based, or solid-form outputs without sacrificing throughput. Companies that can manage these layers efficiently gain room to invest in higher-margin custom grades while maintaining competitive base pricing.
Competitive Landscape and Leading Strategies
The competitive environment in modified phenolic resins is characterized by a mix of global specialists, regional manufacturers, and custom toll producers, with a meaningful portion of market value concentrated among a relatively small group of established players. This concentration reflects the importance of formulation expertise, application testing, consistent quality, and long qualification cycles in end markets such as electronics, automotive, abrasives, and wood composites. At the same time, the landscape is not static; differentiation is becoming more pronounced as companies pursue distinct strategic positions.
Several themes define how leading companies are positioning themselves. One is biomass and sustainability integration. Companies that have introduced lignin-modified or other biomass-linked phenolic systems are signaling a shift from incremental improvement to feedstock-level differentiation. This strategy is especially relevant where customers need measurable carbon footprint reductions and certification support, because it combines technical performance with a credible sustainability story. Another theme is application specialization. Manufacturers with deep roots in friction materials, abrasives, refractory products, insulation, and industrial bonding are expanding their modified portfolios to serve those sectors with tailored resol and novolac options. This approach reduces exposure to commoditization and builds stickier relationships with customers that rely on specific processing characteristics. A third theme is format and service flexibility. Offering pastilles, powders, flakes, lumps, solvent-based, and water-based forms allows suppliers to match downstream handling requirements and reduce conversion friction for buyers. Custom toll manufacturing and certified quality systems further strengthen this value proposition by enabling smaller or more specialized buyers to access modified grades without building their own formulation infrastructure.
The market is also showing signs of both consolidation and fragmentation, depending on the segment. Larger global participants are well placed to invest in broader application portfolios and international distribution, while regional manufacturers can compete on responsiveness, local feedstock dynamics, and custom formulation services. New or expanding entrants often find opportunity in niche modifications, contract production, or region-specific compliance needs rather than attempting to compete directly on scale. Overall, the trajectory favors companies that combine technical credibility with commercial flexibility. Price competition remains present, but the more decisive battles are being fought over qualification speed, consistency, emission performance, and the ability to co-develop modified systems that fit specific end-use conditions.
Forward-Looking Trends for the Next Three to Five Years
One of the clearest near-term trends is the continued integration of sustainable feedstocks and lower-emission formulations into mainstream product lines. Modified phenolic resins that incorporate biomass-derived inputs or deliver measurable carbon footprint reductions are likely to move from specialty offerings toward broader commercial adoption, especially in wood composites, coatings, and industrial adhesives where sustainability credentials influence procurement decisions. The commercial opportunity here lies in pairing formulation performance with certification support and transparent lifecycle messaging, enabling suppliers to command preference in qualified supply chains.
A second trend is the growing importance of application-specific customization over standardized volume supply. As end-use requirements become more varied, buyers will increasingly seek resin systems optimized for curing behavior, emission limits, substrate compatibility, and processing conditions. This creates opportunities for manufacturers that can shorten development cycles, provide robust technical support, and maintain consistent quality across smaller batch sizes or custom formats. Companies that build modular modification platforms will be better positioned to scale these solutions without sacrificing margin.
A third trend involves feedstock cost and regional supply dynamics remaining a strategic variable rather than a background condition. Even with recent price moderation, phenol-related economics will continue to influence margin structures and sourcing decisions. Businesses that diversify input strategies, optimize regional production footprints, and maintain flexibility across solvent-based and water-based systems will be better equipped to manage cost fluctuations while preserving performance standards. The primary risk is that feedstock volatility, regulatory changes, or formulation compliance failures could disrupt pricing stability and qualification timelines, particularly for newer biomass-integrated products that still require broad market acceptance.
Strategic Actions for Decision Makers
For resin manufacturers and formulators, the priority is to treat modification capability as a core commercial asset. Building a broader library of proven modified grades, strengthening application testing, and offering format flexibility can improve qualification success and protect margins. Investing in low-emission and biomass-linked options should be paired with credible certification and customer-facing documentation so that sustainability claims translate into procurement advantage rather than remaining symbolic.
For investors and corporate development teams, the most compelling opportunities lie in capabilities that combine formulation expertise with application proximity. Assets that enable custom toll production, regional compliance support, or rapid co-development with end-users are likely to hold strategic value as buyers seek more tailored solutions. Due diligence should focus on technical depth, consistency records, feedstock flexibility, and the ability to scale modified systems without eroding quality or cost discipline.
For procurement and sourcing leaders, the practical move is to qualify modified suppliers earlier and evaluate them on more than unit price. Consistency, emission performance, processing compatibility, and sustainability documentation increasingly affect total cost and operational risk. Developing a shortlist of partners with demonstrated modification breadth and reliable technical support can reduce reformulation churn and improve supply resilience across printing inks, coatings, adhesives, friction materials, and foundry applications. Given the pace of change in feedstock economics, regulatory expectations, and formulation options, timely access to detailed market segmentation and company-level intelligence can sharpen these decisions and reduce uncertainty in planning cycles.
Phenolic Resins Market
For detailed analysis of this topic, please visit the official page: Modified Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Circuit Breakers for New Energy Power Generation: The 8.25% CAGR Redefining Market Dynamics
By pmarketresearch, 2026-09-18
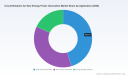
Circuit Breakers for New Energy Power Generation: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for circuit breakers dedicated to new energy power generation has entered a period of accelerated, structurally driven expansion. Valued at approximately $2.05 billion in 2020, the market crossed the $3.1 billion threshold by 2025, reflecting a compound annual growth rate of 8.25 percent through 2032. By the end of the forecast horizon, total market revenue is projected to surpass $5.4 billion. This trajectory is not merely a reflection of broader renewable capacity additions; it signals a fundamental shift in how electrical protection systems are specified, engineered, and integrated into modern power generation architectures.
Despite the robust expansion, the sector faces several structural inflection points that will dictate competitive outcomes over the next half-decade. First, the transition toward inverter-based and DC-coupled generation assets is outpacing legacy protection paradigms. Traditional alternating-current circuit breaker frameworks, while mature, are increasingly mismatched with the fault behavior, response timing, and interconnection requirements of solar arrays, wind farms, and battery energy storage systems. Engineers and project developers must navigate a fragmented standards landscape while balancing reliability, switching speed, and system efficiency.
Second, material cost volatility has introduced sustained pressure on manufacturing margins and pricing predictability. The surge in industrial metal benchmarks during early 2026, including sharp year-over-year increases in copper, aluminum, and steel mill products, directly translates into higher input costs for wiring, contact assemblies, and structural housings. Suppliers that lack agile procurement frameworks or pricing pass-through mechanisms are facing compressed profitability, particularly in mid-voltage segment where competition remains intense.
Third, regulatory recalibration in key demand regions is reshaping project economics and procurement timelines. In the United States, recent legislative adjustments have altered the incentive architecture for solar and wind deployments, tightening placed-in-service requirements and expanding foreign entity restrictions. These changes do not eliminate demand, but they compress development windows, shift procurement toward compliant supply chains, and elevate the importance of equipment that can accelerate interconnection approvals and reduce commissioning risk.
Key Drivers Shaping Market Dynamics
Technological Innovation and Protection Architecture Evolution
The most consequential force reshaping the market is the rapid evolution of protection technologies tailored to new energy topologies. Manufacturers are moving beyond incremental improvements in interrupting capacity and are rearchitecting breakers for hybrid AC/DC environments, high-frequency inverter interfaces, and modular storage configurations. Vacuum-based solutions continue to dominate where high reliability and minimal maintenance are priorities, while air-blast and specialized contact designs are being optimized for higher current ratings and faster arc extinguishment in wind and utility-scale solar applications.
PW Consulting Chemical & Energy Research Center
A notable shift is the accelerated development of DC-rated and hybrid-switching solutions. Collaborative engineering efforts between major equipment suppliers are producing specification frameworks for multi-terminal high-voltage direct current systems, directly enabling large-scale renewable integration and offshore wind aggregation. These initiatives are not isolated R&D exercises; they are translating into commercially viable product roadmaps that address the unique fault currents and commutation challenges inherent to DC-coupled generation and storage assets.
Policy, Regulation, and Grid Modernization Mandates
Regulatory frameworks and grid code requirements are acting as powerful demand amplifiers, particularly where transmission constraints and interconnection backlogs are pressing policymakers to streamline approvals. Regions that have tied renewable portfolio standards or clean energy targets to grid readiness are seeing heightened specification requirements for protection equipment that can satisfy both utility compliance and fast-response operational profiles.
At the same time, environmental and emission-related expectations are influencing technology selection. The broader industry movement toward reducing reliance on high-global-warming-potential gases has spurred the commercial introduction of SF6-free breaker families and alternative insulating media. Utilities and developers increasingly factor sustainability credentials into procurement decisions, especially for public-sector tenders and projects with corporate offtake commitments that require alignment with decarbonization goals.
DC Circuit Breaker Market
Demand-Side Shifts and Application Diversification
On the demand side, the convergence of generation and storage is altering specification patterns. Solar installations continue to drive substantial volume, but wind power and energy storage systems are expanding the addressable base for specialized protection components. Storage deployments, in particular, introduce bidirectional power flow, rapid cycling, and hybrid AC/DC interfaces that require breakers capable of handling diverse operational modes without compromising safety or service life.
Corporate procurement behavior is also evolving. Developers and independent power producers are prioritizing equipment that reduces integration complexity, supports remote monitoring, and minimizes field commissioning time. This has elevated the value of digitally enabled interfaces and modular designs that can be scaled across project portfolios, from distributed solar to utility-scale hybrid plants.
Supply Chain Reconfiguration and Cost Structure Pressures
Supply chain dynamics remain a critical driver of both risk and opportunity. The recent spike in base metal prices has rippled through component manufacturing, affecting everything from conductive elements to mechanical assemblies. Suppliers that operate with vertically integrated production, long-term raw material contracts, or diversified sourcing networks are better positioned to stabilize output costs. Conversely, reliance on spot-market procurement is exposing manufacturers to margin erosion and delivery uncertainty.
Simultaneously, geopolitical and compliance considerations are reshaping sourcing strategies for North American and European projects. Equipment that aligns with localization expectations, transparent supply chain documentation, and evolving foreign entity restrictions is gaining preference in tenders where project financing and permitting depend on demonstrable compliance. This dynamic is encouraging both incumbent suppliers and regional manufacturers to reinforce domestic or nearshore production capabilities.
Worldwide Classified Circuit Breaker Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderately concentrated field of global incumbents, specialized regional players, and emerging niche suppliers. The top three competitors collectively account for slightly more than one-third of market revenue, while the top five approach just above half, leaving substantial room for differentiated positioning and regional share gains. This structure favors players that can combine scale, technical specialization, and responsive localization rather than those competing solely on price.
Strategic Positioning and Differentiation Levers
Leading participants are pursuing distinct differentiation pathways. Global manufacturers with broad switchgear portfolios are emphasizing high-current ratings, generator-protection specialization, and end-to-end integration for renewable and gas-based generation assets. Recent product launches targeting next-generation wind turbines and refurbished power plants illustrate a strategy centered on expanding the operational envelope of breaker families, enabling them to serve both new capacity and modernization programs.
A second group is concentrating on sustainability-driven innovation and grid-modernization alignment. Suppliers offering SF6-free interrupting technologies, digitalized medium-voltage switchgear, and IoT-enabled protection devices are positioning their products as enablers of lower-emission operations and predictive maintenance workflows. These offerings resonate with utilities and developers seeking to meet environmental targets while improving asset visibility across distributed portfolios.
A third cohort, often originating in Asia, is focusing on application-specific DC protection, solar PV interfaces, and battery energy storage compatibility. These companies have built credibility around specialized photovoltaic DC switchgear and storage-oriented protection components, frequently competing on application fit, cost efficiency, and rapid adaptation to regional project requirements. Their growth reflects the broader shift toward distributed and hybrid installations where tailored protection solutions can command premium positioning.
Market Evolution: Consolidation, Specialization, and New Entrants
The landscape is evolving along two parallel tracks. Large incumbents are deepening their capabilities through collaboration and targeted product expansion, pairing AC protection expertise with DC switching development to address transmission-scale renewable integration. These partnerships are accelerating specification maturity for multi-terminal systems and creating cross-licensing opportunities that broaden technology access without requiring every player to build every capability internally.
At the same time, market fragmentation persists at the application and regional levels. New and expanding entrants are carving out positions in solar DC protection, storage switchgear, and medium-voltage solutions for renewable facilities. This specialization creates a dynamic environment where incumbents must defend broad-platform advantages while remaining responsive to niche demands that can rapidly scale into significant volume pools. The net effect is a market in which success depends on balancing portfolio breadth with deep application engineering, localized supply resilience, and the ability to align product roadmaps with evolving grid codes and procurement criteria.
Future Outlook for 2027 to 2032
Over the next three to five years, the market is likely to be shaped by three interlocking trends. First, DC and hybrid protection architectures will move from emerging to mainstream in a growing share of solar-plus-storage and offshore wind projects. As inverter-based resources and storage systems become more tightly integrated, demand for breakers designed for bidirectional flow, fast fault response, and DC commutation will expand beyond specialized deployments into broader project specifications. Commercial opportunities will accrue to suppliers that can offer tested, code-aligned DC solutions with clear interoperability pathways and field-service support.
Second, sustainability requirements and digital integration will increasingly function as procurement gatekeepers rather than optional enhancements. SF6-free product lines, lower-emission manufacturing practices, and connected protection devices capable of remote diagnostics will become standard expectations in utility tenders and corporate-backed developments. This creates opportunities for suppliers to bundle hardware with service-oriented value propositions, including monitoring platforms, predictive maintenance tools, and lifecycle support contracts that improve total-cost-of-ownership outcomes.
Third, regional supply realignment will continue as project developers navigate incentive uncertainty, interconnection delays, and compliance requirements. Markets with strong renewable deployment pipelines but challenged transmission timelines will favor equipment that accelerates commissioning, reduces interconnection risk, and aligns with localization expectations. Suppliers that can demonstrate reliable delivery, documentation transparency, and adaptability to shifting regulatory parameters will be better positioned to capture share, particularly where project economics are sensitive to schedule compression.
The principal uncertainties tempering this outlook include ongoing raw material price swings, the pace at which DC protection standards mature across jurisdictions, and the potential for incentive recalibration to alter project pipelines in key regions. These variables do not negate long-term growth, but they reward flexibility. Companies that can adjust product mix, secure resilient input channels, and align engineering roadmaps with evolving grid and regulatory conditions will be best equipped to convert market expansion into durable commercial gains.
Strategic Implications for Decision Makers
For manufacturers, the priority is to align product roadmaps with the convergence of DC integration, sustainability expectations, and digital service demands. Developing modular, application-specific protection platforms and pairing them with monitoring or maintenance capabilities can differentiate offerings in a market where hardware specifications are increasingly table stakes. Equally important is securing supply chain resilience through diversified sourcing, long-term material contracts, or localized production to mitigate input-cost volatility.
For investors, the opportunity lies in identifying companies with clear technological adjacencies, particularly those bridging AC protection expertise with DC switching development or those expanding into storage and hybrid plant interfaces. Suppliers with strong application engineering, credible sustainability roadmaps, and the ability to serve both utility-scale and distributed segments offer broader exposure to the structural growth trajectory. Attention to regional compliance readiness and supply chain transparency will be critical when evaluating near-term scalability.
For procurement teams and project developers, equipment selection should extend beyond interrupting ratings and price. Evaluating compatibility with DC-coupled architectures, SF6-free options, digital integration capabilities, and supplier localization profiles can reduce interconnection risk, accelerate commissioning, and support long-term sustainability commitments. In an environment where project timelines and regulatory parameters are shifting, partnering with suppliers that offer specification flexibility and reliable delivery can materially improve project outcomes.
Detailed segmentation data, regional volume breakdowns, company-level positioning maps, and scenario-based forecasts are available in the full research report for teams that require granular inputs for portfolio planning, investment evaluation, or procurement strategy.
For detailed analysis of this topic, please visit the official page: Circuit Breakers for New Energy Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Recycled Containerboard Market: Why a 4.69% CAGR to $202B Redefines Packaging
By pmarketresearch, 2026-09-18
Recycled Containerboard Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
The recycled containerboard market has transitioned from a cyclical commodity segment into a structurally expanding supply chain component that mediates between waste recovery and industrial packaging demand. The industry has demonstrated steady growth across the historical period from 2020 to 2025, with the market value reaching 146.5 billion USD in the base year of 2025. Forward projections indicate sustained momentum, with the market expected to expand to approximately 153.96 billion USD in 2026 and continue climbing through the forecast horizon to 2032, when it is anticipated to approach 201.88 billion USD. This trajectory reflects a compound annual growth rate of 4.69 percent over the forecast period. The expansion is not merely a function of volume; it represents a reconfiguration of how packaging value chains source, grade, and deploy recovered fiber in response to regulatory pressure, buyer specifications, and cost dynamics.
Despite this constructive backdrop, the market sits at a series of inflection points that will separate resilient operators from those caught flat-footed. Three challenges merit immediate attention. First, the cost structure of recovered fiber is becoming increasingly volatile and regionally segmented. While long-term demand for recycled grades remains robust, pricing for old corrugated container material has exhibited sharp directional swings, with early 2026 showing modest rebounds after late-2025 softness. These fluctuations are not random; they reflect tightening collection economics, sorting capacity constraints, and shifting trade flows that complicate input planning for mills relying on diversified waste streams.
Second, the regulatory environment is accelerating but uneven. Extended producer responsibility frameworks for packaging and paper products have moved from legislative drafts to operational reality in multiple jurisdictions, reshaping who bears end-of-life costs and how recycled content is incentivized. In some markets, requirements for post-consumer recycled content are climbing toward thresholds that materially alter formulation strategies, procurement planning, and compliance verification. Operators must now reconcile sustainability mandates with the technical reality that recycled fiber performance varies by source, contamination levels, and processing configuration.
Third, the underlying production environment is tightening even as demand grows. Containerboard output in key regions has shown contraction while operating rates have remained elevated, signaling that capacity additions are not keeping pace with structural demand shifts and that existing assets are running close to their practical limits. This combination of high utilization and modest output changes implies limited slack in the system, which amplifies the impact of feedstock disruptions, maintenance cycles, and grade transitions. For decision-makers, the implication is clear: recycled containerboard is no longer a passive input category but a strategically managed one, where access to quality fiber, consistent specifications, and regulatory alignment directly influence commercial positioning.
Key Demand Drivers
Technical Innovation and Fiber Performance Gains
The most consequential driver reshaping the recycled containerboard market is the convergence of fiber performance engineering and application-specific grading. Recycled containerboard was historically treated as a functional commodity where strength and consistency were acceptable but not differentiated. That paradigm is eroding. Producers are increasingly designing recycled linerboard and medium grades with targeted strength profiles, surface characteristics, and runnability attributes that meet demanding downstream requirements, particularly in e-commerce, food and beverage, and consumer goods packaging. The shift is visible in the introduction of high-performance lightweight grades, low-basis-weight options, and engineered testliner and fluting specifications that preserve protective functionality while reducing material mass.
These innovations matter because they change the value equation for buyers. A lighter yet structurally reliable recycled grade can lower total packaging cost, improve pallet efficiency, and align with brand sustainability narratives without sacrificing performance. For manufacturers, the ability to offer reproducible, application-tuned recycled grades creates a clearer differentiation path in a market that has long competed on price alone. The trend is reinforced by equipment and process upgrades that improve deinking, cleaning, and fiber selection, enabling higher brightness, better surface finish, and more consistent printing quality where required. In practice, this means recycled containerboard is increasingly participating in applications that previously leaned toward virgin fiber or blended solutions, expanding the addressable market beyond traditional bulk packaging.
Regulatory and Extended Producer Responsibility Dynamics
Policy and regulatory pressure is functioning as both a constraint and a catalyst. Extended producer responsibility laws for packaging and paper products are being implemented or proposed across multiple regions, requiring producers and brand owners to account for end-of-life management costs and, in many cases, to incorporate specified levels of recycled content. Where post-consumer recycled content thresholds are rising, the commercial logic shifts toward securing reliable streams of recovered fiber and building compliance documentation into procurement contracts. This is not a marginal adjustment; it restructures how packaging decisions are made, how sourcing is validated, and how sustainability claims are substantiated.
At the same time, regulatory momentum is not uniform. Some jurisdictions are setting explicit recycled content expectations for paper and paper packaging, while others are focusing on collection, sorting, and producer-funded recovery systems. The practical result is a patchwork environment in which strategic players must map regulatory exposure by market, anticipate compliance timelines, and prepare for higher scrutiny of recycled content claims. For mills and converters, this creates both a competitive moat and a risk: firms that can demonstrate traceable, certified recycled content and consistent grade performance will be better positioned to serve brand owners navigating EPR obligations, whereas operators dependent on less transparent fiber sourcing may face growing friction in premium segments.
Demand-Side Shifts in E-commerce, Retail, and Brand Packaging
Demand-side behavior is changing the shape of containerboard consumption. E-commerce and retail continue to drive sustained packaging intensity, but the nature of that demand is evolving. Shipment protection requirements, damage reduction targets, and brand-facing presentation considerations are pushing buyers toward grades that balance strength, printability, and surface quality. At the same time, consumer-facing brands are under increasing pressure to make packaging decisions that are defensible on sustainability, which elevates the importance of verified recycled content and lifecycle considerations. The result is a more discerning buyer base that evaluates recycled containerboard not simply by cost per ton, but by total application performance and compliance alignment.
This shift has commercial consequences. Purchasers are more willing to lock in dedicated recycled grade supply when specifications are stable and performance is demonstrable. They are also more sensitive to variability in fiber quality and more interested in collaborative development of grades that fit specific box designs, load conditions, and printing needs. For producers, this means that the opportunity is not only in volume but in specification loyalty: customers who depend on a particular recycled linerboard or medium grade for a recurring application are less likely to treat the purchase as a spot transaction. The market is therefore moving toward stronger co-development relationships, longer planning horizons, and tighter integration between fiber availability, grade design, and end-use requirements.
Waste Paper Recycling Market
Supply Chain and Cost Structure Realignment
Cost and supply chain dynamics are reshaping where value is captured and where margin pressure accumulates. Recovered fiber pricing, contamination management, and collection logistics are becoming more important determinants of competitiveness than in prior cycles. In early 2026, indicators suggested renewed movement in recovered fiber pricing after a period of downward pressure, reflecting localized supply tightening and renewed demand balance. This kind of volatility underscores the importance of sourcing diversification, regional fiber strategy, and inventory planning. Mills and converters that rely on narrow feedstock bases or single-channel collection systems are more exposed to price shocks and grade interruptions, while those with multi-source procurement and strong sorting partnerships can moderate input risk.
The cost structure is also being influenced by capacity utilization and asset configuration. With operating rates remaining high in key regions while output adjusted modestly, the system shows limited buffering capacity. That has two implications. First, it raises the strategic premium attached to reliable production continuity and grade consistency, particularly for customers operating lean logistics models. Second, it highlights the importance of modernization investments that improve yield, reduce reject rates, and enable smoother grade transitions. In this environment, supply chain resilience is not merely an operations concern; it is a commercial differentiator. Buyers increasingly favor suppliers that can demonstrate control over fiber availability, contamination handling, and output predictability, especially when those capabilities reduce downstream disruption.
Competitive Landscape and Leading Strategies
The competitive field in recycled containerboard is defined less by sheer scale than by differentiated positioning around fiber quality, grade specialization, and regional execution. Several large and mid-tier manufacturers are actively shaping the market through distinct strategic postures. International Paper, for example, is building a high-performance recycled liner and fluting portfolio, including lightweight grades designed for corrugated packaging, supported by mill assets in Europe and North Africa. Its emphasis on reproducible performance and lightweight engineering aligns with the broader market shift toward optimized strength-to-weight outcomes. ND Paper is pursuing a complementary angle by concentrating on strength consistency, print quality, and repeatability for demanding applications, positioning recycled containerboard as a technically credible option where specification precision matters.
European and North American players are also distinguishing themselves through clear sustainability and fiber narratives. Stora Enso has emphasized testliner produced from fully recycled fibers, targeting e-commerce, industrial, and consumer goods applications with an emphasis on strength, flatness, and low weights. Cascades has focused on a broad range of recycled linerboard weights and performance categories, including white chlorine-free and extra high-performance grades, reinforcing its position as a sustainable alternative to virgin fiber where surface quality and environmental profile both matter. DS Smith has carved out a niche around high-brightness, smooth, printing-quality recycled white liner grades suitable for food, beverage, agricultural, and fast-moving consumer goods packaging, reflecting the demand for recycled board that can satisfy both protective and presentation requirements.
Regional leaders are using technical and operational specificity to strengthen their positions. Kruger Inc. has long been associated with 100 percent recycled containerboard production in North America and has expanded its portfolio to include extra high-performance linerboard, white top grades, and specialty products such as tube stock and colored board. Pratt Industries operates as a large-scale privately held producer of fully recycled containerboard with multiple mills and a closed-loop model that converts recovered paper into packaging, an approach that directly addresses fiber availability, process control, and customer integration. New Indy Containerboard combines recycled fiber with virgin grades in a high-quality brown paper portfolio, offering flexibility in formulation that can be valuable for applications requiring specific performance or cost trade-offs. Mondi has reinforced its recycled containerboard capabilities through new wide paper machine capacity for testliner and fluting from recovered fiber, expanding its ability to serve quality-sensitive segments with scalable production.
Recent developments illustrate how this landscape is evolving. A major producer brought a new recycled containerboard paper machine online in Italy with substantial annual capacity for testliner and fluting from recovered fiber, signaling a clear commitment to expanding recycled grade output in response to demand and regulatory tailwinds. At the same time, another leading manufacturer invested in capacity and quality control improvements for uncoated recycled boxboard, emphasizing surface finish and printing performance. These moves are not isolated; they reflect a broader pattern in which recycled containerboard capacity and grade engineering are being upgraded to meet higher specification thresholds and more demanding buyer expectations.
The market structure is therefore moving along two tracks simultaneously. Consolidation and scale advantages remain relevant, particularly where fiber procurement, logistics, and multi-mill networks create cost and supply chain leverage. At the same time, differentiation is intensifying through grade specialization, performance reliability, and sustainability credentials. New entrants and expanding incumbents are most likely to succeed where they can combine reliable recovered fiber access with demonstrable product consistency and compliance-ready documentation. In contrast, undifferentiated commodity positioning is increasingly vulnerable to price competition and specification shifts. The strategic implication is that competitive advantage in recycled containerboard is being rebuilt around technical credibility, sourcing resilience, and the ability to align product attributes with application needs rather than around price leadership alone.
Outlook for the Next Three to Five Years
Looking ahead, three trends are likely to define the recycled containerboard market through the late 2020s and into the early 2030s. The first is the continued migration of recycled containerboard into higher-value applications. As lightweighting, strength consistency, and surface quality improve, recycled grades will capture a larger share of e-commerce, food and beverage, and consumer goods packaging where buyers are balancing protection, presentation, and sustainability. This shift expands the commercial opportunity beyond bulk carton and industrial use and creates more attractive margin potential for producers that can deliver application-specific performance with verifiable recycled content.
The second trend is the deepening influence of regulation on sourcing and product design. As extended producer responsibility frameworks and recycled content expectations take hold in more jurisdictions, procurement will increasingly favor suppliers that can provide traceable fiber streams, documented recycled content, and stable specification performance. This will likely accelerate investment in quality control, sorting partnerships, and compliance-oriented product lines. It will also heighten the importance of regional strategy, since regulatory requirements and fiber availability will vary significantly by market. Companies that treat compliance as a structural design constraint rather than a reporting exercise will be better positioned to secure long-term customer relationships.
The third trend is the growing premium attached to supply resilience and operational reliability. With utilization rates high and input volatility present, customers will value partners that can reduce disruption risk, maintain grade consistency, and respond quickly to specification changes. This favors operators with diversified fiber sourcing, strong mill performance, and flexible production configurations. At the same time, the environment carries risk. Feedstock availability can tighten unexpectedly, regulatory timelines can shift, and demand patterns can be altered by broader economic conditions or changes in trade flows. There is also the risk that recycled content requirements and performance standards could outpace some producers’ ability to deliver consistent quality at scale, creating separation between capable and lagging operators. The overarching opportunity is to treat recycled containerboard as a strategic materials category in which fiber access, grade engineering, and compliance alignment are jointly managed rather than as a generic input market.
Recommendations for Decision-Makers
For manufacturers, the priority is to align product strategy with the direction of buyer demand and regulatory pressure. That means investing in grade differentiation that delivers measurable performance in target applications, improving consistency and surface quality where printability and presentation matter, and building fiber sourcing resilience through diversified procurement and stronger sorting relationships. Capacity and process decisions should be evaluated not only on throughput but on the ability to run stable, specification-compliant recycled grades that customers can rely on in recurring applications.
Recovered Carbon Black Rcb Market
For investors, the focus should be on distinguishing operators with genuine competitive moats from those exposed to commodity volatility and input disruption. The most durable opportunities are likely to be found in companies with reliable recovered fiber access, credible quality control, application-oriented product portfolios, and the ability to meet rising recycled content expectations. Capex plans, regional fiber strategy, and compliance readiness should be assessed as indicators of future positioning rather than as isolated operational items.
PW Consulting Chemical & Energy Research Center
For procurement and purchasing teams, the practical move is to shift from transactional buying toward specification-based sourcing with clear performance and compliance criteria. Where possible, establish longer planning horizons with suppliers that can demonstrate consistent recycled content, reproducible grade attributes, and reliable delivery. In a market where utilization is high and input dynamics can shift quickly, supply predictability and quality assurance are increasingly valuable. For organizations seeking a more detailed view of regional segmentation, grade-level dynamics, and scenario-based implications across the forecast period, the full market intelligence report provides the deeper segmentation data and customized analysis needed to translate these trends into concrete commercial decisions.
For detailed analysis of this topic, please visit the official page: Recycled Containerboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
OLED Vapor Deposition Materials: Why 17.02% CAGR and Asia’s Dominance Redefine This Market
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the OLED Vapor Deposition Materials Market
Market Overview and Structural Shifts
The global market for OLED vapor deposition materials has entered a phase of accelerated expansion, driven by the widespread adoption of organic light-emitting diode technology across consumer electronics and automotive sectors. Industry data indicates that the market generated approximately 2.17 billion USD in 2025, reflecting a compound annual growth rate of 17.02 percent over the historical period from 2020 to 2025. Projections suggest continued momentum, with the market expected to reach 2.58 billion USD in 2026 and expand further to 6.51 billion USD by 2032. This trajectory underscores the critical role that high-purity evaporation materials play in enabling advanced display architectures, particularly as manufacturers transition from solution processing to vacuum-based thermal evaporation for improved efficiency, longevity, and pixel density.
Several structural challenges are shaping the competitive landscape. First, the energy intensity of vacuum deposition processes remains a significant operational burden. Manufacturing facilities relying on traditional thermal evaporation require substantial power consumption, which amplifies production costs and contributes to the overall carbon footprint of display fabrication. As environmental scrutiny intensifies and energy prices fluctuate, producers must balance performance optimization with sustainability mandates. Second, raw material supply chains face increasing pressure. The demand for electronic-grade precursors and specialized intermediates has grown alongside panel production capacity, particularly in large-format manufacturing hubs. Volatility in the availability and pricing of key chemical inputs introduces margin uncertainty for material suppliers and downstream display makers alike. Third, the market exhibits a high degree of concentration among established players, with the top three firms controlling a substantial share of revenue. While this concentration signals technical maturity and strong intellectual property positions, it also raises questions about supply resilience and the pace of innovation entry from emerging suppliers seeking to scale capabilities in specific material segments.
Demand-Side Evolution and Application Diversification
Consumer behavior and enterprise purchasing patterns are reshaping the demand profile for vapor deposition materials. Smartphones continue to represent a core application segment, but growth dynamics are shifting as device manufacturers pursue higher resolution, improved color accuracy, and thinner form factors. The transition toward premium display specifications increases the consumption of specialized emissive and transport layer materials per unit, amplifying the value contribution of high-performance evaporation compounds. At the same time, new application categories are gaining traction. OLED televisions, information technology displays, and automotive interfaces are expanding the addressable market beyond mobile devices, creating additional volume demand for functional layers optimized for large-area and high-reliability deposition conditions.
Wearable devices and emerging form factors further diversify the demand base. As manufacturers integrate OLED panels into smartwatches, augmented reality optics, and foldable or rollable devices, material requirements become more stringent regarding uniformity, thermal stability, and compatibility with complex stack architectures. This diversification does not merely add volume; it alters the product mix, favoring suppliers that can offer differentiated material solutions tailored to specific deposition environments and performance targets. The broadening application landscape also encourages panel makers to diversify their supplier bases, reducing dependency on single-source materials and creating openings for qualified alternatives that can meet stringent quality and yield standards.
Regional Dynamics and Geographic Concentration
The Asia Pacific region accounts for the majority of market revenue, reflecting the concentration of panel manufacturing capacity, consumer electronics production, and associated material supply chains in the region. North America and Europe represent smaller but strategically significant shares, driven by advanced display development, equipment integration, and specific high-value material applications. The rest of the world contributes a modest portion of overall revenue, though localized fabrication initiatives and supply chain diversification efforts could gradually alter this distribution over the forecast period.
Geographic concentration carries both advantages and risks. Centralized manufacturing ecosystems enable close collaboration between equipment providers, material suppliers, and panel fabricators, accelerating process optimization and reducing time-to-market for new technologies. However, heavy reliance on a limited set of regions can expose the industry to logistical disruptions, regulatory changes, and geopolitical shifts. As a result, stakeholders are increasingly evaluating supply chain resilience, considering alternative sourcing pathways, and monitoring the emergence of regionally integrated material production capabilities that could support broader geographic diversification without sacrificing process compatibility or material performance.
Key Drivers Propelling Market Expansion
Technological Innovation and Material Performance Advances
Continuous improvements in material chemistry and deposition engineering remain the primary catalysts for market growth. Phosphorescent OLED emitter materials have demonstrated superior efficiency and lifespan characteristics, particularly when optimized for vacuum thermal evaporation processes. Advances in host materials, charge transport layers, and hole injection compounds contribute to higher luminous efficiency, lower driving voltage, and improved device reliability. These performance gains are critical as display manufacturers push toward higher resolutions and more demanding operating conditions. The ability to achieve consistent film uniformity, precise layer thickness control, and stable charge balance across large substrates directly influences yield and final product quality, making material performance a decisive competitive factor.
Recent equipment and process innovations reinforce the material-driven growth narrative. Applied Materials introduced a MAX OLED solution featuring an advanced angle-controlled evaporator and a novel material deposition method designed to improve pixel brightness, resolution, energy efficiency, and lifespan during vapor deposition. Such developments illustrate how equipment and material capabilities are co-evolving, with process improvements unlocking new value from existing material formulations and encouraging further refinement of evaporation-compatible compounds.
Sustainability Pressures and Regulatory Dynamics
Environmental and regulatory considerations are increasingly influencing material development and procurement strategies. Vacuum deposition processes are energy-intensive, and the associated carbon footprint of production has attracted attention from regulators, corporate sustainability teams, and end customers. In response, the industry is exploring pathways to reduce energy consumption, improve material utilization, and incorporate recycled or eco-friendly alternatives where feasible. Samsung SDI's sustainability reporting highlights efforts to develop recyclable and environmentally conscious OLED materials, reflecting a broader industry trend toward aligning performance goals with responsible sourcing and end-of-life considerations.
Regulatory uncertainty also affects raw material management. Global environmental regulations and supply stability concerns are prompting manufacturers to evaluate the lifecycle implications of precursor selection, solvent use, and material disposal. These pressures do not merely constrain operations; they create incentives for innovation in material design, process efficiency, and waste reduction. Suppliers that can offer materials compatible with lower-energy deposition parameters or that demonstrate reduced environmental impact may secure preferential positioning in procurement evaluations, particularly among panel makers with public sustainability commitments.
Supply Chain Restructuring and Regional Supplier Evolution
The material supply base is undergoing gradual restructuring as regional capabilities mature and new entrants seek to capture share in high-growth segments. In China, OLED evaporation material suppliers are expanding their market presence, with industry reports indicating that one company is projected to enter the global top ten in 2025. This shift reflects investments in material synthesis, purification, and process compatibility that enable domestic and regional panel makers to access qualified alternatives to long-established international suppliers. The trend contributes to a more multipolar supply landscape, particularly for intermediates and functional layer materials where localized production can reduce logistics costs, shorten lead times, and provide greater continuity in periods of global market volatility.
At the same time, raw material consumption patterns are intensifying. Electronic-grade silane, for example, sees annual consumption exceeding 500 metric tons per new Gen 8.6 or Gen 10.5 AMOLED fab in China, underscoring the scale of precursor demand as manufacturing capacity expands. Such volume requirements highlight the importance of stable upstream supply, purification consistency, and cost management. Suppliers that can guarantee purity, batch-to-batch reproducibility, and reliable delivery volumes will be better positioned to support large-scale fabrication without exposing panel makers to quality drift or production interruptions.
Demand-Side Behavior and Portfolio Diversification
Demand is being shaped not only by volume growth but also by the pursuit of differentiated display experiences. Consumers and enterprise buyers increasingly expect higher contrast, wider color gamuts, and adaptive display characteristics across devices ranging from flagship smartphones to in-vehicle infotainment systems. These expectations translate into more complex stack designs and greater reliance on specialized vapor deposition materials that can deliver consistent performance under varied operating conditions. As a result, panel manufacturers are incentivized to adopt materials that support multi-functionality, such as improved charge balance, enhanced thermal stability, and compatibility with fine-pitch patterning.
The diversification of application portfolios also affects procurement behavior. When display usage spans mobile, television, IT, automotive, and wearable segments, material suppliers must respond with product lines that address distinct performance and scalability requirements. This dynamic encourages closer collaboration between material developers and panel makers, as joint optimization of deposition parameters and material properties becomes essential to achieving target yield, efficiency, and durability. Suppliers capable of supporting multiple application domains while maintaining consistent quality standards gain strategic relevance in an environment where flexibility and reliability are equally valued.
Polarizer for OLED Market
Competitive Landscape and Strategic Positioning
Leading Players and Differentiated Capabilities
Universal Display Corporation occupies a prominent position as a leading provider of phosphorescent OLED emitter materials and technologies optimized for vacuum thermal evaporation processes. Its emphasis on high-efficiency emitter chemistry and process-compatible materials supports applications where luminous efficiency and device lifetime are paramount. The company's continued investment in deposition alternatives, including the relocation of research and development for Universal Vapor Jet Printing technology to a subsidiary in Singapore, signals a strategic interest in high-deposition-rate dry printing methods that could complement or extend traditional vacuum evaporation capabilities. Such moves underscore a broader ambition to shape next-generation deposition workflows while strengthening regional operational flexibility.
Merck KGaA supplies host materials, emitters, and transport layer materials specifically formulated for vacuum vapor deposition in OLED stack architectures. Its broad material portfolio and established formulation expertise enable support across multiple device architectures and performance targets. LG Chem produces OLED stack materials including hole and electron transport layers and emitters tailored for vapor deposition manufacturing of AMOLED panels, contributing to a vertically integrated value chain that aligns material development with panel-level requirements. Samsung SDI develops emitting layer materials and functional layers for vacuum deposition, reinforcing its role as a key material supplier within a broader display ecosystem.
In Japan, Idemitsu Kosan stands out as a major supplier of blue emitters, host materials, and charge transport materials designed for thermal vacuum vapor deposition, addressing a particularly demanding color and stability segment. Sumitomo Chemical offers small-molecule materials for vapor-deposition type OLEDs with additional focus on related functional layers, while Hodogaya Chemical provides specialized OLED intermediates and materials compatible with vacuum processes. JNC Corporation manufactures functional materials and intermediates for OLED vapor deposition applications, and Tokuyama Corporation produces high-purity materials and precursors used in OLED vapor deposition layers. Together, these Japanese firms contribute deep chemical synthesis expertise and a strong emphasis on purity and consistency, which are critical for fine-pitch and high-efficiency deposition environments.
In the United States, Materion Corporation supplies evaporation materials and high-purity compounds for thin-film vapor deposition in OLED production, supporting the broader equipment and materials ecosystem with specialized precursor and compound offerings. In China, a growing set of producers—including Jilin OLED Material Tech, Changchun Hyperions Technology, and Shaanxi Lighte Optoelectronics Material—manufacture OLED evaporation materials and intermediates for vapor deposition applications. These regional suppliers are expanding their capabilities in response to domestic panel demand and the broader push toward supply chain localization, creating additional options for buyers seeking qualified alternatives and reinforcing the trend toward a more geographically diversified material base.
Strategic Themes Across the Competitive Field
Several strategic themes emerge across the competitive landscape. First, technical differentiation remains central. Companies that advance emitter efficiency, host material stability, and transport layer performance for vacuum evaporation gain leverage in high-value applications where device performance directly influences product positioning. Second, process compatibility is increasingly important. Materials must integrate smoothly with existing deposition equipment and emerging process variations, including angle-controlled evaporation and high-throughput dry printing methods. Suppliers that collaborate closely with equipment vendors and panel makers to optimize deposition parameters can achieve faster qualification cycles and stronger customer relationships.
Third, supply resilience and purity assurance are becoming strategic differentiators. As fabrication scales and material specifications tighten, the ability to deliver consistent purity, reproducible batches, and reliable volumes reduces risk for downstream manufacturers. Fourth, sustainability alignment is moving from a compliance concern to a competitive consideration. Materials and processes that support lower energy intensity, improved utilization, and responsible sourcing may influence procurement decisions among organizations with explicit environmental targets.
Market Evolution and Emerging Dynamics
The competitive field is evolving through a combination of concentration, niche differentiation, and gradual entry by regional suppliers. High concentration among top players reflects strong intellectual property positions and mature material portfolios, but it also creates incentives for new entrants to compete in specific segments such as blue emitters, intermediates, or region-specific supply solutions. Over time, this can lead to a more layered market structure in which established firms continue to lead in high-performance categories while regional and specialized suppliers expand in adjacent material classes.
Integration and collaboration are likely to increase as panel makers, equipment providers, and material suppliers seek to co-optimize deposition workflows and reduce qualification risk. At the same time, the push toward dry printing alternatives and improved deposition efficiency may reshape material requirements over the medium term, encouraging suppliers to adapt formulations and processes to maintain relevance across evolving manufacturing paradigms. The overall trajectory points toward a market that remains performance-driven but is increasingly sensitive to supply continuity, geographic diversification, and sustainability considerations.
PW Consulting Chemical & Energy Research Center
Forward-Looking Trends and Commercial Implications
Trend 1: Co-Optimization of Materials and Deposition Equipment
The convergence of material chemistry and deposition engineering is expected to intensify over the next three to five years. Equipment innovations such as advanced angle-controlled evaporation and novel deposition methods are designed to enhance pixel brightness, resolution, energy efficiency, and lifespan. For material suppliers, this implies a growing need to tailor formulations that perform optimally under these refined process conditions. Commercial opportunities will accrue to firms that can demonstrate compatibility, support pilot-scale qualification, and provide data that links material attributes to equipment-level outcomes. Panel makers and equipment vendors, in turn, benefit from shorter development cycles and higher yield stability when materials and tools are optimized together.
Trend 2: Expansion of Regional Supply Bases and Supplier Diversification
Regional suppliers are gaining share, particularly in markets with expanding fabrication capacity and localized procurement preferences. As one Chinese evaporation material supplier is projected to join the global top ten in 2025, the competitive map is becoming more multipolar. This trend offers buyers greater sourcing flexibility and may improve supply continuity, but it also requires rigorous qualification and quality assurance practices. For material producers, regional expansion can reduce logistics burdens and align product offerings with local fab requirements, creating opportunities for differentiated service models, technical support, and customized material grades that match regional process configurations.
Trend 3: Sustainability-Linked Material and Process Innovation
Environmental and supply stability pressures are unlikely to abate. Energy-intensive deposition processes, raw material constraints, and rising sustainability expectations will continue to shape material development priorities. Over the forecast horizon, expect greater attention to material utilization efficiency, lower-energy deposition compatibility, recycled or eco-friendly material pathways, and supply chain transparency. These developments can translate into commercial advantages for suppliers positioned to offer performance without compromising environmental or sourcing goals. At the same time, uncertainty remains regarding the pace of regulatory evolution, the cost implications of sustainable alternatives, and the willingness of buyers to absorb premium pricing for greener material solutions. Strategic planning should account for both the upside of differentiation and the risk of shifting standards.
Strategic Considerations for Decision Makers
For Display Manufacturers and Panel Fabricators
Prioritize material qualification programs that emphasize process compatibility, batch consistency, and performance under target deposition conditions. As equipment and material innovations converge, early collaboration with suppliers and equipment partners can reduce qualification risk and accelerate adoption of higher-efficiency deposition methods. Evaluate supplier diversification strategies to balance performance, resilience, and regional sourcing needs, particularly where large-scale capacity expansion increases raw material consumption and supply continuity requirements.
For Investors and Strategic Planners
Focus on capabilities that link material performance to evolving deposition workflows and application diversification. Companies with strong emitter chemistry, transport layer expertise, and adaptive process compatibility are well positioned as panel makers pursue higher resolution, improved efficiency, and broader application portfolios. Monitor the pace of regional supplier maturation and the emergence of qualified alternatives, as shifts in the top-tier ranking may influence supply dynamics and margin structures. Consider sustainability-linked innovation as a potential differentiator, while remaining attentive to cost, scale, and regulatory uncertainty.
Organic Photovoltaics (OPV) Market
For Procurement and Supply Chain Leaders
Strengthen qualification frameworks that capture purity, reproducibility, delivery reliability, and environmental attributes in a unified evaluation. As raw material demand grows with fab expansion, secure long-term supply arrangements where feasible and maintain visibility into upstream precursor availability, particularly for high-volume inputs such as electronic-grade silane. Where sustainability commitments are material to corporate strategy, incorporate eco-friendly and recycled material options into sourcing reviews without sacrificing performance or yield.
Market evolution in OLED vapor deposition materials will be shaped by the interplay of technical performance, equipment co-optimization, regional supply expansion, and sustainability pressures. Decision makers who align procurement, investment, and development strategies with these forces will be better prepared to capture value as the market moves toward higher efficiency, broader application coverage, and more diversified sourcing. For a detailed view of segmentation data, regional revenue splits, competitive benchmarking, and scenario-based forecasts, the full PW Consulting report provides the granular intelligence needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: OLED Vapor Deposition Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com