

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
FAI Market: Why 28.42% CAGR and Perovskite Solar Cells Redefine Growth

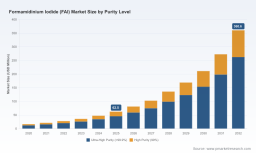
Strategic Horizons: Decoding the Formamidinium Iodide (FAI) Market Dynamics and Opportunities
Market Overview: A Sector in Rapid Transition
The Formamidinium Iodide (FAI) market has evolved from a niche material supply chain into a critical enabler of next-generation opto-electronic and photovoltaic technologies. Over the historical review period, the sector demonstrated consistent expansion, reflecting the accelerating adoption of perovskite-based architectures across energy and electronics applications. Current market valuation stands at a significant milestone, with trajectory models projecting sustained growth through the end of the forecast horizon. The compounding annual growth rate underscores a structural shift rather than a cyclical upturn, driven by the material's unique position as a high-performance precursor for formamidinium lead iodide perovskites.
PW Consulting Chemical & Energy Research Center
From an industry standpoint, this expansion is not uniform. Demand is concentrated among segments requiring stringent material specifications, particularly ultra-high purity grades that meet the exacting tolerances of advanced device fabrication. The market's value distribution reflects a clear hierarchy where premium-grade materials command disproportionate share, signaling that performance differentiation and reliability are becoming primary commercial differentiators. This concentration also indicates that early movers who established production capabilities for specialized grades have secured defensible positions, while late entrants face higher barriers to achieving comparable quality benchmarks.
Despite the favorable trajectory, the sector faces structural headwinds that will shape competitive outcomes. First, the pharmaceutical and electronic-grade classification frameworks are tightening around iodine-containing compounds, introducing compliance complexity and cost escalation that vary sharply by jurisdiction. Second, the transition from laboratory-scale synthesis to industrial-grade consistency remains a friction point; maintaining ultra-low moisture content and batch-to-batch reproducibility at scale requires capital-intensive process controls that not all manufacturers have mastered. Third, the raw material base for high-purity production carries inherent cost premiums, with advanced purification techniques adding meaningful expense layers compared to standard-grade output. These challenges are not insurmountable, but they demand strategic foresight in capacity planning, regulatory navigation, and vertical integration decisions.
Key Drivers Reshaping the FAI Landscape
Several interdependent forces are accelerating market evolution, each carrying distinct implications for production strategies, pricing dynamics, and demand forecasting.
Worldwide Rhodium(III) Iodide Market
Technological Innovation and Performance Gradients
The core technological driver lies in the material science advantages that FAI enables. When integrated into perovskite architectures, formamidinium-based compounds exhibit narrower bandgaps compared to earlier methylammonium analogs, translating into improved solar conversion efficiencies and broader spectral absorption. This performance gradient has made FAI a preferred precursor for high-efficiency photovoltaic research and commercialization pathways. Simultaneously, advances in deposition techniques and encapsulation strategies are reducing historical degradation concerns, expanding the viable application envelope. Manufacturers are responding by refining synthesis protocols that minimize impurity profiles and moisture ingress, recognizing that even trace deviations can compromise device longevity and performance consistency.
Regulatory and Classification Dynamics
Regulatory frameworks are reshaping supply chain economics in measurable ways. Several jurisdictions have introduced stricter oversight of iodine-containing compounds, with certain precursor classifications triggering additional handling, documentation, and compliance requirements. These measures add meaningful expense layers to production in affected regions, influencing where capacity is sited and how materials are routed to end users. Companies that proactively align manufacturing processes with evolving classification standards, invest in transparent supply chain traceability, and maintain robust regulatory affairs capabilities are better positioned to absorb compliance costs without sacrificing competitive pricing. Conversely, operators treating regulatory adaptation as reactive face margin compression and potential supply disruptions.
Demand-Side Shifts and Application Diversification
Demand patterns are broadening beyond early research channels into pilot production and early commercial deployments. The perovskite solar cell segment remains the dominant consumption driver, reflecting sustained investment in tandem cell architectures and efficiency roadmaps that target commercial viability milestones. Alongside this, perovskite light-emitting diodes and photodetector applications are cultivating additional demand nodes, though at smaller absolute scales. End users are increasingly prioritizing material consistency, technical documentation, and supply reliability over pure price competition, recognizing that material variability can cascade into yield losses and performance inconsistencies at integrated manufacturing levels.
Cost Structure Evolution and Supply Chain Adjustments
The cost architecture of FAI production is undergoing recalibration. Achieving ultra-high purity grades demands specialized techniques that elevate manufacturing expenses relative to standard grades, creating a clear value gradient that informed buyers are willing to pay for. At the same time, supply chain participants are exploring vertical integration, localized sourcing of iodine derivatives, and process intensification to mitigate cost volatility. The interplay between raw material availability, purification complexity, and scale economies is producing a bifurcated market where premium-grade producers capture stronger margins, while standard-grade segments face intensifying price competition. Strategic capacity allocation, therefore, hinges on aligning production grades with target customer segments and securing reliable input streams that can sustain quality at volume.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive field spans a diverse set of players, from specialized material manufacturers focusing exclusively on perovskite precursors to broader chemical and electronics suppliers offering FAI as part of wider product portfolios. This diversity shapes how competition unfolds and where strategic advantages crystallize.
Leading manufacturers have carved distinct positioning strategies. Specialized producers emphasize ultra-high purity thresholds, extremely low moisture content, and in-house production capabilities that allow them to control quality from synthesis through packaging. These operators often market directly to research institutions and early-stage device manufacturers, building reputation through consistent material performance and technical support. Their differentiation rests on reproducibility, documentation rigor, and the ability to supply quantities ranging from grams for R&D to kilogram-scale batches for pilot lines.
Dye Sensitized Solar Cell Market
Larger or multinational suppliers leverage complementary strengths. Some bring established distribution networks, flexible packaging options spanning bench-scale to industrial volumes, and the capacity to support customers across development stages. Others integrate FAI into broader portfolios of electronic and photovoltaic precursors, offering procurement convenience and cross-material sourcing advantages. These players benefit from brand recognition, logistical infrastructure, and the ability to bundle materials for complex device fabrication workflows. Their competitive edge often lies in service breadth, global reach, and the perceptions of reliability that come with established institutional presence.
Regional manufacturers, particularly in China and across Asia Pacific, contribute significant volume and are increasingly investing in purification technologies and quality certifications. Their participation has expanded accessible supply and introduced competitive pressure on pricing, especially in standard and high-purity tiers. This dynamic encourages broader industry maturation, but it also raises the importance of verification, certification, and technical specification alignment for end users seeking consistent performance.
Market structure is evolving along several axes. Consolidation pressures are emerging as larger entities seek to secure reliable precursor supply chains and as specialized producers explore partnerships or acquisitions to scale capacity and broaden technical capabilities. At the same time, fragmentation persists at the research-grade level, where numerous suppliers serve niche demand with varying specification sets. New entrants are assessing opportunities where existing supply falls short of ultra-high purity, moisture control, or regulatory compliance expectations. The net effect is a market that rewards clarity of positioning: operators that define their grade focus, customer segment, and compliance posture with precision are better equipped to sustain margins and defend against commoditization.
Future Outlook: Trends and Commercial Implications (2026-2032)
Looking ahead, three trends are likely to define the next phase of market development and shape where commercial value accrues.
Premium-grade specialization will deepen. As device architectures push efficiency and stability targets, the premium attached to ultra-high purity and ultra-low moisture specifications will intensify. Suppliers that can reliably deliver these grades at scale, backed by verifiable quality documentation and process control, will capture disproportionate demand from high-value applications. The cost premium associated with advanced purification is unlikely to erode; instead, it will become a recognized and accepted component of total device economics, reinforcing segmentation between premium and standard tiers.
Regulatory alignment will become a competitive lever. Classification and handling requirements for iodine-related compounds will continue to influence sourcing decisions. Companies that proactively integrate compliance into their operational design, maintain transparent audit trails, and offer regionally compliant supply routes will reduce friction for downstream customers. This creates an operational advantage that extends beyond cost, affecting procurement confidence, risk management, and long-term partnership stability.
Application diversification will broaden demand nodes while solar remains central. Perovskite solar cells will continue to anchor volume growth, but light-emitting diodes, photodetectors, and specialized opto-electronic uses will add incremental demand streams. This diversification does not diminish the centrality of photovoltaic demand; rather, it creates multiple growth vectors that can buffer sector volatility and open cross-selling opportunities for suppliers with broad capability sets. End users will increasingly seek partners who can support varied application requirements without compromising material consistency.
These trends carry commercial opportunities, but also uncertainties. Scale-up challenges, raw material availability, and the pace at which regulatory frameworks settle across regions will influence how quickly new capacity translates into reliable supply. Buyers should anticipate continued differentiation in specification quality and service models, while suppliers should plan for a landscape where technical performance, compliance readiness, and supply reliability matter as much as price.
Strategic Actions for Decision-Makers
For manufacturers, the priority is aligning production capacity with the grade segments that command durable demand. Investing in purification consistency, moisture control, and verifiable quality documentation will strengthen positioning in premium tiers where differentiation translates into margin resilience. At the same time, maintaining flexible packaging and scale options allows suppliers to serve both research and pilot-commercial customers without compromising quality standards.
For investors, the opportunity lies in identifying operators with clear technical differentiation, robust compliance capabilities, and credible pathways to scale. Evaluate production processes, certification status, customer concentration, and regional risk exposure rather than relying solely on top-line growth narratives. Companies that can demonstrate reproducible ultra-high purity output and navigate regulatory complexity are better positioned to capture sustained demand as the market matures.
For procurement and sourcing teams, the focus should shift from unit price toward total value, including specification reliability, documentation quality, supply continuity, and compliance alignment. Establishing clear material requirements, verifying batch consistency, and engaging suppliers with transparent quality systems will reduce downstream risk and support manufacturing yield stability. As the market expands and segmentation sharpens, sourcing strategies that prioritize performance assurance and regulatory readiness will deliver stronger long-term outcomes.
For stakeholders seeking granular segmentation data, regional supply dynamics, pricing benchmarks across purity tiers, and customized scenario analysis, the full research report provides detailed breakdowns and actionable frameworks to inform planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Formamidinium Iodide (FAI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com