

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Modified Phenolic Resins Market: Why Asia Pacific’s 5.29% CAGR Drives Strategic Shifts

Navigating the Modified Phenolic Resins Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
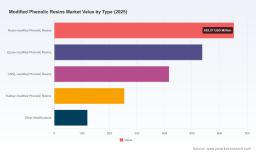
The modified phenolic resins market has demonstrated steady expansion over the past five years, evolving from a mature specialty chemical segment into a strategically important enabler for higher-performance industrial applications. Total market revenue reached approximately $1,980.5 million in 2025, reflecting a compound annual growth rate of 5.29 percent across the forecast horizon extending through 2032. This trajectory signals more than incremental volume growth; it indicates a structural shift toward formulations that balance thermal resistance, adhesion strength, and environmental compliance across multiple downstream sectors. The expansion is particularly visible in application categories such as printing inks, coatings and varnishes, adhesives and sealants, friction materials, and foundry and abrasives, where end-users increasingly demand tailored resin architectures rather than commodity-grade alternatives.
Despite this positive momentum, the market is navigating several structural pressures that will define competitive positioning in the coming years. First, formulation complexity is rising as performance specifications tighten across automotive, electronics, and construction sectors. Traditional novolac and resol systems are being pushed to their limits in terms of curing speed, moisture resistance, and volatile organic compound management, forcing manufacturers to invest in modification chemistries that add technical and operational overhead. Second, feedstock volatility remains a persistent margin pressure point. Phenol pricing dynamics are closely tied to benzene and propylene fundamentals, and while recent price movements have provided temporary relief, regional cost disparities and logistics constraints continue to influence production economics. Third, regulatory and customer-driven sustainability mandates are reshaping procurement criteria. Lower formaldehyde emissions, biomass-derived inputs, and measurable carbon footprint reductions are transitioning from optional differentiators to baseline expectations in many end markets.
Together, these pressures create a clear inflection point: companies that treat modification as a cost center will face margin compression and customer attrition, while those that embed formulation agility, feedstock flexibility, and sustainability credentials into their operating models can capture premium positioning. The market is no longer rewarding scale alone; it is rewarding the ability to deliver modified systems that solve specific performance and compliance problems without disrupting downstream processing conditions.
Key Drivers of Market Evolution
Technical Innovation and Formulation Breakthroughs
Innovation in modification chemistry is one of the most meaningful value-creation levers in this market. Rather than relying on standard phenolic backbones, leading developers are integrating rosin, epoxy, cashew nut shell liquid, rubber-based modifiers, and lignin-derived inputs to tune rheology, heat resistance, and curing behavior. These modifications are not incremental tweaks; they enable resins to perform in environments where conventional systems struggle, such as high-temperature friction applications, moisture-exposed coatings, and bonding interfaces that require low emission profiles. The commercialization of lignin-modified resol-type resins illustrates how biomass substitution can reduce fossil resource dependence while maintaining structural integrity. When a lignin-modified formulation achieves a lower carbon footprint and meets recognized industrial standards for plywood and laminated wood products, it demonstrates that sustainability and performance can be aligned rather than traded off.
PW Consulting Chemical & Energy Research Center
Policy, Regulation, and Compliance Pressure
Regulatory environments and customer sustainability programs are accelerating adoption of modified resins that address emission limits and material sourcing expectations. Formaldehyde management remains a central focus across construction, wood products, and consumer-facing applications, while broader decarbonization goals are influencing procurement decisions in automotive and industrial supply chains. Compliance is increasingly viewed as a design parameter rather than a post-production checkpoint. Manufacturers that proactively develop low-emission and biomass-integrated formulations gain a smoother path through certification requirements and a stronger narrative for downstream customers facing their own reporting obligations. This dynamic is particularly impactful in regions where construction and wood composite standards are tightening, as modified resins that satisfy those specifications can secure longer-term qualification status and reduce the risk of formulation swaps.
Rosin Modified Phenolic Resin Market
Demand-Side Shifts in End-Use Sectors
Demand behavior is changing as end-users look for resins that do more than bind or coat. Printing ink formulators seek modifiers that improve gloss, adhesion, and drying consistency on diverse substrates. Coatings and varnishes customers require enhanced weatherability and chemical resistance without sacrificing application properties. Adhesive and sealant producers need systems that cure predictably across varying humidity and temperature conditions while maintaining bond strength. Meanwhile, friction material and foundry applications continue to demand heat stability, wear resistance, and reliable performance under mechanical stress. This multifaceted demand profile pushes suppliers to offer more granular product portfolios and to engage earlier in customer development cycles. The practical implication is that revenue growth is increasingly tied to solution-level engagement, not just volume sales of standard grades.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by feedstock behavior, regional production economics, and the operational footprint required for modified formulations. Phenol pricing has shown downward movement through 2025, and near-term outlooks suggest a range that remains sensitive to benzene supply, demand recovery in downstream derivatives, and regional differentials. At the same time, Northeast Asia and other key production zones exhibit their own cost baselines, meaning that competitiveness is partly determined by location, logistics, and feedstock access. For modified resins specifically, the cost equation also includes additional processing steps, quality control for consistency, and the ability to handle solvent-based, water-based, or solid-form outputs without sacrificing throughput. Companies that can manage these layers efficiently gain room to invest in higher-margin custom grades while maintaining competitive base pricing.
Competitive Landscape and Leading Strategies
The competitive environment in modified phenolic resins is characterized by a mix of global specialists, regional manufacturers, and custom toll producers, with a meaningful portion of market value concentrated among a relatively small group of established players. This concentration reflects the importance of formulation expertise, application testing, consistent quality, and long qualification cycles in end markets such as electronics, automotive, abrasives, and wood composites. At the same time, the landscape is not static; differentiation is becoming more pronounced as companies pursue distinct strategic positions.
Several themes define how leading companies are positioning themselves. One is biomass and sustainability integration. Companies that have introduced lignin-modified or other biomass-linked phenolic systems are signaling a shift from incremental improvement to feedstock-level differentiation. This strategy is especially relevant where customers need measurable carbon footprint reductions and certification support, because it combines technical performance with a credible sustainability story. Another theme is application specialization. Manufacturers with deep roots in friction materials, abrasives, refractory products, insulation, and industrial bonding are expanding their modified portfolios to serve those sectors with tailored resol and novolac options. This approach reduces exposure to commoditization and builds stickier relationships with customers that rely on specific processing characteristics. A third theme is format and service flexibility. Offering pastilles, powders, flakes, lumps, solvent-based, and water-based forms allows suppliers to match downstream handling requirements and reduce conversion friction for buyers. Custom toll manufacturing and certified quality systems further strengthen this value proposition by enabling smaller or more specialized buyers to access modified grades without building their own formulation infrastructure.
The market is also showing signs of both consolidation and fragmentation, depending on the segment. Larger global participants are well placed to invest in broader application portfolios and international distribution, while regional manufacturers can compete on responsiveness, local feedstock dynamics, and custom formulation services. New or expanding entrants often find opportunity in niche modifications, contract production, or region-specific compliance needs rather than attempting to compete directly on scale. Overall, the trajectory favors companies that combine technical credibility with commercial flexibility. Price competition remains present, but the more decisive battles are being fought over qualification speed, consistency, emission performance, and the ability to co-develop modified systems that fit specific end-use conditions.
Forward-Looking Trends for the Next Three to Five Years
One of the clearest near-term trends is the continued integration of sustainable feedstocks and lower-emission formulations into mainstream product lines. Modified phenolic resins that incorporate biomass-derived inputs or deliver measurable carbon footprint reductions are likely to move from specialty offerings toward broader commercial adoption, especially in wood composites, coatings, and industrial adhesives where sustainability credentials influence procurement decisions. The commercial opportunity here lies in pairing formulation performance with certification support and transparent lifecycle messaging, enabling suppliers to command preference in qualified supply chains.
A second trend is the growing importance of application-specific customization over standardized volume supply. As end-use requirements become more varied, buyers will increasingly seek resin systems optimized for curing behavior, emission limits, substrate compatibility, and processing conditions. This creates opportunities for manufacturers that can shorten development cycles, provide robust technical support, and maintain consistent quality across smaller batch sizes or custom formats. Companies that build modular modification platforms will be better positioned to scale these solutions without sacrificing margin.
A third trend involves feedstock cost and regional supply dynamics remaining a strategic variable rather than a background condition. Even with recent price moderation, phenol-related economics will continue to influence margin structures and sourcing decisions. Businesses that diversify input strategies, optimize regional production footprints, and maintain flexibility across solvent-based and water-based systems will be better equipped to manage cost fluctuations while preserving performance standards. The primary risk is that feedstock volatility, regulatory changes, or formulation compliance failures could disrupt pricing stability and qualification timelines, particularly for newer biomass-integrated products that still require broad market acceptance.
Strategic Actions for Decision Makers
For resin manufacturers and formulators, the priority is to treat modification capability as a core commercial asset. Building a broader library of proven modified grades, strengthening application testing, and offering format flexibility can improve qualification success and protect margins. Investing in low-emission and biomass-linked options should be paired with credible certification and customer-facing documentation so that sustainability claims translate into procurement advantage rather than remaining symbolic.
For investors and corporate development teams, the most compelling opportunities lie in capabilities that combine formulation expertise with application proximity. Assets that enable custom toll production, regional compliance support, or rapid co-development with end-users are likely to hold strategic value as buyers seek more tailored solutions. Due diligence should focus on technical depth, consistency records, feedstock flexibility, and the ability to scale modified systems without eroding quality or cost discipline.
For procurement and sourcing leaders, the practical move is to qualify modified suppliers earlier and evaluate them on more than unit price. Consistency, emission performance, processing compatibility, and sustainability documentation increasingly affect total cost and operational risk. Developing a shortlist of partners with demonstrated modification breadth and reliable technical support can reduce reformulation churn and improve supply resilience across printing inks, coatings, adhesives, friction materials, and foundry applications. Given the pace of change in feedstock economics, regulatory expectations, and formulation options, timely access to detailed market segmentation and company-level intelligence can sharpen these decisions and reduce uncertainty in planning cycles.
Phenolic Resins Market
For detailed analysis of this topic, please visit the official page: Modified Phenolic Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com