

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Indoor Wall Decoration Paint Market: Why 5.45% CAGR Through 2032 Changes Everything

Strategic Trends and Commercial Opportunities in the Indoor Wall Decoration Paint Market
Market Landscape and Core Challenges
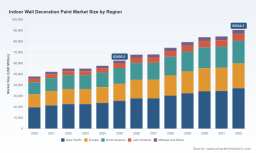
The indoor wall decoration paint market is undergoing a period of measured but consistent expansion, driven by sustained construction activity, evolving consumer expectations, and tightening environmental standards. From 2020 to 2025, the industry demonstrated resilience through cycles of economic fluctuation, with total revenue climbing steadily to surpass sixty-two billion dollars by the 2025 base year. Looking ahead, the market is projected to grow at a compound annual rate of approximately 5.45 percent through 2032, reaching an estimated valuation of over ninety billion dollars by the close of the forecast horizon. This trajectory reflects a mature yet evolving sector where growth is increasingly tied to product innovation, regulatory compliance, and regional demand shifts rather than volume expansion alone.
Several structural challenges are reshaping how manufacturers, distributors, and end-users navigate this space. First, the regulatory landscape has become increasingly complex and fragmented across major markets. New mandatory standards governing volatile organic compound limits, hazardous substance restrictions, and compulsory certification requirements are forcing manufacturers to reformulate products, adjust production processes, and invest in compliance infrastructure. While these measures align with broader sustainability goals, they introduce short-term cost pressures and create barriers for smaller players lacking the technical and financial resources to adapt quickly. Second, the industry continues to grapple with raw material volatility. Key inputs such as titanium dioxide, a critical pigment for coverage and finish quality, have experienced notable price fluctuations in recent periods, directly impacting margin stability and pricing strategies for formulators. Third, shifting demand patterns are compelling companies to balance volume-driven residential construction cycles with higher-margin specialty and commercial applications, requiring more agile portfolio management and channel strategies.
PW Consulting Chemical & Energy Research Center
Competitive Concentration and Market Dynamics
The market remains moderately concentrated, with the top three players capturing a significant share of total revenue and the top five collectively accounting for just over half of industry sales. This concentration level suggests that scale advantages, brand recognition, and distribution networks continue to provide meaningful competitive insulation. However, the structure also indicates room for targeted disruption, particularly in segments where performance differentiation, localized formulation capabilities, or direct-to-consumer engagement models can unlock value outside the dominant incumbents. Companies that can align product innovation with regulatory readiness and cost discipline are best positioned to convert market growth into sustained profitability.
Core Drivers Shaping Market Evolution
Technological Innovation and Formulation Advances
Product innovation remains one of the most powerful levers for differentiation in this market. Leading manufacturers have progressively shifted their R&D focus toward water-based systems that deliver superior coverage, improved scrub resistance, and enhanced color retention without compromising environmental performance. One-coat application capabilities, stain-blocking formulations, and low-odor emulsions have moved from premium niche offerings to mainstream expectations, particularly in residential and light commercial settings. Advanced additive technologies are also enabling functional benefits such as anti-fungal properties, air-purifying characteristics, and moisture resistance, which resonate strongly with end-users concerned about indoor air quality and long-term maintenance costs. Companies that integrate these performance attributes with consistent finish quality and ease of application are capturing incremental share, especially in markets where renovation and upgrade cycles are accelerating.
The emphasis on low-VOC and eco-friendly formulations has evolved from a compliance exercise into a competitive necessity. Formulators are leveraging advanced resin technologies and pigment dispersion methods to achieve high opacity and washability while meeting stringent emissions thresholds. This technical progress is particularly relevant as regulatory bodies across multiple regions tighten allowable limits on volatile organic compounds, semi-volatile compounds, formaldehyde, benzene, and heavy metals. Manufacturers that have invested early in reformulation pipelines and testing infrastructure are converting compliance requirements into market-facing advantages, positioning their products as safer, cleaner, and more future-proof options for both professional applicators and DIY consumers.
Policy and Regulatory Environment
Regulatory developments are exerting a decisive influence on product architecture, market access, and competitive positioning. In China, new mandatory national standards governing hazardous substance limits in architectural coatings are set to take effect, replacing earlier frameworks with stricter thresholds across multiple chemical categories. This shift is complemented by compulsory certification requirements for water-based interior wall paints, adding an additional layer of scrutiny to product approvals and supply chain documentation. These measures are accelerating the phase-out of older solvent-heavy formulations and pushing both domestic and international players to localize their compliance strategies.
Across Europe, decorative paint and varnish regulations cap VOC content within defined ranges to reduce ozone-forming emissions, reinforcing demand for low-emission interior wall coatings and encouraging cross-border alignment on sustainability benchmarks. In the United States, stringent VOC limits for architectural coatings, particularly in leading states such as California, continue to shape formulation trends nationwide. Flat interior paints face tighter ceilings than non-flat products, compelling manufacturers to balance performance expectations with regulatory constraints. Collectively, these regulatory trajectories are narrowing the window for legacy formulations and rewarding companies that can demonstrate consistent compliance, transparent ingredient disclosure, and verifiable environmental benefits.
Demand-Side Shifts and Consumer Behavior
Demand patterns are increasingly shaped by a combination of housing market dynamics, renovation activity, and heightened awareness of indoor environmental quality. Residential construction continues to represent the largest application segment, with homeowners and renters prioritizing finishes that combine aesthetic appeal, durability, and ease of maintenance. At the same time, commercial building operators are seeking wall decoration solutions that support tenant retention, reduce lifecycle maintenance costs, and align with green building certifications. Educational and healthcare facilities represent a growing niche where hygiene, low odor, and washability are non-negotiable requirements, creating steady demand for specialized interior coatings.
Consumer expectations are also shifting toward premiumization in key demographics. Buyers are increasingly willing to pay a premium for paints that deliver richer color depth, superior stain resistance, and one-coat coverage, particularly in high-visibility areas such as living rooms, entryways, and commercial interiors. This trend is encouraging manufacturers to expand their premium and super-premium portfolios, while simultaneously pushing value-tier offerings to emphasize functional clarity, reliable performance, and accessible pricing. The result is a more segmented demand landscape where product positioning, channel strategy, and technical communication all play critical roles in capturing the right audience.
Supply Chain and Cost Structure Dynamics
Cost structures in the indoor wall decoration paint market are being reshaped by upstream input volatility and evolving logistics realities. Titanium dioxide, the primary pigment responsible for opacity and coverage, experienced a notable price decline in China during 2025, ending the year at a level that provided some relief to formulators after earlier periods of pressure. While such movements can improve short-term margin flexibility, they also introduce planning complexity, as pricing can reverse quickly in response to supply disruptions, energy costs, and regional demand shifts. Companies that maintain diversified supplier networks, implement strategic inventory buffers, and incorporate flexible pricing mechanisms are better equipped to manage these fluctuations without eroding customer confidence.
Beyond raw materials, supply chain resilience has become a strategic priority. Regulatory changes, certification requirements, and regional compliance standards are forcing manufacturers to strengthen documentation, quality control, and production traceability. At the same time, the growing importance of both professional and retail channels is driving investments in packaging, color matching systems, and application support tools that reduce waste and improve end-user outcomes. Firms that integrate cost discipline with channel-specific value propositions are gaining an edge in a market where price competition alone is rarely sufficient to sustain long-term advantage.
Competitive Landscape and Leading Strategies
Strategic Positioning of Key Players
The competitive field is defined by a mix of global incumbents and regionally dominant specialists, each pursuing distinct pathways to differentiation. Large multinational players are leveraging broad product portfolios, extensive distribution networks, and brand equity to maintain presence across residential, commercial, and specialty segments. Several of these companies have built reputations around premium acrylic latex systems that emphasize superior coverage, scrubbability, and low-VOC formulations, often supported by one-coat application claims and professional-grade color matching services. Their scale enables continued investment in formulation technology, compliance infrastructure, and marketing reach, reinforcing their position in both developed and high-growth markets.
Regional leaders are competing with a different playbook, focusing on localized market knowledge, tailored product lines, and deep relationships with contractors, retailers, and end-users. In Asia, for example, dominant players have built strong associations with luxury finishes, stain repellency, and water-beading technologies, while also expanding low-VOC and washable emulsion offerings to meet evolving sustainability expectations. Other regional specialists have differentiated through functional coatings that address specific pain points such as anti-fungal performance, odor reduction, and easy-clean surfaces, making their products particularly attractive in humid climates and high-traffic environments. Specialist and value-oriented brands, meanwhile, are carving out share through retail-focused formulations that balance one-coat coverage, stain-blocking, and accessible pricing, appealing to DIY consumers and budget-conscious professional buyers alike.
Differentiation Advantages and Capability Gaps
Across the competitive set, companies that consistently outperform tend to share several capability advantages. Strong formulation expertise enables them to deliver high opacity, color depth, and durability while meeting regulatory thresholds. Robust quality assurance and certification readiness allow faster market access in jurisdictions with strict compliance requirements. Effective channel management ensures that products reach both professional applicators and retail consumers with appropriate technical support, color selection tools, and application guidance. Brand trust and consistent finish quality further reinforce repeat purchases and professional recommendations, which remain influential in a category where visual results and long-term performance matter deeply to end-users.
Conversely, gaps in these areas create vulnerability. Manufacturers that lag in low-VOC reformulation, lack transparent certification pathways, or rely too heavily on legacy solvent-based systems face increasing risk as regulations tighten and buyer preferences shift. Companies that fail to invest in application support, color consistency, or retail experience may struggle to justify premium pricing or defend against competitors offering comparable performance at lower cost. In a market with moderate concentration, such gaps can be exploited by rivals with more agile product development cycles or stronger regional execution.
Evolving Market Structure and Entry Dynamics
The market structure is gradually evolving along two parallel tracks: consolidation among scale players seeking broader geographic and segment coverage, and fragmentation in niche or high-growth regions where localized expertise and functional specialization create openings for focused competitors. M&A activity, brand portfolio optimization, and distribution partnerships are likely to shape the next phase of industry evolution, particularly as companies look to strengthen their presence in high-growth regions and expand into premium or specialty decorative coatings. At the same time, new entrants and smaller regional brands can still gain traction by targeting underserved application needs, leveraging digital color visualization tools, or building direct engagement models that resonate with modern consumers. The result is a dynamic landscape where scale provides advantages, but execution quality, regulatory readiness, and customer-centric innovation determine who captures disproportionate value.
Future Trends and Forward Outlook
Accelerated Adoption of Low-Emission and Functional Coatings
Over the next three to five years, low-emission interior wall coatings are expected to move from a compliance-driven requirement to a baseline market expectation. As regulatory thresholds tighten across major regions and buyer awareness of indoor air quality continues to rise, formulators will increasingly prioritize water-based systems that combine high performance with reduced environmental impact. Functional benefits such as stain resistance, anti-fungal protection, odor control, and air-purifying properties will become more common across premium and mid-tier portfolios, not just specialty lines. This trend creates opportunities for companies that can communicate verifiable performance benefits, maintain consistent finish quality, and align product claims with recognized certification or testing standards.
Premiumization and Segment-Specific Portfolio Strategies
Demand segmentation is likely to deepen, with residential, commercial, and institutional applications drawing increasingly distinct product requirements and purchasing criteria. In residential settings, homeowners and renovators will continue to seek finishes that deliver visual richness, easy maintenance, and application convenience, supporting continued premiumization in color depth, coverage, and durability. Commercial and institutional buyers will place greater weight on lifecycle costs, hygiene performance, and alignment with green building standards, favoring coatings that reduce repainting frequency and support indoor environmental quality goals. Manufacturers that develop segment-specific portfolios rather than relying on one-size-fits-all offerings will be better positioned to capture margin and defend share in a maturing market.
Cost Volatility, Compliance Investment, and Strategic Risk
Despite the favorable growth outlook, several uncertainty factors warrant attention. Raw material pricing can shift quickly, particularly for key pigments and resins, creating margin volatility that requires disciplined procurement and pricing strategies. Regulatory complexity is likely to increase rather than stabilize, with more jurisdictions introducing stricter VOC limits, hazardous substance restrictions, and mandatory certification processes. Companies that delay compliance investments or depend on outdated formulations risk lost market access, reputational exposure, and higher reformulation costs later. Additionally, macroeconomic fluctuations in construction and renovation activity can create uneven demand cycles, making portfolio flexibility and channel diversification important risk mitigation tools. The central strategic question for leaders will be how to balance cost efficiency, compliance readiness, and product differentiation in a market where all three dimensions interact continuously.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
Invest early in low-VOC and water-based formulation capabilities, and treat compliance as a competitive advantage rather than a cost center. Prioritize product lines that combine high coverage, durability, and functional benefits with clear, verifiable environmental claims. Strengthen quality assurance and certification readiness to accelerate market access in regions with tightening standards, and consider portfolio segmentation that aligns premium, mid-tier, and value offerings with distinct use cases and channels. Finally, review supplier diversification and inventory planning for critical inputs to reduce exposure to raw material price swings.
Interior Stain Market
For Investors and Strategic Buyers
Evaluate companies based on their formulation pipeline, regulatory readiness, regional execution strength, and ability to capture premiumization trends without overrelying on price competition. Look for players with strong brand positioning in water-borne and specialty decorative coatings, as well as those demonstrating disciplined cost management and channel flexibility. In consolidation scenarios, assess whether target companies bring complementary geographic reach, technical capabilities, or segment expertise that can accelerate growth in high-value applications. Pay close attention to compliance infrastructure and certification status, since these factors increasingly influence market access and brand trust.
For Procurement and Channel Decision-Makers
Prioritize suppliers that can demonstrate consistent color performance, low-emission compliance, and application reliability across residential, commercial, and institutional projects. Request clear documentation on VOC limits, certification status, and product performance claims, especially when specifying finishes for healthcare, education, or green building projects. Balance premium options for high-visibility areas with value-tier solutions for routine refresh cycles, and work with partners who offer robust color matching, technical support, and waste-reducing application guidance. Building a diversified supplier base can also help mitigate pricing volatility and ensure continuity as regulatory requirements evolve.
The indoor wall decoration paint market is entering a phase where growth is increasingly tied to product performance, regulatory alignment, and segment-specific execution. Companies and investors that maintain disciplined focus on formulation quality, compliance readiness, and customer-centric innovation will be best positioned to navigate the next wave of market change. For decision-makers seeking deeper segmentation data, regional dynamics, and tailored scenario planning, the full research report provides expanded detail and actionable frameworks to support strategic planning.
Paint Market
For detailed analysis of this topic, please visit the official page: Indoor Wall Decoration Paint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com