

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Circuit Breakers for New Energy Power Generation: The 8.25% CAGR Redefining Market Dynamics

Circuit Breakers for New Energy Power Generation: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for circuit breakers dedicated to new energy power generation has entered a period of accelerated, structurally driven expansion. Valued at approximately $2.05 billion in 2020, the market crossed the $3.1 billion threshold by 2025, reflecting a compound annual growth rate of 8.25 percent through 2032. By the end of the forecast horizon, total market revenue is projected to surpass $5.4 billion. This trajectory is not merely a reflection of broader renewable capacity additions; it signals a fundamental shift in how electrical protection systems are specified, engineered, and integrated into modern power generation architectures.
Despite the robust expansion, the sector faces several structural inflection points that will dictate competitive outcomes over the next half-decade. First, the transition toward inverter-based and DC-coupled generation assets is outpacing legacy protection paradigms. Traditional alternating-current circuit breaker frameworks, while mature, are increasingly mismatched with the fault behavior, response timing, and interconnection requirements of solar arrays, wind farms, and battery energy storage systems. Engineers and project developers must navigate a fragmented standards landscape while balancing reliability, switching speed, and system efficiency.
Second, material cost volatility has introduced sustained pressure on manufacturing margins and pricing predictability. The surge in industrial metal benchmarks during early 2026, including sharp year-over-year increases in copper, aluminum, and steel mill products, directly translates into higher input costs for wiring, contact assemblies, and structural housings. Suppliers that lack agile procurement frameworks or pricing pass-through mechanisms are facing compressed profitability, particularly in mid-voltage segment where competition remains intense.
Third, regulatory recalibration in key demand regions is reshaping project economics and procurement timelines. In the United States, recent legislative adjustments have altered the incentive architecture for solar and wind deployments, tightening placed-in-service requirements and expanding foreign entity restrictions. These changes do not eliminate demand, but they compress development windows, shift procurement toward compliant supply chains, and elevate the importance of equipment that can accelerate interconnection approvals and reduce commissioning risk.
Key Drivers Shaping Market Dynamics
Technological Innovation and Protection Architecture Evolution
The most consequential force reshaping the market is the rapid evolution of protection technologies tailored to new energy topologies. Manufacturers are moving beyond incremental improvements in interrupting capacity and are rearchitecting breakers for hybrid AC/DC environments, high-frequency inverter interfaces, and modular storage configurations. Vacuum-based solutions continue to dominate where high reliability and minimal maintenance are priorities, while air-blast and specialized contact designs are being optimized for higher current ratings and faster arc extinguishment in wind and utility-scale solar applications.
PW Consulting Chemical & Energy Research Center
A notable shift is the accelerated development of DC-rated and hybrid-switching solutions. Collaborative engineering efforts between major equipment suppliers are producing specification frameworks for multi-terminal high-voltage direct current systems, directly enabling large-scale renewable integration and offshore wind aggregation. These initiatives are not isolated R&D exercises; they are translating into commercially viable product roadmaps that address the unique fault currents and commutation challenges inherent to DC-coupled generation and storage assets.
Policy, Regulation, and Grid Modernization Mandates
Regulatory frameworks and grid code requirements are acting as powerful demand amplifiers, particularly where transmission constraints and interconnection backlogs are pressing policymakers to streamline approvals. Regions that have tied renewable portfolio standards or clean energy targets to grid readiness are seeing heightened specification requirements for protection equipment that can satisfy both utility compliance and fast-response operational profiles.
At the same time, environmental and emission-related expectations are influencing technology selection. The broader industry movement toward reducing reliance on high-global-warming-potential gases has spurred the commercial introduction of SF6-free breaker families and alternative insulating media. Utilities and developers increasingly factor sustainability credentials into procurement decisions, especially for public-sector tenders and projects with corporate offtake commitments that require alignment with decarbonization goals.
DC Circuit Breaker Market
Demand-Side Shifts and Application Diversification
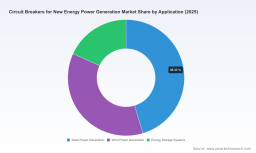
On the demand side, the convergence of generation and storage is altering specification patterns. Solar installations continue to drive substantial volume, but wind power and energy storage systems are expanding the addressable base for specialized protection components. Storage deployments, in particular, introduce bidirectional power flow, rapid cycling, and hybrid AC/DC interfaces that require breakers capable of handling diverse operational modes without compromising safety or service life.
Corporate procurement behavior is also evolving. Developers and independent power producers are prioritizing equipment that reduces integration complexity, supports remote monitoring, and minimizes field commissioning time. This has elevated the value of digitally enabled interfaces and modular designs that can be scaled across project portfolios, from distributed solar to utility-scale hybrid plants.
Supply Chain Reconfiguration and Cost Structure Pressures
Supply chain dynamics remain a critical driver of both risk and opportunity. The recent spike in base metal prices has rippled through component manufacturing, affecting everything from conductive elements to mechanical assemblies. Suppliers that operate with vertically integrated production, long-term raw material contracts, or diversified sourcing networks are better positioned to stabilize output costs. Conversely, reliance on spot-market procurement is exposing manufacturers to margin erosion and delivery uncertainty.
Simultaneously, geopolitical and compliance considerations are reshaping sourcing strategies for North American and European projects. Equipment that aligns with localization expectations, transparent supply chain documentation, and evolving foreign entity restrictions is gaining preference in tenders where project financing and permitting depend on demonstrable compliance. This dynamic is encouraging both incumbent suppliers and regional manufacturers to reinforce domestic or nearshore production capabilities.
Worldwide Classified Circuit Breaker Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderately concentrated field of global incumbents, specialized regional players, and emerging niche suppliers. The top three competitors collectively account for slightly more than one-third of market revenue, while the top five approach just above half, leaving substantial room for differentiated positioning and regional share gains. This structure favors players that can combine scale, technical specialization, and responsive localization rather than those competing solely on price.
Strategic Positioning and Differentiation Levers
Leading participants are pursuing distinct differentiation pathways. Global manufacturers with broad switchgear portfolios are emphasizing high-current ratings, generator-protection specialization, and end-to-end integration for renewable and gas-based generation assets. Recent product launches targeting next-generation wind turbines and refurbished power plants illustrate a strategy centered on expanding the operational envelope of breaker families, enabling them to serve both new capacity and modernization programs.
A second group is concentrating on sustainability-driven innovation and grid-modernization alignment. Suppliers offering SF6-free interrupting technologies, digitalized medium-voltage switchgear, and IoT-enabled protection devices are positioning their products as enablers of lower-emission operations and predictive maintenance workflows. These offerings resonate with utilities and developers seeking to meet environmental targets while improving asset visibility across distributed portfolios.
A third cohort, often originating in Asia, is focusing on application-specific DC protection, solar PV interfaces, and battery energy storage compatibility. These companies have built credibility around specialized photovoltaic DC switchgear and storage-oriented protection components, frequently competing on application fit, cost efficiency, and rapid adaptation to regional project requirements. Their growth reflects the broader shift toward distributed and hybrid installations where tailored protection solutions can command premium positioning.
Market Evolution: Consolidation, Specialization, and New Entrants
The landscape is evolving along two parallel tracks. Large incumbents are deepening their capabilities through collaboration and targeted product expansion, pairing AC protection expertise with DC switching development to address transmission-scale renewable integration. These partnerships are accelerating specification maturity for multi-terminal systems and creating cross-licensing opportunities that broaden technology access without requiring every player to build every capability internally.
At the same time, market fragmentation persists at the application and regional levels. New and expanding entrants are carving out positions in solar DC protection, storage switchgear, and medium-voltage solutions for renewable facilities. This specialization creates a dynamic environment where incumbents must defend broad-platform advantages while remaining responsive to niche demands that can rapidly scale into significant volume pools. The net effect is a market in which success depends on balancing portfolio breadth with deep application engineering, localized supply resilience, and the ability to align product roadmaps with evolving grid codes and procurement criteria.
Future Outlook for 2027 to 2032
Over the next three to five years, the market is likely to be shaped by three interlocking trends. First, DC and hybrid protection architectures will move from emerging to mainstream in a growing share of solar-plus-storage and offshore wind projects. As inverter-based resources and storage systems become more tightly integrated, demand for breakers designed for bidirectional flow, fast fault response, and DC commutation will expand beyond specialized deployments into broader project specifications. Commercial opportunities will accrue to suppliers that can offer tested, code-aligned DC solutions with clear interoperability pathways and field-service support.
Second, sustainability requirements and digital integration will increasingly function as procurement gatekeepers rather than optional enhancements. SF6-free product lines, lower-emission manufacturing practices, and connected protection devices capable of remote diagnostics will become standard expectations in utility tenders and corporate-backed developments. This creates opportunities for suppliers to bundle hardware with service-oriented value propositions, including monitoring platforms, predictive maintenance tools, and lifecycle support contracts that improve total-cost-of-ownership outcomes.
Third, regional supply realignment will continue as project developers navigate incentive uncertainty, interconnection delays, and compliance requirements. Markets with strong renewable deployment pipelines but challenged transmission timelines will favor equipment that accelerates commissioning, reduces interconnection risk, and aligns with localization expectations. Suppliers that can demonstrate reliable delivery, documentation transparency, and adaptability to shifting regulatory parameters will be better positioned to capture share, particularly where project economics are sensitive to schedule compression.
The principal uncertainties tempering this outlook include ongoing raw material price swings, the pace at which DC protection standards mature across jurisdictions, and the potential for incentive recalibration to alter project pipelines in key regions. These variables do not negate long-term growth, but they reward flexibility. Companies that can adjust product mix, secure resilient input channels, and align engineering roadmaps with evolving grid and regulatory conditions will be best equipped to convert market expansion into durable commercial gains.
Strategic Implications for Decision Makers
For manufacturers, the priority is to align product roadmaps with the convergence of DC integration, sustainability expectations, and digital service demands. Developing modular, application-specific protection platforms and pairing them with monitoring or maintenance capabilities can differentiate offerings in a market where hardware specifications are increasingly table stakes. Equally important is securing supply chain resilience through diversified sourcing, long-term material contracts, or localized production to mitigate input-cost volatility.
For investors, the opportunity lies in identifying companies with clear technological adjacencies, particularly those bridging AC protection expertise with DC switching development or those expanding into storage and hybrid plant interfaces. Suppliers with strong application engineering, credible sustainability roadmaps, and the ability to serve both utility-scale and distributed segments offer broader exposure to the structural growth trajectory. Attention to regional compliance readiness and supply chain transparency will be critical when evaluating near-term scalability.
For procurement teams and project developers, equipment selection should extend beyond interrupting ratings and price. Evaluating compatibility with DC-coupled architectures, SF6-free options, digital integration capabilities, and supplier localization profiles can reduce interconnection risk, accelerate commissioning, and support long-term sustainability commitments. In an environment where project timelines and regulatory parameters are shifting, partnering with suppliers that offer specification flexibility and reliable delivery can materially improve project outcomes.
Detailed segmentation data, regional volume breakdowns, company-level positioning maps, and scenario-based forecasts are available in the full research report for teams that require granular inputs for portfolio planning, investment evaluation, or procurement strategy.
For detailed analysis of this topic, please visit the official page: Circuit Breakers for New Energy Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com