

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Germacrene D Market 5.02% CAGR: Why Fragrance Demand Drives $29.3M Growth by 2032

Germacrene D Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for Germacrene D has demonstrated consistent expansion over the past five years, moving from approximately $16.5 million in 2020 to an estimated $20.8 million in 2025. This trajectory reflects a compound annual growth rate of 5.02 percent, with projections indicating the market will reach $29.3 million by 2032. The steady upward curve underscores growing industrial reliance on specialized sesquiterpenes across multiple application verticals. However, beneath these aggregate figures lies a complex landscape shaped by supply chain vulnerabilities, regulatory evolution, and shifting consumer expectations.
One of the most pressing challenges facing market participants is the convergence of raw material volatility and sustainability mandates. Germacrene D is primarily sourced as a sesquiterpene from essential oils of plants such as Solidago canadensis or produced via microbial fermentation from renewable sugar-based feedstocks. Both pathways carry distinct risk profiles. Botanical extraction is subject to agricultural yield fluctuations, climate variability, and land-use constraints, while fermentation-based routes demand capital-intensive bioreactor infrastructure and face scaling bottlenecks. Companies must navigate these dual supply realities while maintaining cost competitiveness and meeting increasingly stringent environmental standards.
A second critical inflection point involves the tightening regulatory framework governing fragrance and flavor ingredients. Recent safety assessments have clarified the risk profile of Germacrene D, with a 2024 evaluation concluding no genotoxicity or skin sensitization concerns at current declared fragrance use levels. While this provides regulatory certainty, it also raises the bar for documentation, traceability, and compliance verification. Suppliers must invest in robust quality management systems and maintain alignment with evolving standards such as EU Regulation (EC) No 1334/2008 and US CFR 101.22 for natural flavor use. The burden of compliance disproportionately affects smaller manufacturers, potentially accelerating market consolidation.
A third structural challenge lies in balancing purity requirements across divergent application segments. The market spans natural extract grades with specified purity levels alongside high-purity reagent grades used in research and specialized formulations. Each grade demands distinct production protocols, validation procedures, and customer engagement models. Manufacturers that attempt to serve both segments without clear operational segmentation risk margin erosion, quality inconsistencies, or brand positioning conflicts. The ability to cleanly separate production streams and communicate value propositions to different buyer personas has become a decisive competitive factor.
Key Drivers of Market Evolution
Technological Innovation and Fermentation Breakthroughs
Advancements in microbial fermentation have fundamentally altered the supply dynamics of Germacrene D. Fermentation-based production enables consistent output independent of seasonal agricultural cycles, reduces reliance on land-intensive crop cultivation, and aligns with circular economy principles when paired with renewable sugar feedstocks. Several industry participants have demonstrated that carefully optimized bioprocesses can achieve purity levels suitable for flavor and fragrance applications while maintaining certifications such as kosher, halal, and pesticide-free status. These capabilities expand the addressable market by offering formulators a reliable, scalable alternative to botanical extraction, particularly in regions where agricultural supply chains face disruption or where traceability requirements are intensifying.
Beyond production methods, downstream formulation technologies are also shaping demand. The integration of Germacrene D into complex fragrance architectures requires precise understanding of its olfactory profile, stability characteristics, and interaction with other aroma chemicals. Suppliers that invest in application labs, sensory evaluation capabilities, and technical support services create stickier customer relationships and command premium positioning. This shift from commoditized molecule supply to integrated solution provision represents a meaningful margin opportunity for organizations willing to build technical depth.
Regulatory Clarity and Certification Momentum
Regulatory developments have moved from ambiguous risk discussions to more definitive safety conclusions, providing a foundation for confident commercialization. The affirmation of a FEMA GRAS number and compliance with major food and fragrance regulations reduce barriers to adoption in end-use products. Concurrently, certification renewals and expansions, such as the renewal of kosher certification for fermentation-derived Germacrene D through early 2026, signal ongoing commitment to dietary and religious compliance standards that matter to global brand owners.
These regulatory and certification dynamics are not merely compliance exercises; they function as market access enablers. Multinational consumer goods companies require ingredient suppliers to demonstrate harmonized compliance across multiple jurisdictions. Suppliers that proactively maintain and document certifications across EU, US, and international frameworks reduce friction in the procurement process and become preferred partners for large-scale formulation projects. The regulatory environment thus rewards completeness and transparency over speed-to-market alone.
Demand-Side Shifts Toward Natural and Sustainable Ingredients
Consumer and brand preferences continue to gravitate toward natural-origin and sustainably sourced ingredients. In the fragrance and personal care sectors, this trend drives formulators to seek sesquiterpenes that can deliver characteristic woody-spicy, minty, or herbal notes while meeting clean-label expectations. The commercial appeal extends beyond marketing narratives; it influences procurement specifications, supplier qualification criteria, and long-term contract structures. Brands are increasingly willing to pay a premium for ingredients that combine verified natural status with reliable supply and consistent sensory performance.
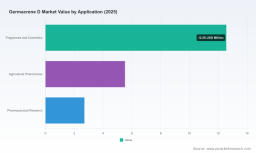
Parallel demand is emerging from agricultural pheromone applications, where Germacrene D serves as a component in insect attractant and mating disruption formulations. This segment benefits from broader agricultural trends emphasizing reduced synthetic pesticide reliance and integrated pest management strategies. While smaller in absolute terms compared to fragrance and cosmetics, the agricultural pheromone segment offers diversification benefits and growth potential tied to regulatory pressure on conventional agrochemicals and expanding adoption of biocontrol methods.
Supply Chain Restructuring and Cost Dynamics
Cost structures in the Germacrene D market are being reshaped by logistics complexity, energy input requirements, and the economics of scale. Fermentation-based routes, while offering supply stability, involve significant upfront capital expenditure and operational expertise in bioprocess engineering. Botanical extraction pathways face fluctuating input costs tied to crop yields and geographic sourcing constraints. In both cases, organizations that achieve scale, optimize yield per unit of input, and streamline downstream purification can establish meaningful cost advantages.
Farnesene Market
Supply chain resilience has also become a strategic priority. Buyers are increasingly evaluating suppliers not only on price and purity but on geographic diversification, inventory buffering capabilities, and contingency planning. The market concentration, with the top three participants holding a modest share and the top five capturing a slightly larger portion, indicates room for both specialized niche players and larger diversified ingredient companies. This fragmentation creates opportunities for regional suppliers to secure local partnerships while inviting larger entities to pursue selective acquisitions that broaden geographic reach and technical portfolios.
Competitive Landscape and Leading Strategies
Differentiation Through Positioning and Technical Capability
Market participants have adopted distinct strategic postures that reflect their organizational capabilities and target customer segments. Some companies emphasize fermentation-derived natural Germacrene D with comprehensive dietary and regulatory certifications, positioning themselves as reliable partners for flavor and fragrance formulators who require clean-label compliance and consistent supply. This approach combines biotechnological manufacturing with rigorous quality documentation, appealing to brand owners who prioritize transparency and auditability.
Other organizations focus on high-purity reagent and fragrance-grade products packaged for industrial and research use. These suppliers cater to application development, analytical testing, and specialized formulation work, where purity specifications and packaging integrity take precedence over natural-origin claims. By maintaining strict quality controls and offering flexible packaging options, these participants serve a different buyer persona that values technical precision and rapid availability over certification breadth.
Large flavor and fragrance houses with diversified botanical extraction capabilities include Germacrene D within broader portfolios of natural-origin ingredients. Their strategic advantage lies in integrated supply chains, established customer relationships, and the ability to offer formulation guidance alongside raw material supply. For these organizations, Germacrene D is one element of a larger sustainable sourcing narrative, supported by eco-friendly extraction practices and long-standing botanical expertise. Their scale and brand recognition provide credibility with multinational clients, while their portfolio breadth allows cross-selling and formulation synergy.
Recent Strategic Moves and Market Signals
Recent industry activity highlights how participants are sharpening their competitive positioning. A fermentation-based supplier renewed kosher certification for its natural Germacrene D product, reinforcing its commitment to dietary compliance and maintaining eligibility for markets where such certification is a procurement prerequisite. This type of certification maintenance may appear routine, but it signals ongoing operational discipline and protects market access in segments where religious and dietary standards influence purchasing decisions.
A major global fragrance and flavor company introduced a Germacrene D-based fragrance ingredient as part of an expanded natural-origin portfolio. This launch illustrates the use of targeted molecule development to refresh ingredient offerings, respond to formulator demand for specific olfactory profiles, and reinforce sustainability messaging. By embedding Germacrene D within a broader portfolio narrative, the company leverages the molecule's sensory characteristics while aligning with brand-level commitments to natural sourcing.
Another significant move involved a strategic partnership between two ingredient companies to co-develop sustainable fragrance ingredients, including Germacrene D, with an emphasis on resilient natural sourcing. Collaborative development arrangements allow participants to share technical risk, pool botanical or bioprocess expertise, and accelerate time-to-market for improved ingredients. Such partnerships also reflect an industry-wide recognition that sustainability and supply resilience are not easily achieved in isolation; they often require joint investment in sourcing relationships, process optimization, and certification alignment.
Sclareolide Market
Market Structure Evolution
The competitive landscape is undergoing gradual transformation rather than abrupt disruption. Market concentration remains moderate, indicating that no single entity dominates supply and that differentiated positioning can still yield viable market share. Over the forecast horizon, several dynamics are likely to shape structure. Larger ingredient companies may pursue selective acquisitions to fill technical gaps, expand geographic coverage, or bring fermentation capabilities in-house. Specialized manufacturers with unique purity profiles, certification portfolios, or regional sourcing advantages can maintain strong niche positions by serving customers who value specificity over breadth. New entrants with novel bioprocess technologies or alternative feedstock strategies may emerge if they can demonstrate cost parity, regulatory compliance, and scalable production.
The overall trend points toward a market where value creation shifts from volume-only competition to capability-based differentiation. Suppliers that combine reliable production, regulatory completeness, technical support, and sustainability credentials will be better positioned to command favorable terms and build long-term partnerships. Conversely, participants that compete solely on price without clear quality or compliance differentiation may face margin pressure as buyers increasingly weigh total cost of ownership and supply risk.
PW Consulting Chemical & Energy Research Center
Future Trends and Commercial Implications
Convergence of Natural Certification and Biotechnological Scale
Over the next three to five years, the intersection of natural-certification requirements and fermentation scalability will likely become a central theme. As formulators seek ingredients that satisfy both sensory expectations and sustainability mandates, suppliers capable of delivering certified natural-status molecules through reproducible bioprocesses will capture growing demand. The commercial opportunity lies in offering a credible alternative to botanically sourced sesquiterpenes while maintaining documentation that satisfies global regulatory and consumer expectations. Organizations that invest early in process optimization, certification breadth, and supply transparency can establish defensible positions before the segment becomes crowded.
Expansion of Application Diversification
Application diversification represents another meaningful trend. While fragrance and cosmetics continue to anchor demand, agricultural pheromone formulations and specialized research uses provide adjacent growth avenues. The agricultural segment, in particular, benefits from structural shifts toward reduced synthetic pesticide reliance and increased adoption of behavioral pest control methods. Suppliers that develop technical expertise in pheromone formulation requirements, stability testing, and field-performance considerations can extend their reach beyond traditional aroma chemical markets. This diversification also serves as a hedge against cyclicality in consumer-facing fragrance spending, smoothing revenue profiles across economic cycles.
Regulatory and Compliance Sophistication as Competitive Moat
Regulatory sophistication will increasingly function as a competitive moat rather than a baseline requirement. As safety assessments solidify and certification frameworks mature, the ability to maintain harmonized compliance across jurisdictions becomes a differentiator. Buyers will favor suppliers that provide clear documentation, predictable audit outcomes, and proactive engagement with evolving standards. The risk side of this trend involves the possibility of regulatory divergence across regions or the emergence of new substance-specific requirements that challenge existing production or labeling practices. Companies that monitor regulatory developments closely and maintain flexible quality systems will be better prepared to adapt without disrupting customer supply.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient suppliers, the priority is to clarify segment focus and align operational capabilities with the value propositions that matter most to target customers. Companies serving fragrance and flavor formulators should invest in certification maintenance, application support, and supply transparency. Those focused on high-purity reagent or research-grade markets should emphasize quality control rigor, packaging integrity, and technical documentation. In both cases, building a clear narrative around sourcing, production method, and compliance status helps reduce customer uncertainty and supports pricing discipline.
Investors evaluating opportunities in this space should weigh the balance between scale advantages and specialization premiums. Larger diversified ingredient platforms offer portfolio breadth and customer relationships that can absorbGermacrene D within broader sustainable sourcing strategies. Specialized participants with differentiated fermentation capabilities, certification portfolios, or regional sourcing strengths may offer attractive growth profiles if they can demonstrate reproducible quality and market access. Due diligence should examine production scalability, regulatory standing, customer concentration, and the durability of any purity or certification advantages.
For procurement leaders and formulation teams, supplier selection should extend beyond unit price to encompass compliance documentation, supply resilience, technical support, and long-term sourcing strategy. Engaging suppliers that can articulate their production method, certification status, and continuity planning reduces downstream risk and facilitates smoother product development cycles. Early involvement of ingredient suppliers in formulation projects can also surface technical considerations before they become costly redesigns.
Market participants and investors seeking detailed segmentation data, competitive benchmarking, and customized scenario analysis will find value in consulting the complete research report, which provides deeper breakdowns of regional dynamics, purity-grade trends, application-specific demand patterns, and firm-level strategic profiles.
For detailed analysis of this topic, please visit the official page: Germacrene D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com