

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
OLED Vapor Deposition Materials: Why 17.02% CAGR and Asia’s Dominance Redefine This Market

Strategic Trends and Commercial Opportunities in the OLED Vapor Deposition Materials Market
Market Overview and Structural Shifts
The global market for OLED vapor deposition materials has entered a phase of accelerated expansion, driven by the widespread adoption of organic light-emitting diode technology across consumer electronics and automotive sectors. Industry data indicates that the market generated approximately 2.17 billion USD in 2025, reflecting a compound annual growth rate of 17.02 percent over the historical period from 2020 to 2025. Projections suggest continued momentum, with the market expected to reach 2.58 billion USD in 2026 and expand further to 6.51 billion USD by 2032. This trajectory underscores the critical role that high-purity evaporation materials play in enabling advanced display architectures, particularly as manufacturers transition from solution processing to vacuum-based thermal evaporation for improved efficiency, longevity, and pixel density.
Several structural challenges are shaping the competitive landscape. First, the energy intensity of vacuum deposition processes remains a significant operational burden. Manufacturing facilities relying on traditional thermal evaporation require substantial power consumption, which amplifies production costs and contributes to the overall carbon footprint of display fabrication. As environmental scrutiny intensifies and energy prices fluctuate, producers must balance performance optimization with sustainability mandates. Second, raw material supply chains face increasing pressure. The demand for electronic-grade precursors and specialized intermediates has grown alongside panel production capacity, particularly in large-format manufacturing hubs. Volatility in the availability and pricing of key chemical inputs introduces margin uncertainty for material suppliers and downstream display makers alike. Third, the market exhibits a high degree of concentration among established players, with the top three firms controlling a substantial share of revenue. While this concentration signals technical maturity and strong intellectual property positions, it also raises questions about supply resilience and the pace of innovation entry from emerging suppliers seeking to scale capabilities in specific material segments.
Demand-Side Evolution and Application Diversification
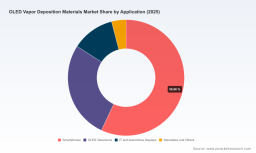
Consumer behavior and enterprise purchasing patterns are reshaping the demand profile for vapor deposition materials. Smartphones continue to represent a core application segment, but growth dynamics are shifting as device manufacturers pursue higher resolution, improved color accuracy, and thinner form factors. The transition toward premium display specifications increases the consumption of specialized emissive and transport layer materials per unit, amplifying the value contribution of high-performance evaporation compounds. At the same time, new application categories are gaining traction. OLED televisions, information technology displays, and automotive interfaces are expanding the addressable market beyond mobile devices, creating additional volume demand for functional layers optimized for large-area and high-reliability deposition conditions.
Wearable devices and emerging form factors further diversify the demand base. As manufacturers integrate OLED panels into smartwatches, augmented reality optics, and foldable or rollable devices, material requirements become more stringent regarding uniformity, thermal stability, and compatibility with complex stack architectures. This diversification does not merely add volume; it alters the product mix, favoring suppliers that can offer differentiated material solutions tailored to specific deposition environments and performance targets. The broadening application landscape also encourages panel makers to diversify their supplier bases, reducing dependency on single-source materials and creating openings for qualified alternatives that can meet stringent quality and yield standards.
Regional Dynamics and Geographic Concentration
The Asia Pacific region accounts for the majority of market revenue, reflecting the concentration of panel manufacturing capacity, consumer electronics production, and associated material supply chains in the region. North America and Europe represent smaller but strategically significant shares, driven by advanced display development, equipment integration, and specific high-value material applications. The rest of the world contributes a modest portion of overall revenue, though localized fabrication initiatives and supply chain diversification efforts could gradually alter this distribution over the forecast period.
Geographic concentration carries both advantages and risks. Centralized manufacturing ecosystems enable close collaboration between equipment providers, material suppliers, and panel fabricators, accelerating process optimization and reducing time-to-market for new technologies. However, heavy reliance on a limited set of regions can expose the industry to logistical disruptions, regulatory changes, and geopolitical shifts. As a result, stakeholders are increasingly evaluating supply chain resilience, considering alternative sourcing pathways, and monitoring the emergence of regionally integrated material production capabilities that could support broader geographic diversification without sacrificing process compatibility or material performance.
Key Drivers Propelling Market Expansion
Technological Innovation and Material Performance Advances
Continuous improvements in material chemistry and deposition engineering remain the primary catalysts for market growth. Phosphorescent OLED emitter materials have demonstrated superior efficiency and lifespan characteristics, particularly when optimized for vacuum thermal evaporation processes. Advances in host materials, charge transport layers, and hole injection compounds contribute to higher luminous efficiency, lower driving voltage, and improved device reliability. These performance gains are critical as display manufacturers push toward higher resolutions and more demanding operating conditions. The ability to achieve consistent film uniformity, precise layer thickness control, and stable charge balance across large substrates directly influences yield and final product quality, making material performance a decisive competitive factor.
Recent equipment and process innovations reinforce the material-driven growth narrative. Applied Materials introduced a MAX OLED solution featuring an advanced angle-controlled evaporator and a novel material deposition method designed to improve pixel brightness, resolution, energy efficiency, and lifespan during vapor deposition. Such developments illustrate how equipment and material capabilities are co-evolving, with process improvements unlocking new value from existing material formulations and encouraging further refinement of evaporation-compatible compounds.
Sustainability Pressures and Regulatory Dynamics
Environmental and regulatory considerations are increasingly influencing material development and procurement strategies. Vacuum deposition processes are energy-intensive, and the associated carbon footprint of production has attracted attention from regulators, corporate sustainability teams, and end customers. In response, the industry is exploring pathways to reduce energy consumption, improve material utilization, and incorporate recycled or eco-friendly alternatives where feasible. Samsung SDI's sustainability reporting highlights efforts to develop recyclable and environmentally conscious OLED materials, reflecting a broader industry trend toward aligning performance goals with responsible sourcing and end-of-life considerations.
Regulatory uncertainty also affects raw material management. Global environmental regulations and supply stability concerns are prompting manufacturers to evaluate the lifecycle implications of precursor selection, solvent use, and material disposal. These pressures do not merely constrain operations; they create incentives for innovation in material design, process efficiency, and waste reduction. Suppliers that can offer materials compatible with lower-energy deposition parameters or that demonstrate reduced environmental impact may secure preferential positioning in procurement evaluations, particularly among panel makers with public sustainability commitments.
Supply Chain Restructuring and Regional Supplier Evolution
The material supply base is undergoing gradual restructuring as regional capabilities mature and new entrants seek to capture share in high-growth segments. In China, OLED evaporation material suppliers are expanding their market presence, with industry reports indicating that one company is projected to enter the global top ten in 2025. This shift reflects investments in material synthesis, purification, and process compatibility that enable domestic and regional panel makers to access qualified alternatives to long-established international suppliers. The trend contributes to a more multipolar supply landscape, particularly for intermediates and functional layer materials where localized production can reduce logistics costs, shorten lead times, and provide greater continuity in periods of global market volatility.
At the same time, raw material consumption patterns are intensifying. Electronic-grade silane, for example, sees annual consumption exceeding 500 metric tons per new Gen 8.6 or Gen 10.5 AMOLED fab in China, underscoring the scale of precursor demand as manufacturing capacity expands. Such volume requirements highlight the importance of stable upstream supply, purification consistency, and cost management. Suppliers that can guarantee purity, batch-to-batch reproducibility, and reliable delivery volumes will be better positioned to support large-scale fabrication without exposing panel makers to quality drift or production interruptions.
Demand-Side Behavior and Portfolio Diversification
Demand is being shaped not only by volume growth but also by the pursuit of differentiated display experiences. Consumers and enterprise buyers increasingly expect higher contrast, wider color gamuts, and adaptive display characteristics across devices ranging from flagship smartphones to in-vehicle infotainment systems. These expectations translate into more complex stack designs and greater reliance on specialized vapor deposition materials that can deliver consistent performance under varied operating conditions. As a result, panel manufacturers are incentivized to adopt materials that support multi-functionality, such as improved charge balance, enhanced thermal stability, and compatibility with fine-pitch patterning.
The diversification of application portfolios also affects procurement behavior. When display usage spans mobile, television, IT, automotive, and wearable segments, material suppliers must respond with product lines that address distinct performance and scalability requirements. This dynamic encourages closer collaboration between material developers and panel makers, as joint optimization of deposition parameters and material properties becomes essential to achieving target yield, efficiency, and durability. Suppliers capable of supporting multiple application domains while maintaining consistent quality standards gain strategic relevance in an environment where flexibility and reliability are equally valued.
Polarizer for OLED Market
Competitive Landscape and Strategic Positioning
Leading Players and Differentiated Capabilities
Universal Display Corporation occupies a prominent position as a leading provider of phosphorescent OLED emitter materials and technologies optimized for vacuum thermal evaporation processes. Its emphasis on high-efficiency emitter chemistry and process-compatible materials supports applications where luminous efficiency and device lifetime are paramount. The company's continued investment in deposition alternatives, including the relocation of research and development for Universal Vapor Jet Printing technology to a subsidiary in Singapore, signals a strategic interest in high-deposition-rate dry printing methods that could complement or extend traditional vacuum evaporation capabilities. Such moves underscore a broader ambition to shape next-generation deposition workflows while strengthening regional operational flexibility.
Merck KGaA supplies host materials, emitters, and transport layer materials specifically formulated for vacuum vapor deposition in OLED stack architectures. Its broad material portfolio and established formulation expertise enable support across multiple device architectures and performance targets. LG Chem produces OLED stack materials including hole and electron transport layers and emitters tailored for vapor deposition manufacturing of AMOLED panels, contributing to a vertically integrated value chain that aligns material development with panel-level requirements. Samsung SDI develops emitting layer materials and functional layers for vacuum deposition, reinforcing its role as a key material supplier within a broader display ecosystem.
In Japan, Idemitsu Kosan stands out as a major supplier of blue emitters, host materials, and charge transport materials designed for thermal vacuum vapor deposition, addressing a particularly demanding color and stability segment. Sumitomo Chemical offers small-molecule materials for vapor-deposition type OLEDs with additional focus on related functional layers, while Hodogaya Chemical provides specialized OLED intermediates and materials compatible with vacuum processes. JNC Corporation manufactures functional materials and intermediates for OLED vapor deposition applications, and Tokuyama Corporation produces high-purity materials and precursors used in OLED vapor deposition layers. Together, these Japanese firms contribute deep chemical synthesis expertise and a strong emphasis on purity and consistency, which are critical for fine-pitch and high-efficiency deposition environments.
In the United States, Materion Corporation supplies evaporation materials and high-purity compounds for thin-film vapor deposition in OLED production, supporting the broader equipment and materials ecosystem with specialized precursor and compound offerings. In China, a growing set of producers—including Jilin OLED Material Tech, Changchun Hyperions Technology, and Shaanxi Lighte Optoelectronics Material—manufacture OLED evaporation materials and intermediates for vapor deposition applications. These regional suppliers are expanding their capabilities in response to domestic panel demand and the broader push toward supply chain localization, creating additional options for buyers seeking qualified alternatives and reinforcing the trend toward a more geographically diversified material base.
Strategic Themes Across the Competitive Field
Several strategic themes emerge across the competitive landscape. First, technical differentiation remains central. Companies that advance emitter efficiency, host material stability, and transport layer performance for vacuum evaporation gain leverage in high-value applications where device performance directly influences product positioning. Second, process compatibility is increasingly important. Materials must integrate smoothly with existing deposition equipment and emerging process variations, including angle-controlled evaporation and high-throughput dry printing methods. Suppliers that collaborate closely with equipment vendors and panel makers to optimize deposition parameters can achieve faster qualification cycles and stronger customer relationships.
Third, supply resilience and purity assurance are becoming strategic differentiators. As fabrication scales and material specifications tighten, the ability to deliver consistent purity, reproducible batches, and reliable volumes reduces risk for downstream manufacturers. Fourth, sustainability alignment is moving from a compliance concern to a competitive consideration. Materials and processes that support lower energy intensity, improved utilization, and responsible sourcing may influence procurement decisions among organizations with explicit environmental targets.
Market Evolution and Emerging Dynamics
The competitive field is evolving through a combination of concentration, niche differentiation, and gradual entry by regional suppliers. High concentration among top players reflects strong intellectual property positions and mature material portfolios, but it also creates incentives for new entrants to compete in specific segments such as blue emitters, intermediates, or region-specific supply solutions. Over time, this can lead to a more layered market structure in which established firms continue to lead in high-performance categories while regional and specialized suppliers expand in adjacent material classes.
Integration and collaboration are likely to increase as panel makers, equipment providers, and material suppliers seek to co-optimize deposition workflows and reduce qualification risk. At the same time, the push toward dry printing alternatives and improved deposition efficiency may reshape material requirements over the medium term, encouraging suppliers to adapt formulations and processes to maintain relevance across evolving manufacturing paradigms. The overall trajectory points toward a market that remains performance-driven but is increasingly sensitive to supply continuity, geographic diversification, and sustainability considerations.
PW Consulting Chemical & Energy Research Center
Forward-Looking Trends and Commercial Implications
Trend 1: Co-Optimization of Materials and Deposition Equipment
The convergence of material chemistry and deposition engineering is expected to intensify over the next three to five years. Equipment innovations such as advanced angle-controlled evaporation and novel deposition methods are designed to enhance pixel brightness, resolution, energy efficiency, and lifespan. For material suppliers, this implies a growing need to tailor formulations that perform optimally under these refined process conditions. Commercial opportunities will accrue to firms that can demonstrate compatibility, support pilot-scale qualification, and provide data that links material attributes to equipment-level outcomes. Panel makers and equipment vendors, in turn, benefit from shorter development cycles and higher yield stability when materials and tools are optimized together.
Trend 2: Expansion of Regional Supply Bases and Supplier Diversification
Regional suppliers are gaining share, particularly in markets with expanding fabrication capacity and localized procurement preferences. As one Chinese evaporation material supplier is projected to join the global top ten in 2025, the competitive map is becoming more multipolar. This trend offers buyers greater sourcing flexibility and may improve supply continuity, but it also requires rigorous qualification and quality assurance practices. For material producers, regional expansion can reduce logistics burdens and align product offerings with local fab requirements, creating opportunities for differentiated service models, technical support, and customized material grades that match regional process configurations.
Trend 3: Sustainability-Linked Material and Process Innovation
Environmental and supply stability pressures are unlikely to abate. Energy-intensive deposition processes, raw material constraints, and rising sustainability expectations will continue to shape material development priorities. Over the forecast horizon, expect greater attention to material utilization efficiency, lower-energy deposition compatibility, recycled or eco-friendly material pathways, and supply chain transparency. These developments can translate into commercial advantages for suppliers positioned to offer performance without compromising environmental or sourcing goals. At the same time, uncertainty remains regarding the pace of regulatory evolution, the cost implications of sustainable alternatives, and the willingness of buyers to absorb premium pricing for greener material solutions. Strategic planning should account for both the upside of differentiation and the risk of shifting standards.
Strategic Considerations for Decision Makers
For Display Manufacturers and Panel Fabricators
Prioritize material qualification programs that emphasize process compatibility, batch consistency, and performance under target deposition conditions. As equipment and material innovations converge, early collaboration with suppliers and equipment partners can reduce qualification risk and accelerate adoption of higher-efficiency deposition methods. Evaluate supplier diversification strategies to balance performance, resilience, and regional sourcing needs, particularly where large-scale capacity expansion increases raw material consumption and supply continuity requirements.
For Investors and Strategic Planners
Focus on capabilities that link material performance to evolving deposition workflows and application diversification. Companies with strong emitter chemistry, transport layer expertise, and adaptive process compatibility are well positioned as panel makers pursue higher resolution, improved efficiency, and broader application portfolios. Monitor the pace of regional supplier maturation and the emergence of qualified alternatives, as shifts in the top-tier ranking may influence supply dynamics and margin structures. Consider sustainability-linked innovation as a potential differentiator, while remaining attentive to cost, scale, and regulatory uncertainty.
Organic Photovoltaics (OPV) Market
For Procurement and Supply Chain Leaders
Strengthen qualification frameworks that capture purity, reproducibility, delivery reliability, and environmental attributes in a unified evaluation. As raw material demand grows with fab expansion, secure long-term supply arrangements where feasible and maintain visibility into upstream precursor availability, particularly for high-volume inputs such as electronic-grade silane. Where sustainability commitments are material to corporate strategy, incorporate eco-friendly and recycled material options into sourcing reviews without sacrificing performance or yield.
Market evolution in OLED vapor deposition materials will be shaped by the interplay of technical performance, equipment co-optimization, regional supply expansion, and sustainability pressures. Decision makers who align procurement, investment, and development strategies with these forces will be better prepared to capture value as the market moves toward higher efficiency, broader application coverage, and more diversified sourcing. For a detailed view of segmentation data, regional revenue splits, competitive benchmarking, and scenario-based forecasts, the full PW Consulting report provides the granular intelligence needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: OLED Vapor Deposition Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com