

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Bulk Continuous Filament Carpet Fiber Market: Why 4.51% CAGR. Reshapes Global Dynamics Beyond 2032

Navigating Growth and Transformation in the Bulk Continuous Filament Carpet Fiber Market
Market Overview: Scale, Trajectory, and Core Pressures
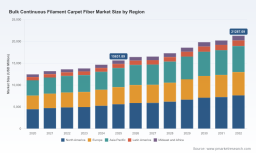
The Bulk Continuous Filament (BCF) carpet fiber market has entered a phase of steady, measured expansion, driven by the widespread adoption of synthetic fibers in both residential and commercial flooring. Valued at approximately $15.63 billion in 2025, the market is projected to reach $21.29 billion by 2032, growing at a compound annual growth rate of 4.51% over the forecast period. This trajectory reflects a broader structural shift away from spun yarns and natural fibers toward continuous filament solutions that deliver superior durability, consistent texture, and enhanced stain resistance. The market’s expansion is underpinned by consistent demand across building construction, renovation cycles, and interior fit-out programs, though the pace of growth varies significantly by region and application segment.
Polyester Fiber Market
Despite the positive medium-term outlook, the industry is navigating several structural pressures that are reshaping competitive dynamics and investment priorities. First, raw material volatility continues to exert margin pressure across key polymer feedstocks. Nylon 6 BCF production relies heavily on caprolactam pricing, while nylon 6,6 depends on adipic acid and hexamethylenediamine supply chains. In 2025, global nylon fiber and feedstock markets experienced profitability headwinds driven by caprolactam oversupply and soft demand for PA6 and PA66 in several key regions. These conditions have forced producers to balance volume commitments against pricing flexibility, particularly in cost-sensitive commercial segments.
Second, the regulatory and sustainability agenda is accelerating material substitution and formulation changes. The industry is witnessing a pronounced shift toward recycled content in BCF yarns, including 100% recycled nylon 6 and post-consumer recycled PET. This transition is being reinforced by circular economy mandates in automotive interiors and commercial flooring, where brand owners and building specifications increasingly demand traceable recycled content and lower lifecycle emissions. While this creates differentiation opportunities, it also raises technical and supply chain complexity, particularly around consistency, dyeability, and performance validation across recycled feedstocks.
Third, the market is being reshaped by shifting demand patterns and competitive intensity across regions. Asia Pacific continues to represent a substantial share of global volume, supported by domestic carpet manufacturing, infrastructure-linked interior demand, and expanding production capacity. North America and Europe remain important markets, but growth is increasingly tied to premiumization, performance specifications, and sustainability requirements rather than raw volume expansion. In this environment, manufacturers are being forced to choose between cost leadership, performance differentiation, and sustainability positioning, with few players able to dominate all three simultaneously.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
Technology innovation is acting as a primary catalyst for market evolution, particularly in fiber engineering, spinning efficiency, and solution-dyeing capabilities. Advanced BCF architectures are enabling manufacturers to improve bulk, resilience, and stain resistance without sacrificing processing speed or yarn uniformity. Solution-dyed nylon and polyester BCF fibers, in particular, are gaining traction because they offer superior colorfastness, reduced water consumption, and better alignment with commercial warranty requirements. These technical advantages are especially valuable in high-traffic commercial environments and automotive interiors, where durability and appearance retention directly influence specification decisions.
The regulatory environment is reinforcing the importance of sustainable fiber portfolios. As circular economy expectations become embedded in procurement standards, producers are investing in recycled feedstocks and mono-material architectures that simplify end-of-life processing. This shift is not merely compliance-driven; it is increasingly tied to customer preference and brand positioning. Automotive and commercial flooring buyers are integrating recycled content targets into their supply chain criteria, which is pushing BCF manufacturers to expand recycled nylon and recycled PET capabilities while maintaining performance parity with virgin materials.
On the demand side, consumer and enterprise behavior is shifting toward flooring solutions that combine aesthetics, longevity, and environmental credentials. Residential demand continues to be supported by renovation activity and a preference for low-maintenance, durable carpet fibers in both new builds and retrofit projects. Commercial demand is being shaped by workplace reconfiguration, hygiene expectations, and the need for materials that can withstand frequent cleaning cycles. Automotive and transport applications add another layer of demand stability, with interior weight reduction, noise control, and recycled content targets influencing material selection.
PW Consulting Chemical & Energy Research Center
Supply chain and cost structures remain a critical driver of competitive outcomes. Polyest er BCF yarns have gained significant global market share in carpet yarns, largely due to cost advantages over polypropylene and nylon in many applications. This cost dynamic has encouraged capacity expansion and product diversification among polyester-focused producers, while nylon players have concentrated on performance niches and recycled differentiation. At the same time, feedstock interdependence means that polymer pricing cycles can quickly translate into margin variability. Producers with integrated feedstock access, flexible production lines, and diversified material portfolios are better positioned to absorb price swings and reallocate output according to demand signals.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive environment in the BCF carpet fiber market is characterized by a mix of established multinational producers, regional specialists, and expanding Asian capacity. Market concentration remains meaningful, with the top three players holding roughly 38% of the market and the top five approaching 52%. This level of concentration indicates that scale, technology access, and customer relationships still matter, but it also leaves meaningful room for regional players and niche specialists to compete on customization, speed, and local service.
Leading companies are pursuing distinct strategic positions rather than competing on a single dimension. Aquafil has built a strong identity around recycled nylon 6 BCF, using ECONYL as a platform for residential, commercial, and automotive applications with an explicit circular economy focus. Universal Fibers has emphasized solution-dyed nylon BCF with recycled content, targeting commercial and residential buyers who value color consistency and sustainability in tandem. Ascend Performance Materials has concentrated on premium nylon 6,6 BCF for commercial applications, differentiating on durability, color retention, and performance under demanding use conditions. B.I.G. Yarns has diversified across nylon PA6, polypropylene, and virgin polyester BCF, recently completing industrial production runs of virgin PET BCF for automotive carpet applications to enable mono-polymer solutions alongside its existing lines.
Concrete Fiber Market
Asian producers are playing an increasingly important role in shaping supply dynamics. Toray Industries continues to offer nylon and polyester BCF yarns with advanced fiber technology for carpet and textile flooring markets. Hyosung Advanced Materials manufactures nylon BCF yarns, including recycled options for automotive floor carpets, aligning with regional demand and sustainability incentives. In India, AYM Syntex and Beekaylon Synthetics are expanding specialty BCF offerings across polyester, nylon 6, and polypropylene, with Beekaylon leveraging advanced Neumag technology for tri-color and standard yarn production. Shanthi Industries adds further regional depth with polypropylene, polyester, and nylon BCF yarns focused on carpet manufacturing applications. In China, Zhejiang Sitong New Material Technology has moved to strengthen its position as one of Asia’s largest BCF yarn producers by commissioning additional Oerlikon Neumag BCF S+ positions for polyester yarn, supporting a more balanced production mix across polyester, polyamide, and polypropylene. Zhejiang Hengyuan Chemical Fiber Group has similarly emphasized strength, resilience, and durability in heavy-duty flooring-grade BCF yarns.
Polymer suppliers and mid-stream players also influence competitive outcomes. Nylene supplies multiple-dye-level nylon 6 polymers specifically for BCF and solution-dyed carpet fibers, enabling downstream customization. RadiciGroup contributes nylon BCF yarns within its broader synthetic fibers portfolio, while Gülsan Holding maintains significant polypropylene and synthetic capacity for the carpet industry. Collectively, these players illustrate how the market is structured not only by yarn producers but also by feedstock specialization and processing technology access.
The strategic trend across the landscape is one of selective differentiation rather than undifferentiated capacity expansion. Companies are investing where they can command a clearer value proposition: recycled content credentials, solution-dyeing performance, mono-material design for automotive, or cost-efficient polyester scale. At the same time, capacity additions in Asia are increasing competitive pressure on pricing and availability, particularly in polyester. This suggests a market that is simultaneously consolidating around leading technology and sustainability capabilities while fragmenting in cost-driven segments where regional producers can win on speed, service, and local demand knowledge.
Forward Outlook: Trends Shaping the Next Three to Five Years
Over the next three to five years, one of the most consequential trends will be the continued escalation of recycled and mono-material fiber architectures. As automotive and commercial flooring specifications tighten around circularity, BCF producers that can deliver consistent recycled nylon and recycled PET yarns with verified performance will gain preferential access to high-value contracts. This trend favors players with established recycling feedstocks, polymer engineering expertise, and the ability to maintain dye and performance consistency across batches.
A second trend is the widening performance gap between standard and premium BCF solutions. Demand in commercial and automotive applications is likely to reward fibers that combine solution-dyeing, improved bulk, and stronger color retention with lower maintenance requirements. In residential markets, premiumization may be more uneven, but there is clear opportunity in fibers that offer better durability and easier care without a disproportionate price premium. This creates a two-tier market dynamic in which volume growth is available across segments, but margin expansion will depend on technical differentiation and specification wins.
A third trend is regional realignment in production and sourcing. Capacity expansion in Asia, especially in polyester BCF, is likely to keep cost pressure elevated while also improving supply resilience for downstream carpet manufacturers. North American and European producers will increasingly compete on sustainability credentials, specialty formulations, and proximity to end-market specification channels. For buyers and investors, this means that sourcing strategies and capacity planning will need to account for both cost efficiency and the risk of regulatory or customer-driven material shifts.
These trends carry meaningful opportunity, but also uncertainty. Feedstock pricing volatility, especially in nylon-related polymers, can quickly alter profitability assumptions. Recycled content mandates may accelerate in some markets faster than supply chains can scale consistent quality. In addition, macroeconomic cycles affecting construction, renovation, and auto production can shift demand timing and intensity. Companies that treat sustainability, performance, and cost as an integrated strategy rather than separate initiatives will be best positioned to navigate these uncertainties.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product portfolios with the durability, colorfastness, and recycled-content requirements that are becoming baseline expectations in commercial and automotive specifications. Investing in solution-dyeing capability, flexible BCF lines, and reliable recycled feedstock access can create defensible differentiation. At the same time, cost discipline remains essential, particularly in polyester-heavy segments where price competition is intensifying. Manufacturers should also consider mono-material approaches where they can simplify downstream processing and improve circularity claims without compromising performance.
For investors, the market offers attractive but uneven exposure. The strongest near-term value creation is likely to come from companies with clear sustainability differentiation, strong commercial specification relationships, and the ability to manage feedstock volatility. Capacity expansion alone is unlikely to guarantee outsized returns unless it is tied to a specific application advantage or regional demand opportunity. Due diligence should focus on feedstock positioning, recycled content readiness, technology access, and the durability of customer relationships in high-specification segments.
For procurement and sourcing leaders, diversification and specification clarity are critical. Relying on a single material type or supplier increases exposure to feedstock cycles and regulatory shifts. Building a sourcing strategy that balances cost, performance, and recycled content across nylon, polyester, and polypropylene can improve resilience while meeting evolving customer requirements. It is equally important to validate performance claims early in the specification process, especially when introducing recycled yarns into demanding commercial or automotive applications. For organizations that need detailed segmentation data, regional supply mappings, and customized scenario planning, the full PW Consulting research report provides deeper granularity and tailored recommendations for specific portfolio and market decisions.
For detailed analysis of this topic, please visit the official page: Bulk Continuous Filament Carpet Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com