

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
p.p'-Dibromobiphenyl Market Outlook: Why 4.12% CAGR Masks SKU-Level Value Shifts Through 2032

Strategic Trends and Commercial Opportunities in the p.p'-Dibromobiphenyl Market
Market Overview and Core Challenges
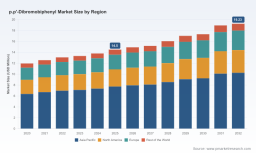
The p.p'-Dibromobiphenyl market has demonstrated steady, incremental growth over the past half-decade, transitioning from a niche specialty chemical segment to a recognized component in advanced materials supply chains. Valued at approximately USD 11.95 million in 2020, the overall market expanded to an estimated USD 14.5 million in 2025, reflecting a compound annual growth rate of roughly 4.12% projected through 2032. This trajectory underscores a maturing but still evolving ecosystem where demand is increasingly tied to high-performance electronic materials and specialty polymer applications. The market structure remains moderately concentrated, with the top three players accounting for approximately 64% of total revenue and the top five representing over 81%. Such concentration suggests established relationships between key manufacturers and end-users, yet also leaves room for agile entrants and regional specialists to capture value through differentiation in purity, logistics, or service integration.
Despite the positive growth trajectory, the segment faces several structural challenges that are reshaping how participants navigate pricing, compliance, and capacity allocation. First, raw material volatility has become a persistent pressure point. Bromine pricing has experienced sharp fluctuations in recent months, with Chinese supply experiencing a notable 46% surge between mid-2025 and early 2026, while Northeast Asian and European markets have seen more moderate but still upward movements. These swings cascade into synthesis costs, affecting margin resilience for producers who lack hedging strategies or diversified sourcing arrangements. Second, regulatory scrutiny around polybrominated biphenyl compounds continues to tighten across major jurisdictions. Substances falling within this chemical family are subject to monitoring frameworks that emphasize environmental persistence and aquatic toxicity, prompting stricter documentation requirements, supply chain transparency, and end-of-life considerations for downstream users. While p.p'-Dibromobiphenyl itself is not broadly restricted, its regulatory adjacency introduces compliance overhead and can influence procurement preferences toward fully traceable, audited supply lines. Third, the market is experiencing a divergence in purity expectations across application tiers. Certain end-use segments prioritize cost-efficient intermediate grades, while advanced electronic and pharmaceutical-adjacent applications demand consistent high-purity specifications with rigorous batch-to-batch validation. Balancing these competing requirements without compromising operational efficiency or qualification timelines remains a central challenge for producers and buyers alike.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Advancements
Progress in electronic materials and specialty polymers continues to anchor demand for brominated biphenyl derivatives. The compound serves as a building block in the synthesis of organic semiconductors and small-molecule materials, where precise substitution patterns and controlled purity levels directly influence device performance. Concurrently, liquid crystal polymer formulations increasingly rely on specialized intermediates to achieve targeted thermal stability, mechanical strength, and processing characteristics. These applications reward suppliers that can provide consistent specifications, robust technical data packages, and responsive support during product qualification cycles. The trend is not merely about volume; it is about reliability and technical compatibility. Manufacturers able to standardize production protocols, reduce impurity profiles, and streamline documentation are gaining an edge in applications where development timelines are compressed and failure costs are high.
Worldwide Bromobenzene Market
Regulatory and Compliance Evolution
The regulatory landscape is reinforcing a preference for transparent, documented supply chains. Monitoring frameworks for brominated compounds place additional emphasis on environmental fate, aquatic toxicity, and responsible handling across the value chain. In practice, this translates into more rigorous batch testing, clearer safety data alignment, and enhanced traceability from feedstock to finished intermediate. Companies that proactively align with these expectations are better positioned to serve multinational end-users who must satisfy internal audit requirements and downstream compliance obligations. The regulatory environment also encourages regional diversification of supply, as procurement teams seek to reduce exposure to concentrations that could be disrupted by policy shifts or inspection regimes. Over time, compliance capability is becoming a competitive differentiator rather than a baseline cost of doing business.
Demand-Side Shifts in Electronics and Specialty Chemicals
Demand patterns are being shaped by the expansion of high-value applications that require controlled molecular architectures. Organic light-emitting diode material intermediates represent one of the larger demand pools, driven by continued development in display technologies and related optoelectronic components. At the same time, liquid crystal polymer uses are supported by sectors that value dimensional stability, chemical resistance, and performance under demanding operating conditions. Beyond these core uses, laboratory and analytical applications sustain a steady baseline of demand, particularly among organizations that require certified reference materials or high-purity samples for method development and quality assurance. Across these segments, buyers are increasingly balancing cost considerations against the need for consistency, lead-time reliability, and technical support. This shift favors suppliers that can present clear value propositions beyond unit price alone, including packaging flexibility, inventory availability in key regions, and documented purity verification.
Supply Chain and Cost Structure Dynamics
Cost structures are being influenced by feedstock dynamics and regional capacity configurations. Bromine pricing has been notably volatile, with significant increases observed in China and upward pressure recorded across Northeast Asia and Europe. These movements affect not only direct input costs but also the economics of transportation, warehousing, and inventory planning for intermediaries and end-users. At the same time, the broader biphenyl feedstock environment remains sensitive to benzene-related volatility, adding another layer of uncertainty to upstream economics. In response, many participants are reevaluating sourcing strategies, exploring longer-term supply agreements, and considering regional production footprints that reduce exposure to single-market shocks. Capacity expansion in certain locales has also introduced a more tiered supply environment, where scale players compete on volume and cost while specialty suppliers compete on purity, certification, and application-focused service. This bifurcation is gradually redefining negotiation dynamics and encouraging more segmented procurement strategies.
Competitive Landscape and Leading Strategies
The competitive field blends established specialty chemical suppliers with regional manufacturers that have expanded their footprint through targeted product positioning. Tokyo Chemical Industry Co., Ltd. (TCI) exemplifies a reagent-focused model, offering p.p'-Dibromobiphenyl as a building block for organic semiconductors and small-molecule materials, with packaging options tailored to laboratory and pilot-scale needs and inventory positioned in Japanese warehouses. This orientation emphasizes availability, specification clarity, and support for research and early-stage development workflows. On the pharmaceutical-adjacent side, Simson Pharma Limited and Pharmaffiliates approach the material as a reference standard and analytical/reuse-grade intermediate, aligning their offerings with documentation rigor and traceability that appeal to regulated environments. Deep Pharm Chem further reinforces this angle through certified quality systems and assay specifications suited to analytical applications. In the manufacturing segment, several China-based producers, including Alfa Chem, Zhejiang Free Trade Zone Violet Trade Co., Ltd., Nantong Reform Petro-Chemical Co., Ltd., Henan Violet Technology Co., Ltd., Mascot Chem, and Ruifu Chem, demonstrate a spectrum of capabilities ranging from cost-efficient bulk supply to higher-purity pharmaceutical-grade output. Ruifu Chem’s export-oriented presence across multiple regions highlights how certain suppliers leverage scale and logistics to serve diverse downstream markets, while others differentiate through purity tiers and melting-point specifications that cater to particular application tolerances.
Leading players are pursuing differentiation along three primary axes: purity and specification control, application-specific packaging and service, and geographic availability. Suppliers that can demonstrate tight control over assay, impurity profiles, and batch consistency are gaining preference in segments where downstream processing is sensitive to variability. Packaging flexibility, from small-scale trial quantities to multi-ton batches, allows manufacturers to serve both early-stage qualification and larger production campaigns without forcing customers into suboptimal inventory commitments. Geographic positioning also matters; having stock or production capacity near key demand centers reduces lead times and improves responsiveness during qualification windows or supply disruptions. These strategic choices are especially relevant given the market’s moderate concentration, where incumbents hold meaningful share but do not fully lock out competitors that offer compelling technical or commercial combinations.
4,4-Biphenol Market
The landscape is evolving through a blend of consolidation pressure and niche expansion. On one hand, larger entities benefit from established supplier qualifications, broader distribution networks, and the ability to absorb raw material fluctuations more effectively. On the other hand, regional manufacturers and specialized suppliers continue to enter or expand by focusing on purity grades, certification depth, or application-aligned technical support. New entrants that can deliver consistent quality, transparent documentation, and reliable logistics are finding pathways into procurement considerations, particularly where incumbent supply is constrained or where end-users seek to diversify risk. The result is a market that is neither fully commoditized nor tightly controlled, but rather segmented by value drivers that reward capabilities beyond simple volume pricing.
Forecasting the Next Three to Five Years
Several interconnected trends are likely to shape the market through the end of the decade. First, purity segmentation will become more pronounced as downstream applications continue to differentiate. Higher-purity offerings will remain critical for electronic materials and regulated environments, while intermediate grades will continue to serve cost-sensitive polymer and specialty synthesis uses. Suppliers that can efficiently manage multiple purity tiers within streamlined operations will be better positioned to capture demand across segments without diluting margin quality. Second, supply chain resilience will move from a procurement preference to a strategic requirement. Given the observed volatility in bromine pricing and the sensitivity of feedstock economics, buyers and producers alike will increasingly favor arrangements that reduce exposure to abrupt cost shocks and regional disruptions. This may include longer-term agreements, diversified sourcing, inventory buffering in strategic locations, and closer collaboration between suppliers and end-users on demand forecasting. Third, regulatory and documentation expectations will continue to intensify, reinforcing the value of traceability, certified quality systems, and clear safety and handling information. Companies that treat compliance as part of their value proposition, rather than a back-office function, will find it easier to qualify in multinational supply chains and to maintain preferred-supplier status over time.
These trends create clear commercial opportunities for participants willing to invest in differentiation and operational discipline. Producers that align capacity with application-specific purity needs, strengthen documentation, and secure reliable feedstock access can command more stable negotiations and improve customer retention. For buyers, the opportunity lies in building multi-source strategies that balance cost, quality, and continuity, while avoiding overreliance on a single region or supplier tier. At the same time, uncertainty persists. Raw material pricing could continue to fluctuate, regulatory definitions and monitoring expectations may evolve, and demand from electronic materials applications remains linked to broader technology adoption cycles. Navigating these variables will require continuous monitoring of pricing signals, feedstock conditions, and policy developments, as well as the flexibility to adjust sourcing and production strategies as the landscape changes.
Actionable Recommendations for Decision-Makers
For manufacturers, the priority is to align product portfolios with the purity and documentation expectations of the most value-intensive applications while maintaining efficient pathways for intermediate-grade demand. Investing in batch consistency, certification readiness, and technical support capabilities can improve positioning with end-users who prioritize reliability in qualification and scale-up. Exploring feedstock hedging or diversified sourcing arrangements may also help cushion the impact of bromine price volatility and improve margin predictability.
PW Consulting Chemical & Energy Research Center
For investors, the market’s moderate concentration and segmentation by purity, application, and geography suggest selective opportunities rather than broad-based exposure. Due diligence should focus on suppliers with demonstrated quality systems, credible export capabilities, and supply chain practices that reduce regulatory and operational risk. Tracking feedstock economics and regional pricing trends will be essential for assessing cost resilience and long-term competitiveness.
For procurement teams, a balanced sourcing strategy that combines primary suppliers with qualified alternates can mitigate disruption risk while preserving cost discipline. Prioritizing partners that offer transparent documentation, consistent specifications, and flexible packaging can shorten qualification cycles and improve supply continuity. As regulatory expectations and raw material dynamics continue to evolve, maintaining access to current market intelligence will be valuable for timing contracts, evaluating regional sourcing options, and anticipating shifts in supplier capability.
For organizations seeking a more granular view of regional demand patterns, purity-grade economics, application-level volume trajectories, and competitive positioning, a comprehensive market study can provide the detailed segmentation and scenario context needed for planning. Deeper data on pricing structures, capacity developments, and compliance-related purchasing behavior can support more precise sourcing decisions, investment prioritization, and product strategy refinement.
For detailed analysis of this topic, please visit the official page: p.p'-Dibromobiphenyl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com