

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Recycled Containerboard Market: Why a 4.69% CAGR to $202B Redefines Packaging

Recycled Containerboard Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
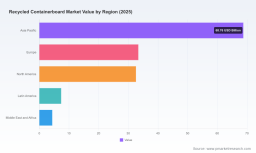
The recycled containerboard market has transitioned from a cyclical commodity segment into a structurally expanding supply chain component that mediates between waste recovery and industrial packaging demand. The industry has demonstrated steady growth across the historical period from 2020 to 2025, with the market value reaching 146.5 billion USD in the base year of 2025. Forward projections indicate sustained momentum, with the market expected to expand to approximately 153.96 billion USD in 2026 and continue climbing through the forecast horizon to 2032, when it is anticipated to approach 201.88 billion USD. This trajectory reflects a compound annual growth rate of 4.69 percent over the forecast period. The expansion is not merely a function of volume; it represents a reconfiguration of how packaging value chains source, grade, and deploy recovered fiber in response to regulatory pressure, buyer specifications, and cost dynamics.
Despite this constructive backdrop, the market sits at a series of inflection points that will separate resilient operators from those caught flat-footed. Three challenges merit immediate attention. First, the cost structure of recovered fiber is becoming increasingly volatile and regionally segmented. While long-term demand for recycled grades remains robust, pricing for old corrugated container material has exhibited sharp directional swings, with early 2026 showing modest rebounds after late-2025 softness. These fluctuations are not random; they reflect tightening collection economics, sorting capacity constraints, and shifting trade flows that complicate input planning for mills relying on diversified waste streams.
Second, the regulatory environment is accelerating but uneven. Extended producer responsibility frameworks for packaging and paper products have moved from legislative drafts to operational reality in multiple jurisdictions, reshaping who bears end-of-life costs and how recycled content is incentivized. In some markets, requirements for post-consumer recycled content are climbing toward thresholds that materially alter formulation strategies, procurement planning, and compliance verification. Operators must now reconcile sustainability mandates with the technical reality that recycled fiber performance varies by source, contamination levels, and processing configuration.
Third, the underlying production environment is tightening even as demand grows. Containerboard output in key regions has shown contraction while operating rates have remained elevated, signaling that capacity additions are not keeping pace with structural demand shifts and that existing assets are running close to their practical limits. This combination of high utilization and modest output changes implies limited slack in the system, which amplifies the impact of feedstock disruptions, maintenance cycles, and grade transitions. For decision-makers, the implication is clear: recycled containerboard is no longer a passive input category but a strategically managed one, where access to quality fiber, consistent specifications, and regulatory alignment directly influence commercial positioning.
Key Demand Drivers
Technical Innovation and Fiber Performance Gains
The most consequential driver reshaping the recycled containerboard market is the convergence of fiber performance engineering and application-specific grading. Recycled containerboard was historically treated as a functional commodity where strength and consistency were acceptable but not differentiated. That paradigm is eroding. Producers are increasingly designing recycled linerboard and medium grades with targeted strength profiles, surface characteristics, and runnability attributes that meet demanding downstream requirements, particularly in e-commerce, food and beverage, and consumer goods packaging. The shift is visible in the introduction of high-performance lightweight grades, low-basis-weight options, and engineered testliner and fluting specifications that preserve protective functionality while reducing material mass.
These innovations matter because they change the value equation for buyers. A lighter yet structurally reliable recycled grade can lower total packaging cost, improve pallet efficiency, and align with brand sustainability narratives without sacrificing performance. For manufacturers, the ability to offer reproducible, application-tuned recycled grades creates a clearer differentiation path in a market that has long competed on price alone. The trend is reinforced by equipment and process upgrades that improve deinking, cleaning, and fiber selection, enabling higher brightness, better surface finish, and more consistent printing quality where required. In practice, this means recycled containerboard is increasingly participating in applications that previously leaned toward virgin fiber or blended solutions, expanding the addressable market beyond traditional bulk packaging.
Regulatory and Extended Producer Responsibility Dynamics
Policy and regulatory pressure is functioning as both a constraint and a catalyst. Extended producer responsibility laws for packaging and paper products are being implemented or proposed across multiple regions, requiring producers and brand owners to account for end-of-life management costs and, in many cases, to incorporate specified levels of recycled content. Where post-consumer recycled content thresholds are rising, the commercial logic shifts toward securing reliable streams of recovered fiber and building compliance documentation into procurement contracts. This is not a marginal adjustment; it restructures how packaging decisions are made, how sourcing is validated, and how sustainability claims are substantiated.
At the same time, regulatory momentum is not uniform. Some jurisdictions are setting explicit recycled content expectations for paper and paper packaging, while others are focusing on collection, sorting, and producer-funded recovery systems. The practical result is a patchwork environment in which strategic players must map regulatory exposure by market, anticipate compliance timelines, and prepare for higher scrutiny of recycled content claims. For mills and converters, this creates both a competitive moat and a risk: firms that can demonstrate traceable, certified recycled content and consistent grade performance will be better positioned to serve brand owners navigating EPR obligations, whereas operators dependent on less transparent fiber sourcing may face growing friction in premium segments.
Demand-Side Shifts in E-commerce, Retail, and Brand Packaging
Demand-side behavior is changing the shape of containerboard consumption. E-commerce and retail continue to drive sustained packaging intensity, but the nature of that demand is evolving. Shipment protection requirements, damage reduction targets, and brand-facing presentation considerations are pushing buyers toward grades that balance strength, printability, and surface quality. At the same time, consumer-facing brands are under increasing pressure to make packaging decisions that are defensible on sustainability, which elevates the importance of verified recycled content and lifecycle considerations. The result is a more discerning buyer base that evaluates recycled containerboard not simply by cost per ton, but by total application performance and compliance alignment.
This shift has commercial consequences. Purchasers are more willing to lock in dedicated recycled grade supply when specifications are stable and performance is demonstrable. They are also more sensitive to variability in fiber quality and more interested in collaborative development of grades that fit specific box designs, load conditions, and printing needs. For producers, this means that the opportunity is not only in volume but in specification loyalty: customers who depend on a particular recycled linerboard or medium grade for a recurring application are less likely to treat the purchase as a spot transaction. The market is therefore moving toward stronger co-development relationships, longer planning horizons, and tighter integration between fiber availability, grade design, and end-use requirements.
Waste Paper Recycling Market
Supply Chain and Cost Structure Realignment
Cost and supply chain dynamics are reshaping where value is captured and where margin pressure accumulates. Recovered fiber pricing, contamination management, and collection logistics are becoming more important determinants of competitiveness than in prior cycles. In early 2026, indicators suggested renewed movement in recovered fiber pricing after a period of downward pressure, reflecting localized supply tightening and renewed demand balance. This kind of volatility underscores the importance of sourcing diversification, regional fiber strategy, and inventory planning. Mills and converters that rely on narrow feedstock bases or single-channel collection systems are more exposed to price shocks and grade interruptions, while those with multi-source procurement and strong sorting partnerships can moderate input risk.
The cost structure is also being influenced by capacity utilization and asset configuration. With operating rates remaining high in key regions while output adjusted modestly, the system shows limited buffering capacity. That has two implications. First, it raises the strategic premium attached to reliable production continuity and grade consistency, particularly for customers operating lean logistics models. Second, it highlights the importance of modernization investments that improve yield, reduce reject rates, and enable smoother grade transitions. In this environment, supply chain resilience is not merely an operations concern; it is a commercial differentiator. Buyers increasingly favor suppliers that can demonstrate control over fiber availability, contamination handling, and output predictability, especially when those capabilities reduce downstream disruption.
Competitive Landscape and Leading Strategies
The competitive field in recycled containerboard is defined less by sheer scale than by differentiated positioning around fiber quality, grade specialization, and regional execution. Several large and mid-tier manufacturers are actively shaping the market through distinct strategic postures. International Paper, for example, is building a high-performance recycled liner and fluting portfolio, including lightweight grades designed for corrugated packaging, supported by mill assets in Europe and North Africa. Its emphasis on reproducible performance and lightweight engineering aligns with the broader market shift toward optimized strength-to-weight outcomes. ND Paper is pursuing a complementary angle by concentrating on strength consistency, print quality, and repeatability for demanding applications, positioning recycled containerboard as a technically credible option where specification precision matters.
European and North American players are also distinguishing themselves through clear sustainability and fiber narratives. Stora Enso has emphasized testliner produced from fully recycled fibers, targeting e-commerce, industrial, and consumer goods applications with an emphasis on strength, flatness, and low weights. Cascades has focused on a broad range of recycled linerboard weights and performance categories, including white chlorine-free and extra high-performance grades, reinforcing its position as a sustainable alternative to virgin fiber where surface quality and environmental profile both matter. DS Smith has carved out a niche around high-brightness, smooth, printing-quality recycled white liner grades suitable for food, beverage, agricultural, and fast-moving consumer goods packaging, reflecting the demand for recycled board that can satisfy both protective and presentation requirements.
Regional leaders are using technical and operational specificity to strengthen their positions. Kruger Inc. has long been associated with 100 percent recycled containerboard production in North America and has expanded its portfolio to include extra high-performance linerboard, white top grades, and specialty products such as tube stock and colored board. Pratt Industries operates as a large-scale privately held producer of fully recycled containerboard with multiple mills and a closed-loop model that converts recovered paper into packaging, an approach that directly addresses fiber availability, process control, and customer integration. New Indy Containerboard combines recycled fiber with virgin grades in a high-quality brown paper portfolio, offering flexibility in formulation that can be valuable for applications requiring specific performance or cost trade-offs. Mondi has reinforced its recycled containerboard capabilities through new wide paper machine capacity for testliner and fluting from recovered fiber, expanding its ability to serve quality-sensitive segments with scalable production.
Recent developments illustrate how this landscape is evolving. A major producer brought a new recycled containerboard paper machine online in Italy with substantial annual capacity for testliner and fluting from recovered fiber, signaling a clear commitment to expanding recycled grade output in response to demand and regulatory tailwinds. At the same time, another leading manufacturer invested in capacity and quality control improvements for uncoated recycled boxboard, emphasizing surface finish and printing performance. These moves are not isolated; they reflect a broader pattern in which recycled containerboard capacity and grade engineering are being upgraded to meet higher specification thresholds and more demanding buyer expectations.
The market structure is therefore moving along two tracks simultaneously. Consolidation and scale advantages remain relevant, particularly where fiber procurement, logistics, and multi-mill networks create cost and supply chain leverage. At the same time, differentiation is intensifying through grade specialization, performance reliability, and sustainability credentials. New entrants and expanding incumbents are most likely to succeed where they can combine reliable recovered fiber access with demonstrable product consistency and compliance-ready documentation. In contrast, undifferentiated commodity positioning is increasingly vulnerable to price competition and specification shifts. The strategic implication is that competitive advantage in recycled containerboard is being rebuilt around technical credibility, sourcing resilience, and the ability to align product attributes with application needs rather than around price leadership alone.
Outlook for the Next Three to Five Years
Looking ahead, three trends are likely to define the recycled containerboard market through the late 2020s and into the early 2030s. The first is the continued migration of recycled containerboard into higher-value applications. As lightweighting, strength consistency, and surface quality improve, recycled grades will capture a larger share of e-commerce, food and beverage, and consumer goods packaging where buyers are balancing protection, presentation, and sustainability. This shift expands the commercial opportunity beyond bulk carton and industrial use and creates more attractive margin potential for producers that can deliver application-specific performance with verifiable recycled content.
The second trend is the deepening influence of regulation on sourcing and product design. As extended producer responsibility frameworks and recycled content expectations take hold in more jurisdictions, procurement will increasingly favor suppliers that can provide traceable fiber streams, documented recycled content, and stable specification performance. This will likely accelerate investment in quality control, sorting partnerships, and compliance-oriented product lines. It will also heighten the importance of regional strategy, since regulatory requirements and fiber availability will vary significantly by market. Companies that treat compliance as a structural design constraint rather than a reporting exercise will be better positioned to secure long-term customer relationships.
The third trend is the growing premium attached to supply resilience and operational reliability. With utilization rates high and input volatility present, customers will value partners that can reduce disruption risk, maintain grade consistency, and respond quickly to specification changes. This favors operators with diversified fiber sourcing, strong mill performance, and flexible production configurations. At the same time, the environment carries risk. Feedstock availability can tighten unexpectedly, regulatory timelines can shift, and demand patterns can be altered by broader economic conditions or changes in trade flows. There is also the risk that recycled content requirements and performance standards could outpace some producers’ ability to deliver consistent quality at scale, creating separation between capable and lagging operators. The overarching opportunity is to treat recycled containerboard as a strategic materials category in which fiber access, grade engineering, and compliance alignment are jointly managed rather than as a generic input market.
Recommendations for Decision-Makers
For manufacturers, the priority is to align product strategy with the direction of buyer demand and regulatory pressure. That means investing in grade differentiation that delivers measurable performance in target applications, improving consistency and surface quality where printability and presentation matter, and building fiber sourcing resilience through diversified procurement and stronger sorting relationships. Capacity and process decisions should be evaluated not only on throughput but on the ability to run stable, specification-compliant recycled grades that customers can rely on in recurring applications.
Recovered Carbon Black Rcb Market
For investors, the focus should be on distinguishing operators with genuine competitive moats from those exposed to commodity volatility and input disruption. The most durable opportunities are likely to be found in companies with reliable recovered fiber access, credible quality control, application-oriented product portfolios, and the ability to meet rising recycled content expectations. Capex plans, regional fiber strategy, and compliance readiness should be assessed as indicators of future positioning rather than as isolated operational items.
PW Consulting Chemical & Energy Research Center
For procurement and purchasing teams, the practical move is to shift from transactional buying toward specification-based sourcing with clear performance and compliance criteria. Where possible, establish longer planning horizons with suppliers that can demonstrate consistent recycled content, reproducible grade attributes, and reliable delivery. In a market where utilization is high and input dynamics can shift quickly, supply predictability and quality assurance are increasingly valuable. For organizations seeking a more detailed view of regional segmentation, grade-level dynamics, and scenario-based implications across the forecast period, the full market intelligence report provides the deeper segmentation data and customized analysis needed to translate these trends into concrete commercial decisions.
For detailed analysis of this topic, please visit the official page: Recycled Containerboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com