

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Manhole Covers Market CAGR Insights: How Asia Pacific and Cast Iron Are Driving Growth
By pmarketresearch, 2026-09-21
The Manhole Covers Market: Strategic Shifts, Supply Chain Pressures, and the Road to 2032
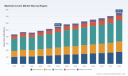
The global market for manhole covers has evolved from a commoditized municipal procurement category into a strategically significant segment of the broader infrastructure and civil engineering ecosystem. Valued at approximately $547.6 million in 2025, the market has demonstrated consistent expansion over the past five years, with historical growth reflecting steady infrastructure renewal, urban density increases, and gradual material substitution. Looking ahead to 2032, the market is projected to reach $750.9 million, supported by a compound annual growth rate of 4.6 percent. This trajectory is neither explosive nor stagnant; it is indicative of a mature, regulation-bound market where incremental innovation, compliance-driven substitution, and regional infrastructure spending patterns dictate competitive positioning.
For executives, strategists, and investors, the manhole cover market offers a useful lens into how seemingly low-tech industrial categories respond to digitalization, sustainability mandates, and cost volatility. The core opportunity lies not in volume alone, but in understanding where specification power, material performance, and service integration are creating durable differentiation. The sections below examine the market’s current realities, the forces reshaping demand and supply, competitive dynamics among leading players, and the strategic implications for the next several years.
Market Context and Core Challenges
The market’s scale and growth profile reflect a steady, demand-driven expansion rather than a speculative upcycle. Revenue has climbed through 2025 with a pattern of moderate year-over-year gains, consistent with long-cycle municipal and industrial infrastructure replacement programs. The forward projection through 2032 points to continued expansion, albeit at a measured pace that will reward operators who can manage specification cycles, material costs, and compliance requirements efficiently. The category is relatively fragmented at the top, with the three largest players holding a combined share near 24.6 percent and the top five accounting for approximately 26.2 percent, indicating room for consolidation as well as persistent niche competition.
Several structural challenges define the current market environment and are likely to influence strategic decisions through the forecast period.
Material cost volatility and input price sensitivity. Iron castings and scrap-based feedstocks form the backbone of traditional cover manufacturing, and price movements in these inputs translate quickly into margin pressure. Recent producer price indices for ductile iron castings have shown upward movement, while heavy melting steel scrap pricing has reflected broader commodity dynamics. Manufacturers operating on fixed-price municipal contracts or long bid cycles face the dual challenge of absorbing input cost spikes while maintaining competitiveness in re-bid situations. This environment favors firms with diversified sourcing, hedging strategies, and the ability to shift mix toward higher-margin products.
Regulatory compliance as both barrier and catalyst. Specification standards are tightening in multiple geographies. In the United States, approved material lists and performance requirements for state-funded projects increasingly mandate specific load ratings and standards alignment, directly influencing procurement eligibility. Elsewhere, sewage network specifications require compliance with recognized load-class certifications and documented conformity. These requirements elevate the importance of certification readiness, quality documentation, and technical support during the specification process. Operators without robust compliance infrastructure risk disqualification from high-value public tenders, while those with established certification portfolios can use compliance as a differentiator rather than a baseline cost.
Substitution pressure from alternative materials. Composite and other non-metallic solutions are gaining traction where weight reduction, corrosion resistance, or installation logistics are prioritized. This substitution is not uniform across applications or regions; it is most pronounced where labor costs, traffic disruption costs, or aggressive corrosion environments make traditional cast or ductile iron less advantageous on a total-cost basis. The strategic implication is that incumbents must compete not only on price but on lifecycle value, installation efficiency, and application-specific engineering justification.
Key Drivers Reshaping the Market
The market’s trajectory is being shaped by a combination of technology adoption, regulatory evolution, changing user expectations, and shifting cost structures. These drivers interact in ways that create both margin opportunities and competitive risk.
Technology innovation and intelligent infrastructure integration. The most visible innovation pathway is the integration of sensor-enabled functionality into cover and frame systems for monitoring, safety, and asset management. Investments in new manufacturing capacity oriented toward smart cover technology reflect an attempt to attach recurring value to a traditionally one-time procurement. Beyond sensors, advances in casting precision, surface treatments, locking mechanisms, and ergonomic installation features are improving operational outcomes for utilities and contractors. The strategic significance lies in shifting the category from a replaceable commodity to a monitored asset, which can strengthen customer stickiness when paired with service and maintenance relationships.
Policy and regulatory environment. Standards and approved material lists are becoming more explicit, particularly in public works. Load ratings, structural performance criteria, and certification requirements are increasingly tied to procurement eligibility. This trend advantages suppliers that can demonstrate compliance across multiple standards and provide transparent documentation. It also raises entry barriers for smaller producers that cannot sustain the administrative and testing overhead associated with multi-jurisdiction compliance. At the same time, regulation can accelerate replacement cycles where older infrastructure fails to meet updated standards, creating incremental demand for compliant replacements.
Demand-side behavior and total-cost consideration. Procurement decisions are increasingly influenced by total installation and lifecycle cost rather than unit price alone. Lightweight, high-strength alternatives are being evaluated for their potential to reduce manual handling risk, shorten installation time, and lower transportation costs. Urban utilities managing extensive networks in dense environments are especially sensitive to labor productivity and traffic disruption. As a result, specification conversations are shifting toward application-specific engineering, safety outcomes, and operational efficiency, particularly in industrial and commercial settings where downtime and safety incidents carry high indirect costs.
Supply chain and cost structure dynamics. The cost environment for ferrous inputs remains a critical variable. Producer price movements for ductile iron castings and fluctuating scrap pricing have introduced uncertainty into cost planning. Suppliers that rely on single-region sourcing or narrow supplier bases are more exposed to price shocks and logistics disruptions. Meanwhile, the relative attractiveness of composite solutions is partly a response to metal input volatility, as well as to the operational benefits of lower weight and improved corrosion behavior. Over the forecast period, cost structure resilience—through procurement diversification, inventory discipline, and product mix optimization—will differentiate financially stable operators from those exposed to raw material swings.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of regional incumbents, application-focused specialists, and exporters that compete on specification support, certification breadth, and manufacturing flexibility. The market’s top-heavy but not highly concentrated structure means that scale alone does not guarantee advantage; specification relationships, service capabilities, and differentiation in high-value niches often determine winning positions.
Leading manufacturers are pursuing distinct strategic positions that align with their capabilities and target segments.
Neenah Foundry illustrates the pivot toward innovation-led differentiation. By expanding manufacturing capabilities with a focus on smart cover technology and IoT-enabled infrastructure monitoring, the company is positioning beyond the traditional replacement cycle. This strategy is designed to attach higher-value functionality to standard infrastructure assets, potentially opening pathways to specification wins where monitoring, safety, and asset visibility are priorities. The approach carries execution risk—integration complexity, customer adoption cycles, and the need to demonstrate measurable operational returns—but it signals a longer-term positioning in intelligent infrastructure rather than purely metal fabrication.
EJ Group, Inc. represents a complementary strategy centered on material substitution and installation economics. The launch of a new line of lightweight, high-strength composite covers targets safety improvement and reduced installation costs. This direction aligns with demand-side shifts toward labor efficiency and risk reduction, particularly in environments where weight and handling are significant cost drivers. Composite solutions also offer corrosion advantages that can be compelling in aggressive environments. The challenge for this strategy is sustained adoption across specification bodies that may default to familiar metallic standards, which places emphasis on pilot projects, specification support, and total-cost justification.
Manhole Covers Limited and Manhole Covers Direct reflect the importance of regional presence, specification responsiveness, and channel access. In markets where local compliance, rapid fulfillment, and application-specific consultation influence purchasing decisions, these players compete through service agility and targeted product breadth. Their relevance underscores that even in a globalizing category, proximity to specification processes, distributor networks, and end-user support remains a meaningful advantage.
The market is likely to evolve along two parallel paths. First, consolidation may accelerate among producers seeking scale in manufacturing, sourcing, and compliance overhead, particularly where raw material volatility and certification demands raise the fixed-cost floor. Second, differentiation will intensify in segments where intelligent features, composite substitution, and specification-led value can command premium positioning. New entrants with specialized material science capabilities, sensor integration expertise, or application-specific engineering may gain footholds in niches that incumbents undervalue, while broader market share shifts will depend on the ability to win recurring municipal and industrial specification cycles.
Worldwide LED Tube Covers Market
Outlook for the Next 3–5 Years
Based on current market structure, regulatory direction, and innovation activity, several trends are likely to shape the market through the end of the decade.
Standardization of intelligent and connected infrastructure components. Sensor-enabled covers and related monitoring capabilities are likely to move from early-adoption projects toward broader consideration in smart city and utility modernization programs. The commercial opportunity lies not in the cover alone, but in the integration of monitoring with asset management workflows and maintenance planning. Operators that can offer compatible data interfaces, service relationships, and clear return-on-investment narratives will be better positioned to convert pilot interest into specification wins. A key uncertainty is the pace of public-sector budget allocation for smart infrastructure add-ons, which can be uneven across regions and procurement cycles.
Continued material diversification tied to lifecycle economics. Composite and hybrid solutions are expected to capture additional share where weight, corrosion, safety, and installation efficiency strongly influence total cost. This shift is unlikely to displace metal covers across the board, given the durability and familiarity of cast and ductile iron in many applications. Instead, the market will likely see a more segmented material mix, with choice driven by environment, load requirement, and operational priorities. Manufacturers that can provide credible testing data, certification support, and field evidence will be better equipped to compete for specifications that are open to alternatives. The uncertainty here is regulatory inertia; in some markets, established standards and procurement habits slow substitution even when total-cost arguments are strong.
Compliance-driven replacement and consolidation pressure. Updated load ratings, approved material lists, and certification expectations will continue to trigger replacement demand where existing infrastructure falls short of current requirements. At the same time, rising compliance overhead and input cost volatility may encourage consolidation among smaller producers and create supply advantages for operators with broader manufacturing footprints and more resilient sourcing. The strategic opportunity is to align production and certification capacity with the specifications most likely to see repeat procurement. The risk is margin compression if cost inflation outpaces pricing flexibility, especially in markets where bids are heavily price-driven and differentiation is limited.
Worldwide Cast Iron Manhole Covers Market
Regional divergence in growth drivers. While the market is expanding globally, demand momentum will not be uniform. Regions with active municipal renewal programs, dense utility networks, and stricter compliance requirements are likely to generate steadier replacement volume. In contrast, markets with slower public investment or limited specification formalization may see more intermittent demand. Companies operating across regions will need to calibrate capacity, product mix, and compliance portfolios to local specification realities rather than relying on a single global formula.
Strategic Actions for Decision-Makers
The market’s trajectory suggests that value creation will come from alignment across specification strategy, material and product mix, and cost resilience rather than from volume expansion alone. The following actions are most relevant depending on organizational role.
PW Consulting
For manufacturers and suppliers.
- Invest in certification breadth and documentation agility so that compliance becomes a competitive asset rather than an administrative burden, especially where public procurement requires explicit standards alignment and load-class verification.
- Develop application-specific value narratives that quantify installation efficiency, safety outcomes, and lifecycle performance, particularly for lightweight and composite offerings where total-cost justification is essential to overcome specification inertia.
- Diversify raw material sourcing and strengthen inventory and pricing flexibility to reduce exposure to ferrous input volatility, while evaluating product mix shifts that protect margin during cost spikes.
- Build credible pathways for intelligent infrastructure offerings by linking sensor integration to measurable operational benefits and service models, rather than treating connectivity as an isolated feature.
For investors and strategic acquirers.
- Focus diligence on specification relationships, certification readiness, and regional distribution strength, since these often determine repeat procurement more reliably than headline capacity.
- Assess exposure to raw material cycles and the flexibility of pricing and mix strategies, as input cost volatility can quickly alter margin profiles in otherwise stable-volume businesses.
- Identify targets with credible differentiation in smart infrastructure, composite substitution, or high-compliance municipal segments, where future value is likely to concentrate as standards tighten and replacement cycles accelerate.
For procurement and infrastructure operators.
- Evaluate covers on total installation and lifecycle cost, including handling safety, traffic disruption, corrosion environment, and maintenance implications, rather than on unit price alone.
- Align procurement specifications with current standards and load requirements to reduce re-work and disqualification risk, while leaving room for application-specific alternatives where they improve operational outcomes.
- Request documented certification, testing evidence, and installation guidance during the specification process to avoid downstream compatibility issues and compliance gaps.
Manhole covers may appear to be a straightforward industrial product, but the market’s evolution is increasingly defined by compliance, material economics, installation efficiency, and the early stages of intelligent infrastructure integration. For organizations operating in or adjacent to this category, timely access to detailed segmentation, regional specification patterns, and competitive movement data can sharpen procurement, investment, and product strategy. The broader market trajectory is clear; the actionable nuance lies in how each player positions for the intersections of regulation, material substitution, and innovation over the coming years.
For detailed analysis of this topic, please visit the official page: Manhole Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
SOM Market: 9.2% CAGR Trajectory and the Architecture Shift Reshaping 2032
By pmarketresearch, 2026-09-21
System on Module Market Outlook: Strategic Trends and Commercial Opportunities (2026–2032)
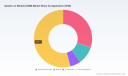
The System on Module (SOM) market has entered a phase of accelerated expansion, driven by the convergence of edge computing, industrial automation, and the proliferation of specialized embedded architectures. Between 2020 and 2025, global revenue climbed from approximately $1.2 billion to nearly $1.94 billion, reflecting a compound annual growth rate of roughly 9.2 percent through the forecast horizon extending to 2032. By the close of that decade, market size is projected to approach $3.43 billion, signaling a structural shift rather than a cyclical upturn. The trajectory is supported by sustained demand across industrial automation, medical device development, transportation systems, and a broad base of other application domains that continue to evaluate modular computing as a way to compress design cycles and manage long-term platform risk.
Market concentration remains relatively fragmented at the top tier, with the largest three participants holding a combined share in the mid-twenties and the top five extending only slightly further. This dispersion indicates that value capture is still distributed across regional specialists, architecture-focused suppliers, and broad-line embedded computing providers. At the same time, the competitive landscape is being reshaped by rapid productization cycles, architecture diversification, and an emerging emphasis on edge AI capabilities that extend well beyond traditional compute-density metrics. For executives and investors, the relevant question is no longer whether SOMs will continue to gain share in embedded design, but how to align product roadmaps, sourcing strategies, and portfolio investments with a market that is maturing while simultaneously fragmenting into more specialized use cases.
The period ahead will be defined by several intersecting forces: architectural choices between ARM, x86, and Power-based designs; the speed at which edge AI workloads migrate from proof-of-concept to production; the regulatory and compliance pressures that are altering the cost of packaging, materials, and end-of-life obligations in certain regions; and the supply chain dynamics that continue to reward suppliers who can offer predictable availability, long-term support, and validated integration paths. The following analysis examines these dynamics in detail, with an emphasis on what they mean for strategy, capital allocation, and operational planning.
Market Context and Critical Inflection Points
A Market Built on Modularization and Edge Expansion
The SOM market's growth story is rooted in a simple but durable premise: customers want to move faster without inheriting the full burden of board-level integration, long-term silicon validation, and multi-architecture porting. Modular platforms allow OEMs, integrators, and system builders to separate core compute selection from carrier-board design, thermal planning, and application software stacks. That separation has become increasingly valuable as embedded projects span longer lifecycles and face more demanding environmental, safety, and reliability requirements.
This dynamic has helped SOMs expand across industrial automation, medical systems, transportation, and a wide range of additional application areas where platform longevity and design flexibility matter as much as raw performance. The revenue pattern over the past several years reflects steady adoption rather than a one-time surge, with 2025 estimated at roughly $1.94 billion and the forward path suggesting continued double-digit momentum. More importantly, the composition of demand is shifting. Projects are no longer being evaluated solely on whether a module can meet today's compute target; they are being assessed on whether they can support future software updates, accommodate evolving security requirements, and remain available across multi-year production runs.
Key Pressures Shaping the Next Phase
Three pressure points stand out as especially consequential for the next planning cycle.
- Architecture decision complexity. The rise of multiple viable compute paths, including ARM-based designs, x86 options, and Power-based solutions, gives engineering teams more flexibility but also more evaluation overhead. Buyers must weigh performance-per-watt, software ecosystem maturity, long-term supply stability, and integration risk. This complexity increases the need for suppliers who can provide clear migration guidance and validated roadmaps rather than a broad catalog alone.
- Edge AI moving from acceleration to operating requirement. AI-related workloads at the edge are increasingly treated as baseline functionality rather than optional enhancements. That shift is pushing SOM suppliers to integrate specialized processing capabilities, optimize memory paths, and simplify the deployment of models in constrained environments. It also raises the bar for thermal management, software tooling, and lifecycle support, especially where devices must operate in industrial or medical settings.
- Regulatory surface area expanding beyond electronics itself. Packaging and extended producer responsibility requirements are tightening in several jurisdictions, and electronics suppliers that manufacture, distribute, or assemble in affected regions are exposed indirectly through packaging, logistics, and compliance documentation. While SOMs are not the central target of these rules, the broader operational environment is becoming more costly and more administrative. Suppliers that treat sustainability and compliance as design inputs rather than after-the-fact reporting items will have an operational advantage.
Taken together, these pressures suggest a market that will continue to grow, but with higher expectations around support, traceability, and architectural fit. Companies that compete primarily on price or catalog breadth without a clear migration path or application-specific validation may find it harder to hold share as design cycles lengthen and accountability increases.
Core Drivers Reshaping Demand and Supply
Technology Innovation as the Primary Accelerator
The most direct driver of SOM adoption remains technology innovation, but it is evolving in character. The immediate emphasis has shifted from generic compute availability to more targeted capabilities: integrated AI acceleration, improved power efficiency, smaller form factors for constrained installations, and architectures that can be adapted across multiple product generations. Recent product activity illustrates this direction clearly. In March 2026, Grinn launched the AstraSOM-261x, described as an ultra-compact Edge AI SOM built around the Synaptics Astra AI-native processor. At roughly the same time, the company introduced the aReady.CoM module to support Arm technology migration within its SOM portfolio. These releases are not isolated product announcements; they reflect a broader industry movement toward tightly optimized modules for edge AI and toward smoother migration between processor generations or ecosystems.
This shift matters commercially because it compresses the time between concept and deployment in edge scenarios where space, thermal budget, and software complexity are all constrained. It also favors suppliers that can pair hardware with evaluation platforms, carrier-board templates, and reference software flows. In practice, the winners are increasingly those who sell a design-ready environment, not just a module.
Policy and Regulatory Pressure as a Hidden Cost Structure
Regulatory developments are increasingly influencing the operational backdrop for embedded hardware suppliers. In the United States, multiple states advanced packaging and extended producer responsibility frameworks in 2025, with coverage expanding across material types and producer obligations. California's SB 54, for example, extends EPR requirements to certain single-use plastic food service ware and sets recycling-rate expectations for expanded polystyrene producers beginning in 2025. Oregon launched its packaging EPR program in July 2025, requiring participating producers to report material volumes through designated stewardship channels. Maine began formal rulemaking later in 2025 to update packaging stewardship rules and clarify recyclable, compostable, and reusable material listings. Similar activity is visible across Canadian provinces, where nine out of thirteen jurisdictions operated packaging EPR programs as of early 2025, covering plastics, paper and cardboard, glass, and metal packaging.
For SOM providers and their customers, the implication is not a direct electronics regulation but a wider compliance burden that touches packaging, distribution, and regional market access. As more jurisdictions move from voluntary sustainability initiatives to mandatory reporting and material requirements, companies with fragmented supplier documentation or inconsistent packaging standards will face higher administrative and logistical friction. This environment rewards suppliers who can standardize materials, provide clear reporting support, and align product design with regional compliance expectations early rather than retrofitting them during production ramp-up.
Demand-Side Shifts Toward Platform Durability and Edge Intelligence
On the demand side, the most meaningful change is a growing preference for platforms that are durable, modular, and capable of accommodating evolving workloads. Industrial automation projects, in particular, increasingly prioritize long availability windows, field upgradeability, and predictable software support. Medical applications require validated designs, stable documentation, and rigorous control over component changes. Transportation and other rugged use cases add environmental tolerance and lifecycle reliability to the mix. Across these segments, SOMs offer a way to reduce redesign friction when requirements change, which is especially valuable in programs that span years rather than months.
At the same time, edge intelligence is reshaping what customers consider "sufficient" performance. It is no longer enough for a module to deliver processing headroom; it must also support efficient inference, manageable power consumption, and integration paths that do not require extensive custom engineering for every deployment. This shift benefits suppliers with strong application alignment and clear software ecosystems, and it increases scrutiny of the total cost of ownership, including integration effort and long-term support.
Supply Chain and Cost Dynamics Favoring Predictability
Cost structures in the SOM market are being influenced by more than component pricing alone. Lead-time predictability, validation support, and regional availability increasingly affect purchasing decisions, particularly in applications where production disruptions carry high downstream costs. Suppliers that can provide transparent roadmaps, durable part availability, and design assistance reduce one of the largest hidden costs in embedded development: schedule uncertainty.
PW Consulting
The market is also seeing a gradual recalibration of where value is created. Some suppliers compete by offering broad architecture coverage and distribution reach; others compete through specialized vertical solutions and tighter integration with specific application domains. The result is a market in which cost leadership is less decisive than reliability of delivery, clarity of migration options, and the ability to reduce integration risk. That has important implications for both procurement strategy and supplier selection.
Competitive Landscape: Positioning, Differentiation, and Evolution
Differentiated Strategies Among Leading Participants
The competitive set in the SOM market reflects a wide range of positioning choices. Several suppliers focus on architecture-specific strength, while others emphasize multi-architecture breadth, ruggedization, or vertical application alignment. Rather than viewing the field through a single dimension, it is more useful to recognize that differentiation now comes from a combination of architecture expertise, application fit, integration support, and long-term availability commitments.
Toradex AG, based in Switzerland, is strongly associated with high-performance ARM-based modules for industrial, medical, and IoT applications. That focus gives the company a clear identity around ARM-centric design environments and application domains where longevity and embedded software continuity are priorities. Congatec AG, headquartered in Germany, concentrates on COM Express and SMARC-based modules optimized for embedded computing, positioning the firm around standardized form factors and scalable embedded platforms. Kontron AG, also in Germany, emphasizes x86 and ARM-based SOMs for industrial automation and edge computing, aligning its portfolio with sectors that demand a blend of performance and application-ready support.
Advantech Co., Ltd., based in Taiwan, rounds out a broad embedded footprint with rugged SOMs spanning ARM, x86, and RISC-V architectures, an approach that suits customers who need flexibility across multiple deployment environments. Aaeon Technology Inc., also in Taiwan, focuses on compact SOMs for edge AI and industrial applications, emphasizing small-footprint designs suited to space-constrained intelligent systems. Phytec Messtechnik GmbH, in Germany, offers the phyCORE SOM series based on ARM, PowerPC, and RISC-V for embedded systems, reinforcing a multi-architecture path for projects that may require diverse processor ecosystems.
SECO S.p.A., in Italy, provides industrial SOMs with ARM and x86 processors for automation and robotics, a positioning that highlights application-driven engineering rather than generic catalog breadth. Portwell Inc., also in Taiwan, supports high-performance SOMs across multiple architectures for edge computing, targeting applications where performance and integration flexibility both matter. Variscite Ltd., based in Israel, focuses on SOMs built around Renesas and NXP for industrial and automotive use, an approach that connects product strategy closely with specific processor ecosystems and use cases. SolidRun Ltd., also in Israel, concentrates on ARM-based SOMs for embedded and edge applications, reinforcing its identity around ARM-centric embedded design.
MYIR Tech, in China, offers SOMs with ARM and RISC-V processors for IoT and industrial projects, emphasizing accessible designs for broader deployment scenarios. iWave Systems, based in India, focuses on SOMs built on Qualcomm and NXP for mobile and embedded solutions, aligning its portfolio with communications-oriented and embedded applications. Grinn, headquartered in Poland, has carved out a niche in nano-sized Edge AI SOMs based on Synaptics processors, and its recent launches show a clear intent to push miniaturization and migration flexibility. Technexion, in Taiwan, provides ARM and NXP-based SOMs for robotics and industrial automation, reinforcing a vertical tilt toward mechatronics and automation workflows.
EMAC, based in the United States, addresses industrial and defense applications, a positioning that implies a greater emphasis on ruggedness, specialized support, and longer lifecycle accountability. Avalue Technology Inc., also in Taiwan, offers rugged SOMs for transportation and edge computing, reflecting the demand for environmental resilience in mobile and infrastructure-facing deployments. Forlinx, in China, focuses on SOMs for industrial and IoT deployments, positioning itself around practical embedded deployment rather than flagship performance alone. MSC Technologies, operating under Avnet in the United States, distributes SOM solutions through Avnet channels, adding the dimension of broad distribution reach and customer access across multiple application segments.
Computer On Module (COM) Market
Strategic Positioning Themes
Across this group, several positioning themes recur.
- Architecture specialization versus multi-architecture breadth. Some suppliers compete by going deep on one architecture family and the ecosystems that surround it, while others emphasize the ability to cover ARM, x86, RISC-V, and Power-based designs within a single engagement. Both models can work, but they attract different buyer profiles. Specialists tend to win when project teams want a clear path and deeply aligned tooling; broad-line suppliers win when procurement or engineering teams need flexibility across multiple programs.
- Application-centric engineering. The most meaningful differentiation often comes from application alignment. Suppliers that build reference designs, carrier-board guidance, and domain-specific support around industrial automation, medical systems, transportation, or edge AI reduce integration risk in ways that catalog listings cannot. This is especially important where certification, documentation, or long-term maintenance expectations are high.
- Miniaturization and edge AI readiness. The move toward smaller, purpose-built modules for AI workloads is creating a distinct value layer within the market. Modules that combine compact form factor with dedicated AI processing and migration-friendly design are likely to attract early adoption in edge scenarios where space and integration effort are constrained.
- Distribution and ecosystem reach. Distribution partnerships and channel access can matter as much as product features, particularly for buyers who prioritize sourcing simplicity, regional availability, and established procurement pathways. This dimension does not replace product differentiation, but it can amplify reach and reduce friction in volume programs.
How the Landscape Is Evolving
The market is not consolidating into a single dominant structure. Instead, it is evolving through a mix of specialization, selective convergence around edge AI, and expanding regional participation. Some suppliers are likely to deepen vertical focus in high-value sectors such as industrial automation or medical devices, while others will continue to compete by offering multi-architecture coverage and wider distribution. New entrants can still find space by addressing a specific form factor, processor ecosystem, or application niche, especially when they pair hardware with a compelling development experience.
At the same time, incumbents face growing pressure to prove long-term support, migration clarity, and application validation. The presence of multiple capable players reduces the risk of supplier lock-in, but it also raises expectations. Buyers increasingly compare not just features and unit cost, but the quality of engineering support, documentation stability, and the likelihood that a chosen module will remain viable through multiple product generations. In that environment, the strategic moat belongs to suppliers that can reduce uncertainty across the entire design lifecycle.
Forward-Looking Trends and Commercial Opportunities
Trend One: Edge AI as a Core Evaluation Criterion
Over the next three to five years, edge AI capability is likely to become a central part of SOM evaluation rather than a differentiating feature in a subset of projects. As inference moves from experimental deployment to routine operation, buyers will look for modules that combine efficient processing, manageable thermal profiles, and straightforward software integration. This trend opens commercial opportunities for suppliers that can offer validated AI-ready modules, reference software flows, and clear guidance on model deployment in resource-constrained environments.
The broader opportunity lies in helping customers move from prototype to production faster. Suppliers that reduce the friction of AI integration, including model portability, memory planning, and carrier-board compatibility, will be well positioned to capture design wins in automation, medical devices, smart infrastructure, and other edge-heavy domains. The risk is that expectations will rise quickly; modules that appear AI-capable on paper but lack practical deployment support may lose credibility in demanding applications.
Worldwide System on Module Boards Market
Trend Two: Multi-Architecture Navigation Will Become More Strategic
ARM, x86, RISC-V, and Power-based designs will continue to coexist, and the practical question will increasingly be how to choose and migrate between them without costly redesigns. Buyers will look for clearer migration paths, more transparent roadmaps, and support for transitions across processor generations. This creates an opportunity for suppliers that invest in migration tooling, documentation, and carrier-board strategies that simplify architecture changes.
This trend also creates risk for companies that treat architecture choice as a one-time decision rather than a lifecycle consideration. As software stacks, toolchains, and long-term availability expectations evolve, the cost of staying on a rigid platform may exceed the cost of building in migration flexibility. Organizations that ignore this dynamic may face avoidable redesign pressure later.
Trend Three: Operational Compliance Will Influence Supplier Preference
The expansion of packaging and extended producer responsibility requirements will continue to shape operational preferences, especially for suppliers serving multiple jurisdictions. While SOMs are not the primary subject of these rules, the broader compliance environment affects packaging, documentation, reporting, and regional market access. This creates a commercial advantage for suppliers that can standardize materials, streamline reporting, and help customers navigate regional obligations without disrupting production timelines.
The commercial implication is subtle but real. In programs where compliance overhead is high, buyers may favor suppliers who reduce administrative burden even if the immediate hardware price differential is small. Over time, this can shift competitive advantage toward suppliers with cleaner operational processes and stronger documentation discipline. The uncertainty lies in how quickly and uniformly these requirements spread; variability across regions can create uneven exposure and complicate global sourcing strategies.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Development Leaders
- Prioritize architecture decisions based on lifecycle fit, not just current performance. Evaluate migration paths, software ecosystem continuity, and long-term availability before committing to a platform. A module that supports a smoother transition across generations can reduce redesign risk more than a short-term performance advantage.
- Treat integration support as part of the product cost. Reference designs, carrier-board guidance, and application-specific validation can shorten development timelines and reduce engineering exposure. Select suppliers that offer a repeatable design environment rather than only a hardware module.
- Plan for edge intelligence as a baseline requirement in relevant applications. If a product roadmap anticipates AI-related features, choose a module strategy that can accommodate inference workloads without forcing a complete redesign later.
For Investors and Strategic Planners
- Focus on differentiation that compounds over time. In a fragmented market, durable advantages tend to come from application alignment, migration support, and integration tooling rather than catalog size alone. Companies that can demonstrate repeatable design wins in industrial automation, medical, transportation, or edge AI are likely to be more resilient than those competing on breadth without clear application fit.
- Watch for consolidation around edge AI value chains. As miniaturized AI modules and migration-friendly designs gain traction, expect more activity around specialized suppliers and potentially more partnerships that combine hardware, distribution, and software enablement. The opportunity is in platforms that reduce deployment complexity, not just in modules that add processing capability.
- Monitor regulatory exposure as a competitive variable. Suppliers that can anticipate regional compliance requirements and streamline documentation and packaging processes may gain preference in multi-region programs, even when hardware specifications are broadly similar.
For Procurement and Sourcing Teams
- Evaluate total cost of ownership beyond unit price. Factor in lead-time reliability, documentation quality, support responsiveness, and the operational burden of regional compliance. In many embedded programs, schedule stability and integration support matter more than marginal component savings.
- Build sourcing flexibility without sacrificing validation discipline. Multi-supplier strategies can reduce risk, but they should be paired with clear qualification criteria so that migration between suppliers does not create new integration debt.
- Confirm long-term availability expectations early. Where programs span several years, align procurement commitments with supplier roadmaps and change-control processes to avoid disruptive revisions during production.
For teams that need deeper segmentation, regional nuance, and supplier-by-supplier performance benchmarking, the full PW Consulting research suite provides a more detailed view of market structure, architecture splits, application demand, and competitive positioning. The complete report can support scenario planning, sourcing strategy, and investment prioritization with more granular data and customized analysis.
For detailed analysis of this topic, please visit the official page: System on Module (SOM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mobile Crushers and Screeners Market: Asia Pacific’s 5.26% Growth and the Shift to Recycling
By pmarketresearch, 2026-09-21
Mobile Crushers and Screeners Market: Strategic Trends and Commercial Opportunities Through 2032
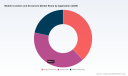
The mobile crushing and screening sector has evolved from a commoditized equipment niche into a strategically critical segment within the broader heavy machinery landscape. As construction activity intensifies, stricter environmental mandates tighten operational constraints, and material recycling becomes economically imperative, manufacturers and fleet operators alike are recalibrating their investment theses. The market has demonstrated consistent growth over the past half-decade and is projected to expand at a steady compound annual growth rate of 5.26 percent through 2032. While aggregate revenue figures provide a useful baseline, the real strategic value lies in understanding where value is migrating: from raw tonnage capacity toward electrified drivetrains, modular screening architectures, integrated telematics, and compliance-ready emission control systems. This shift is reshaping competitive positioning, procurement criteria, and capital allocation strategies across mining, construction, and recycling verticals.
With a market base exceeding two billion dollars in recent years and a projected trajectory approaching four billion by the early 2030s, the segment is large enough to attract sustained capital but fragmented enough to reward operators who anticipate structural inflection points. Three forces are defining the current landscape: tightening dust and particulate regulations that force equipment redesigns, accelerating electrification that blurs the line between mobile machinery and industrial power electronics, and cyclical but structurally rising demand for on-site material processing that favors flexibility over stationary plant investments. Navigating these dynamics requires a clear grasp of technology roadmaps, regulatory exposure, and competitive differentiation rather than reliance on historical equipment replacement cycles alone.
Market Context and Core Challenges
The mobile crushers and screeners market has matured beyond the simple replacement cycle model that characterized its earlier growth phase. Revenue expansion has been supported by sustained infrastructure development, urbanization-driven aggregate demand, and a growing preference for mobile configurations that reduce haul distances, lower fuel consumption, and enable rapid redeployment across multiple sites. However, the growth path is no longer purely volume-driven. The strategic question for operators and capital allocators is how to capture margin expansion while absorbing higher compliance costs, technology transition expenses, and supply chain volatility.
PW Consulting Automotive & Machinery Research Center
One defining challenge is the regulatory tightening around particulate emissions, noise, and site suppression. Environmental agencies across multiple jurisdictions have moved from advisory guidance to enforceable permitting and operational mandates for mobile crushing and screening equipment. Plants exceeding certain throughput thresholds now face permit requirements, wet suppression systems are increasingly mandated on aggregate processing sites, and operator safety standards have been reinforced with stricter lockout, tagout, and personal protective equipment protocols. These mandates are not marginal compliance footnotes; they influence equipment architecture, site planning, maintenance cycles, and total cost of ownership. Manufacturers that treat regulation as a design constraint rather than an afterthought are gaining a meaningful commercial advantage.
A second challenge is the technology transition from conventional diesel-mechanical drives to hybrid and fully electrified configurations. Electrification is reshaping performance expectations, service requirements, and onsite infrastructure needs. While hybrid and plug-in systems can reduce fuel consumption and operating emissions, they also introduce new dependencies on battery management, power electronics, charging logistics, and technician training. The industry is still resolving questions around battery durability in harsh quarry conditions, grid or generator support on remote sites, and the economic payback under volatile energy pricing. This transition is opening opportunities for differentiated product lines, but it is also raising the performance bar for market participation.
A third challenge is market fragmentation combined with cyclical demand exposure. The sector features a mix of global incumbents, regional specialists, and emerging entrants, each competing on different axes such as mobility, screening precision, application-specific configurations, and service networks. At the same time, capital-intensive end markets remain sensitive to interest rates, public spending cycles, and commodity price fluctuations. This creates a landscape where scale alone is insufficient; resilience, application breadth, and aftermarket monetization are becoming decisive differentiators.
Key Demand Drivers
Technology Innovation and Electrification
Electrification and hybrid drivetrain architecture are among the most consequential innovation vectors in the mobile crushing and screening space. Manufacturers are moving beyond incremental fuel efficiency gains toward integrated power systems that combine diesel-electric gensets, battery buffers, and plug-in capability. These platforms enable lower onsite emissions, reduced noise, and more precise process control, which in turn supports compliance in sensitive operating environments and expands work windows in urban or regulated zones. The competitive edge is increasingly tied to how seamlessly electrification is integrated into crusher and screener functions, including feed control, screening kinematics, and conveyance, rather than treating it as a standalone powertrain swap.
Digitalization and telematics are reinforcing this trend. Real-time monitoring of crusher loads, screen wear, fuel or energy consumption, and maintenance intervals supports predictive service, reduces downtime, and strengthens the value proposition of integrated equipment fleets. Equipment that can be configured rapidly, moved efficiently, and diagnosed remotely is gaining preference in multi-site operations where labor availability and specialization are constrained. Innovation is therefore shifting from purely mechanical performance to system-level reliability, connectivity, and operational flexibility.
Policy and Regulatory Environment
Regulatory pressure is becoming a direct driver of product design and procurement decisions. Permitting requirements for nonmetallic mineral processing, suppression mandates for crushers and screens, and stricter air-quality oversight for mobile operations are influencing equipment selection at the project level. In many cases, the fastest path to compliance is not incremental retrofit but the selection of mobile plants designed from the outset with dust suppression integration, lower particulate generation, and operator safety controls.
These dynamics are particularly relevant where aggregate processing occurs near populated or environmentally sensitive areas. Site permitting timelines, community acceptance, and operator safety obligations are increasingly tied to equipment specifications. Manufacturers and fleet managers that align product design with prevailing and anticipated regulatory requirements can shorten project approval cycles and reduce operational friction. At the same time, the regulatory environment varies by region and application, which means compliance strategy must be localized rather than assumed from a single benchmark.
Demand-Side Shifts in Mining, Construction, and Recycling
On-site material processing is being driven by a combination of logistical efficiency and material circularity. In mining and quarry operations, mobile configurations reduce the need for fixed infrastructure and long-haul movement of raw material, supporting flexible expansion and site switching. In construction, road building and aggregate processing demand is benefiting from rising infrastructure spending, with mobile plants enabling faster mobilization and quicker return on project timelines. In material recycling, the ability to process concrete, asphalt, and construction debris at or near the source is becoming economically and operationally attractive as disposal constraints and material recovery goals increase.
The demand profile is thus diversifying. It is no longer sufficient to optimize equipment solely for primary crushing throughput. Screening accuracy, adaptability to different feed materials, rapid setup and teardown, and support for secondary and tertiary processing have become commercial priorities. Recycling applications, in particular, are pushing equipment toward configurations that handle mixed inputs, support selective output fractions, and withstand more abrasive and variable feed conditions. This broadens the addressable opportunity but also raises the bar for versatility and durability.
Cone Crushers Market
Cost Structure and Supply Chain Dynamics
Cost dynamics are being reshaped by component availability, energy pricing, and the economics of electrification. Traditional cost structures centered on diesel consumption and mechanical wear are giving way to more complex operating expense profiles that include electrical infrastructure, battery service life, hybrid system maintenance, and software-enabled diagnostics. For fleet operators, the relative attractiveness of hybrid or electric configurations depends heavily on local fuel costs, access to power, labor costs, and the intensity of utilization.
Supply chain resilience is equally important. Manufacturers that can secure drivetrain components, hydraulic systems, wear parts, and electronic controls without extended lead times are better positioned to maintain delivery credibility and service responsiveness. Conversely, supply bottlenecks can erode the advantage of new product launches and delay customer payback. In this environment, procurement strategy is moving toward partnership-based sourcing, regionalization where feasible, and inventory planning that accounts for both mechanical wear and electronic subsystem replacement cycles.
Competitive Landscape and Leading Strategies
The competitive field features a mix of established European and North American manufacturers and growing regional players, each pursuing different strategic identities. Rather than competing purely on machine size or price, leaders are differentiating through application breadth, electrification readiness, mobility design, and aftermarket service systems. The resulting landscape is both consolidated in certain premium segments and active in others where localized support, application focus, and cost positioning create viable niches.
Several incumbents have anchored their positioning around complete mobile crushing and screening trains with hybrid or electrified power options. This approach emphasizes integrated process flow, consistent control across crusher and screen units, and reduced onsite complexity for the operator. By offering coordinated jaw, cone, and impact configurations together with screening and conveying, these manufacturers aim to reduce integration risk for customers and strengthen retention through multi-unit deployments and service contracts. Their differentiation often rests on proven mobility, modular scaling, and the ability to serve multiple applications without extensive re-engineering.
A parallel strategy is emerging around dedicated electrification and hybrid expertise, with some manufacturers building identity around diesel-electric plug-in capability, battery-backed systems, and multi-decade experience with hybrid drivetrains. This positioning is particularly relevant where noise, emissions, and urban proximity constrain conventional diesel operations. These players are positioning electrification not as a feature set but as an operational enabler, paired with equipment designs that support quick deployment, reduced fuel dependence, and compliance-friendly site profiles. In recycling-focused applications, specialized mobile screening and crushing configurations are also gaining traction, with manufacturers emphasizing process flexibility for secondary material recovery, concrete recycling, and abrasive feed handling.
Regional players continue to expand their footprint by combining competitive price positioning with application-specific configurations and accessible service models. Some are building credible offerings around compact tracked screens, jaw crushers, and integrated mobile units for mining, construction, and recycling. Others are developing excavator-attached screening and crushing solutions that expand the definition of mobile processing beyond standalone vehicles. These entrants do not need to replicate full-scale global platforms to compete; instead, they can win by targeting specific application gaps, delivery responsiveness, and localized service coverage.
Impact Crusher Market
Recent market activity reflects the speed of product refresh and customer-facing engagement. Trade show presence and new product introductions are being used to signal technology direction, reinforce application breadth, and maintain visibility in a competitive cycle. For example, the sector has seen coordinated launches and exhibition activity encompassing hybrid and electric crusher ranges, new cone crusher models, and recycling process demonstrations. Such moves matter because they shape buyer perception around innovation readiness and after-sales support, especially in a market where total cost of ownership and uptime are central to purchasing decisions.
The competitive evolution is likely to continue along two tracks: consolidation among players seeking scale, service coverage, and broader application portfolios, and differentiation among specialists targeting electrification, recycling, or compact mobility. New entrants will probably find the most traction where they can solve a clear application problem, offer speed-to-deployment advantages, or provide a distinct cost-service balance. Incumbents will need to defend their position through technology integration, uptime assurance, and compliance-aligned product design rather than scale alone.
Future Trends and Commercial Implications
Electrified and Hybrid Platforms Become a Default Consideration
Over the next three to five years, hybrid and electric configurations are expected to move from differentiated offerings to standard considerations in many applications. This does not mean every unit will be fully electric, but procurement discussions will increasingly weigh energy architecture alongside mechanical performance. The commercial implication is that manufacturers will need to offer clear trade-offs between diesel, hybrid, and electric options, with transparent operating cost modeling and service plans. For fleet operators, early familiarity with electrified equipment, charging or generator support strategies, and maintenance requirements will reduce deployment risk and improve site planning. Companies that delay engagement with these platforms risk higher retrofit costs and slower access to compliant configurations in regulated operating environments.
Application Diversification Toward Recycling and On-Site Processing
Material recycling and on-site aggregate processing are likely to remain important growth vectors, supported by circularity objectives, disposal constraints, and the economic logic of reducing haul distances. Mobile crushing and screening equipment that can handle variable feed, produce multiple output fractions, and be redeployed efficiently will see stronger demand. The commercial opportunity lies in designing product lines and service offerings that address these mixed-material realities rather than treating recycling as a secondary application. For investors and manufacturers, the strategic question is how to scale versatility without sacrificing durability or depressing margin structure.
Data-Driven Service and Integrated Fleet Management
Telematics, predictive maintenance, and fleet-level optimization are expected to become more central to competitive differentiation. Equipment that generates reliable operational data and integrates smoothly into fleet management workflows can reduce downtime and improve utilization across multiple sites. This creates value not only in new equipment sales but also in service contracts, wear-part optimization, and performance-based offerings. The risk is that data integration remains fragmented across manufacturers and sites, limiting the practical benefit. Operators that standardize on interoperable monitoring, service response, and parts logistics will capture more of the efficiency gain than those treating digital tools as isolated features.
Regulatory Risk and Regional Variation
Regulatory conditions will continue to evolve and vary by jurisdiction, creating both opportunity and uncertainty. Plants that proactively align with current permitting and suppression requirements will face fewer delays and lower compliance cost, but assumptions made in one region may not hold in another. The strategic response is to treat regulatory readiness as a design and procurement variable, not a fixed constant. Where possible, equipment and site plans should anticipate stricter particulate, noise, and safety requirements, especially for operations near communities or sensitive environments. Uncertainty remains around the pace and uniformity of regulatory adoption, which makes flexibility in equipment configuration and site design a valuable hedge.
Actionable Recommendations for Decision-Makers
For Manufacturers and Equipment Suppliers
Prioritize integration over isolated feature upgrades. Electrification, telematics, screening precision, and suppression capability should be developed as a coherent system that reduces site complexity and improves compliance readiness. Product roadmaps should be aligned with application realities in mining, construction, and recycling rather than optimized for a single performance metric. Service and parts availability should be treated as a product attribute, because uptime assurance increasingly determines repeat purchase behavior and fleet conversion. Where regional growth is targeted, localized support and delivery responsiveness can be as decisive as headline specifications.
For Investors and Capital Allocators
Focus on companies with credible technology pathways, application breadth, and aftermarket monetization rather than on volume growth narratives alone. The most durable value capture is likely to come from manufacturers that can convert technology transitions into service revenue, shorten deployment cycles, and maintain delivery credibility through supply chain resilience. Pay close attention to how firms are positioned for electrification, regulatory compliance, and recycling-related demand, since these areas are shaping both growth and competitive differentiation. Avoid underwriting strategies that depend on a single application cycle or a narrow geographic exposure without clear diversification levers.
For Procurement and Operations Leaders
Evaluate mobile crusher and screener purchases through total cost of ownership, compliance exposure, and redeployment flexibility rather than initial price or nominal capacity. Consider how energy architecture, suppression systems, and telematics affect site permitting, operating cost, and maintenance planning. Where multi-site or multi-application use is expected, favor configurations that can be rapidly mobilized and adapted to variable feed. Build service relationships and spare-parts strategies around actual utilization patterns and wear profiles, and validate electrification or hybrid choices against local energy access and labor capability instead of relying on generic efficiency assumptions.
The strategic window in this market is defined by the intersection of technology transition, regulatory pressure, and application diversification. Companies that interpret these forces as design and investment constraints rather than background conditions will be better positioned to capture durable value. For decision-makers who need deeper segmentation, regional variation, competitor-level benchmarking, and customized planning inputs, the full market study provides the detailed framework required to translate these trends into executable strategy.
For detailed analysis of this topic, please visit the official page: Mobile Crushers and Screeners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beryllium Copper Market 2026: The Real Drivers Behind 7.85% CAGR Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Beryllium Copper Market
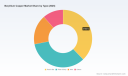
The beryllium copper market has evolved from a niche specialty alloys sector into a strategically critical component of global industrial and defense supply chains. With total market revenue reaching approximately 506.35 million in 2025 and a projected compound annual growth rate of 7.85 percent through 2032, the market trajectory reflects a convergence of technological demand, supply chain recalibration, and regulatory stability. This growth pattern is not merely a function of incremental expansion. It signals a structural shift where high-performance copper-beryllium alloys are increasingly positioned as enablers of miniaturization, reliability, and mission-critical performance across multiple industries.
The market's historical progression from 347.02 million in 2020 to 506.35 million in 2025 demonstrates consistent upward momentum, with notable acceleration in recent years. The forecast period extending to 859.39 million by 2032 underscores sustained demand fundamentals. This expansion is distributed across multiple forms and applications, with rod and bar products, plate and strip configurations, wire, and other specialized formats each serving distinct manufacturing requirements. Application demand spans automotive systems, aerospace and defense platforms, electronics and connector markets, oil and gas equipment, industrial machinery, and additional niche segments. Regional dynamics further reflect a diversified footprint, with North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each contributing to demand patterns shaped by local industrial priorities and supply chain architectures.
Market concentration remains moderately fragmented, with the top three players holding approximately 38 percent share and the top five reaching 45 percent. This structure indicates that while established producers maintain strong positions, there is meaningful room for differentiated strategies, regional specialization, and technology-led competition. Understanding the current landscape requires looking beyond headline figures to the underlying forces reshaping how beryllium copper is sourced, engineered, and deployed.
PW Consulting
1. Market Context and Core Challenges
A Market at an Inflection Point
The beryllium copper market is navigating a period where growth momentum intersects with structural tensions. The consistent revenue expansion from 2020 through 2025 reflects durable demand, yet several challenges define the current operating environment and will influence how companies capture value over the next several years.
One of the most significant challenges lies in balancing performance expectations with processing complexity. Beryllium copper alloys deliver exceptional strength, conductivity, and fatigue resistance, but realizing these properties requires controlled fabrication, precise heat treatment, and specialized handling. For manufacturers, this creates a trade-off between material performance and production efficiency. The need for in-house processing capabilities, skilled technical support, and consistent quality control can constrain adoption in applications where lead time, cost sensitivity, or fabrication flexibility are paramount. This dynamic is particularly relevant as downstream industries increasingly seek pre-engineered solutions that reduce processing burden while preserving alloy performance.
A second challenge involves supply chain concentration and raw material visibility. Beryllium is a relatively scarce material with specialized sourcing pathways, and apparent consumption levels underscore the niche but essential nature of the supply base. The materiality of beryllium within the broader copper alloy ecosystem means that any disruption in ore supply, refining capacity, or logistics can reverberate through downstream product availability. At the same time, the strategic importance of beryllium copper in defense, aerospace, and high-reliability electronics has elevated supply assurance from a procurement concern to a resilience priority. This shift is reshaping how producers and end users think about inventory, vertical integration, and long-term supply commitments.
A third challenge emerges from the regulatory and compliance landscape. While beryllium copper benefits from a comparatively favorable regulatory status in major markets, the broader industrial environment is characterized by increasing scrutiny of materials, substances, and manufacturing practices. Companies must navigate differing regional frameworks, maintain documentation, and ensure that product claims align with evolving standards. The presence of regulatory certainty in some jurisdictions does not eliminate the operational burden of compliance management, especially for organizations operating across multiple markets or serving customers with strict material specifications.
These challenges do not undermine the market's growth outlook. Instead, they highlight where strategic differentiation is possible. Producers and suppliers that can reduce processing friction, strengthen supply assurance, and streamline compliance navigation are well positioned to capture share in a market where performance and reliability remain non-negotiable.
Worldwide Beryllium Copper Probe Tips Market
2. Key Demand Drivers and Structural Forces
Innovation in Alloys and Pre-Engineered Solutions
Technological innovation continues to be a primary driver of market evolution, particularly in the direction of alloys and product formats that simplify downstream manufacturing. The push toward pre-engineered strip alloys optimized for stamping and forming reflects a broader industry preference for reducing cycle time, minimizing in-house processing, and accelerating time to market. This trend is especially relevant for connector OEMs and precision component manufacturers, where form complexity, tolerance requirements, and production throughput directly affect competitiveness.
The introduction of product lines that bring engineered characteristics closer to the point of fabrication represents a meaningful shift in value creation. Rather than selling only standard alloy formats, producers are increasingly offering solutions that embed processing guidance, consistency, and performance predictability into the material itself. This approach addresses a practical pain point: customers want the mechanical and electrical advantages of beryllium copper without shouldering the full burden of secondary processing. As a result, innovation is not only about composition but also about how alloys are delivered, supported, and integrated into customer workflows.
In parallel, advances in casting, forging, and precision fabrication expand the range of applications that can leverage beryllium copper's properties. Components requiring high strength-to-weight ratios, corrosion resistance, and reliable contact performance benefit from these capabilities. The combination of alloy development and manufacturing refinement creates a feedback loop: improved material formats enable new design possibilities, which in turn stimulate demand in sectors where performance margins are tight.
Policy and Regulatory Environment as a Stabilizing Force
Policy and regulatory dynamics are shaping the market in ways that are more stabilizing than restrictive. Beryllium copper's classification as a critical material in certain jurisdictions reinforces its strategic significance and supports attention to supply continuity. At the same time, regulatory assessments in major markets have generally not recommended broad restrictions on beryllium in commercial alloys, helping preserve the material's role in electronics, industrial equipment, and other applications.
This regulatory context matters because it influences purchasing confidence. When manufacturers and procurement teams evaluate materials for long-lifecycle products, regulatory clarity reduces uncertainty. For beryllium copper, the combination of critical material recognition and the absence of restrictive recommendations in key regulatory reviews supports continued use in high-reliability applications. It also encourages producers to maintain documentation, compliance alignment, and transparent communication with customers who need to validate material suitability across different standards regimes.
Trade and tariff conditions further influence market accessibility. Favorable tariff treatment under normal trade relations for certain imports can reduce cost friction and support cross-border supply of beryllium copper products. While trade policy can shift, the current environment illustrates how regulatory and trade frameworks can either facilitate or constrain market flow. Producers with diversified manufacturing footprints and distribution networks are better equipped to adapt to changes in trade conditions while preserving supply reliability.
Demand-Side Shifts in Automotive, Electronics, Aerospace, and Industrial Sectors
Demand-side behavior is changing as end-use industries pursue higher performance in more compact and energy-efficient designs. In electronics and connector markets, the drive toward miniaturization, higher contact reliability, and durability under repeated cycling favors materials that combine strength with conductivity. Beryllium copper's properties align with these requirements, making it relevant for applications where failure is costly and performance consistency is essential.
In automotive and aerospace contexts, the emphasis on weight reduction, durability, and system reliability continues to support demand for advanced alloys. Components exposed to mechanical stress, thermal cycling, or demanding service conditions can benefit from beryllium copper's engineering characteristics. The defense and aerospace supply chain, in particular, places a premium on material assurance and long-term availability, which strengthens the role of established producers with vertically integrated or strategically managed beryllium sourcing.
Industrial machinery and oil and gas applications also contribute to demand, especially where wear resistance, corrosion performance, and operational reliability are priorities. These sectors often operate with long equipment lifecycles and strict procurement standards, meaning that material selection decisions are less about short-term cost and more about total cost of ownership and risk mitigation. As a result, demand in these segments tends to be stable and less sensitive to minor price fluctuations, provided that product quality and supply consistency are maintained.
A notable shift in demand-side behavior is the growing expectation for supplier partnership. Customers increasingly look for technical support, application guidance, and responsive service rather than treating suppliers as transactional sources of material. This expectation elevates the importance of companies that can combine product availability with engineering insight and consistent quality.
Supply Chain and Cost Structure Dynamics
Supply chain and cost dynamics remain central to market competitiveness. Beryllium copper's value proposition is tied to both material performance and the efficiency with which it can be produced, distributed, and processed. Cost structures are influenced by raw material availability, manufacturing complexity, and the scale of production runs. Because beryllium is a specialized input, supply chain resilience depends on reliable sourcing, controlled processing, and effective inventory management.
Investments in capacity and supply assurance reflect the strategic weight of these considerations. When defense and industrial priorities increase the need for replenished inventory and expanded capability, producers that can respond with targeted capacity investments gain a competitive edge. Such investments are not only about volume; they also signal reliability to customers who depend on continuous supply for mission-critical programs. This dynamic reinforces the importance of vertical integration, strategic procurement, and long-term planning in a market where shortages or delays can have outsized consequences.
At the same time, cost pressures in downstream manufacturing encourage innovation in product formats that reduce processing steps. Pre-engineered strip and rod products that simplify forming and stamping can lower total production cost for customers, even if the base material carries a premium relative to less specialized alternatives. In this sense, the cost conversation is increasingly about total system cost and productivity rather than material price alone.
3. Competitive Landscape and Leading Strategies
Established Leaders and Strategic Positioning
The competitive landscape features a mix of vertically integrated producers, specialty manufacturers, and distributors that serve distinct segments of the market. Leading companies differentiate themselves through combinations of material expertise, product breadth, regulatory alignment, and supply chain reliability. While share concentration is moderate, the market rewards companies that can combine technical capability with consistent delivery and application support.
Materion Corporation stands out for its vertically integrated beryllium supply from U.S. bertrandite ore and its broad portfolio of high-strength copper-beryllium alloys. Its product range includes well-known alloy families and specialty series used in aerospace, defense, connectors, and industrial applications. The company's recent capacity expansion supported by a major defense prime contractor underscores the strategic importance of supply assurance in high-priority programs. The launch of pre-engineered strip alloys for stamping and forming further illustrates a strategy centered on reducing customer processing burden and accelerating time to market. This dual emphasis on supply resilience and product engineering positions Materion as a comprehensive solutions provider rather than a commodity supplier.
Worldwide Copper-beryllium Alloys Market
NGK Metals Corporation, known for its Berylco-branded alloys, maintains a strong global presence with production capability in Japan, the United States, and Europe. Its focus on precision strip, rod, sheet, and ingot products serves electronics, telecommunications, and high-reliability industrial markets. ISO-certified operations and a commitment to regulatory compliance across multiple frameworks reinforce its positioning as a dependable supplier for customers who require consistent quality and documentation. The company's long-standing brand recognition in beryllium-copper alloys contributes to trust in applications where material provenance and specification compliance matter.
IBC Advanced Alloys Corp. concentrates on castings, forgings, and plates for the aerospace supply chain, precision connectors, and defense contractors. This focus on engineered forms and mission-relevant customers reflects a strategy aligned with high-specification demand. Belmont Metals Inc. operates as a specialty metals distributor with technical support across aerospace, electronics, and industrial sectors, emphasizing accessibility and application assistance for standard-format alloys.
European players such as Wieland-Werke AG and AMPCO METAL S.A. contribute regional depth and industrial application expertise. Wieland's role as a European producer and supplier of beryllium-copper alloys and semi-finished products supports industrial customers seeking regional supply and technical compatibility. AMPCO METAL's focus on high-performance industrial uses, combined with European manufacturing and distribution, adds another layer of regional capability. These companies illustrate how geographic presence and application specialization can support competitive differentiation even in a globally connected market.
Japanese manufacturer Mitsubishi Materials Corporation and U.S.-based specialty suppliers such as Aviva Metals Inc., CDA Metals, and Smiths Metal Centres Limited further broaden the competitive field. Mitsubishi Materials serves electronics, telecommunications, and industrial applications, while the distributor and fabricator segment provides accessibility, standard formats, and technical support to downstream customers. Together, these players show that the market is served not only by large integrated producers but also by specialized distributors and fabricators that enable adoption through service, flexibility, and regional proximity.
Market Evolution: Integration, Differentiation, and Entry Points
The competitive landscape is evolving along several lines. Vertical integration remains a powerful advantage where beryllium sourcing and alloy production are closely linked, particularly for customers in defense and aerospace who value supply continuity. At the same time, product-level differentiation is becoming increasingly important. Companies that offer pre-engineered formats, application-specific guidance, and reduced processing complexity are creating value beyond traditional alloy supply.
The market also shows signs of regional specialization. Producers with manufacturing and distribution footprints in multiple regions can better serve local customer requirements, adapt to trade conditions, and provide responsive technical support. This regional dimension matters as customers increasingly weigh supply resilience alongside material performance.
New entry or expansion is challenging but not impossible, especially for companies that can bring a clear differentiator. The barrier is not only technical; it is also commercial. Success often depends on building trust with high-specification customers, maintaining compliance documentation, and offering the combination of product consistency and service that downstream manufacturers expect. As a result, the market is likely to see continued emphasis on strengthening existing positions, deepening application relationships, and expanding capabilities in high-priority segments rather than broad-based commoditization.
4. Forward Outlook: Trends and Commercial Implications
Trend 1: Rising Demand for Pre-Engineered and Processing-Optimized Alloys
Over the next three to five years, demand is expected to increasingly favor alloys and product formats that reduce downstream processing effort. Connector manufacturers, electronics producers, and precision component makers are likely to seek materials that combine performance with ease of fabrication. This trend creates opportunities for suppliers that can deliver engineered strip, rod, and sheet products with consistent characteristics and clear processing support. Commercially, it shifts competition toward value-added solutions rather than base material pricing alone.
For businesses, the implication is clear: the ability to shorten production cycles, reduce scrap, and simplify fabrication will become a stronger purchasing criterion. Companies that invest in product formats aligned with these priorities can capture preference in segments where time to market and manufacturing efficiency are critical.
Trend 2: Supply Assurance as a Strategic Procurement Priority
Supply assurance is likely to remain a defining theme, particularly in defense, aerospace, and high-reliability industrial applications. As customers place greater weight on continuity of supply and inventory resilience, producers with integrated sourcing, expanded capacity, and long-term commitments will be better positioned to win and retain strategic contracts. Investments tied to replenishment and capability expansion reflect this priority and are likely to influence purchasing decisions.
The commercial opportunity lies in building supply relationships that go beyond transactional procurement. Customers may be willing to align with suppliers that can demonstrate reliability, transparency, and the ability to scale with program needs. In this environment, supply chain credibility becomes a competitive asset.
Trend 3: Regulatory Clarity Supporting Continued Adoption in Key Applications
The regulatory environment is expected to continue supporting beryllium copper's role in major applications, provided that compliance documentation and material stewardship remain robust. Regulatory assessments that do not recommend broad restrictions, combined with critical material recognition in some jurisdictions, create a favorable backdrop for sustained adoption. This does not eliminate the need for compliance management, but it reduces the risk of disruptive restrictions that could otherwise reshape material selection.
For commercial strategy, the implication is to maintain strong documentation practices, stay aligned with regional requirements, and communicate compliance status clearly to customers. In sectors where material qualification cycles are long, regulatory consistency can be a meaningful advantage.
Risks and Uncertainties
Despite positive fundamentals, several uncertainties warrant attention. Raw material availability and pricing can affect cost structures and supply confidence, especially if consumption patterns shift or sourcing challenges arise. Trade policy changes could alter tariff conditions and cross-border supply dynamics, influencing competitiveness in specific regions. In addition, downstream demand can be sensitive to broader industrial cycles, particularly in sectors such as electronics and industrial machinery where investment timing and production volumes fluctuate.
Another source of uncertainty is the pace of product format adoption. While pre-engineered and processing-optimized solutions offer clear benefits, adoption depends on customer readiness, existing fabrication capabilities, and the cost calculus of changing supply chains. Companies should monitor where adoption accelerates and where traditional formats remain preferred, as this will shape demand patterns across product types.
5. Strategic Considerations for Decision Makers
For Manufacturers and Fabricators
Manufacturers should evaluate how beryllium copper product formats align with production efficiency and application requirements. Where possible, explore pre-engineered strip, rod, and plate solutions that reduce in-house processing and shorten lead times. Building closer technical collaboration with suppliers can improve yield, consistency, and time to market, especially for complex stampings, precision connectors, and high-reliability components. It is also advisable to review supply contingency planning, particularly for programs where material availability directly affects delivery commitments.
For Investors and Strategic Planners
Investment decisions should account for the market's combination of steady growth, specialized supply dynamics, and increasing value placed on supply assurance. Capacity expansion tied to defense and high-reliability demand, along with product engineering that reduces processing burden, points to areas where competitive advantage can be strengthened. When assessing opportunities, consider not only volume growth but also the concentration of demand in high-value applications, the importance of regional supply footprints, and the role of compliance and documentation in customer selection. Diversification of supply and manufacturing presence can mitigate exposure to regional or trade-related disruptions.
For Procurement and Supply Chain Leaders
Procurement teams should prioritize suppliers that offer a balance of material performance, reliability, and technical support. In high-specification applications, qualification lead time, documentation quality, and supply continuity can be as important as unit price. Establishing multi-source strategies where feasible, maintaining visibility into inventory and capacity commitments, and aligning material choices with long-term regulatory and compliance expectations can reduce risk. For programs with extended lifecycles, early coordination with suppliers on specification, availability, and processing requirements can prevent downstream delays.
Closing Perspective
The beryllium copper market is advancing through a combination of steady demand growth, product-level innovation, and heightened attention to supply resilience and regulatory alignment. The trajectory from 2020 to 2032 reflects more than incremental expansion; it points to a market where performance, reliability, and processing efficiency increasingly determine competitive success. For organizations operating in or adjacent to this market, the strategic imperative is to look beyond base material characteristics and evaluate how alloys are engineered, supplied, and supported across the value chain.
As demand becomes more application-specific and supply assurance gains strategic weight, detailed segmentation data, regional demand patterns, and company-level capability assessments become essential for precise planning. For decision makers seeking a deeper operational view, including granular segmentation, competitive benchmarking, and customized scenario analysis, the full PW Consulting market research report provides expanded data and tailored guidance to support more targeted strategy development.
For detailed analysis of this topic, please visit the official page: Beryllium Copper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Reciprocating Saw Blades Market: Metal Processing Leads 58% Share as CAGR Hits 5.85% Through 2032
By pmarketresearch, 2026-09-21
The Reciprocating Saw Blades Market: Strategic Trends and Commercial Opportunities Through 2032
The reciprocating saw blades market is entering a phase defined by steady expansion, material science innovation, and shifting demand patterns across industrial and professional trade sectors. Valued at approximately 95.5 million USD in 2020, the market reached an estimated 123.4 million USD in 2025, reflecting a compound annual growth rate of roughly 5.85 percent through the 2020-2025 period. Forward projections indicate continued momentum through 2032, with revenue expected to approach 186.3 million USD by the end of the forecast horizon. Growth is not uniform across segments, nor is it immune to cost pressures and competitive dynamics. For executives and investors, the market presents a mix of incremental volume gains, margin compression risks, and opportunities tied to product differentiation and application-specific engineering.
Market Landscape and Core Challenges
The base-year valuation of 123.4 million USD in 2025 places the market in a mid-tier industrial consumables category, characterized by fragmented supply, application-driven purchasing, and a meaningful share of replacement-driven demand. Market concentration remains moderate, with the top three players holding roughly 28.5 percent of revenue and the top five accounting for approximately 35.8 percent. This structure leaves room for regional specialists, tool-brand ecosystems, and value-oriented suppliers to compete on price, compatibility, or application expertise. Segment leadership is distributed across material types, with carbon steel blades commanding the largest share, followed closely by bi-metal designs, high-speed steel variants, and a smaller remainder of specialty or alternative materials. Application-wise, metal processing represents the dominant end-use, construction materials processing holds a substantial portion, wood processing contributes a meaningful share, and other applications round out the remainder. Regionally, Asia Pacific accounts for the largest revenue share, North America follows with a strong professional and contractor base, Europe maintains a mature but segmented demand profile, Latin America represents a smaller but growing market, and the Middle East and Africa comprise a modest share with region-specific procurement patterns.
Three structural challenges are reshaping how participants compete and where margins are expected to settle over the next several years.
- Raw material cost volatility is pressuring both premium and value segments. High-speed steel and carbide raw material pricing variations continue to influence production costs for industrial blade manufacturers, while premium carbide tips in reciprocating saw blades have shown year-over-year cost increases of roughly 15 to 20 percent driven by supply chain dynamics. This creates a difficult balance between maintaining performance credentials and protecting unit economics, especially for suppliers serving price-sensitive channels.
- Labor constraints are changing purchasing criteria on the demand side. Professional contractors report increasing demand for longer-life blades due to labor shortages in the trades. When skilled labor is scarce, downtime and blade change frequency become more costly, pushing buyers to prioritize durability, consistency, and reduced rework over lowest unit price. This shift rewards products that demonstrably reduce total cost of ownership, even if their sticker price is higher.
- Regulatory and safety expectations are reinforcing specification discipline. Industrial safety standards for tool use in construction and manufacturing continue to emphasize proper blade selection and handling. As compliance and site-safety expectations tighten, procurement teams increasingly require documentation, application matching, and consistent product quality, which raises the bar for suppliers that rely on generalized or loosely specified offerings.
Key Drivers Shaping the Market
Growth in the reciprocating saw blades market is being propelled by four interacting forces: material and design innovation, regulatory and safety pressures, demand-side behavior shifts, and supply chain and cost-structure dynamics. Each force has distinct implications for product roadmaps, channel strategy, and go-to-market positioning.
Technology and Material Innovation as a differentiator
Advancements in blade construction are moving the market beyond generic commodity blades toward application-optimized, longer-life solutions. Bi-metal blades incorporate high-performance edges electron-beam welded to high-strength steel backers, delivering multiple times the life of standard designs in demanding applications. Such engineering matters because reciprocating saws are used across demolition, metal cutting, pruning, and general-purpose tasks, each imposing different wear patterns and load conditions. Premium coatings and carbide-tipped technologies further extend service life and improve cutting efficiency across wood, metal, plastic, and mixed-material environments. The practical effect is a widening performance gap between top-tier offerings and entry-level alternatives, which creates commercial headroom for brands that can back up performance claims with consistent quality and clear application guidance.
Regulatory and safety standards reinforcing specification discipline
The continued emphasis on proper blade selection and handling in construction and manufacturing reinforces a market where compatibility, documentation, and reliability matter more than ever. For manufacturers, this means that product naming, packaging, and technical guidance are not cosmetic details; they are part of the value proposition. Blades that clearly communicate intended material use, tooth geometry rationale, and handling considerations reduce misuse risk and align with procurement teams seeking to standardize across crews and subcontractors. For distributors and large buyers, safety-driven standardization can increase repeat purchase consistency and reduce SKU proliferation, favoring suppliers with well-organized application matrices and clear replacement pathways.
PW Consulting
Demand-side behavior shifts in professional and industrial channels
Demand is being reshaped by the same labor pressures affecting many trades. As skilled workers become harder to recruit and retain, project owners and contractors are more willing to invest in tools and consumables that reduce time per cut, minimize blade changes, and lower the risk of blade failure during critical tasks. This behavior extends beyond professional contractors into industrial settings, where metal processing and construction materials processing demand higher throughput with fewer interruptions. In parallel, cordless and corded power tool ecosystems are increasingly influencing blade purchases. Buyers frequently seek blades labeled as compatible with their existing saw platforms, which rewards manufacturers that align product lines with popular tool brands and provide clear cross-compatibility. As a result, the market is seeing more emphasis on ecosystem fit, not just blade performance in isolation.
Supply chain and cost-structure dynamics
Cost structures remain sensitive to raw material pricing, particularly for high-speed steel and carbide inputs, which influence the economics of premium blade production. At the same time, value-oriented manufacturing capacity has expanded in global markets, offering competitive-priced options for distribution and professional use. This dual dynamic creates a bifurcated environment: premium suppliers compete on durability, coating technology, and application-specific performance, while lower-cost producers compete on price, broad compatibility, and distribution reach. The strategic question is how each participant manages the trade-off between margin protection and volume capture. Suppliers that can segment their offerings clearly, control variant complexity, and align pricing with demonstrated performance tend to navigate raw material swings more effectively than those forced into undifferentiated price competition.
Competitive Landscape and Leading Strategies
The market features a broad set of participants spanning American and European tool manufacturers, Japanese industrial brands, German engineering specialists, and value-focused suppliers with global distribution. Several names stand out for the way they position reciprocating saw blades within broader product ecosystems and application-specific value propositions.
The M.K. Morse Company emphasizes high-performance bi-metal and cobalt reciprocating saw blades, with product families designed for demolition, general purpose, and metal cutting. Its positioning centers on long blade life and American-made manufacturing, with updated guidance on matching blades to materials and applications. This focus on selection clarity is strategically important because it reduces buyer uncertainty and aligns with the safety and specification trends described earlier.
Worldwide Manual Hacksaw Blades Market
LENOX competes with professional reciprocating saw blades featuring advanced coatings and construction designed for extended life and faster cutting across wood, metal, and industrial applications. Its brand positioning leans toward professional users who value consistent performance and wear resistance, reinforcing a premium-professional lane in the market.
Diablo Tools distinguishes itself through carbide-tipped reciprocating saw blades that pair specialized coatings with high-density carbide for substantially longer life across wood, metal, plastic, and demolition applications. This approach targets the performance ceiling, appealing to users who want to minimize blade replacement frequency and maximize cut quality in mixed-material environments.
Milwaukee Tools integrates reciprocating saw blades into its professional tool ecosystem, offering models for pruning, metal cutting, and demolition with advanced tooth designs. The brand has continued to expand its blade lineup with new models across multiple sizes and price points, reinforcing a strategy that ties consumables to platform loyalty and professional contractor relationships.
DeWalt and Makita similarly embed blade offerings within broader power tool ecosystems, with DeWalt focusing on professional-grade blades integrated across its tool lines and Makita supplying blades compatible with its cordless and corded ranges for industrial and professional use. Bosch Power Tools and Metabo extend this pattern in professional demolition and heavy-duty settings, with Bosch emphasizing high-performance blades for demolition and metal cutting and Metabo offering blades for heavy-duty and general-purpose metal and wood cutting.
On the specialty and value side, Freud Tools provides carbide-tipped and bi-metal blades with advanced tooth geometry for precision wood, metal, and demolition cutting, while Wilh. Putsch GmbH & Co. KG concentrates on industrial-grade blades with a focus on durability and performance in metal cutting. Skil Tools addresses consumer and light-duty professional applications with more affordable options. In global value segments, KWCT and Greatstar provide competitively priced blades for wide distribution and professional use, and Moretop Tools builds its identity around coated reciprocating saw blades with advanced coatings for demanding cuts. Distributors and specialty suppliers such as HUB Industrial Supply and Brock Supply add another layer, with HUB focusing on precision industrial and manufacturing applications and Brock Supply emphasizing premium bi-metal blades with cobalt content for heavy-duty use. Disston rounds out the list with durable bi-metal blades for professional and industrial use.
Several strategic patterns emerge from this landscape. First, ecosystem alignment is a powerful differentiator. Brands that connect blade offerings to popular saw platforms and professional tool lines reduce switching friction and create natural repeat-purchase behavior. Second, application clarity is increasingly decisive. Suppliers that publish clear guidance on blade selection for specific materials and applications help buyers standardize and reduce risk, which strengthens procurement relationships. Third, the premium-versus-value divide is widening. Carbide-tipped and advanced-coated designs push the upper end of performance and life, while competitive-priced models serve broader distribution and price-sensitive channels. The result is a market where segmentation discipline matters more than ever.
Market structure is likely to continue evolving along two axes. On one side, consolidation pressures may intensify among mid-tier players seeking scale in distribution, raw material procurement, and application development. On the other, niche differentiation will remain viable for suppliers that can demonstrate measurable advantages in life, cut quality, or compatibility for specific end-uses. New entrants and regional suppliers can still gain traction by targeting underserved applications, offering well-defined compatibility with popular saw systems, or providing strong technical support and selection guidance. The key is not to compete on every front, but to own a defensible position in a clearly defined segment.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define how the reciprocating saw blades market grows and where value is captured.
- Application-specific engineering will move from a premium feature to a baseline expectation in higher-value segments. As buyers become more familiar with blade construction differences and more sensitive to downtime, demand will increasingly favor products designed for distinct material families and use cases rather than generic one-blade-fits-many approaches. Commercial opportunity lies in developing clear application families, simplifying SKU decision-making for distributors and large buyers, and pairing product lines with selection tools and guidance.
- Long-life consumables will gain share as labor scarcity and project scheduling pressures persist. Contractors and industrial operators are likely to keep prioritizing blades that reduce change frequency and maintain consistent performance over time. The opportunity here is not simply to market durability claims, but to quantify total cost of ownership in terms that procurement teams can act on, such as cuts per blade, replacement intervals, and reliability under defined conditions.
- Ecosystem and compatibility strategy will remain central to repeat purchase behavior. Suppliers that align blade lines with widely used saw platforms and communicate compatibility clearly are better positioned to capture recurring demand. This creates openings for tool brands to deepen consumables attach rates, and for independent blade suppliers to strengthen cross-compatibility messaging where it is credible and consistent.
- Cost-structure management will separate resilient suppliers from those exposed to raw material volatility. With carbide and high-speed steel pricing subject to fluctuations, companies that diversify material options, segment product tiers by performance and price, and control variant complexity are better placed to protect margins without sacrificing relevance. This also opens the door for hybrid strategies that pair premium coated or carbide-tipped lines with value-oriented bi-metal or carbon steel options, depending on channel and application needs.
These trends carry risk and uncertainty. Raw material pricing can compress margins if not managed through pricing strategy, product tiering, or sourcing flexibility. Demand may shift faster in some regions than others, particularly where construction activity, metal processing investment, or contractor labor markets diverge. Competition from value-oriented suppliers may intensify in price-sensitive channels, pressuring undifferentiated premium products. And regulatory or safety expectations can change the pace at which buyers adopt new specifications, especially in larger industrial accounts with formal procurement and compliance processes. Participants that monitor these signals and adjust segmentation, pricing, and application support accordingly will be better positioned to capture growth without racing into margin-eroding competition.
Actionable Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the board.
For manufacturers and suppliers, the most valuable moves are to sharpen segmentation, protect margin through clear tier architecture, and invest in application guidance that reduces buyer uncertainty. Build product lines around well-defined material and use-case families rather than broad, overlapping SKUs. Where advanced coatings or carbide-tipped designs justify premium positioning, ensure that performance claims are supported by consistent quality and clear handling guidance. At the same time, maintain credible value tiers for channels where price sensitivity and broad compatibility matter more than maximum life. Pricing strategy should reflect raw material volatility without forcing an all-or-nothing response, and variant complexity should be managed so that inventory, distribution, and customer support remain efficient.
For investors, the market rewards participants that combine ecosystem alignment, application clarity, and disciplined cost management. Look for companies with defensible positions in professional or industrial channels, strong repeat-purchase dynamics through tool-platform compatibility or specification standardization, and the ability to segment premium and value offerings without diluting brand identity. Pay attention to how suppliers are responding to labor-driven demand for longer-life blades and whether they can quantify total cost of ownership in a way that resonates with procurement teams. Monitor raw material exposure and the flexibility of product tiers, since these will influence margin stability as input costs move. Entry and expansion opportunities may exist for suppliers that can serve underserved application niches, strengthen compatibility messaging, or improve technical support and selection guidance in fragmented regional markets.
Circular Saw Blades Market
For procurement leaders and industrial buyers, the priority is to standardize on blades that match real application requirements and to evaluate total cost of ownership rather than unit price alone. Where labor constraints or project schedules make downtime costly, prioritize blade life, consistency, and compatibility with the saw platforms in use. Use selection guidance and application matching to reduce misuse risk and to align purchasing across crews and subcontractors. Develop specifications that reflect safety expectations and material conditions, and review supplier support and documentation as part of the evaluation, since these factors influence correct use and predictable performance over time.
Detailed segmentation data, regional dynamics, application-specific sizing, and competitive benchmarks can sharpen these decisions further. For teams that need granular breakdowns across type, application, and region, or that want customized scenarios for pricing, product tiering, and channel strategy, the full market study provides expanded data sets and actionable frameworks tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Reciprocating Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Knife Gate Valves Market: Why 5.8% CAGR and Wastewater Demand Change Everything
By pmarketresearch, 2026-09-21
Knife Gate Valves Market: Strategic Shifts and Commercial Opportunities Through 2032
1. Market Trajectory and Defining Challenges
The global knife gate valves market has demonstrated consistent growth over the past five years, expanding from approximately $163 million in 2020 to an estimated $215 million in 2025. This trajectory reflects a compound annual growth rate of 5.8 percent, with projections indicating the market will surpass $320 million by 2032. The steady upward movement underscores the critical role of knife gate valves in handling slurries, abrasive media, and viscous fluids across heavy industry and municipal infrastructure. While the growth profile appears linear at first glance, a closer examination reveals underlying structural shifts that are reshaping competitive dynamics, pricing models, and end-user procurement behavior.
Elastic Sealing Gate Valve Market
Three key challenges are currently defining the industry's transition point. First, the sector is navigating mounting pressure from raw material cost volatility. Global stainless steel prices rose by 12 to 15 percent from 2024 to 2025, directly contributing to an 8 to 10 percent increase in the purchase price of valve products manufactured in China and other major production hubs. This input cost escalation is compressing margins for fabricators and forcing end-users to reconsider total cost of ownership calculations rather than focusing solely on upfront procurement expenses.
Second, compliance and standardization requirements are becoming more stringent. Knife gate valves deployed in severe service applications must now align with ASME Class 150 and 300 flange pressure ratings and meet MSS SP-135 specifications. Separately, stainless steel, bonnetless, flanged configurations are expected to conform to MSS SP-81 standards. These regulatory expectations are not merely technical checkpoints; they are reshaping qualification processes, extending lead times, and raising the barrier to entry for manufacturers without robust engineering documentation and testing capabilities.
Third, the industry is contending with persistent labor shortages in manufacturing. The scarcity of skilled fabricators and installation technicians is driving up costs for specialized valve production, particularly in slurry and wastewater applications where precision fitting and field adjustment remain labor-intensive. This workforce constraint is accelerating interest in modular designs, pre-assembled components, and automated actuation solutions that reduce on-site installation complexity.
PW Consulting
2. Core Drivers Reshaping the Market
Technological Innovation and Actuation Evolution
The shift toward automated and semi-automated valve actuation is one of the most consequential technology trends in the knife gate valves sector. Pneumatic configurations have historically dominated the product mix, reflecting their reliability in harsh environments and compatibility with existing plant control systems. However, electric actuation is gaining traction as industrial users seek tighter process control, reduced maintenance overhead, and integration with remote monitoring platforms. This transition is not simply a component swap; it represents a broader move toward valves as intelligent nodes within larger process ecosystems. Manufacturers that offer integrated actuation options, configuration software, and compatibility with supervisory control systems are positioning themselves for longer-term service relationships rather than one-time equipment sales.
Engineering advancements in valve body design and lining materials are also expanding the operational envelope of knife gate valves. Companies are introducing extended service models, bi-directional configurations, metal-cutting variants, and urethane-lined options that address abrasive wear, bidirectional flow requirements, and severe service conditions. These product developments are enabling end-users to standardize on fewer valve models across broader operating ranges, simplifying inventory management and reducing spare parts complexity.
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst. Environmental mandates around wastewater collection, stormwater management, and industrial effluent treatment are driving sustained capital investment in municipal and industrial piping systems. At the same time, the expectation that knife gate valves meet recognized pressure ratings and severe service standards is elevating the importance of certified product documentation. Procurement teams are increasingly requiring evidence of compliance with MSS SP-135, MSS SP-81, and related ASME flange classifications before awarding contracts. This regulatory emphasis favors established manufacturers with demonstrated testing records and clear traceability, while creating headwinds for lower-cost entrants that cannot readily substantiate performance claims.
In parallel, sustainability and durability expectations are influencing specification decisions. Operators are prioritizing valves that reduce fugitive emissions, withstand abrasive media without frequent replacement, and minimize downtime during maintenance windows. These priorities align with broader infrastructure modernization goals, particularly in regions where aging collection systems and process piping are being upgraded to improve reliability and reduce lifecycle costs.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by the relative growth trajectories of key application sectors. Wastewater treatment continues to represent a substantial demand center, reflecting ongoing investment in collection systems, stormwater infrastructure, and municipal treatment capacity. The pulp and paper industry remains a core application area, particularly where slurries, chemical recovery streams, and fiber suspensions require reliable isolation and flow control. Oil and gas operations also contribute meaningful volume, especially in regions where slurry handling and heavy media movement are integral to processing and extraction workflows.
Mining represents another significant demand segment, driven by the need to manage abrasive slurries, tailings, and mineral processing streams under demanding operating conditions. Power generation, while smaller in relative terms, provides steady demand for valves that can handle fly ash, biomass feedstocks, and other particulate-laden flows. Across these sectors, the common thread is a growing preference for valve solutions that combine severe service durability with operational flexibility, rather than simply meeting minimum functional requirements.
Supply Chain and Cost Structure Dynamics
The cost structure of knife gate valve production is being reshaped by the interplay of material pricing, labor availability, and geographic sourcing patterns. The increase in stainless steel prices has had a direct impact on valve pricing, particularly for manufacturers that rely on imported raw materials or produce in regions where input costs have risen sharply. This dynamic is prompting buyers to reevaluate supplier diversification strategies and consider nearshoring or dual-sourcing arrangements to mitigate price and supply continuity risks.
At the same time, the labor shortage in specialized fabrication is encouraging manufacturers to explore design simplifications, standardized sub-assemblies, and improved manufacturing workflows. Companies that can maintain quality while reducing labor intensity are better positioned to protect margins in an environment where both material and workforce costs are trending upward. For procurement organizations, this means that supplier selection is increasingly influenced by production resilience and process maturity, not just unit price.
3. Competitive Landscape and Leading Strategies
The knife gate valves market remains moderately concentrated, with the top three players collectively holding approximately 35 percent of revenue and the top five reaching roughly 48 percent. This structure indicates a market where established manufacturers maintain meaningful share, but there is still room for differentiation through product specialization, application focus, and regional presence. The competitive environment is not defined by a single dominant strategy; rather, it reflects a range of positioning choices that align with each company's engineering heritage, manufacturing capabilities, and target end markets.
Several leading manufacturers have built their market position around application-specific engineering and product breadth. Emerson, for example, has focused on Clarkson knife gate valves designed for heavy slurry service across mining, power, pulp and paper, and wastewater industries. This application-oriented approach allows the company to align its product line with the operational realities of high-abrasion and high-volume environments. Henry Pratt Company has differentiated through custom knife gate valves ranging from 2 inches to 96 inches and above, using carbon steel, stainless steels, and weldable alloys to meet specialized project requirements. DeZURIK has emphasized a broad portfolio that includes cast and fabricated options, with premier KGC extended service, bi-directional, metal cutting, KSV severe service, KUL urethane lined, and KSL slurry models. This breadth supports a strategy of matching specific valve configurations to distinct service conditions rather than offering a single generalized product.
Other manufacturers are competing through material specialization, actuation focus, or regional strength. ITT Engineered Valves offers the Fabri-Valve series, including C45 ductile iron, C67 bi-directional, and CF134 bonneted models, targeting users who need robust fabricated construction in demanding service. Orbinox has established a European manufacturing base with uni-directional, bi-directional, and wafer-style knife gate valves for industrial applications, giving it credibility in markets where European engineering standards and export networks carry weight. Red Valve Company has focused on Tideflex knife gate valves tailored for slurry and abrasive applications, emphasizing flexible element performance in challenging media conditions. Fabricast Valve has concentrated on pneumatic and manual knife gate valves, including large diameter models, serving customers who prioritize straightforward actuation options and wide size availability. Keckley Company produces low-pressure flanged and fabricated knife gate valves for pulp and paper, chemical, power, and mining applications, aligning its offering with sectors that require reliable low-pressure isolation. Hawle Armaturen has directed attention to wastewater networks and viscous fluids through the Erhard ERU K1 knife gate valve, reflecting a municipal and utility-oriented specialization.
The market is also showing signs of evolution in how companies engage with end-users and project ecosystems. Recent trade show participation highlights a continued emphasis on in-person technical engagement and direct showcase of valve capabilities. Elite Valve exhibited its complete range of engineered knife gate valves at the Valve World Calgary Conference & Expo in June 2026. DeZURIK attended the Design-Build for Water/Wastewater Conference in Dallas in April 2026 and the WEF Collection Systems and Stormwater Conference in Portland in July 2026, using these platforms to present knife gate valve solutions to water and wastewater professionals. These activities suggest that face-to-face technical marketing, project-focused demonstrations, and sector-specific conferences remain important channels for building specification awareness and supporting procurement decisions.
Looking ahead, the competitive landscape is likely to evolve along three dimensions. First, consolidation pressure may increase as larger valve and flow control groups seek to broaden their severe service portfolios through acquisition or strategic partnership. Second, segmentation is likely to deepen, with companies increasingly defining themselves by application niche, material capability, or actuation integration rather than competing solely on general-purpose product lines. Third, new entrants and regional manufacturers may continue to challenge incumbents in price-sensitive segments, particularly where standard configurations and shorter lead times are valued over highly specialized engineering. In response, established players are expected to reinforce their differentiation through compliance documentation, application engineering support, and long-term service relationships.
4. Forward Outlook: Trends and Opportunities to 2032
The next three to five years are likely to be shaped by three interconnected trends, each carrying distinct commercial implications.
Automation and digital integration will become baseline expectations rather than premium features. As pneumatic and electric actuation options mature and remote monitoring becomes more common in industrial and municipal settings, buyers will increasingly expect knife gate valves to support configuration flexibility, condition feedback, and integration with broader control architectures. This trend creates opportunities for manufacturers that can offer integrated actuation packages, predictable maintenance intervals, and compatibility with digital process platforms. It also raises the stakes for suppliers that remain focused only on mechanical valve hardware, since specification decisions may increasingly favor solutions that reduce operational uncertainty and simplify lifecycle management.
Severe service specification and compliance documentation will increasingly dictate winning vendor lists. The expectation that valves meet ASME flange ratings and MSS SP-135 or MSS SP-81 requirements is likely to intensify as project owners standardize procurement criteria and reduce discretion in vendor qualification. Companies that invest early in clear documentation, application-tested product lines, and reliable quality systems will be better positioned to secure specification shares in demanding sectors such as wastewater, mining, and pulp and paper. Conversely, price-driven sourcing without robust compliance support may face growing pushback in projects where failure risk or downtime costs are material.
Lifecycle economics will outweigh initial purchase price in more procurement decisions. The combination of rising stainless steel costs, labor constraints, and pressure to reduce maintenance disruption is pushing buyers toward a more total-cost-oriented evaluation. This shift favors product designs that extend service intervals, resist abrasive wear, simplify installation, and reduce the frequency of replacement. It also creates opportunities for manufacturers and distributors that can provide application guidance, configuration support, and service planning rather than transactional sales alone.
These trends intersect with meaningful commercial opportunities. Manufacturers can pursue growth by expanding actuation-integrated offerings, developing standardized severe service lines that reduce customization cost, and strengthening application-specific support for wastewater, mining, and pulp and paper projects. There is also potential in regional market expansion where infrastructure modernization and industrial processing investment are accelerating. For investors and strategic buyers, the market presents interest in companies with strong compliance credentials, application engineering depth, and the ability to serve both standard and severe service requirements without sacrificing margin. At the same time, uncertainty remains around raw material pricing trajectories, the pace of labor market normalization, and the degree to which end-users will consolidate procurement around fewer vendors or continue to diversify across multiple suppliers.
5. Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Prioritize application-specific differentiation over broad product proliferation. Knife gate valves are increasingly evaluated against service conditions, compliance expectations, and total cost of ownership, which means that clear positioning in severe service, wastewater, slurry, or custom-size applications can create more sustainable advantage than competing across too many generic configurations. Invest in documentation, testing, and engineering support that make it easier for specification engineers and procurement teams to justify selection during vendor qualification. At the same time, evaluate actuation integration and design simplification as margin-protection levers in an environment where material and labor costs are rising.
Butterfly Valves Market
For Investors and Strategic Buyers
Focus on companies with durable specification relationships, recognized compliance alignment, and the ability to serve demanding end markets without overreliance on price competition. Look for product portfolios that balance standard configurations with severe service capability, since this mix can support both volume stability and higher-margin project work. Assess whether the manufacturer's production model can withstand raw material volatility and labor constraints, and consider whether the business is positioned to benefit from infrastructure modernization, wastewater investment, and mining or pulp and paper process upgrades. Entry or expansion opportunities may be strongest where a supplier can pair technical credibility with regional reach and responsive project support.
For Procurement and Operations Leaders
Expand evaluation criteria beyond initial price to include compliance documentation, service durability, actuation integration, and installation complexity. In applications involving abrasive slurries, viscous fluids, or severe service conditions, the cost of downtime and premature replacement can outweigh modest savings on upfront procurement. Supplier diversification and dual-sourcing can also help manage exposure to material price swings and production bottlenecks. Where possible, standardize on valve models that have demonstrated alignment with relevant pressure ratings and service standards, while retaining flexibility for custom requirements on critical projects.
The knife gate valves market is moving from a period of steady expansion into a phase where technical differentiation, compliance readiness, and lifecycle value will play a larger role in determining commercial success. Companies that understand these shifts and act on them early will be better positioned to capture specification share, protect margins, and align with the next wave of infrastructure and industrial investment. For a more detailed view of segmentation dynamics, regional demand patterns, and customized strategic scenarios, the full PW Consulting market research report provides expanded data and decision-ready analysis across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Knife Gate Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Intravenous Solutions Market: Strategic Trends and Commercial Opportunities Through 2032
The intravenous solutions market has entered a phase of sustained expansion, driven by evolving clinical needs, regulatory interventions, and structural shifts in manufacturing and distribution. Valued at approximately 161 million USD in 2025, the market has demonstrated consistent growth from 2020 through 2025, and forward projections indicate a compound annual growth rate of 7.1 percent across the 2026 to 2032 forecast period. By the end of the decade, revenue trajectories point toward a market size exceeding 260 million USD. This growth is not merely a function of demographic expansion or incremental volume increases; it reflects deeper transformations in how intravenous therapies are formulated, delivered, reimbursed, and secured against supply chain volatility. For executives, investors, and procurement leaders, the market presents both operational complexities and strategic openings that demand forward-looking positioning.
Market Snapshot and Core Challenges
The revenue trajectory across the 2020 to 2025 historical window shows steady compounding, with growth accelerating in the latter years as clinical demand stabilized and supply constraints began to ease. The forecast period from 2026 to 2032 suggests a market that will continue to expand, though the pace and composition of growth will vary depending on regional adoption, product mix, and regulatory outcomes. While the market is broadly diversified across geographies and clinical applications, concentration remains a defining structural feature. The top three players account for roughly 48.6 percent of market share, and the top five collectively hold about 61.2 percent. This concentration signals an industry where scale, regulatory compliance, and manufacturing reliability confer meaningful advantages, yet it also leaves room for specialized entrants and regional players to capture niche demand.
Key Challenges and Inflection Points
Several structural challenges are reshaping how companies approach product development, capacity planning, and risk management. First, the industry continues to navigate the aftermath of supply disruptions that exposed fragilities in concentrated manufacturing footprints and single-source dependencies. Second, input cost pressures have persisted over the past two decades, with pharmaceutical ingredients and plastics used in solution production experiencing upward cost trends, further compounded by regulatory and quality maintenance requirements. These cost dynamics squeeze margins and force manufacturers to balance pricing strategies with volume commitments and long-term supply agreements. Third, reimbursement and billing frameworks create operational complexity, as intravenous administration sets and related components are billed under specific coding structures that influence hospital purchasing behavior and vendor contracting. Together, these factors point to an industry at an inflection point where resilience, regulatory agility, and cost discipline are becoming competitive differentiators.
Key Drivers Reshaping the Market
Technological Innovation and Formulation Advances
Innovation in intravenous solutions is moving beyond volume production toward formulation precision, material science improvements, and delivery compatibility. Manufacturers are increasingly focused on flexible container designs, non-PVC and non-DEHP alternatives, and multi-electrolyte formulations that better align with clinical requirements and patient safety considerations. These advances are not purely technical; they directly influence procurement decisions, as healthcare providers seek products that reduce compatibility risks, simplify storage and handling, and support broader therapeutic applications. The push toward smarter infusion compatibility and specialized formulations also creates opportunities for companies that can integrate product development with clinical workflow optimization, rather than competing solely on unit price.
Regulatory Environment and Policy Interventions
Regulatory actions have become a central force shaping market dynamics, particularly in response to supply shortages and quality concerns. Recent regulatory clearance resolved a nationwide shortage of sodium chloride 0.9 percent injection products, enabling removal of the product from the FDA Drug Shortages Database. This outcome was supported by a combination of temporary importation facilitation, expedited reviews to increase manufacturing capacity, and scientific assessments that extended shelf life for more than 50 intravenous and irrigation products. In parallel, temporary policies for compounding certain parenteral drug products were implemented to help fill gaps from manufacturing disruptions. These interventions demonstrate a regulatory environment willing to use flexibility and accelerated pathways to stabilize supply, but they also introduce uncertainty for manufacturers that must align production planning, expiry management, and compliance documentation with shifting policy windows.
Demand-Side Shifts in Clinical Care
Demand patterns are being reshaped by changes in hospital care models, outpatient transitions, and the growing use of nutritional support and fluid and electrolyte balance therapies across diverse patient populations. The increasing complexity of patient care, including longer stays for chronic conditions and greater reliance on parenteral nutrition in specialized settings, is expanding the addressable market beyond acute care volume alone. Providers are also prioritizing supply reliability and product consistency, which influences purchasing decisions and long-term contracting. As clinical protocols evolve and patient acuity profiles shift, demand is becoming more segmented, rewarding manufacturers that can tailor portfolios to specific care settings and therapeutic needs.
Supply Chain and Cost Structure Dynamics
The cost structure of intravenous solutions continues to be influenced by raw material trends, regulatory compliance costs, and logistics complexity. Pharmaceutical ingredients and plastics have experienced increasing costs over extended periods, and regulatory quality requirements add further operational expense. At the same time, reimbursement coding for administration sets creates a billing environment where procurement teams weigh total cost of ownership, compatibility, and supply continuity rather than focusing exclusively on per-unit pricing. These dynamics are encouraging manufacturers to invest in supply chain diversification, long-term supplier agreements, and production efficiency initiatives. For buyers, this environment underscores the importance of contractual flexibility and multi-source strategies to mitigate cost volatility and availability risk.
PW Consulting Health Care Research Center
Competitive Landscape and Leading Strategies
The market is anchored by a set of globally active manufacturers with distinct strategic positioning. Baxter International Inc., based in Deerfield, Illinois, remains a major producer of intravenous solutions, including sodium chloride 0.9 percent injection and multi-electrolyte formulations, with manufacturing capabilities across North America and international sites. Its scale and breadth of formulation options support a positioning centered on reliability, product range, and integration with broader hospital supply needs. Fresenius Kabi AG, headquartered in Bad Homburg vor der Höhe, Germany, provides a comprehensive IV fluids portfolio that includes freeflex bags, electrolyte solutions, and parenteral nutrition products. Its strategy emphasizes portfolio completeness and clinical alignment, appealing to procurement teams that value integrated product availability and consistent supply.
Intravenous Fluid Bags Market
B. Braun Melsungen AG, located in Melsungen, Germany, offers a broad portfolio of IV fluids, irrigation solutions, and smart infusion products with full supply availability. Its differentiation lies in combining fluid products with infusion technology and irrigation applications, creating cross-product value for clinical settings that seek operational efficiency across multiple use cases. ICU Medical, Inc., based in San Clemente, California, manufactures and distributes intravenous solutions in flexible containers, including non-PVC and non-DEHP alternatives, through a joint venture with Otsuka. This partnership structure gives ICU Medical access to specialized formulations and multi-site manufacturing flexibility, while allowing it to focus on material innovation and container design. Otsuka Pharmaceutical Co., Ltd., headquartered in Tokyo, Japan, supplies pediatric intravenous solutions and supports multi-site manufacturing for IV fluids under the same joint venture, bringing formulation expertise and a focus on specialized patient populations.
Strategic Positioning and Differentiation
Across these players, differentiation is increasingly defined by supply resilience, formulation specialization, and material science capabilities rather than price competition alone. Scale manufacturers leverage broad portfolios and international production footprints to support continuity of supply and large-volume contracts. Specialized and partnership-driven players compete on formulation alternatives, container technology, and targeted clinical segments such as pediatric care or non-PVC preferences. The strategic implication is clear: companies that can demonstrate both supply reliability and product-specific advantages are better positioned to secure long-term contracts and navigate regulatory or shortage-driven disruptions.
Market Evolution Trends
The competitive landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Concentration among leading players suggests that scale advantages will continue to matter, particularly in regulatory compliance, quality systems, and cost management. At the same time, the demand for specialized formulations and alternative materials creates openings for focused competitors and partnership models that can move faster in niche segments. New entrants may find opportunity not by matching the full breadth of incumbent portfolios, but by addressing specific pain points such as material safety, pediatric formulations, or regional supply gaps. Over time, the market is expected to remain concentrated at the top while becoming more differentiated in the middle and lower tiers, where agility and clinical alignment can compensate for smaller scale.
Future Trends and Commercial Opportunities
Supply Resilience as a Strategic Priority
Over the next three to five years, supply resilience is expected to move from an operational concern to a strategic differentiator. Regulatory actions have already demonstrated that shortage resolution can involve temporary importation, expedited reviews, expiry extensions, and compounding policy flexibility. Manufacturers that invest in diversified production capacity, multi-source ingredient procurement, and robust expiry and quality management will be better positioned to capture demand during periods of disruption. For commercial teams, resilience creates opportunities to strengthen contracts, build trust with procurement organizations, and command preference in procurement evaluations where continuity of supply is weighted heavily.
Formulation and Material Innovation Driving Segmentation
Innovation in formulations and container materials is likely to deepen market segmentation and create premium opportunities in specific clinical categories. Non-PVC and non-DEHP alternatives, multi-electrolyte solutions, and pediatric-focused formulations are examples of product areas where clinical preference and safety considerations can support differentiated positioning. Companies that align product development with evolving hospital protocols and patient safety priorities can build defensible niches, even in a market where overall growth is broad-based. The commercial opportunity lies in translating clinical advantages into procurement value, such as reduced handling complexity, improved compatibility, or lower risk of supply disruption for specialized therapies.
Reimbursement and Procurement Complexity Shaping Buying Behavior
Reimbursement and billing frameworks will continue to influence purchasing behavior, particularly where administration sets and solution components are billed under specific coding structures. This environment encourages buyers to evaluate total cost, compatibility, and supply reliability rather than focusing on isolated unit prices. For manufacturers and distributors, the implication is that value propositions must address procurement workflows, contracting flexibility, and integration with hospital cost management. Companies that can provide clear documentation, predictable availability, and compliant product structures will have an advantage in procurement negotiations, especially in settings where reimbursement constraints make cost predictability a priority.
Risks and Uncertainties
Despite the positive growth trajectory, several risks could alter market outcomes. Regulatory flexibility used to resolve shortages may shift as supply conditions improve, potentially changing the competitive dynamics that temporary policies created. Raw material cost pressures and quality maintenance requirements may continue to challenge margin stability, especially for manufacturers with limited pricing power or concentrated supplier exposure. In addition, reimbursement and coding frameworks can evolve in ways that affect purchasing patterns and product valuation. Finally, concentration in the market means that supply disruptions at a small number of major sites can have outsized effects, reinforcing the need for contingency planning and diversification. Companies that treat these risks as strategic variables rather than isolated operational issues will be better prepared to navigate uncertainty.
Actionable Recommendations for Decision Makers
For Manufacturers
Manufacturers should prioritize supply chain resilience and formulation differentiation as complementary growth levers. Diversifying production capacity and ingredient sourcing can reduce exposure to localized disruptions, while targeted innovation in materials and formulations can create preference in specific clinical segments. It is also important to align compliance and quality systems with the regulatory pathways that have recently been used to stabilize supply, including expiry management and compounding-related guidance, so that opportunities for shelf-life extension and policy-supported continuity can be captured efficiently. Pricing and contracting strategies should reflect total cost of ownership and supply reliability, not just per-unit economics, particularly when procurement teams weigh continuity and compatibility alongside price.
IV Bags Market
For Investors
Investors should focus on companies that demonstrate a credible combination of scale, regulatory agility, and product specialization. Market concentration suggests that incumbents with broad portfolios and international manufacturing footprints are well placed to benefit from demand growth and supply stabilization, but differentiation in materials, pediatric formulations, and flexible container technology can create valuable niches. When evaluating opportunities, it is important to assess exposure to raw material cost trends, reimbursement dynamics, and the ability to adapt to regulatory changes that affect expiry, importation, and compounding. Companies with clear contingency planning and diversified supply chains are likely to offer more durable value in an environment where disruption risk remains a central market factor.
For Procurement and Supply Chain Leaders
Procurement leaders should treat intravenous solution sourcing as a resilience and total-cost decision rather than a purely transactional purchase. Multi-source strategies, contractual flexibility around volume and expiry, and clear evaluation criteria for material safety and compatibility can reduce vulnerability to shortage-driven pricing and availability swings. It is also valuable to engage suppliers on continuity planning, quality documentation, and regulatory compliance, given the recent emphasis on expiry extensions and temporary importation pathways. By aligning procurement criteria with clinical priorities and supply risk management, organizations can improve both cost predictability and patient care continuity.
The intravenous solutions market is entering a period where growth, regulation, and supply resilience intersect in ways that reward strategic foresight. Companies and investors that understand the interplay between formulation innovation, regulatory dynamics, and procurement behavior will be better positioned to capture opportunity while managing risk. For decision makers seeking deeper segmentation data, regional nuance, and customized strategic guidance, the full research report provides detailed breakdowns and scenario-based analysis to support more precise planning.
For detailed analysis of this topic, please visit the official page: Intravenous Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High-Speed Disperser Market: Why 3.8% CAGR and Regional Shifts Redefine Growth Through 2032
By pmarketresearch, 2026-09-21
High-Speed Disperser Market: Strategic Trends & Business Opportunities
Navigating Growth and Transformation in Industrial Mixing Equipment
The high-speed disperser market has entered a phase of structured expansion, driven by cross-industry demand for precision mixing, tighter quality standards, and the need to compress processing cycles. Valued at approximately 2.2 billion USD in 2025, the market is projected to sustain a compound annual growth rate of 3.8 percent through 2032. This trajectory signals a mature but steadily evolving landscape, where incremental gains increasingly depend on equipment performance, regional capability shifts, and the alignment of manufacturing footprints with end-user priorities. For executive teams and investors, the question is no longer whether the market will grow, but how value will be captured amid pricing pressure, application-specific customization, and a broadening competitive field.
The headline numbers obscure important structural realities. Growth is not uniformly distributed across end-use sectors, and regional advantages are tied to localized sourcing, technical support infrastructure, and the pace of industrial upgrading. At the same time, the equipment category itself is being redefined by higher throughput expectations, stricter safety and compliance requirements, and a growing premium on consistent dispersion quality across variable viscosities and solid loadings. Understanding these dynamics is essential for positioning capital, product development, and supply chain decisions ahead of the next investment cycle.
Market Landscape and Core Challenges
A Market in Transition, Not Stasis
Over the 2020 to 2025 period, revenue climbed from 1.6 billion USD to roughly 2.2 billion USD, reflecting a post-normalization rebound in capital equipment spending and a renewed focus on production efficiency after earlier supply disruptions. The forecast horizon extending to 2032 suggests continued but measured expansion, with the market advancing toward the 2.8 billion USD range. The 3.8 percent CAGR indicates a segment that is growing faster than many traditional industrial machinery categories yet still constrained by discretionary capital cycles, project-based purchasing patterns, and the sensitivity of end-use demand to broader economic conditions.
Two interconnected developments stand out. First, the market is increasingly application-led. As coating formulators, adhesive producers, pharmaceutical processors, and food manufacturers push for tighter particle size distributions, improved stability, and faster cycle times, the value of high-speed dispersers shifts from basic blending capability toward process consistency and repeatability. Second, geography matters more than ever. Regional demand is shaped by localized industrial clusters, the availability of aftermarket service, and the willingness of end-users to adopt higher-specification equipment that reduces labor intensity and improves batch-to-batch uniformity. These forces are reshaping how manufacturers price, configure, and deploy equipment.
High Speed Packaging Machine Market
Key Challenges and Inflection Points
Several pressures are converging at once, creating both risk and opportunity for firms that can respond strategically.
- Cost and capacity balance. Operators face pressure to justify equipment investment against rising energy costs and tighter margin expectations. The trade-off between higher throughput and energy consumption is no longer theoretical; it is a purchasing criterion. Units that deliver rapid dispersion without over-consuming power, or that integrate efficiently with downstream milling and finishing steps, are gaining attention.
- Safety, compliance, and specification rigor. Hazardous-process environments and stringent workplace standards are pushing standard design features toward explosion-proof motor configurations and integrated safety controls. Compliance is no longer a checkbox but a baseline expectation in chemical, coatings, and pharmaceutical-adjacent applications. Equipment that defaults to these specifications reduces integration friction and accelerates procurement.
- The customization-versus-scale tension. End-users increasingly want configurations tuned to viscosity ranges, batch sizes, and material sensitivities, while manufacturers seek to keep lead times and service complexity manageable. This tension is especially acute as laboratory-scale work, pilot validation, and pilot-to-production handoffs become more tightly linked. Equipment families that span these scales with consistent process logic can capture more of the workflow than single-point solutions.
These pressures are not insurmountable, but they do raise the bar for differentiation. Suppliers that treat the disperser as a standalone machine rather than a node in a broader dispersion workflow risk losing share to competitors who can reduce total processing time, improve consistency, and lower the total cost of ownership across the batch lifecycle.
Core Drivers Reshaping the Market
Technical Innovation and Process Performance
Performance is the currency of this market. High-speed dispersers are being evaluated less on nominal blending capacity and more on their ability to create turbulent flow conditions that break agglomerates, wet solids efficiently, and produce uniform dispersions in fewer passes. Equipment designed to deliver high tip speeds and robust rotor-stator architectures is broadening the practical envelope of what can be dispersed economically in a single stage. This matters for low-to-medium viscosity batches where turbulent mixing can compress cycle times relative to slower, conventional approaches.
At the component level, precision-balanced stainless steel shafts and blades are becoming standard for high-speed operation, supporting repeatable performance and reducing wear-related variability. The broader trend is toward equipment that is easier to integrate with media milling, pre-mixing, and finishing steps. Manufacturers offering modular integration paths are better positioned to address tough batching applications where raw dispersion alone is insufficient. The practical implication is that the market is rewarding completeness of process design, not just horsepower or bowl size.
Regulatory and Safety-Centric Design
Regulatory expectations and operational safety requirements are influencing baseline equipment design. In hazardous process industries, explosion-proof motor designs and safety switches are increasingly standard, reflecting both compliance demands and the practical need to reduce operational risk in environments with combustible dusts, volatile solvents, or sensitive chemistries. This does not merely add cost; it shapes buyer behavior. Units that default to safety-oriented designs reduce the burden on end-users to retrofit or requalify equipment, shortening evaluation cycles and lowering perceived implementation risk.
For manufacturers, the strategic question is whether safety and compliance features are treated as differentiators or as non-negotiable baselines. The market is moving toward the latter. Suppliers that build these specifications into core product lines, rather than offering them as afterthoughts or premium add-ons, can create a smoother path to purchase and a more defensible standard offering across regulated segments.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by the priorities of the industries that deploy dispersers. In paints and coatings, formulators continue to seek consistency, color stability, and rapid dispersion of pigments and extenders, particularly as formulation complexity increases. In adhesives and sealants, variability in filler loading and resin systems demands equipment that can handle wide viscosity ranges without sacrificing batch uniformity. Pharmaceutical-adjacent processing places a premium on cleanliness, repeatability, and contamination control, even when the disperser itself is part of a broader wet-processing chain. Food and beverage applications add another layer of concern around material compatibility, cleaning convenience, and throughput flexibility.
The common thread is a shift from volume-only thinking to process reliability and operational flexibility. Buyers are increasingly willing to pay for equipment that reduces batch variability, shortens turnaround between runs, and integrates cleanly with the rest of the line. In practical terms, this means that the value proposition of high-speed dispersers is expanding beyond “mixing” toward “controlled dispersion with predictable downstream results.”
Supply Chain and Cost Structure Dynamics
Cost dynamics are being shaped by raw material availability, manufacturing geography, and the balance between domestic production and imported equipment. Stainless steel components, precision balancing, and motor specifications all feed into cost structures, but the larger story is about access to reliable supply and the ability to deliver equipment without long lead times. Some manufacturers have leaned into quick-ship and short-lead options to meet project-driven purchasing. Others have focused on competitive cost positioning to win volume in price-sensitive markets. Both strategies can work, but they require different operating models and service commitments.
The broader implication is that supply chain resilience is becoming a competitive attribute. Buyers are attentive not only to sticker price but to the reliability of delivery, the availability of spares, and the speed of technical support when production schedules are on the line. In a market where batch schedules and line uptime matter, the financial case for equipment that is backed by dependable service is strengthening.
High Speed Motor Market
Competitive Landscape and Leading Strategies
Divergent Positioning in a Fragmented Field
The competitive landscape is broad, with manufacturers spanning mature industrial suppliers in North America, cost-competitive producers in China, and application-focused builders in India. Rather than converging into a single template, leading players are pursuing distinct forms of differentiation.
- Performance-oriented leaders emphasize rugged construction, vacuum-enabled dispersion, and rotor-stator architectures designed for particle size reduction and uniform dispersion in demanding wet-grinding and chemical applications. Their value proposition leans on process precision, repeatability, and the ability to address difficult batching conditions where agglomerates and solids loading make dispersion challenging.
- Service-and-integration-oriented suppliers focus on quick-ship options, stainless steel durability, and integration with media mills for pre-mixing. In tough batching applications, this approach reduces the friction of converting a disperser from a standalone unit into part of a staged process. Fast lead times and predictable configuration can be decisive for project-driven buyers.
- Cost-competitive regional players compete on price and accessibility, targeting industrial mixing across chemical, food, beverage, ink, cosmetic, and pharmaceutical segments. Their strength often lies in reaching buyers who need functional high-speed dispersion at a point in the cost curve where budget sensitivity is high, while still meeting core performance expectations.
- Application-customized exporters build their positioning around tailored coating and formulation solutions, often showing strong presence at regional and global exhibitions. Their strategy emphasizes fit-for-purpose configuration, demonstrating that dispersion equipment can be adapted to specific process windows rather than sold as a generic commodity.
Taken together, these strategies reveal a market where no single playbook dominates. Differentiation is real, but it is fragmented across performance, service responsiveness, price, and application fit. That fragmentation creates room for multiple winners, but it also raises the importance of clarity in positioning. Buyers are comparing not just technical specs but the total experience of specifying, installing, operating, and maintaining equipment.
Evolving Market Dynamics
Several structural shifts are visible. First, the boundary between laboratory, pilot, and production-scale equipment is becoming more strategically important. High-speed dispersers are available across a wide scale range, and organizations that can move from small-batch formulation to larger production with consistent process logic can reduce handoff risk and speed development cycles. Second, exhibitional presence and trade-show engagement remain meaningful, not because attendance alone drives sales, but because it signals visibility, technical credibility, and proximity to end-use communities in coatings, chemicals, and related sectors. Third, geographic diversity is increasing the importance of localized capability. Buyers in different regions weigh factors such as part availability, installation support, and the practical ability to adapt equipment to local operating conditions.
The competitive field is therefore unlikely to consolidate into a single dominant model in the near term. Instead, the market is shaping up as a layered competition in which some players win on performance and process integration, others on cost and accessibility, and still others on application-specific customization. The long-term question is which combinations of these attributes are most durable as buyers become more sophisticated about total cost and process outcomes.
Forward Outlook: Three Trends to Watch
1. Performance Integration Will Outweigh Standalone Specifications
Over the next three to five years, buyers are likely to evaluate dispersers less as isolated machines and more as components of an integrated dispersion workflow. Equipment that connects cleanly with pre-mixing, media milling, and downstream finishing steps will be favored in applications where particle size control and batch consistency matter most. This trend favors suppliers that can offer staged process logic, not just high tip speeds or large batch capacities. It also increases the importance of application engineering capability, since the right configuration depends on material properties, viscosity, solids loading, and target dispersion quality.
For manufacturers, this means that roadmap planning should prioritize integration flexibility, scalable process families, and the ability to support customers in matching equipment to real formulation constraints. For investors, the signal is that value may shift toward companies that can capture more of the workflow rather than those competing solely on unit price.
2. Safety, Compliance, and Energy Awareness Will Become Default Purchasing Criteria
As operational expectations rise, equipment that defaults to explosion-proof designs, integrated safety controls, and efficient power usage will face less friction in regulated or safety-sensitive environments. At the same time, energy efficiency is likely to gain salience as operators compare throughput gains against operating cost. Equipment that can deliver turbulent dispersion effectively without excessive power draw, or that helps reduce overall batch time in a way that improves line utilization, will be better positioned in procurement evaluations.
PW Consulting
The practical opportunity is to align product roadmaps with these expectations early. Treating safety and efficiency as core design attributes, rather than optional upgrades, reduces cycle time in qualified buyer segments and strengthens the case for equipment that must meet stringent operating standards.
3. Regional Capability and Service Proximity Will Drive Share Shifts
Geographic diversification of manufacturing and support is likely to matter more as buyers weigh delivery reliability, aftermarket access, and the practical ease of specifying equipment in local contexts. Competitive advantage may accrue to suppliers who can combine reasonable cost structures with dependable lead times and responsive service, especially in regions where industrial clusters are expanding and end-users are less willing to accept long implementation timelines.
The related risk is that pricing pressure can intensify in price-sensitive segments, particularly where multiple suppliers compete on similar functional specifications. In that environment, sustainable advantage will depend on service quality, process support, and the ability to reduce hidden costs associated with downtime, rework, and integration complexity.
Strategic Guidance for Decision-Makers
For Equipment Manufacturers
- Sharpen positioning around a clear value equation. Whether the emphasis is performance, integration, service speed, or cost, the offering should be coherent and defensible, with product lines that reflect that choice rather than diluting it across unrelated configurations.
- Build process-oriented value into the product family. Customers increasingly care about consistency, batch time reduction, and integration with downstream steps. Roadmaps that support staged dispersion workflows and application-compatible configurations are more likely to win in demanding segments.
- Treat compliance and safety as baseline design logic. In regulated or hazardous environments, default safety and compliance features reduce procurement friction and broaden the addressable market without forcing customers into retrofit decisions.
For Investors and Strategic Buyers
- Look beyond top-line segment size and focus on the durability of differentiation. In a market with moderate growth and multiple competitor archetypes, value capture depends on whether a company has a clear, repeatable advantage in performance, service, or application fit.
- Assess exposure to workflow integration and application specificity. Companies that can reduce total processing time and improve batch consistency may earn stronger retention and pricing resilience than those competing primarily on unit cost.
- Monitor regional shifts in capability and support. Growth may be unevenly distributed, and the ability to deliver equipment and service locally can become a meaningful differentiator in expanding industrial regions.
For Procurement and Operations Leaders
- Evaluate total process impact, not just displacement speed. A disperser that shortens batch time but complicates downstream milling or increases variability may not deliver the expected net benefit. Specification decisions should account for the full workflow.
- Standardize where possible, but preserve application flexibility. Common safety and compliance baselines reduce approval overhead, while configuration options that match viscosity, batch size, and material sensitivity help protect consistency across varied production needs.
- Factor service proximity and lead-time reliability into total cost models. In project-driven environments, the cost of delayed installation, extended commissioning, or limited spares access can outweigh apparent price advantages.
Closing Perspective
The high-speed disperser market is moving from a phase of basic capacity expansion toward a more performance- and process-sensitive era. Growth is real but disciplined, and the way value is created is increasingly tied to how well equipment supports consistency, safety, integration, and localized reliability. For manufacturers, the opportunity lies in aligning product strategy with the workflow realities of coatings, chemicals, pharmaceuticals, adhesives, and food applications. For investors, the signal is that durable advantage will come from clear differentiation and the ability to reduce hidden costs across the process chain. For procurement and operations teams, the challenge is to evaluate dispersers in the context of total batch economics rather than in isolation.
The strategic picture is still forming, and the most consequential decisions will depend on granular insight into segment behavior, regional demand shifts, and the evolving cost and capability profiles of leading suppliers. For teams that need a deeper, data-backed view of these dynamics and how they map to specific operating contexts, the full research report offers a more detailed breakdown of market size, segmentation, competitive positioning, and forward scenarios.
For detailed analysis of this topic, please visit the official page: High-Speed Disperser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com