

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Mobile Crushers and Screeners Market: Asia Pacific’s 5.26% Growth and the Shift to Recycling

Mobile Crushers and Screeners Market: Strategic Trends and Commercial Opportunities Through 2032
The mobile crushing and screening sector has evolved from a commoditized equipment niche into a strategically critical segment within the broader heavy machinery landscape. As construction activity intensifies, stricter environmental mandates tighten operational constraints, and material recycling becomes economically imperative, manufacturers and fleet operators alike are recalibrating their investment theses. The market has demonstrated consistent growth over the past half-decade and is projected to expand at a steady compound annual growth rate of 5.26 percent through 2032. While aggregate revenue figures provide a useful baseline, the real strategic value lies in understanding where value is migrating: from raw tonnage capacity toward electrified drivetrains, modular screening architectures, integrated telematics, and compliance-ready emission control systems. This shift is reshaping competitive positioning, procurement criteria, and capital allocation strategies across mining, construction, and recycling verticals.
With a market base exceeding two billion dollars in recent years and a projected trajectory approaching four billion by the early 2030s, the segment is large enough to attract sustained capital but fragmented enough to reward operators who anticipate structural inflection points. Three forces are defining the current landscape: tightening dust and particulate regulations that force equipment redesigns, accelerating electrification that blurs the line between mobile machinery and industrial power electronics, and cyclical but structurally rising demand for on-site material processing that favors flexibility over stationary plant investments. Navigating these dynamics requires a clear grasp of technology roadmaps, regulatory exposure, and competitive differentiation rather than reliance on historical equipment replacement cycles alone.
Market Context and Core Challenges
The mobile crushers and screeners market has matured beyond the simple replacement cycle model that characterized its earlier growth phase. Revenue expansion has been supported by sustained infrastructure development, urbanization-driven aggregate demand, and a growing preference for mobile configurations that reduce haul distances, lower fuel consumption, and enable rapid redeployment across multiple sites. However, the growth path is no longer purely volume-driven. The strategic question for operators and capital allocators is how to capture margin expansion while absorbing higher compliance costs, technology transition expenses, and supply chain volatility.
PW Consulting Automotive & Machinery Research Center
One defining challenge is the regulatory tightening around particulate emissions, noise, and site suppression. Environmental agencies across multiple jurisdictions have moved from advisory guidance to enforceable permitting and operational mandates for mobile crushing and screening equipment. Plants exceeding certain throughput thresholds now face permit requirements, wet suppression systems are increasingly mandated on aggregate processing sites, and operator safety standards have been reinforced with stricter lockout, tagout, and personal protective equipment protocols. These mandates are not marginal compliance footnotes; they influence equipment architecture, site planning, maintenance cycles, and total cost of ownership. Manufacturers that treat regulation as a design constraint rather than an afterthought are gaining a meaningful commercial advantage.
A second challenge is the technology transition from conventional diesel-mechanical drives to hybrid and fully electrified configurations. Electrification is reshaping performance expectations, service requirements, and onsite infrastructure needs. While hybrid and plug-in systems can reduce fuel consumption and operating emissions, they also introduce new dependencies on battery management, power electronics, charging logistics, and technician training. The industry is still resolving questions around battery durability in harsh quarry conditions, grid or generator support on remote sites, and the economic payback under volatile energy pricing. This transition is opening opportunities for differentiated product lines, but it is also raising the performance bar for market participation.
A third challenge is market fragmentation combined with cyclical demand exposure. The sector features a mix of global incumbents, regional specialists, and emerging entrants, each competing on different axes such as mobility, screening precision, application-specific configurations, and service networks. At the same time, capital-intensive end markets remain sensitive to interest rates, public spending cycles, and commodity price fluctuations. This creates a landscape where scale alone is insufficient; resilience, application breadth, and aftermarket monetization are becoming decisive differentiators.
Key Demand Drivers
Technology Innovation and Electrification
Electrification and hybrid drivetrain architecture are among the most consequential innovation vectors in the mobile crushing and screening space. Manufacturers are moving beyond incremental fuel efficiency gains toward integrated power systems that combine diesel-electric gensets, battery buffers, and plug-in capability. These platforms enable lower onsite emissions, reduced noise, and more precise process control, which in turn supports compliance in sensitive operating environments and expands work windows in urban or regulated zones. The competitive edge is increasingly tied to how seamlessly electrification is integrated into crusher and screener functions, including feed control, screening kinematics, and conveyance, rather than treating it as a standalone powertrain swap.
Digitalization and telematics are reinforcing this trend. Real-time monitoring of crusher loads, screen wear, fuel or energy consumption, and maintenance intervals supports predictive service, reduces downtime, and strengthens the value proposition of integrated equipment fleets. Equipment that can be configured rapidly, moved efficiently, and diagnosed remotely is gaining preference in multi-site operations where labor availability and specialization are constrained. Innovation is therefore shifting from purely mechanical performance to system-level reliability, connectivity, and operational flexibility.
Policy and Regulatory Environment
Regulatory pressure is becoming a direct driver of product design and procurement decisions. Permitting requirements for nonmetallic mineral processing, suppression mandates for crushers and screens, and stricter air-quality oversight for mobile operations are influencing equipment selection at the project level. In many cases, the fastest path to compliance is not incremental retrofit but the selection of mobile plants designed from the outset with dust suppression integration, lower particulate generation, and operator safety controls.
These dynamics are particularly relevant where aggregate processing occurs near populated or environmentally sensitive areas. Site permitting timelines, community acceptance, and operator safety obligations are increasingly tied to equipment specifications. Manufacturers and fleet managers that align product design with prevailing and anticipated regulatory requirements can shorten project approval cycles and reduce operational friction. At the same time, the regulatory environment varies by region and application, which means compliance strategy must be localized rather than assumed from a single benchmark.
Demand-Side Shifts in Mining, Construction, and Recycling
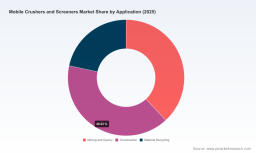
On-site material processing is being driven by a combination of logistical efficiency and material circularity. In mining and quarry operations, mobile configurations reduce the need for fixed infrastructure and long-haul movement of raw material, supporting flexible expansion and site switching. In construction, road building and aggregate processing demand is benefiting from rising infrastructure spending, with mobile plants enabling faster mobilization and quicker return on project timelines. In material recycling, the ability to process concrete, asphalt, and construction debris at or near the source is becoming economically and operationally attractive as disposal constraints and material recovery goals increase.
The demand profile is thus diversifying. It is no longer sufficient to optimize equipment solely for primary crushing throughput. Screening accuracy, adaptability to different feed materials, rapid setup and teardown, and support for secondary and tertiary processing have become commercial priorities. Recycling applications, in particular, are pushing equipment toward configurations that handle mixed inputs, support selective output fractions, and withstand more abrasive and variable feed conditions. This broadens the addressable opportunity but also raises the bar for versatility and durability.
Cone Crushers Market
Cost Structure and Supply Chain Dynamics
Cost dynamics are being reshaped by component availability, energy pricing, and the economics of electrification. Traditional cost structures centered on diesel consumption and mechanical wear are giving way to more complex operating expense profiles that include electrical infrastructure, battery service life, hybrid system maintenance, and software-enabled diagnostics. For fleet operators, the relative attractiveness of hybrid or electric configurations depends heavily on local fuel costs, access to power, labor costs, and the intensity of utilization.
Supply chain resilience is equally important. Manufacturers that can secure drivetrain components, hydraulic systems, wear parts, and electronic controls without extended lead times are better positioned to maintain delivery credibility and service responsiveness. Conversely, supply bottlenecks can erode the advantage of new product launches and delay customer payback. In this environment, procurement strategy is moving toward partnership-based sourcing, regionalization where feasible, and inventory planning that accounts for both mechanical wear and electronic subsystem replacement cycles.
Competitive Landscape and Leading Strategies
The competitive field features a mix of established European and North American manufacturers and growing regional players, each pursuing different strategic identities. Rather than competing purely on machine size or price, leaders are differentiating through application breadth, electrification readiness, mobility design, and aftermarket service systems. The resulting landscape is both consolidated in certain premium segments and active in others where localized support, application focus, and cost positioning create viable niches.
Several incumbents have anchored their positioning around complete mobile crushing and screening trains with hybrid or electrified power options. This approach emphasizes integrated process flow, consistent control across crusher and screen units, and reduced onsite complexity for the operator. By offering coordinated jaw, cone, and impact configurations together with screening and conveying, these manufacturers aim to reduce integration risk for customers and strengthen retention through multi-unit deployments and service contracts. Their differentiation often rests on proven mobility, modular scaling, and the ability to serve multiple applications without extensive re-engineering.
A parallel strategy is emerging around dedicated electrification and hybrid expertise, with some manufacturers building identity around diesel-electric plug-in capability, battery-backed systems, and multi-decade experience with hybrid drivetrains. This positioning is particularly relevant where noise, emissions, and urban proximity constrain conventional diesel operations. These players are positioning electrification not as a feature set but as an operational enabler, paired with equipment designs that support quick deployment, reduced fuel dependence, and compliance-friendly site profiles. In recycling-focused applications, specialized mobile screening and crushing configurations are also gaining traction, with manufacturers emphasizing process flexibility for secondary material recovery, concrete recycling, and abrasive feed handling.
Regional players continue to expand their footprint by combining competitive price positioning with application-specific configurations and accessible service models. Some are building credible offerings around compact tracked screens, jaw crushers, and integrated mobile units for mining, construction, and recycling. Others are developing excavator-attached screening and crushing solutions that expand the definition of mobile processing beyond standalone vehicles. These entrants do not need to replicate full-scale global platforms to compete; instead, they can win by targeting specific application gaps, delivery responsiveness, and localized service coverage.
Impact Crusher Market
Recent market activity reflects the speed of product refresh and customer-facing engagement. Trade show presence and new product introductions are being used to signal technology direction, reinforce application breadth, and maintain visibility in a competitive cycle. For example, the sector has seen coordinated launches and exhibition activity encompassing hybrid and electric crusher ranges, new cone crusher models, and recycling process demonstrations. Such moves matter because they shape buyer perception around innovation readiness and after-sales support, especially in a market where total cost of ownership and uptime are central to purchasing decisions.
The competitive evolution is likely to continue along two tracks: consolidation among players seeking scale, service coverage, and broader application portfolios, and differentiation among specialists targeting electrification, recycling, or compact mobility. New entrants will probably find the most traction where they can solve a clear application problem, offer speed-to-deployment advantages, or provide a distinct cost-service balance. Incumbents will need to defend their position through technology integration, uptime assurance, and compliance-aligned product design rather than scale alone.
Future Trends and Commercial Implications
Electrified and Hybrid Platforms Become a Default Consideration
Over the next three to five years, hybrid and electric configurations are expected to move from differentiated offerings to standard considerations in many applications. This does not mean every unit will be fully electric, but procurement discussions will increasingly weigh energy architecture alongside mechanical performance. The commercial implication is that manufacturers will need to offer clear trade-offs between diesel, hybrid, and electric options, with transparent operating cost modeling and service plans. For fleet operators, early familiarity with electrified equipment, charging or generator support strategies, and maintenance requirements will reduce deployment risk and improve site planning. Companies that delay engagement with these platforms risk higher retrofit costs and slower access to compliant configurations in regulated operating environments.
Application Diversification Toward Recycling and On-Site Processing
Material recycling and on-site aggregate processing are likely to remain important growth vectors, supported by circularity objectives, disposal constraints, and the economic logic of reducing haul distances. Mobile crushing and screening equipment that can handle variable feed, produce multiple output fractions, and be redeployed efficiently will see stronger demand. The commercial opportunity lies in designing product lines and service offerings that address these mixed-material realities rather than treating recycling as a secondary application. For investors and manufacturers, the strategic question is how to scale versatility without sacrificing durability or depressing margin structure.
Data-Driven Service and Integrated Fleet Management
Telematics, predictive maintenance, and fleet-level optimization are expected to become more central to competitive differentiation. Equipment that generates reliable operational data and integrates smoothly into fleet management workflows can reduce downtime and improve utilization across multiple sites. This creates value not only in new equipment sales but also in service contracts, wear-part optimization, and performance-based offerings. The risk is that data integration remains fragmented across manufacturers and sites, limiting the practical benefit. Operators that standardize on interoperable monitoring, service response, and parts logistics will capture more of the efficiency gain than those treating digital tools as isolated features.
Regulatory Risk and Regional Variation
Regulatory conditions will continue to evolve and vary by jurisdiction, creating both opportunity and uncertainty. Plants that proactively align with current permitting and suppression requirements will face fewer delays and lower compliance cost, but assumptions made in one region may not hold in another. The strategic response is to treat regulatory readiness as a design and procurement variable, not a fixed constant. Where possible, equipment and site plans should anticipate stricter particulate, noise, and safety requirements, especially for operations near communities or sensitive environments. Uncertainty remains around the pace and uniformity of regulatory adoption, which makes flexibility in equipment configuration and site design a valuable hedge.
Actionable Recommendations for Decision-Makers
For Manufacturers and Equipment Suppliers
Prioritize integration over isolated feature upgrades. Electrification, telematics, screening precision, and suppression capability should be developed as a coherent system that reduces site complexity and improves compliance readiness. Product roadmaps should be aligned with application realities in mining, construction, and recycling rather than optimized for a single performance metric. Service and parts availability should be treated as a product attribute, because uptime assurance increasingly determines repeat purchase behavior and fleet conversion. Where regional growth is targeted, localized support and delivery responsiveness can be as decisive as headline specifications.
For Investors and Capital Allocators
Focus on companies with credible technology pathways, application breadth, and aftermarket monetization rather than on volume growth narratives alone. The most durable value capture is likely to come from manufacturers that can convert technology transitions into service revenue, shorten deployment cycles, and maintain delivery credibility through supply chain resilience. Pay close attention to how firms are positioned for electrification, regulatory compliance, and recycling-related demand, since these areas are shaping both growth and competitive differentiation. Avoid underwriting strategies that depend on a single application cycle or a narrow geographic exposure without clear diversification levers.
For Procurement and Operations Leaders
Evaluate mobile crusher and screener purchases through total cost of ownership, compliance exposure, and redeployment flexibility rather than initial price or nominal capacity. Consider how energy architecture, suppression systems, and telematics affect site permitting, operating cost, and maintenance planning. Where multi-site or multi-application use is expected, favor configurations that can be rapidly mobilized and adapted to variable feed. Build service relationships and spare-parts strategies around actual utilization patterns and wear profiles, and validate electrification or hybrid choices against local energy access and labor capability instead of relying on generic efficiency assumptions.
The strategic window in this market is defined by the intersection of technology transition, regulatory pressure, and application diversification. Companies that interpret these forces as design and investment constraints rather than background conditions will be better positioned to capture durable value. For decision-makers who need deeper segmentation, regional variation, competitor-level benchmarking, and customized planning inputs, the full market study provides the detailed framework required to translate these trends into executable strategy.
For detailed analysis of this topic, please visit the official page: Mobile Crushers and Screeners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com