

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Manhole Covers Market CAGR Insights: How Asia Pacific and Cast Iron Are Driving Growth

The Manhole Covers Market: Strategic Shifts, Supply Chain Pressures, and the Road to 2032
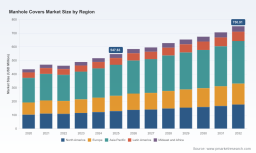
The global market for manhole covers has evolved from a commoditized municipal procurement category into a strategically significant segment of the broader infrastructure and civil engineering ecosystem. Valued at approximately $547.6 million in 2025, the market has demonstrated consistent expansion over the past five years, with historical growth reflecting steady infrastructure renewal, urban density increases, and gradual material substitution. Looking ahead to 2032, the market is projected to reach $750.9 million, supported by a compound annual growth rate of 4.6 percent. This trajectory is neither explosive nor stagnant; it is indicative of a mature, regulation-bound market where incremental innovation, compliance-driven substitution, and regional infrastructure spending patterns dictate competitive positioning.
For executives, strategists, and investors, the manhole cover market offers a useful lens into how seemingly low-tech industrial categories respond to digitalization, sustainability mandates, and cost volatility. The core opportunity lies not in volume alone, but in understanding where specification power, material performance, and service integration are creating durable differentiation. The sections below examine the market’s current realities, the forces reshaping demand and supply, competitive dynamics among leading players, and the strategic implications for the next several years.
Market Context and Core Challenges
The market’s scale and growth profile reflect a steady, demand-driven expansion rather than a speculative upcycle. Revenue has climbed through 2025 with a pattern of moderate year-over-year gains, consistent with long-cycle municipal and industrial infrastructure replacement programs. The forward projection through 2032 points to continued expansion, albeit at a measured pace that will reward operators who can manage specification cycles, material costs, and compliance requirements efficiently. The category is relatively fragmented at the top, with the three largest players holding a combined share near 24.6 percent and the top five accounting for approximately 26.2 percent, indicating room for consolidation as well as persistent niche competition.
Several structural challenges define the current market environment and are likely to influence strategic decisions through the forecast period.
Material cost volatility and input price sensitivity. Iron castings and scrap-based feedstocks form the backbone of traditional cover manufacturing, and price movements in these inputs translate quickly into margin pressure. Recent producer price indices for ductile iron castings have shown upward movement, while heavy melting steel scrap pricing has reflected broader commodity dynamics. Manufacturers operating on fixed-price municipal contracts or long bid cycles face the dual challenge of absorbing input cost spikes while maintaining competitiveness in re-bid situations. This environment favors firms with diversified sourcing, hedging strategies, and the ability to shift mix toward higher-margin products.
Regulatory compliance as both barrier and catalyst. Specification standards are tightening in multiple geographies. In the United States, approved material lists and performance requirements for state-funded projects increasingly mandate specific load ratings and standards alignment, directly influencing procurement eligibility. Elsewhere, sewage network specifications require compliance with recognized load-class certifications and documented conformity. These requirements elevate the importance of certification readiness, quality documentation, and technical support during the specification process. Operators without robust compliance infrastructure risk disqualification from high-value public tenders, while those with established certification portfolios can use compliance as a differentiator rather than a baseline cost.
Substitution pressure from alternative materials. Composite and other non-metallic solutions are gaining traction where weight reduction, corrosion resistance, or installation logistics are prioritized. This substitution is not uniform across applications or regions; it is most pronounced where labor costs, traffic disruption costs, or aggressive corrosion environments make traditional cast or ductile iron less advantageous on a total-cost basis. The strategic implication is that incumbents must compete not only on price but on lifecycle value, installation efficiency, and application-specific engineering justification.
Key Drivers Reshaping the Market
The market’s trajectory is being shaped by a combination of technology adoption, regulatory evolution, changing user expectations, and shifting cost structures. These drivers interact in ways that create both margin opportunities and competitive risk.
Technology innovation and intelligent infrastructure integration. The most visible innovation pathway is the integration of sensor-enabled functionality into cover and frame systems for monitoring, safety, and asset management. Investments in new manufacturing capacity oriented toward smart cover technology reflect an attempt to attach recurring value to a traditionally one-time procurement. Beyond sensors, advances in casting precision, surface treatments, locking mechanisms, and ergonomic installation features are improving operational outcomes for utilities and contractors. The strategic significance lies in shifting the category from a replaceable commodity to a monitored asset, which can strengthen customer stickiness when paired with service and maintenance relationships.
Policy and regulatory environment. Standards and approved material lists are becoming more explicit, particularly in public works. Load ratings, structural performance criteria, and certification requirements are increasingly tied to procurement eligibility. This trend advantages suppliers that can demonstrate compliance across multiple standards and provide transparent documentation. It also raises entry barriers for smaller producers that cannot sustain the administrative and testing overhead associated with multi-jurisdiction compliance. At the same time, regulation can accelerate replacement cycles where older infrastructure fails to meet updated standards, creating incremental demand for compliant replacements.
Demand-side behavior and total-cost consideration. Procurement decisions are increasingly influenced by total installation and lifecycle cost rather than unit price alone. Lightweight, high-strength alternatives are being evaluated for their potential to reduce manual handling risk, shorten installation time, and lower transportation costs. Urban utilities managing extensive networks in dense environments are especially sensitive to labor productivity and traffic disruption. As a result, specification conversations are shifting toward application-specific engineering, safety outcomes, and operational efficiency, particularly in industrial and commercial settings where downtime and safety incidents carry high indirect costs.
Supply chain and cost structure dynamics. The cost environment for ferrous inputs remains a critical variable. Producer price movements for ductile iron castings and fluctuating scrap pricing have introduced uncertainty into cost planning. Suppliers that rely on single-region sourcing or narrow supplier bases are more exposed to price shocks and logistics disruptions. Meanwhile, the relative attractiveness of composite solutions is partly a response to metal input volatility, as well as to the operational benefits of lower weight and improved corrosion behavior. Over the forecast period, cost structure resilience—through procurement diversification, inventory discipline, and product mix optimization—will differentiate financially stable operators from those exposed to raw material swings.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of regional incumbents, application-focused specialists, and exporters that compete on specification support, certification breadth, and manufacturing flexibility. The market’s top-heavy but not highly concentrated structure means that scale alone does not guarantee advantage; specification relationships, service capabilities, and differentiation in high-value niches often determine winning positions.
Leading manufacturers are pursuing distinct strategic positions that align with their capabilities and target segments.
Neenah Foundry illustrates the pivot toward innovation-led differentiation. By expanding manufacturing capabilities with a focus on smart cover technology and IoT-enabled infrastructure monitoring, the company is positioning beyond the traditional replacement cycle. This strategy is designed to attach higher-value functionality to standard infrastructure assets, potentially opening pathways to specification wins where monitoring, safety, and asset visibility are priorities. The approach carries execution risk—integration complexity, customer adoption cycles, and the need to demonstrate measurable operational returns—but it signals a longer-term positioning in intelligent infrastructure rather than purely metal fabrication.
EJ Group, Inc. represents a complementary strategy centered on material substitution and installation economics. The launch of a new line of lightweight, high-strength composite covers targets safety improvement and reduced installation costs. This direction aligns with demand-side shifts toward labor efficiency and risk reduction, particularly in environments where weight and handling are significant cost drivers. Composite solutions also offer corrosion advantages that can be compelling in aggressive environments. The challenge for this strategy is sustained adoption across specification bodies that may default to familiar metallic standards, which places emphasis on pilot projects, specification support, and total-cost justification.
Manhole Covers Limited and Manhole Covers Direct reflect the importance of regional presence, specification responsiveness, and channel access. In markets where local compliance, rapid fulfillment, and application-specific consultation influence purchasing decisions, these players compete through service agility and targeted product breadth. Their relevance underscores that even in a globalizing category, proximity to specification processes, distributor networks, and end-user support remains a meaningful advantage.
The market is likely to evolve along two parallel paths. First, consolidation may accelerate among producers seeking scale in manufacturing, sourcing, and compliance overhead, particularly where raw material volatility and certification demands raise the fixed-cost floor. Second, differentiation will intensify in segments where intelligent features, composite substitution, and specification-led value can command premium positioning. New entrants with specialized material science capabilities, sensor integration expertise, or application-specific engineering may gain footholds in niches that incumbents undervalue, while broader market share shifts will depend on the ability to win recurring municipal and industrial specification cycles.
Worldwide LED Tube Covers Market
Outlook for the Next 3–5 Years
Based on current market structure, regulatory direction, and innovation activity, several trends are likely to shape the market through the end of the decade.
Standardization of intelligent and connected infrastructure components. Sensor-enabled covers and related monitoring capabilities are likely to move from early-adoption projects toward broader consideration in smart city and utility modernization programs. The commercial opportunity lies not in the cover alone, but in the integration of monitoring with asset management workflows and maintenance planning. Operators that can offer compatible data interfaces, service relationships, and clear return-on-investment narratives will be better positioned to convert pilot interest into specification wins. A key uncertainty is the pace of public-sector budget allocation for smart infrastructure add-ons, which can be uneven across regions and procurement cycles.
Continued material diversification tied to lifecycle economics. Composite and hybrid solutions are expected to capture additional share where weight, corrosion, safety, and installation efficiency strongly influence total cost. This shift is unlikely to displace metal covers across the board, given the durability and familiarity of cast and ductile iron in many applications. Instead, the market will likely see a more segmented material mix, with choice driven by environment, load requirement, and operational priorities. Manufacturers that can provide credible testing data, certification support, and field evidence will be better equipped to compete for specifications that are open to alternatives. The uncertainty here is regulatory inertia; in some markets, established standards and procurement habits slow substitution even when total-cost arguments are strong.
Compliance-driven replacement and consolidation pressure. Updated load ratings, approved material lists, and certification expectations will continue to trigger replacement demand where existing infrastructure falls short of current requirements. At the same time, rising compliance overhead and input cost volatility may encourage consolidation among smaller producers and create supply advantages for operators with broader manufacturing footprints and more resilient sourcing. The strategic opportunity is to align production and certification capacity with the specifications most likely to see repeat procurement. The risk is margin compression if cost inflation outpaces pricing flexibility, especially in markets where bids are heavily price-driven and differentiation is limited.
Worldwide Cast Iron Manhole Covers Market
Regional divergence in growth drivers. While the market is expanding globally, demand momentum will not be uniform. Regions with active municipal renewal programs, dense utility networks, and stricter compliance requirements are likely to generate steadier replacement volume. In contrast, markets with slower public investment or limited specification formalization may see more intermittent demand. Companies operating across regions will need to calibrate capacity, product mix, and compliance portfolios to local specification realities rather than relying on a single global formula.
Strategic Actions for Decision-Makers
The market’s trajectory suggests that value creation will come from alignment across specification strategy, material and product mix, and cost resilience rather than from volume expansion alone. The following actions are most relevant depending on organizational role.
PW Consulting
For manufacturers and suppliers.
- Invest in certification breadth and documentation agility so that compliance becomes a competitive asset rather than an administrative burden, especially where public procurement requires explicit standards alignment and load-class verification.
- Develop application-specific value narratives that quantify installation efficiency, safety outcomes, and lifecycle performance, particularly for lightweight and composite offerings where total-cost justification is essential to overcome specification inertia.
- Diversify raw material sourcing and strengthen inventory and pricing flexibility to reduce exposure to ferrous input volatility, while evaluating product mix shifts that protect margin during cost spikes.
- Build credible pathways for intelligent infrastructure offerings by linking sensor integration to measurable operational benefits and service models, rather than treating connectivity as an isolated feature.
For investors and strategic acquirers.
- Focus diligence on specification relationships, certification readiness, and regional distribution strength, since these often determine repeat procurement more reliably than headline capacity.
- Assess exposure to raw material cycles and the flexibility of pricing and mix strategies, as input cost volatility can quickly alter margin profiles in otherwise stable-volume businesses.
- Identify targets with credible differentiation in smart infrastructure, composite substitution, or high-compliance municipal segments, where future value is likely to concentrate as standards tighten and replacement cycles accelerate.
For procurement and infrastructure operators.
- Evaluate covers on total installation and lifecycle cost, including handling safety, traffic disruption, corrosion environment, and maintenance implications, rather than on unit price alone.
- Align procurement specifications with current standards and load requirements to reduce re-work and disqualification risk, while leaving room for application-specific alternatives where they improve operational outcomes.
- Request documented certification, testing evidence, and installation guidance during the specification process to avoid downstream compatibility issues and compliance gaps.
Manhole covers may appear to be a straightforward industrial product, but the market’s evolution is increasingly defined by compliance, material economics, installation efficiency, and the early stages of intelligent infrastructure integration. For organizations operating in or adjacent to this category, timely access to detailed segmentation, regional specification patterns, and competitive movement data can sharpen procurement, investment, and product strategy. The broader market trajectory is clear; the actionable nuance lies in how each player positions for the intersections of regulation, material substitution, and innovation over the coming years.
For detailed analysis of this topic, please visit the official page: Manhole Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com