

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
High-Speed Disperser Market: Why 3.8% CAGR and Regional Shifts Redefine Growth Through 2032

High-Speed Disperser Market: Strategic Trends & Business Opportunities
Navigating Growth and Transformation in Industrial Mixing Equipment
The high-speed disperser market has entered a phase of structured expansion, driven by cross-industry demand for precision mixing, tighter quality standards, and the need to compress processing cycles. Valued at approximately 2.2 billion USD in 2025, the market is projected to sustain a compound annual growth rate of 3.8 percent through 2032. This trajectory signals a mature but steadily evolving landscape, where incremental gains increasingly depend on equipment performance, regional capability shifts, and the alignment of manufacturing footprints with end-user priorities. For executive teams and investors, the question is no longer whether the market will grow, but how value will be captured amid pricing pressure, application-specific customization, and a broadening competitive field.
The headline numbers obscure important structural realities. Growth is not uniformly distributed across end-use sectors, and regional advantages are tied to localized sourcing, technical support infrastructure, and the pace of industrial upgrading. At the same time, the equipment category itself is being redefined by higher throughput expectations, stricter safety and compliance requirements, and a growing premium on consistent dispersion quality across variable viscosities and solid loadings. Understanding these dynamics is essential for positioning capital, product development, and supply chain decisions ahead of the next investment cycle.
Market Landscape and Core Challenges
A Market in Transition, Not Stasis
Over the 2020 to 2025 period, revenue climbed from 1.6 billion USD to roughly 2.2 billion USD, reflecting a post-normalization rebound in capital equipment spending and a renewed focus on production efficiency after earlier supply disruptions. The forecast horizon extending to 2032 suggests continued but measured expansion, with the market advancing toward the 2.8 billion USD range. The 3.8 percent CAGR indicates a segment that is growing faster than many traditional industrial machinery categories yet still constrained by discretionary capital cycles, project-based purchasing patterns, and the sensitivity of end-use demand to broader economic conditions.
Two interconnected developments stand out. First, the market is increasingly application-led. As coating formulators, adhesive producers, pharmaceutical processors, and food manufacturers push for tighter particle size distributions, improved stability, and faster cycle times, the value of high-speed dispersers shifts from basic blending capability toward process consistency and repeatability. Second, geography matters more than ever. Regional demand is shaped by localized industrial clusters, the availability of aftermarket service, and the willingness of end-users to adopt higher-specification equipment that reduces labor intensity and improves batch-to-batch uniformity. These forces are reshaping how manufacturers price, configure, and deploy equipment.
High Speed Packaging Machine Market
Key Challenges and Inflection Points
Several pressures are converging at once, creating both risk and opportunity for firms that can respond strategically.
- Cost and capacity balance. Operators face pressure to justify equipment investment against rising energy costs and tighter margin expectations. The trade-off between higher throughput and energy consumption is no longer theoretical; it is a purchasing criterion. Units that deliver rapid dispersion without over-consuming power, or that integrate efficiently with downstream milling and finishing steps, are gaining attention.
- Safety, compliance, and specification rigor. Hazardous-process environments and stringent workplace standards are pushing standard design features toward explosion-proof motor configurations and integrated safety controls. Compliance is no longer a checkbox but a baseline expectation in chemical, coatings, and pharmaceutical-adjacent applications. Equipment that defaults to these specifications reduces integration friction and accelerates procurement.
- The customization-versus-scale tension. End-users increasingly want configurations tuned to viscosity ranges, batch sizes, and material sensitivities, while manufacturers seek to keep lead times and service complexity manageable. This tension is especially acute as laboratory-scale work, pilot validation, and pilot-to-production handoffs become more tightly linked. Equipment families that span these scales with consistent process logic can capture more of the workflow than single-point solutions.
These pressures are not insurmountable, but they do raise the bar for differentiation. Suppliers that treat the disperser as a standalone machine rather than a node in a broader dispersion workflow risk losing share to competitors who can reduce total processing time, improve consistency, and lower the total cost of ownership across the batch lifecycle.
Core Drivers Reshaping the Market
Technical Innovation and Process Performance
Performance is the currency of this market. High-speed dispersers are being evaluated less on nominal blending capacity and more on their ability to create turbulent flow conditions that break agglomerates, wet solids efficiently, and produce uniform dispersions in fewer passes. Equipment designed to deliver high tip speeds and robust rotor-stator architectures is broadening the practical envelope of what can be dispersed economically in a single stage. This matters for low-to-medium viscosity batches where turbulent mixing can compress cycle times relative to slower, conventional approaches.
At the component level, precision-balanced stainless steel shafts and blades are becoming standard for high-speed operation, supporting repeatable performance and reducing wear-related variability. The broader trend is toward equipment that is easier to integrate with media milling, pre-mixing, and finishing steps. Manufacturers offering modular integration paths are better positioned to address tough batching applications where raw dispersion alone is insufficient. The practical implication is that the market is rewarding completeness of process design, not just horsepower or bowl size.
Regulatory and Safety-Centric Design
Regulatory expectations and operational safety requirements are influencing baseline equipment design. In hazardous process industries, explosion-proof motor designs and safety switches are increasingly standard, reflecting both compliance demands and the practical need to reduce operational risk in environments with combustible dusts, volatile solvents, or sensitive chemistries. This does not merely add cost; it shapes buyer behavior. Units that default to safety-oriented designs reduce the burden on end-users to retrofit or requalify equipment, shortening evaluation cycles and lowering perceived implementation risk.
For manufacturers, the strategic question is whether safety and compliance features are treated as differentiators or as non-negotiable baselines. The market is moving toward the latter. Suppliers that build these specifications into core product lines, rather than offering them as afterthoughts or premium add-ons, can create a smoother path to purchase and a more defensible standard offering across regulated segments.
Demand-Side Shifts in End-Use Industries
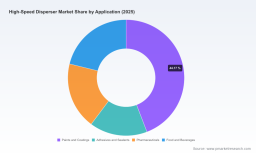
Demand patterns are being reshaped by the priorities of the industries that deploy dispersers. In paints and coatings, formulators continue to seek consistency, color stability, and rapid dispersion of pigments and extenders, particularly as formulation complexity increases. In adhesives and sealants, variability in filler loading and resin systems demands equipment that can handle wide viscosity ranges without sacrificing batch uniformity. Pharmaceutical-adjacent processing places a premium on cleanliness, repeatability, and contamination control, even when the disperser itself is part of a broader wet-processing chain. Food and beverage applications add another layer of concern around material compatibility, cleaning convenience, and throughput flexibility.
The common thread is a shift from volume-only thinking to process reliability and operational flexibility. Buyers are increasingly willing to pay for equipment that reduces batch variability, shortens turnaround between runs, and integrates cleanly with the rest of the line. In practical terms, this means that the value proposition of high-speed dispersers is expanding beyond “mixing” toward “controlled dispersion with predictable downstream results.”
Supply Chain and Cost Structure Dynamics
Cost dynamics are being shaped by raw material availability, manufacturing geography, and the balance between domestic production and imported equipment. Stainless steel components, precision balancing, and motor specifications all feed into cost structures, but the larger story is about access to reliable supply and the ability to deliver equipment without long lead times. Some manufacturers have leaned into quick-ship and short-lead options to meet project-driven purchasing. Others have focused on competitive cost positioning to win volume in price-sensitive markets. Both strategies can work, but they require different operating models and service commitments.
The broader implication is that supply chain resilience is becoming a competitive attribute. Buyers are attentive not only to sticker price but to the reliability of delivery, the availability of spares, and the speed of technical support when production schedules are on the line. In a market where batch schedules and line uptime matter, the financial case for equipment that is backed by dependable service is strengthening.
High Speed Motor Market
Competitive Landscape and Leading Strategies
Divergent Positioning in a Fragmented Field
The competitive landscape is broad, with manufacturers spanning mature industrial suppliers in North America, cost-competitive producers in China, and application-focused builders in India. Rather than converging into a single template, leading players are pursuing distinct forms of differentiation.
- Performance-oriented leaders emphasize rugged construction, vacuum-enabled dispersion, and rotor-stator architectures designed for particle size reduction and uniform dispersion in demanding wet-grinding and chemical applications. Their value proposition leans on process precision, repeatability, and the ability to address difficult batching conditions where agglomerates and solids loading make dispersion challenging.
- Service-and-integration-oriented suppliers focus on quick-ship options, stainless steel durability, and integration with media mills for pre-mixing. In tough batching applications, this approach reduces the friction of converting a disperser from a standalone unit into part of a staged process. Fast lead times and predictable configuration can be decisive for project-driven buyers.
- Cost-competitive regional players compete on price and accessibility, targeting industrial mixing across chemical, food, beverage, ink, cosmetic, and pharmaceutical segments. Their strength often lies in reaching buyers who need functional high-speed dispersion at a point in the cost curve where budget sensitivity is high, while still meeting core performance expectations.
- Application-customized exporters build their positioning around tailored coating and formulation solutions, often showing strong presence at regional and global exhibitions. Their strategy emphasizes fit-for-purpose configuration, demonstrating that dispersion equipment can be adapted to specific process windows rather than sold as a generic commodity.
Taken together, these strategies reveal a market where no single playbook dominates. Differentiation is real, but it is fragmented across performance, service responsiveness, price, and application fit. That fragmentation creates room for multiple winners, but it also raises the importance of clarity in positioning. Buyers are comparing not just technical specs but the total experience of specifying, installing, operating, and maintaining equipment.
Evolving Market Dynamics
Several structural shifts are visible. First, the boundary between laboratory, pilot, and production-scale equipment is becoming more strategically important. High-speed dispersers are available across a wide scale range, and organizations that can move from small-batch formulation to larger production with consistent process logic can reduce handoff risk and speed development cycles. Second, exhibitional presence and trade-show engagement remain meaningful, not because attendance alone drives sales, but because it signals visibility, technical credibility, and proximity to end-use communities in coatings, chemicals, and related sectors. Third, geographic diversity is increasing the importance of localized capability. Buyers in different regions weigh factors such as part availability, installation support, and the practical ability to adapt equipment to local operating conditions.
The competitive field is therefore unlikely to consolidate into a single dominant model in the near term. Instead, the market is shaping up as a layered competition in which some players win on performance and process integration, others on cost and accessibility, and still others on application-specific customization. The long-term question is which combinations of these attributes are most durable as buyers become more sophisticated about total cost and process outcomes.
Forward Outlook: Three Trends to Watch
1. Performance Integration Will Outweigh Standalone Specifications
Over the next three to five years, buyers are likely to evaluate dispersers less as isolated machines and more as components of an integrated dispersion workflow. Equipment that connects cleanly with pre-mixing, media milling, and downstream finishing steps will be favored in applications where particle size control and batch consistency matter most. This trend favors suppliers that can offer staged process logic, not just high tip speeds or large batch capacities. It also increases the importance of application engineering capability, since the right configuration depends on material properties, viscosity, solids loading, and target dispersion quality.
For manufacturers, this means that roadmap planning should prioritize integration flexibility, scalable process families, and the ability to support customers in matching equipment to real formulation constraints. For investors, the signal is that value may shift toward companies that can capture more of the workflow rather than those competing solely on unit price.
2. Safety, Compliance, and Energy Awareness Will Become Default Purchasing Criteria
As operational expectations rise, equipment that defaults to explosion-proof designs, integrated safety controls, and efficient power usage will face less friction in regulated or safety-sensitive environments. At the same time, energy efficiency is likely to gain salience as operators compare throughput gains against operating cost. Equipment that can deliver turbulent dispersion effectively without excessive power draw, or that helps reduce overall batch time in a way that improves line utilization, will be better positioned in procurement evaluations.
PW Consulting
The practical opportunity is to align product roadmaps with these expectations early. Treating safety and efficiency as core design attributes, rather than optional upgrades, reduces cycle time in qualified buyer segments and strengthens the case for equipment that must meet stringent operating standards.
3. Regional Capability and Service Proximity Will Drive Share Shifts
Geographic diversification of manufacturing and support is likely to matter more as buyers weigh delivery reliability, aftermarket access, and the practical ease of specifying equipment in local contexts. Competitive advantage may accrue to suppliers who can combine reasonable cost structures with dependable lead times and responsive service, especially in regions where industrial clusters are expanding and end-users are less willing to accept long implementation timelines.
The related risk is that pricing pressure can intensify in price-sensitive segments, particularly where multiple suppliers compete on similar functional specifications. In that environment, sustainable advantage will depend on service quality, process support, and the ability to reduce hidden costs associated with downtime, rework, and integration complexity.
Strategic Guidance for Decision-Makers
For Equipment Manufacturers
- Sharpen positioning around a clear value equation. Whether the emphasis is performance, integration, service speed, or cost, the offering should be coherent and defensible, with product lines that reflect that choice rather than diluting it across unrelated configurations.
- Build process-oriented value into the product family. Customers increasingly care about consistency, batch time reduction, and integration with downstream steps. Roadmaps that support staged dispersion workflows and application-compatible configurations are more likely to win in demanding segments.
- Treat compliance and safety as baseline design logic. In regulated or hazardous environments, default safety and compliance features reduce procurement friction and broaden the addressable market without forcing customers into retrofit decisions.
For Investors and Strategic Buyers
- Look beyond top-line segment size and focus on the durability of differentiation. In a market with moderate growth and multiple competitor archetypes, value capture depends on whether a company has a clear, repeatable advantage in performance, service, or application fit.
- Assess exposure to workflow integration and application specificity. Companies that can reduce total processing time and improve batch consistency may earn stronger retention and pricing resilience than those competing primarily on unit cost.
- Monitor regional shifts in capability and support. Growth may be unevenly distributed, and the ability to deliver equipment and service locally can become a meaningful differentiator in expanding industrial regions.
For Procurement and Operations Leaders
- Evaluate total process impact, not just displacement speed. A disperser that shortens batch time but complicates downstream milling or increases variability may not deliver the expected net benefit. Specification decisions should account for the full workflow.
- Standardize where possible, but preserve application flexibility. Common safety and compliance baselines reduce approval overhead, while configuration options that match viscosity, batch size, and material sensitivity help protect consistency across varied production needs.
- Factor service proximity and lead-time reliability into total cost models. In project-driven environments, the cost of delayed installation, extended commissioning, or limited spares access can outweigh apparent price advantages.
Closing Perspective
The high-speed disperser market is moving from a phase of basic capacity expansion toward a more performance- and process-sensitive era. Growth is real but disciplined, and the way value is created is increasingly tied to how well equipment supports consistency, safety, integration, and localized reliability. For manufacturers, the opportunity lies in aligning product strategy with the workflow realities of coatings, chemicals, pharmaceuticals, adhesives, and food applications. For investors, the signal is that durable advantage will come from clear differentiation and the ability to reduce hidden costs across the process chain. For procurement and operations teams, the challenge is to evaluate dispersers in the context of total batch economics rather than in isolation.
The strategic picture is still forming, and the most consequential decisions will depend on granular insight into segment behavior, regional demand shifts, and the evolving cost and capability profiles of leading suppliers. For teams that need a deeper, data-backed view of these dynamics and how they map to specific operating contexts, the full research report offers a more detailed breakdown of market size, segmentation, competitive positioning, and forward scenarios.
For detailed analysis of this topic, please visit the official page: High-Speed Disperser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com