

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Nut Ingredients Market 2026: Decoding the 6.39% CAGR Growth Drivers & Shifts
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Nut Ingredients Market
The global nut ingredients market has moved from a niche category to a foundational layer in modern food manufacturing. Over the 2020 to 2025 period, revenue grew from approximately 16.05 billion USD to 23.12 billion USD, reflecting a steady acceleration as processors, formulators, and brand owners expanded beyond whole nuts into flours, butters, pastes, and protein isolates. The forward trajectory points to 24.17 billion USD in 2026, rising to 35.73 billion USD by 2032, with a compound annual growth rate of 6.39 percent. This is not a simple extension of snack consumption; it is a structural shift in how nuts are sourced, processed, and embedded into mainstream product architectures.
For decision-makers, this expansion matters because nut ingredients now sit at the intersection of taste, texture, protein delivery, and clean-label formulation. The category is no longer just about almonds, cashews, or walnuts as finished snacks. It is about ingredient-ready outputs that behave predictably in industrial baking, confectionery, beverages, functional nutrition, and personal care. That breadth creates value, but it also introduces tradeoffs in supply consistency, regulatory handling, and formulation precision. The companies that can balance volume, quality, and traceability are positioned to capture a larger share of downstream growth.
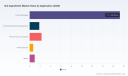
At the same time, the market is not uniformly distributed in its value pools. Europe and Asia Pacific together account for the largest regional shares of current revenue, while North America remains a highly active innovation and processing hub. In terms of ingredient forms, whole nuts continue to represent the largest segment, but processed formats such as butters, flours, and other specialty preparations are increasingly important in industrial applications. On the application side, food and beverage remains the dominant destination for nut ingredients, while smaller but strategically important demand comes from functional supplements, personal care formulations, and pharmaceutical uses. Conventional products still dominate total volume, though organic and clean-label lines are gaining relevance among premium and health-oriented buyers.
The concentration profile also tells a strategic story. The market structure is relatively consolidated, with the top three players holding roughly 65 percent and the top five holding about 75 percent of total market value. This level of concentration suggests that scale, relationships with grower groups, and processing capabilities remain powerful advantages. Yet it also indicates room for targeted entry by specialists offering differentiated formats, new cultivars, and regionally tailored supply chains. The competitive battleground is no longer just price per pound. It is consistency, functionality, sourcing narrative, and speed of reformulation.
Core Challenges and Inflection Points
Several overlapping pressures are reshaping how the nut ingredients market creates value, and each one has direct operational implications.
Raw material volatility remains a central challenge for producers and purchasers alike. Recent crop data indicates that California almond production reached approximately 3.0 billion pounds in 2025, the second largest on record, while walnut output was forecasted at 710,000 tons, up 18 percent from the prior year. Large harvests can ease short-term availability, but they also place downward pressure on prices and complicate margin planning for processors who have already locked in long-term contracts or invested in capacity. For buyers, this volatility creates a need for more flexible procurement strategies and stronger diversification across origins and nut types.
Regulatory compliance is another inflection point. Nut allergens require mandatory labeling under US FDA rules and comparable EU requirements, which affects product development, line management, and consumer communication. At the same time, sourcing increasingly has to account for traceability and due diligence expectations under frameworks such as the EU Deforestation Regulation. For global ingredient supply chains, this means that origin documentation, chain-of-custody practices, and supplier transparency are moving from compliance overhead to core commercial requirements. Companies that cannot demonstrate credible sourcing may find themselves excluded from certain buyers, formulations, or export channels.
A third challenge is the tension between scale and specificity. Demand is rising for clean-label, natural, and plant-based applications in bakery, confectionery, and snacks, but industrial customers want repeatable functionality, predictable viscosity, controlled particle size, and consistent flavor profiles. That combination favors processors who can standardize outputs across batches while still meeting clean-label and allergen-management expectations. The market is therefore caught between two pulls: the need for large-scale supply efficiency and the need for precision ingredient performance. Those who can resolve that tension are likely to command stronger buyer loyalty and better pricing power.
Key Drivers Shaping the Market
The expansion of the nut ingredients market is not being driven by a single force. It is the cumulative effect of technology, regulation, demand behavior, and supply economics. Understanding how these drivers interact is essential for positioning product portfolios and sourcing strategies.
Processing Innovation and Functional Ingredient Design
Technology is reshaping what nut ingredients can do in finished products. Modern processing is increasingly focused on producing bakery-friendly flours, stable butters and pastes, protein isolates, and value-added blends that perform reliably across a range of formulations. This matters because formulation teams are under pressure to reduce synthetic additives, improve texture with fewer stabilizers, and increase protein density without compromising taste. Nut-based ingredients align well with these goals, especially when they are supplied in consistent, ingredient-ready formats.
The industry context reinforces this direction. Recent product activity includes new mixed nut blends, organic and non-GMO lines covering cashew and pecan pieces, and expanded ranges of hazelnut and almond pastes for confectionery and bakery use. These introductions are not isolated launches. They reflect a broader pattern in which processors are building ingredient portfolios that can be integrated directly into industrial production lines. The strategic payoff is clear: when a supplier can offer both raw material reliability and formulation-ready specifications, it becomes a development partner rather than a simple commodity vendor.
Policy, Labeling, and Sourcing Expectations
Policy and regulatory evolution is shaping both product design and supply chain architecture. On the labeling side, allergen disclosure requirements push manufacturers toward stricter separation, clearer ingredient specifications, and more disciplined documentation. On the sourcing side, traceability expectations are becoming a baseline requirement, especially for buyers with global footprints or retail customers who demand deforestation-related due diligence for key inputs.
This does not simply raise compliance costs. It changes the competitive filter. Ingredient suppliers that can provide traceable origin data, allergen-managed processing environments, and consistent documentation are better positioned to serve regulated categories and export markets. It also creates an opportunity for differentiation through sourcing narratives, especially where growers and processors can demonstrate responsible farm management, water stewardship, and supply chain transparency. In practice, the regulatory conversation is becoming part of the commercial conversation, not a separate back-office function.
Dairy Ingredients Market
Demand-Side Shifts in Food, Beverage, and Adjacent Categories
The strongest structural driver remains demand behavior, particularly the rise of plant-based, protein-forward, and clean-label formulations. Nut ingredients are increasingly chosen not only for flavor but also for functional contribution: mouthfeel in sauces and dressings, richness in confectionery fillings, texturizing in baked goods, and protein density in nutritional products. This marks a shift from treating nuts as flavor accents to treating them as structural ingredients.
This trend is visible across bakery, confectionery, snacks, and adjacent sectors such as functional supplements and personal care. In food and beverage, the largest application pool, ingredient buyers are seeking formats that integrate efficiently into high-volume production. In functional nutrition, there is growing interest in nut-based proteins and nutrient-dense formulations. In personal care and cosmetics, nut oils and butters continue to hold relevance in premium skin-care applications. The common thread is demand for ingredients that are both desirable to consumers and practical for manufacturers.
Supply Economics and Procurement Strategy
Cost structures and supply availability are becoming more strategic rather than purely logistical. Changes in crop size, geographic concentration, and processing capacity influence price stability and negotiating power. When harvests are large, buyers may benefit from shorter-term price relief, but long-term planning remains complicated by weather variability, labor constraints, and transportation dynamics. For processors, the challenge is to maintain throughput and margin while managing uneven raw material inflows.
This environment favors procurement strategies that combine multi-origin sourcing, forward contracting, and ingredient flexibility. It also rewards companies that can convert variable raw inputs into consistent finished outputs. In other words, value is increasingly created by the ability to manage variability, not simply to buy cheaply. That is why supply chain design is now a competitive differentiator in the nut ingredients market, not just an operational function.
Competitive Landscape and Leading Strategies
The market’s concentration profile means that scale players can exert significant influence over pricing, supply, and category direction. At the same time, several recent moves show that competition is being waged through specialization, acquisitions, and targeted product expansion rather than broad commodity positioning alone.
Large integrated players are leveraging broad ingredient capabilities and strong food-manufacturing relationships. Companies with almond, nut butter, protein isolate, and processed nut ingredient offerings are well positioned to serve bakery, confectionery, and foodservice applications at scale. Their advantage lies in the ability to connect raw supply with standardized ingredient formats and to support large customers who need reliable volume and repeat specifications. Where these players also invest in protein-rich and plant-based ingredient development, they can address multiple formulation goals simultaneously.
Other participants are competing through narrower but deeper positioning. Some suppliers focus on roasted, seasoned, and private-label-ready tree nuts and peanuts for industrial food manufacturers. Others concentrate on premium nut butters, custom formulations, or bakery-specific fillings and pastes. This fragmentation matters because industrial buyers increasingly need inputs that are tailored to specific end uses rather than generic bulk supply. A supplier that understands how a nut paste behaves in a confectionery filling or how a nut flour interacts with gluten-free systems can command more strategic relevance than a supplier competing only on volume.
Recent industry activity illustrates how these strategies are evolving. Puratos Group expanded its clean-label positioning through an acquisition that strengthened nut butter and paste offerings for baking innovation. Separately, Guardian Capital Partners acquired a California-based developer of specialty nut-based ingredient solutions, signaling investor interest in formulation-focused capabilities. On the product side, Blue Diamond Growers introduced mixed nut blends under an expanded portfolio, Barry Callebaut rolled out new hazelnut and almond pastes for confectionery and bakery, and another processor launched organic and non-GMO nut ingredients for snacks and cereals. These moves are consistent with a market that is moving toward differentiated formats, clean-label credibility, and application-specific performance.
PW Consulting
The competitive trend is therefore dual. Consolidation continues to matter at the top end, but differentiation is intensifying across the rest of the field. Scale gives credibility and supply security. Specialty gives responsiveness, formulation depth, and niche access. The most resilient players are those that can manage both: enough scale to be reliable, and enough specificity to support innovation. For new entrants, the opportunity lies not in trying to out-scale incumbents, but in solving a concrete formulation or sourcing problem better than the current alternatives.
Future Trajectory: What to Expect Over the Next Three to Five Years
Based on current momentum and the structure of demand, a few trends are likely to define the next stage of market development.
First, ingredient functionality will become a more important battleground than nominal categorization. Buyers will increasingly evaluate nut ingredients by performance attributes such as emulsification behavior, viscosity stability, particle size consistency, and compatibility with clean-label systems. As a result, suppliers that can deliver technical documentation, application support, and repeatable batch quality will gain leverage. This will push more processors toward value-added processing and closer collaboration with R&D teams.
Dried Fruit Ingredients Market
Second, traceability and origin transparency will move from “important for compliance” to “important for commercialization.” As buyers expand export activity and retail partners demand stronger due diligence, ingredient suppliers with demonstrable sourcing records and allergen-managed processes will have a practical advantage. The market is likely to see more emphasis on supply chain mapping, documentation, and responsible sourcing narratives as part of the core product proposition.
Third, the category will continue to diversify across forms and applications, with processed ingredients gaining relative importance. Butters, flours, pastes, and protein-rich formats should continue to attract formulation investment because they can be integrated more easily into higher-value food and beverage systems. At the same time, organic, non-GMO, and clean-label lines will likely keep growing in premium segments, even if conventional products remain the volume backbone. This dual structure creates a market where overall growth is steady, but the most attractive margins may shift toward specialized, application-ready offerings.
These trends carry risk as well. Crop variability can still disrupt supply and pricing. Regulatory changes may increase documentation burden and raise the cost of market access. Clean-label expectations may conflict with the need for long shelf life or cost-efficient large-scale production. And consumer preferences can shift quickly, especially in snack, confectionery, and wellness categories. Companies that build flexibility into sourcing, product format, and formulation support will be better placed to absorb these shocks.
Strategic Actions for Decision-Makers
For manufacturers and ingredient suppliers, the priority is to strengthen application-level value rather than compete solely on bulk supply. That means investing in consistent processing outputs, improving technical support for bakery, confectionery, and snack formulators, and building portfolio breadth across whole nuts, flours, butters, pastes, and protein-oriented ingredients. Suppliers should also treat traceability and allergen management as integral to product design, not as separate compliance tasks, because these capabilities increasingly influence buyer selection and market access.
For investors, the most durable value may lie in capabilities that connect sourcing reliability with differentiated ingredient formats. Scale businesses with strong grower relationships and processing infrastructure remain relevant, but specialist assets that offer clean-label positioning, formulation depth, or application-specific performance may command premium strategic value. Diversification across nut types and end markets can also help reduce exposure to single-crop volatility. In this environment, the key question is whether a company can convert raw supply variability into repeatable commercial value.
For procurement teams and product developers, the practical move is to diversify both supplier base and ingredient formats. Relying too heavily on one origin or one nut type increases exposure to price swings and supply interruptions. At the same time, evaluating ingredient options by functional performance and documentation quality can reduce reformulation risk and speed time to market. Where possible, procurement should align with R&D early so that sourcing decisions support long-term formulation goals rather than short-term cost minimization alone.
For organizations planning deeper market entry or portfolio changes, the most useful next step is to ground decisions in detailed segment-level data. Market-level figures tell the direction of travel, but the actionable choices sit in the specifics: which forms are expanding fastest in which applications, how concentration varies by segment, where clean-label premiums are most defensible, and how sourcing constraints differ by region and crop cycle. Accessing comprehensive market intelligence can help validate assumptions before capital or capacity is committed, and it can support more precise prioritization across product lines, geographies, and customer segments. For teams that need tailored views of subsegments, competitive positioning, or sourcing implications, a full research report can provide the level of detail required to move from strategic direction to execution planning.
For detailed analysis of this topic, please visit the official page: Nut Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Take Off Market: Why 4.8% CAGR and Machinery Demand Change Everything
By pmarketresearch, 2026-09-21
Power Take Off Market: Strategic Trends and Commercial Opportunities Through 2032
The Power Take Off (PTO) market operates at the intersection of mechanical engineering, industrial mobility, and downstream application demand. Over the past five years, the sector has transitioned from steady incremental growth to a phase defined by product innovation, regulatory tightening, and regional demand realignment. Current market valuation sits at approximately 430 million USD, with historical performance reflecting a compound annual growth rate of 4.8 percent across the 2026 to 2032 forecast window. The trajectory suggests a market that is expanding in absolute terms while simultaneously undergoing structural refinement, as end users demand higher efficiency, safer operating conditions, and more integrated drivetrain solutions.
This evolution is not merely a function of rising unit volumes. It reflects a broader shift in how mobile and stationary equipment operators approach auxiliary power transmission. PTO systems are no longer treated as interchangeable mechanical add-ons; they are being designed to withstand higher torque loads, operate with reduced vibration, and integrate more cleanly with hydraulic and electrified auxiliary circuits. The market’s maturation is visible in the way manufacturers are balancing volume growth with margin protection, particularly as raw material volatility and international trade dynamics continue to reshape cost structures.
Side Shaft Market
Core Challenges and Inflection Point
Three structural challenges define the current operating environment for PTO manufacturers, distributors, and end users. Understanding these friction points is essential for assessing where near-term value will be created and where exposure should be managed.
First, the regulatory environment has tightened around safety and durability specifications. Updated international standards now mandate enhanced guarding, higher shaft durability thresholds, and more rigorous testing protocols for power transmission assemblies. These requirements are not optional compliance checkpoints; they influence product architecture, validation cycles, and time-to-market. Companies that can embed compliance into design rather than retrofit it gain a meaningful advantage in procurement approvals and customer trust, particularly in agricultural and construction sectors where safety culture is increasingly tied to equipment purchasing decisions.
Second, input cost volatility remains a persistent margin pressure. Steel price fluctuations and tariff movements have been shown to affect PTO shaft manufacturing margins by a measurable range, compressing profitability for producers with limited hedging flexibility or constrained supplier diversification. This is not a transient procurement issue; it is a structural cost dynamic that forces manufacturers to reconsider bill-of-material strategies, regional sourcing, and product standardization. In practical terms, firms that rely on highly customized shafts and components face greater exposure than those with modular architectures and broader supplier networks.
Third, the market is experiencing a functional divergence between traditional mechanical PTO demand and emerging auxiliary power needs. In several application areas, end users are re-evaluating whether mechanical PTO is the most efficient path for powering secondary systems. That reconsideration is creating a split environment: one segment continues to expand on the back of durable machinery and fleet replacement cycles, while another segment is being reshaped by electrification, hybrid auxiliary systems, and integrated power management architectures. The companies that treat this divergence as a strategic choice rather than a generic market trend will be better positioned to allocate R&D and commercial resources.
Key Demand Drivers Reshaping the Market
The PTO market’s growth is being driven by a combination of technology adoption, regulatory pressure, demand-side behavior, and supply chain economics. These drivers do not operate in isolation; they reinforce each other and create distinct competitive implications for manufacturers and buyers.
Technology Innovation and Product Architecture
Product innovation is increasingly centered on reliability, ease of integration, and reduced operational interruption. Hot shift PTO solutions, soft start technology, and improved wet kit configurations are examples of engineering responses to real-world operational pain points. In work truck and commercial vehicle applications, the ability to engage or disengage power transmission without stopping the vehicle, or to reduce shock loading during connection, translates directly into uptime improvements and lower wear on drivetrain components. Likewise, constant mesh designs and refined bolt configurations are being used to improve torque handling and service life in demanding environments.
Recent product activity reflects this direction. In early 2026, Eaton highlighted market-first hot shift PTO solutions, soft start technology, and upgraded wet kits for the work truck segment. Around the same period, Bezares introduced a new constant mesh Series 500 PTO to expand its power take-off range. These moves are not isolated product launches; they indicate a broader industry push toward systems that reduce operational friction, improve installation flexibility, and address the needs of OEMs and aftermarket buyers simultaneously. For commercial decision-makers, the practical implication is that PTO selection is becoming less about baseline mechanical compatibility and more about total operating efficiency, maintenance intervals, and integration with vehicle or machine architecture.
Policy, Standards, and Safety-Driven Demand
Regulatory and standards activity is acting as a demand catalyst in specific segments. Updated safety expectations and guarding requirements are encouraging replacement cycles and upgrades, especially where older equipment lacks modern protective mechanisms. At the same time, occupational safety initiatives have contributed to a measurable reduction in PTO-related injuries in agricultural settings through mandatory guards and automatic clutch mechanisms. This is significant because it reframes PTO procurement from a purely mechanical purchase into a risk-management decision.
For manufacturers, this environment rewards products that make compliance easier to implement and verify. For fleet operators and equipment owners, it raises the importance of purchasing systems that align with evolving site safety requirements without requiring extensive retrofitting. In both cases, the market is moving toward solutions that combine mechanical performance with verifiable safety outcomes, which strengthens the value proposition of integrated PTO and drivetrain packages.
Worldwide Hydrostatic Transmission Market
Demand-Side Behavior and Application Expansion
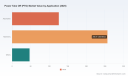
Demand is being shaped by a mix of replacement cycles, fleet modernization, and expanding use cases in off-highway and commercial vehicle environments. Machinery-driven applications remain a major demand center, reflecting the continued need for auxiliary power across construction, agriculture, and material handling equipment. At the same time, automotive-linked PTO demand continues to play a meaningful role, especially where commercial vehicles require integrated hydraulic and power transmission solutions for specialized operations.
What makes this demand environment strategically interesting is not just its size, but its sensitivity to operational economics. End users are increasingly evaluating PTO systems in the context of total cost of ownership, uptime, serviceability, and compatibility with broader vehicle or machine upgrades. That shift favors suppliers who can offer not only components, but also application-specific guidance, integration support, and after-sales service consistency. In practice, this means the commercial battleground is expanding from component performance alone to solution-level value.
Supply Chain and Cost Structure Dynamics
Supply chain conditions continue to influence both product design and pricing strategy. Material volatility and trade-related cost changes have made it more important for manufacturers to balance performance requirements with cost resilience. This has encouraged greater attention to component standardization, multi-source sourcing strategies, and design choices that reduce dependence on highly sensitive inputs. The strategic implication is straightforward: competitiveness is increasingly defined by the ability to maintain specification integrity while adapting to input cost shocks.
For buyers, this environment underscores the importance of long-term supplier relationships, clear specifications, and procurement plans that anticipate variability rather than react to it. For manufacturers, it rewards production strategies that combine engineering discipline with flexible sourcing and informed inventory planning. In a market where margins can be influenced by a notable percentage range due to material and tariff dynamics, cost structure management is not a back-office function; it is a competitive lever.
Competitive Landscape and Strategic Positioning
The PTO market features a mix of specialized manufacturers, broader motion-control companies, and large mobility technology providers. This mix creates a competitive environment where differentiation comes from application focus, product architecture, integration capability, and geographic reach. Rather than competing solely on price, leading players are building advantage through segment expertise, drivetrain integration, and the ability to meet increasingly demanding safety and performance expectations.
Differentiated Strategic Positions
Several company profiles illustrate how competitive advantage is being constructed in this market.
- Bezares has positioned itself as a global manufacturer spanning PTOs, hydraulic pumps, valves, tanks, and wet kits for trucks, industrial vehicles, and gearboxes. Its recent expansion into a constant mesh Series 500 PTO reflects a strategy centered on broadening the product range while maintaining a strong commercial vehicle and industrial vehicle footprint.
- Muncie Power Products focuses on power take-off units and parts alongside hydraulic components for work truck applications. Its strategic strength lies in serving a specialized commercial vehicle segment with a tightly aligned component and service ecosystem.
- Weasler Engineering targets high-performance drivelines and PTO systems for agricultural OEMs. This positioning emphasizes application-specific engineering and durability in demanding field environments.
- Walterscheid GmbH provides PTO driveshafts and drivetrain systems for agricultural, construction, and off-highway applications. Its relevance in off-highway segments gives it exposure to sectors where uptime, torque handling, and harsh-environment reliability are central purchase criteria.
- Eaton Corporation approaches the market from an intelligent power management perspective, offering mobile power solutions that include hot shift PTOs, wet kits, and drivetrain technologies. Its strategy is oriented toward integrated power management rather than isolated mechanical components.
- HYVA operates as a leading provider of hydraulic tipping systems, valves, pumps, and PTO solutions for commercial vehicles. Its positioning links PTO capability with broader hydraulic system functionality, which is valuable where tipping, lifting, and auxiliary operations are closely connected.
- Parker Hannifin Corporation brings a broad motion and control technology base, including hydraulic valves, pumps, and PTO components. Its scale and cross-product integration create advantages in projects that require coordinated hydraulic and power transmission solutions.
- ZF Friedrichshafen AG supplies advanced mobility products, including electrified PTO systems for commercial vehicles. Its presence signals the growing importance of electrification and next-generation drivetrain architectures in the PTO value chain.
- Interpump Group operates as a world leader in hydraulics and power transmission, including a division associated with Muncie Power Products for PTO and hydraulic components. Its structure illustrates how portfolio breadth and divisional specialization can coexist within a larger hydraulics and power transmission ecosystem.
Taken together, these players reveal a landscape where specialization and integration both matter. Some competitors win by deeply serving a specific application segment; others win by offering broader motion-control and power-management portfolios that reduce integration complexity for OEMs and end users. The strategic lesson is that the market does not reward a single winning formula. It rewards alignment between product architecture, application expertise, and the ability to respond to safety and performance expectations.
Market Structure and Evolution
Market concentration remains moderately consolidated, with the top three players accounting for roughly half of market revenue and the top five capturing a slightly larger share. This level of concentration suggests that scale, distribution reach, and portfolio breadth provide meaningful advantages, but it also leaves room for specialized leaders to compete effectively in focused segments. The market is not so concentrated that new ideas or application-specific innovations cannot gain traction, yet it is structured enough that broader portfolios and established supplier relationships influence procurement decisions.
The likely evolution over the next several years is not a simple shakeout. It is more plausibly a combination of selective consolidation in segments where integration and scale matter most, alongside continued differentiation in niches where application engineering, durability, and safety compliance create defensible positions. New entrants and adjacent players may find opportunity not by competing broadly, but by targeting specific drivetrain needs, regional demand pockets, or specialized electrified and hybrid auxiliary power applications.
Forward-Looking Trends and Commercial Implications
Looking toward the 2026 to 2032 horizon, the PTO market is likely to be shaped by three interconnected trends. Each has direct implications for product strategy, commercial planning, and risk management.
1. Integration will increasingly define value. PTO systems are moving from standalone mechanical components toward integrated power transmission and auxiliary systems. Hot shift capability, soft start behavior, wet kit improvements, and electrified PTO concepts all point in the same direction: end users want systems that reduce interruption, improve control, and fit cleanly into broader vehicle or machine architectures. Commercially, this means winning solutions will be those that combine component reliability with integration ease, application guidance, and service continuity. Manufacturers that can offer a coherent package rather than a discrete part will have stronger positioning in both OEM and aftermarket channels.
2. Compliance and safety will become purchase criteria, not side considerations. Updated guarding and durability expectations, together with the demonstrated impact of safety mechanisms on reducing injuries in agricultural environments, are making safety a more visible part of procurement reasoning. This trend supports demand for upgraded systems and creates a differentiation path for products that make compliance straightforward. For buyers, the opportunity lies in selecting PTO solutions that lower operational risk while maintaining performance. For suppliers, the opportunity lies in designing for verifiable safety outcomes and communicating them clearly.
3. Cost resilience and sourcing strategy will separate durable competitors from vulnerable ones. Material price volatility and trade-related cost shifts are likely to remain part of the operating environment. Companies that can manage input exposure through standardization, diversified sourcing, and disciplined product architecture will protect margins more effectively than those dependent on narrow supply chains or highly customized parts. This trend favors organizations that treat cost structure as a strategic variable and build flexibility into both design and procurement. It also means buyers should evaluate suppliers not only on specification and price, but also on supply continuity and ability to navigate cost shocks without compromising delivery quality.
Associated Risks and Uncertainties
These trends come with meaningful uncertainties. Electrification and hybrid auxiliary architectures could redistribute demand away from traditional mechanical PTO in certain segments, creating both opportunity and displacement risk depending on how quickly end users adopt new power layouts. Regulatory expectations may continue to tighten, increasing validation effort and affecting time-to-market for new designs. Input cost volatility could persist or intensify, especially if trade policy and material markets remain unstable. Finally, regional demand patterns may shift as fleet modernization, infrastructure investment, and off-highway activity evolve at different speeds across geographies. Companies that monitor these signals continuously will be better able to adjust product plans, procurement strategies, and commercial messaging before changes become disruptive.
PW Consulting
Strategic Actions for Decision-Makers
The PTO market’s next phase will reward participants who combine engineering discipline with commercial agility. The following actions are most relevant depending on role and exposure.
For Manufacturers and Product Leaders
- Prioritize integration-ready architectures that support hot shift operation, reduced shock loading, and cleaner fitment with hydraulic and drivetrain systems.
- Embed safety and durability requirements into design cycles rather than treating them as late-stage compliance tasks, reducing rework and accelerating customer acceptance.
- Strengthen sourcing flexibility and component standardization to protect margins against material and tariff volatility without sacrificing specification integrity.
For Investors and Strategic Planners
- Focus on companies with clear application specialization, integration capability, and evidence of cost-resilient manufacturing strategies, since these attributes are likely to matter more as the market matures.
- Watch for shifts in electrified and hybrid auxiliary power adoption, as these changes can alter demand patterns for traditional PTO systems and create new plays in integrated power management.
- Monitor M&A and portfolio realignment activity, particularly where broader motion-control or hydraulics players seek to strengthen PTO-related capabilities or application coverage.
For Procurement and Fleet Operators
- Evaluate PTO solutions on total operating impact, including uptime, serviceability, safety compliance, and compatibility with existing or planned vehicle and machine architectures.
- Build supplier relationships that emphasize specification clarity, delivery continuity, and support for replacement and upgrade cycles, especially where older equipment needs modernization.
- Plan procurement with cost variability in mind, using longer-term agreements, clear technical specifications, and diversified sourcing where feasible to reduce exposure to input shocks.
The strategic value of the PTO market lies not only in its growth trajectory, but in the way it is being reshaped by product innovation, safety expectations, and cost dynamics. Participants that treat these forces as interconnected will be better equipped to allocate resources, choose partners, and position for the 2026 to 2032 period with greater confidence. For decision-makers seeking deeper segmentation detail, regional demand patterns, and customized strategic recommendations, PW Consulting’s full research report provides a more granular view of the market and its commercial implications.
For detailed analysis of this topic, please visit the official page: Power Take Off (PTO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aircraft Hangar Doors Market: Why 6.2% CAGR & $2.74B Shift Reshape Airports
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Aircraft Hangar Doors Market
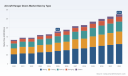
The aircraft hangar doors market has matured into a specialized infrastructure sector where engineering precision, regulatory compliance, and capital intensity converge. Valued at approximately 1.8 billion USD in 2025, the market has grown from 1.33 billion USD in 2020, reflecting a compound annual growth rate of 6.2 percent through the forecast period extending to 2032. At that horizon, revenue is projected to reach 2.74 billion USD. This trajectory is not merely a function of expanded aviation activity; it signals a structural shift in how hangar infrastructure is specified, manufactured, and integrated into broader airport and defense logistics ecosystems. For executives, investors, and procurement teams operating in aviation infrastructure, the market presents a clear opportunity space, but one that demands careful navigation of technical, regulatory, and supply chain complexities.
Market Snapshot and Core Challenges
The revenue trajectory outlined above reflects steady expansion rather than explosive growth, which is consistent with the capital-heavy, project-driven nature of hangar door installations. The market has moved from a post-pandemic recovery phase into a period of normalized demand, with civil aviation hubs driving the bulk of activity while military and private facilities contribute steady, specification-led procurement cycles. The overall picture points to an industry that is scaling incrementally, with growth increasingly tied to fleet modernization, facility upgrades, and the need for higher clearance envelopes as aircraft geometries evolve.
High Speed Doors Market
Several structural challenges define the current operating environment. First, the engineering envelope for hangar doors is being redefined by updated safety and construction standards. Recent revisions to NFPA 409 have raised the height limit for Group II hangars from 28 feet to 35 feet, creating a direct implication for door design, structural support, and clearance planning. This is not a marginal adjustment; it requires revised engineering approaches for facilities accommodating larger aircraft, and it pushes manufacturers and installers to adapt product lines, load calculations, and installation protocols.
Second, material inputs remain a persistent pressure point. Steel constitutes roughly 44.6 percent of hangar door material inputs, with hot-dip galvanizing and powder coating serving as the primary corrosion-resistant treatments for aviation environments. Supply chain disruptions for steel and aluminum components, which together comprise the majority of hangar door materials, continue to affect manufacturer margins and delivery schedules. In a market where custom engineering and installation of large-span doors demand specialized labor and long lead times for structural components, material volatility translates directly into project timeline risk and cost uncertainty.
Third, the market is characterized by meaningful concentration, with the top three players accounting for approximately 55 percent of revenue and the top five reaching roughly 72 percent. This concentration creates a dual dynamic. Incumbents benefit from established specifications, repeat contracts, and deep relationships with airport authorities and defense procurement channels. At the same time, it raises the barrier for new entrants who must demonstrate not only product capability but also compliance credibility, installation reliability, and the ability to meet specialized military and civil standards such as UFC 4-211-02, which specifies design requirements for steel sliding hangar doors in military facilities, including corrosion control and operational safety standards.
Key Demand Drivers
Technological Innovation and Engineering Differentiation
Technology differentiation in this market is less about digital novelty and more about mechanical reliability, clearance optimization, and corrosion management. Manufacturers are increasingly focused on door architectures that reduce operational friction, improve seal integrity, and accommodate larger aircraft footprints without compromising structural performance. Hydraulic and self-supporting systems with patented cam mechanisms have gained attention because they address the practical needs of facilities that require smooth, repeatable operations over large spans. Vertical lifting and sliding configurations are also being positioned as versatile options for aviation MRO environments and infrastructure projects where floor space, traffic flow, and maintenance access must be carefully managed.
Recent activity illustrates how companies are translating engineering capability into market visibility. Gandhi Automations showcased advanced vertical lifting and sliding aircraft hangar doors at MRO Americas 2026 in Orlando, following a similar presence at MRO Americas 2025 in Atlanta. These appearances are not merely promotional; they signal a strategic emphasis on MRO-adjacent infrastructure, where door performance directly affects turnaround efficiency, safety, and maintenance workflow. In parallel, AeroDoor International published analysis highlighting 35-foot height limits enabled by NFPA 409 updates, underscoring how manufacturers are using regulatory change as a platform to demonstrate readiness for larger aircraft clearances. This blend of engineering communication and event-based engagement reflects a market where technical credibility is a primary commercial asset.
Regulatory and Standards-Driven Specification Shifts
Regulatory and standards environments are shaping demand in ways that go beyond compliance. NFPA 409 updates and active military standards such as UFC 4-211-02 create specification anchors that influence procurement decisions long before a door is ordered. For civil airports, these standards interact with local building codes, airfield safety requirements, and operational clearance expectations. For military facilities, the emphasis on corrosion control, operational safety, and material durability means that specification cycles are often longer and more rigorous, but they also create sticky demand once a system is qualified.
PW Consulting
The practical implication is that regulatory change is becoming a demand catalyst rather than a static constraint. As height limits and clearance expectations rise, facilities planning expansions or replacements must revisit door selection earlier in the design process. This creates a window for manufacturers that can demonstrate compliant, scalable solutions and for procurement teams that align specification planning with anticipated regulatory trajectories. It also increases the importance of documentation, testing evidence, and installation track records, since specification decisions in this category are rarely made on price alone.
Demand-Side Shifts in Aviation Infrastructure Usage
Demand is being reshaped by how aviation facilities are used and upgraded. Civil airports continue to be the largest application segment, driven by terminal expansions, apron reorganizations, and the need to accommodate mixed fleets with varying aircraft sizes. Military airports contribute a substantial share of demand, often tied to facility modernization, readiness requirements, and the need for durable, standardized door systems that perform under demanding conditions. Private airports represent a smaller but strategically important segment, where customization, aesthetics, and operational flexibility often carry greater weight than in large-scale public facilities.
Beyond segment mix, the broader demand story is about operational intensity. Hangars are no longer treated as static storage spaces; they are increasingly integrated into maintenance, staging, and turnaround workflows. That shift raises the importance of door systems that support frequent operation, reliable sealing, and minimal downtime. It also reinforces interest in solutions that can be tailored to specific facility layouts, whether for airplane, floatplane, or helicopter hangars. In this environment, door selection is becoming part of a broader infrastructure strategy rather than a standalone purchase.
Supply Chain, Material Economics, and Project Execution
Supply chain and cost structure dynamics remain central to market behavior. Because steel and aluminum dominate material inputs, manufacturers are exposed to fluctuations in commodity availability, processing capacity, and treatment timelines for galvanizing and coating. These inputs are not easily substituted without affecting performance or certification expectations, which limits short-term flexibility. At the same time, custom engineering and installation require specialized labor, and long lead times for structural components can cascade into broader project delays.
This combination creates a market where execution capability is a competitive differentiator. Manufacturers that can stabilize supply arrangements, manage treatment workflows, and coordinate installation resources gain an advantage that extends beyond product design. For buyers, the lesson is that total project risk is shaped as much by lead times, labor availability, and treatment quality as by the door mechanism itself. In practice, this elevates the importance of supplier reliability, project planning discipline, and early alignment between specification, fabrication, and installation phases.
Fixed Drone Hangar Market
Competitive Landscape and Leading Strategies
The competitive environment is defined by a handful of established manufacturers with strong regional footprints, specialized product architectures, and deep installation capabilities. AeroDoor International operates as a manufacturer and installer of custom steel sliding aircraft hangar doors for military, commercial, and private aviation applications, with a profile that emphasizes tailored construction and broad application coverage. Diamond Doors focuses on custom bifold aircraft hangar doors for private, commercial, and aviation hangar buildings, positioning itself around configuration flexibility. Higher Power Doors manufactures self-supporting hydraulic aircraft hangar doors with a patented cam system, highlighting mechanical differentiation and operational reliability.
Schweiss Doors is a leading manufacturer of hydraulic aircraft hangar doors for airplane, floatplane, and helicopter hangars, with a clear focus on hydraulic systems and diversified aircraft types. Norco Manufacturing produces custom bi-parting, one-way, and 90-degree aircraft hangar doors for military, corporate, and large-scale aviation facilities, suggesting strength in specialized configurations and larger facility projects. Gandhi Automations manufactures premium vertical lifting and sliding aircraft hangar doors for global aviation MRO and infrastructure projects, indicating a strategic orientation toward international project work and MRO-linked demand. Champion Door Oy produces fabric fold-up aircraft hangar doors for military to jumbo jet applications, offering a distinct material approach that can suit specific operational and transport requirements. Vortex Doors provides specialized maintenance, repair, and installation services for aircraft hangar doors, including vertical lift and large-scale systems, which positions the company around service continuity and lifecycle support rather than manufacturing alone.
The strategic positioning across these players reveals several differentiation paths. One is product architecture: sliding, folding, roll-up, swinging, and specialized hydraulic or vertical lifting systems each address different facility constraints, clearance needs, and operational preferences. Another is application focus, with some firms leaning into military specifications and large-scale facilities, while others emphasize private aviation, floatplane and helicopter hangars, or MRO-related infrastructure. A third is service integration, where maintenance, repair, and installation capabilities become part of the commercial value proposition, especially for large-span systems where ongoing performance and downtime avoidance matter.
Market structure appears to be evolving along two overlapping trends. Consolidation pressure exists because scale, specification relationships, and installation networks create advantages that are difficult to replicate quickly. At the same time, differentiation remains viable for firms that can claim a clear technical niche, such as fabric-based fold-up systems, patented hydraulic mechanisms, or specialized vertical lifting solutions. New entry is possible but challenging, particularly where military standards, corrosion control expectations, and large-span installation expertise raise the bar for credibility. The more likely evolution is a mix of continued concentration among incumbents serving major civil and military programs, alongside targeted competition in specialized sub-segments and service-led growth for firms with strong installation and maintenance footprints.
Forward-Looking Trends and Commercial Implications
Expansion of Clearance Envelopes and Redesigned Door Systems
Over the next three to five years, one of the most consequential trends will be the continued adjustment of door systems to accommodate higher clearance requirements and larger aircraft footprints. The NFPA 409-driven shift toward 35-foot height limits for Group II hangars is a leading indicator of how standards can reshape product expectations. As facilities plan for mixed fleets, expanded aprons, and modernized maintenance layouts, door systems will need to balance span, structural support, and operational smoothness without sacrificing safety or durability.
The commercial opportunity here lies in early specification alignment and engineering readiness. Manufacturers that can document compliant designs, provide clear guidance on clearance planning, and demonstrate installation experience for larger envelopes will be better positioned to capture projects at the design stage. For procurement teams, the opportunity is to reduce rework and delay by integrating door selection into facility planning earlier, rather than treating it as a downstream procurement item. The risk is that standards interpretation, structural adaptation, and installation sequencing can become complex, especially where existing site conditions constrain redesign.
Service, Lifecycle Support, and MRO-Linked Demand
A second trend is the growing commercial relevance of service and lifecycle support. As hangar doors become more integrated into operational workflows, maintenance reliability, repair responsiveness, and installation quality gain importance. This is visible in the activity of firms that emphasize maintenance, repair, and installation services alongside product offerings, and in the broader MRO context where infrastructure performance affects turnaround efficiency. Vertical lifting and sliding systems, in particular, are being showcased in MRO-adjacent settings, suggesting that door performance is increasingly evaluated in relation to maintenance operations rather than static storage alone.
For manufacturers, this trend opens a path to differentiated value through service contracts, replacement component availability, and installation expertise that reduces operational risk. For investors and strategic buyers, it suggests that businesses with strong service networks and repeat maintenance relationships may command durable revenue characteristics, provided they can scale service delivery without compromising quality. The uncertainty lies in labor specialization and geographic coverage; service-led models depend on skilled crews and responsive logistics, which can be difficult to replicate across broad regions.
Material Strategy, Cost Management, and Regional Demand Shifts
A third trend is the continued emphasis on material strategy and cost management amid ongoing supply chain pressure for steel and aluminum components. With steel representing a significant share of material inputs and corrosion-resistant treatments playing a critical role in aviation applications, manufacturers will keep optimizing sourcing, treatment workflows, and inventory planning to protect margins and delivery reliability. At the same time, regional demand patterns will continue to shape project pipelines, with North America, Europe, and Asia Pacific representing substantial activity, while Latin America and the Middle East and Africa contribute more selective but growing opportunities tied to infrastructure investment and aviation expansion.
The commercial implication is that resilience in material planning and project execution will be a competitive advantage. Manufacturers that can manage treatment lead times, stabilize component supply, and communicate realistic delivery expectations will be better placed to protect margins and customer relationships. Buyers benefit from early engagement, clear specification alignment, and contracting structures that account for material and installation risk. The uncertainty is that commodity volatility and specialized labor constraints can still disrupt timelines, particularly for large, customized projects where structural components and treatment requirements extend lead times.
Actionable Guidance for Decision Makers
For manufacturers and product leaders, the priority is to strengthen engineering differentiation while ensuring that regulatory and standards readiness is visible and verifiable. That means investing in door architectures that address larger clearances, corrosion control, and operational reliability, and making compliance evidence, installation track records, and service capability easy to evaluate. Companies should also treat supply chain and treatment workflows as strategic assets, since margin protection and delivery reliability increasingly depend on how well material inputs and specialized labor are coordinated. Where possible, expanding service and lifecycle support can create a more resilient commercial model, especially for large-span and hydraulic systems where ongoing performance matters.
For investors and strategic acquirers, the market rewards businesses with specification relationships, installation credibility, and the ability to serve regulated or large-scale programs. Due diligence should look beyond unit economics to assess how well a company navigates military and civil standards, manages steel and aluminum supply exposure, and delivers customized engineering without excessive lead-time risk. Service-oriented capabilities and MRO-adjacent positioning may add durability to revenue streams, but only if supported by skilled labor and reliable project execution. Regional exposure is also worth evaluating carefully, since demand intensity and specification requirements vary meaningfully across civil, military, and private applications.
For procurement teams and airport or defense facility planners, the most effective approach is to move door specification earlier in the planning cycle and treat it as part of the broader infrastructure design rather than a final-fit purchase. Early alignment with manufacturers on clearance expectations, material treatments, and installation sequencing can reduce rework and delay, particularly as standards evolve and aircraft footprints expand. Contracting and project planning should account for specialized labor availability, structural component lead times, and corrosion-control requirements, since these factors often shape total project risk more than headline product cost. Where facilities anticipate frequent operation or integrated maintenance workflows, prioritizing systems with strong service and repair support can help protect operational continuity.
The aircraft hangar doors market is entering a phase where growth is increasingly tied to engineering adaptation, standards evolution, and execution reliability. For organizations operating in aviation infrastructure, the most valuable insights are those that connect regulatory change, material economics, and competitive positioning to specific project and investment decisions. Detailed segmentation data, regional demand breakdowns, company-level comparisons, and customized scenario analysis can sharpen those decisions further. To explore the full segmentation structure, regional dynamics, and forward estimates in greater depth, the complete PW Consulting market report provides the supporting detail and tailored frameworks needed for strategic planning.
For detailed analysis of this topic, please visit the official page: Aircraft Hangar Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Peptide Synthesis Market 2026: How 7.85% CAGR and Therapeutics Dominance Reshape Growth Strategy
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Peptide Synthesis Market
Beyond the 7.85% CAGR: Navigating a Maturing and Consolidating Peptide Synthesis Ecosystem
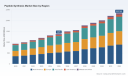
The global peptide synthesis market has transitioned from a niche supporting segment into a central pillar of modern biopharmaceutical manufacturing. From 2020 through 2025, the market expanded from approximately USD 930 million to USD 1.38 billion, reflecting steady compound annual growth that is expected to accelerate into the 2032 forecast horizon, reaching an estimated USD 2.34 billion. This trajectory is underpinned by a projected CAGR of 7.85% across the 2026 to 2032 period, signaling that demand drivers are not cyclical but structural. The expansion is not merely a function of incremental volume growth; it reflects a fundamental shift in how peptides are designed, manufactured, and positioned across therapeutic, diagnostic, and research applications. For executives and investors, the market is no longer defined by isolated laboratory workflows but by integrated, scale-ready supply chains that must balance regulatory rigor, cost efficiency, and technological divergence.
At a high level, the market is characterized by moderate concentration, with the top three firms accounting for roughly 39.5% of revenue and the top five capturing approximately 48.2%. This structure suggests that while scale players dominate commercial endpoints, meaningful differentiation persists through specialized capabilities, regional footprints, and technology choices. The revenue composition shows that reagents and consumables continue to represent the largest share within the product segment, equipment contributes a substantial but secondary portion, and services form a meaningful third pillar that increasingly blurs the line between pure supplier and integrated partner. Technologically, solid-phase peptide synthesis remains the dominant approach, though solution-phase and hybrid or recombinant methods occupy distinct niches that are expanding as manufacturers confront scale and purity requirements. By application, therapeutics command the largest share, followed by diagnosis and research and development, reflecting the pipeline’s growing reliance on peptide-based modalities for targeted interventions and precision diagnostics.
The Structural Inflection: Where the Market Stands Today
The current market environment is shaped by a convergence of scaling capacity, regulatory formalization, and technology adoption that is reshaping competitive dynamics. The most immediate reality is that demand growth is pressuring legacy manufacturing models. Traditional batch-oriented solid-phase workflows, while mature and broadly deployed, face limits when applied to multi-kilogram and commercial-scale production without substantial re-engineering of solvent handling, purification, and waste management. This has forced both incumbents and new entrants to evaluate process intensification, automation, and liquid-phase alternatives as practical necessities rather than optional upgrades. The result is a market in which operational capability has become as strategic as scientific know-how.
A second inflection lies in the regulatory environment. Over the past year, regulatory bodies have moved from general expectations to more explicit, peptide-specific guidance. The adoption of dedicated manufacturing and development guidelines has raised the bar for process documentation, impurity control, and consistency across batches. This formalization has two implications: it creates a higher barrier to entry for manufacturers that lack quality systems and data integrity infrastructure, and it strengthens the positioning of established players who can demonstrate traceability, validation, and regulatory readiness across clinical and commercial stages. For the market as a whole, the shift reduces ambiguity but also compresses timelines for those still building compliance maturity.
The third challenge is commercial scale and cost structure. Peptides remain cost-sensitive relative to small molecules and antibodies, particularly when complex sequences, challenging purifications, or stringent impurity thresholds are involved. As therapeutic programs advance toward commercialization, the economics of goods sold become a decisive factor, especially for chronic indications or large patient populations. This pressure has intensified interest in yield optimization, solvent recovery, convergent synthesis routes, and contract development and manufacturing partnerships that can de-risk scale-up. The market is therefore entering a phase where technical feasibility and commercial viability must be designed in tandem from early development rather than resolved retrospectively at the manufacturing stage.
Core Drivers Shaping the Peptide Synthesis Landscape
Technology Innovation and Process Intensification
The dominant force in the market remains the continued refinement of synthesis technology, especially within solid-phase workflows, but with growing attention to complementary methods. Microwave-assisted synthesis has expanded the practical toolkit for accelerating coupling steps and improving reproducibility for difficult sequences. More importantly, automation is moving from laboratory convenience to industrial necessity, with instrument platforms and integrated process controls becoming central to ensuring lot-to-lot consistency. As programs move from discovery to late-stage development, the ability to standardize cycle times, reduce manual variability, and monitor reaction progress in-line is increasingly tied to readiness for regulated manufacturing.
Parallel to automation, liquid-phase peptide synthesis and hybrid approaches are gaining traction where scale and cost matter most. These methods are not replacing solid-phase synthesis but are being positioned as alternatives for specific use cases, particularly when longer sequences, large-scale production, or cost-efficient impurity management are priorities. The market is witnessing a pragmatic bifurcation: solid-phase synthesis continues to anchor clinical and commercial supply for many programs, while solution-phase and hybrid pathways carve out opportunities where throughput and economics are decisive. This divergence creates an environment in which technology selection is increasingly application-driven, with manufacturers expected to justify their choice based on sequence complexity, target scale, and purity requirements.
A notable real-world indicator of this technological push is the recent expansion of synthesis capacity across multiple manufacturing sites. Facilities have been adding pre-built module installations, commissioning new large-scale solid-phase lines, and integrating upstream and downstream capabilities in a single site. These moves are not simply about adding square footage; they are designed to increase throughput while maintaining process control, and in several cases to enable faster tech transfer between regions. For decision-makers, this signals that capacity is becoming more modular and more regionally distributed, which affects lead times, supply resilience, and the speed at which clinical programs can progress to commercial supply.
Policy and Regulatory Environment as a Competitive Filter
Regulatory evolution is now a meaningful driver of market structure. The introduction of peptide-specific manufacturing guidance, combined with heightened expectations around documentation and quality data integrity, has effectively acted as a competitive filter. Companies with mature GMP systems, robust analytical capabilities, and established drug master file infrastructure are better positioned to support advanced development and commercialization. Recent regulatory milestones, such as filings and acknowledgments tied to major peptide active pharmaceutical ingredients, illustrate how regulatory readiness is becoming a prerequisite rather than an afterthought. These events have also drawn attention to the importance of characterization, stability data, and clear demonstration of process control, especially for complex sequences.
The regulatory momentum has also elevated the strategic value of analytical support. Full-service characterization and synthesis support that align with IND/NDA expectations are increasingly viewed as essential components of a development plan. This is not simply about generating data; it is about designing a regulatory narrative that connects synthesis strategy, impurity profiles, and process consistency to clinical and safety outcomes. In practice, this means that manufacturers and service providers that can integrate synthesis, analytics, and documentation into a coherent package gain a measurable advantage in both speed and credibility.
For the market broadly, regulatory clarity reduces uncertainty but increases the premium on compliance maturity. Organizations that treat regulatory alignment as an ongoing capability rather than a one-time milestone are better positioned to manage the transition from early development to commercial launch, especially as guidance continues to mature across regions.
Demand-Side Shifts and Therapeutic Momentum
Demand is being reshaped by the expanding therapeutic footprint of peptides. The approval landscape for peptide-based interventions has widened, with notable regulatory actions that extend indications and reinforce long-term usage patterns. These developments have reinforced peptide therapeutics as a meaningful category, particularly where receptor targeting, metabolic pathways, or disease-specific pathways can be addressed with high selectivity. As a result, the demand base is no longer confined to early-stage research; it increasingly includes clinical supply and commercial manufacturing that must meet larger volumes, tighter schedules, and more demanding quality thresholds.
Beyond treatments, diagnostic applications continue to contribute to demand, especially where peptide ligands, biomarkers, and targeted detection tools are deployed. Research and development demand remains active as well, though its growth is increasingly tied to translational programs rather than exploratory academic work. The broader implication is that the demand profile is maturing into multiple layers: exploratory research, proof-of-concept clinical work, late-stage development, and commercial supply. Each layer carries different requirements, and the ability to serve across these layers without compromising quality or turnaround has become a defining strength for leading providers.
This multi-layer demand is also changing procurement behavior. Developers are looking for partners that can provide flexible scale, clear technical communication, and predictable quality systems, especially when programs move quickly toward pivotal studies or commercialization. The desire for reduced handoffs and clearer accountability is driving interest in integrated service models, where synthesis, purification, analytics, and regulatory support are coordinated within a single framework.
Gene Synthesis Market
Supply Chain Realignment and Cost Structure Pressures
Cost and supply chain dynamics are reshaping where and how peptides are produced. Reagent and consumable costs, solvent handling, purification efficiency, and yield losses all contribute to the economics of peptide manufacturing, and these factors become more pronounced as programs scale. In response, manufacturers are reassessing process design with a focus on resource efficiency and waste reduction. Where feasible, this has led to investments in closed-system workflows, improved recovery strategies, and more disciplined material usage, all of which contribute to cost control without sacrificing quality.
Regional supply considerations are also gaining importance. Organizations are weighing the benefits of regionalized manufacturing against the traditional model of concentrated production. Recent site expansions and commissioning in multiple geographies reflect a desire to build redundancy, reduce logistics complexity, and support closer interactions with development teams and regulatory authorities. At the same time, consolidation activity has begun to reshape the supply base, with larger players acquiring additional manufacturing capabilities to broaden geographic reach and strengthen capacity across regions. These moves suggest a market that is moving toward integrated networks rather than fragmented point solutions.
For commercial strategy, the supply chain shift has direct consequences. Manufacturers that can demonstrate reliable supply, transparent cost drivers, and scalable processes will have stronger negotiating positions as demand increases. Conversely, providers that cannot manage cost escalation or maintain consistency at scale risk losing share to more capable competitors or to alternative synthesis routes better suited to the program’s economics.
Competitive Landscape and Leading Strategies
Established Strengths and Differentiation Paths
The competitive field includes a mix of instrument and reagent specialists, custom synthesis providers, and large-scale peptide API manufacturers and CDMOs. These players are not competing on a single axis; rather, each is building differentiation around a distinct value proposition. One group centers on automation, instrument platforms, and enabling technologies that support reproducible synthesis workflows, particularly for research and development and early clinical work. Another group focuses on custom synthesis, GMP manufacturing, and commercial-scale peptide API production using established solid-phase and liquid-phase methods, often supporting programs from gram-scale to multi-ton operations. A third group emphasizes fully integrated services, including characterization, regulatory documentation, and compliance support aligned with development filings and commercial requirements.
What distinguishes the more successful players is the ability to connect scientific capability with operational scale and regulatory readiness. Firms that have built strong reputations typically do so by combining domain expertise with disciplined process control, transparent quality systems, and a willingness to invest in the infrastructure needed to support later-stage programs. In several cases, differentiation is also geographic, with multiple sites enabling regional support, faster transfer, and supply flexibility. This multi-site approach is increasingly relevant as programs seek resilience and faster response times without sacrificing compliance standards.
The competitive positioning of leading organizations reflects a broader market truth: in peptide synthesis, credibility is built on both technical performance and operational execution. A strong method or instrument alone is insufficient if it cannot be translated into consistent, documented, and scalable production. Likewise, manufacturing capacity is most valuable when paired with analytical depth and regulatory expertise. As a result, the most resilient companies are those that treat synthesis, analytics, and compliance as interdependent capabilities rather than separate functions.
Consolidation, Integration, and New Entrant Dynamics
The market is showing signs of consolidation through both facility investment and corporate action. Large expansions across multiple manufacturing sites have increased the available capacity for solid-phase synthesis and related services, while targeted acquisitions have extended geographic reach and manufacturing breadth. These developments point toward a landscape in which scale and geographic coverage are becoming more important, particularly for companies that want to support clients across regions and across the development continuum. At the same time, consolidation does not imply homogeneity. Differentiated capabilities remain critical because programs vary widely in sequence complexity, scale requirements, and regulatory pathways.
New entrants and specialized players continue to find space by targeting underserved needs. Some focus on niche synthesis technologies, others on analytical services, and others on regional service models that offer close collaboration and responsiveness. Their presence has the effect of raising the bar on service quality and encouraging more established players to improve flexibility and technical communication. For the market overall, this creates a dynamic environment in which incumbents must continually invest to maintain advantage, while newer players must demonstrate clear differentiation to secure sustained demand.
Strategic positioning is therefore increasingly about integration and optionality. Leading firms are building platforms that can accommodate different synthesis strategies, support multiple geographies, and provide analytical and regulatory support as part of a broader development partnership. This integrated posture is not only a growth strategy; it is a risk-management strategy, enabling providers to adapt as programs move from research to clinical to commercial stages without forcing the client to re-qualify multiple partners at each transition.
Looking Ahead: Three Strategic Trends for 2026 to 2032
Trend One: Process Scale and Modular Capacity as Standard Expectations
Over the next several years, scale-ready manufacturing and modular capacity will move from differentiators to baseline expectations. As more peptide programs advance toward commercialization, the demand for reliable multi-kilogram and commercial-scale supply will increase, and manufacturers will need to demonstrate that they can manage throughput, purification, and solvent management in a controlled and repeatable manner. The trend will favor organizations that can combine automation, process control, and capacity flexibility with strong quality systems. For buyers, this means that selection criteria will increasingly emphasize operational resilience and proven scale-up capability alongside scientific expertise.
The commercial opportunity here lies in service models that reduce friction across the development-to-commercial transition. Providers that can offer predictable timelines, clear scale-up pathways, and integrated analytics will be well positioned to capture demand from programs that want to avoid late-stage surprises. The risk, however, is that over-investment in capacity without corresponding demand realization could pressure utilization rates, especially if therapeutic programs face clinical setbacks or regulatory delays. Balancing capacity growth with disciplined demand forecasting will be essential.
Worldwide Customized Peptide Synthesis Market
Trend Two: Regulatory Maturity Becoming a Market Gatekeeper
Regulatory readiness will continue to act as a structural filter. As peptide-specific guidance matures and enforcement expectations become more consistent, the market will likely see a widening gap between organizations that treat compliance as a core capability and those that treat it as an administrative burden. The strategic implication is that regulatory alignment will increasingly influence partnership decisions, vendor selection, and long-term supply arrangements. Companies able to demonstrate robust documentation, characterization, and process control will have an advantage in supporting advanced development and commercial supply.
This trend creates opportunities for organizations that embed regulatory thinking early in the synthesis strategy, rather than layering it on later. Early alignment can reduce rework, accelerate transitions between development stages, and strengthen confidence for internal and external stakeholders. The uncertainty is that regulatory expectations may continue to evolve, which could require ongoing adjustment in analytical methods, documentation, and process controls. Market participants should therefore treat regulatory strategy as iterative, not static.
Trend Three: Technology Diversification and Sequence-Specific Sourcing
The next phase of market growth will likely be characterized by more deliberate technology selection rather than uniform reliance on a single synthesis method. As programs become more diverse in sequence length, complexity, and production requirements, the market will increasingly reward providers that can match the synthesis approach to the specific demands of the molecule. This includes the practical use of solid-phase synthesis for many applications, the selective use of solution-phase or hybrid methods where scale and economics justify them, and the use of automation or microwave-enabled workflows where speed and reproducibility are priorities.
PW Consulting Health Care Research Center
The commercial opportunity is in creating decision frameworks that help clients choose the right route earlier, reducing wasted effort and improving time to material. Providers that can articulate when and why a particular technology is appropriate, backed by demonstrated performance, will differentiate themselves in a crowded field. The risk is that technology claims outpace operational reality; credible differentiation will require consistent execution, not just capability descriptions. In practice, the winners will be those who can combine technical flexibility with disciplined delivery and transparent communication.
Strategic Actions for Decision-Makers
For Manufacturers and Service Providers
Focus on building integrated capability across synthesis, analytics, and regulatory readiness, rather than competing solely on price or instrument features. The market increasingly rewards providers that can guide programs through technical transitions with minimal handoffs and clear accountability. Invest in process control, solvent handling efficiency, and quality systems that can support both clinical and commercial requirements. At the same time, maintain technology optionality so that the most appropriate synthesis route can be selected for each program, rather than standardizing prematurely on one method. Regional presence and capacity modularity should also be treated as strategic assets, especially if they shorten timelines, improve resilience, and support faster responses to client needs.
For Investors
Evaluate exposure not only to current revenue but to the market’s structural drivers: capacity expansion aligned with realistic demand, regulatory maturity, and technology flexibility. The most durable investment cases will likely belong to organizations that can demonstrate the ability to serve multiple stages of development and to scale without compromising quality. Watch for consolidation activity that improves geographic reach or technical breadth, but scrutinize whether acquisitions are integrated in a way that strengthens execution rather than simply adding facilities. Be mindful of the risk that capacity built ahead of demand realization may create short-term pressure, particularly if clinical or regulatory timelines shift.
For Procurement and Development Teams
Prioritize partners that can show consistent performance across the stages your programs are likely to encounter. Evaluate providers based on their ability to manage scale-up, maintain quality documentation, and provide analytical support that aligns with development and regulatory needs. Ask explicitly about process control, turnaround predictability, and the degree to which synthesis and analytics are coordinated. Where possible, favor partnerships that reduce fragmentation and create clearer accountability across synthesis, purification, and characterization. Given the cost sensitivity of peptide manufacturing, also assess the economic logic of the chosen synthesis route and whether the provider’s approach is sustainable at the volumes and quality levels you expect to require.
Closing Perspective
The peptide synthesis market is entering a phase where growth is no longer driven by novelty alone but by the ability to deliver complex molecules with reliability, compliance, and commercial discipline. The data trajectory points to sustained expansion, but the real strategic story lies in how the market is reorganizing around scale, regulation, technology choice, and integrated service models. For executives, investors, and procurement leaders, the most valuable questions are shifting from whether peptides will matter to how to source, build, and partner in a way that matches the specific demands of each program. Detailed segmentation data, regional nuance, and company-level capability mapping can sharpen those decisions significantly, and a comprehensive market intelligence perspective can help translate broad trends into specific sourcing, investment, and development strategies.
For detailed analysis of this topic, please visit the official page: Peptide Synthesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
HGH Market to Hit $9.72B by 2032: The Structural Shifts Behind 8.52% CAGR
By pmarketresearch, 2026-09-21
Navigating the Human Growth Hormone Market: Strategic Trends and Commercial Opportunities Through 2032
The human growth hormone (HGH) market has entered a phase of deliberate expansion, characterized by steady revenue growth, evolving therapeutic applications, and a competitive landscape that rewards innovation in delivery mechanisms and patient-centric design. As procurement, R&D, and commercial strategy teams evaluate their positioning, understanding the structural forces shaping demand, regulatory pathways, and competitive differentiation becomes essential. The market is projected to grow from 5,530 million in 2025 to approximately 9,720 million by 2032, implying a compound annual growth rate of 8.52 percent across the 2026–2032 forecast horizon. This trajectory reflects more than incremental volume increases; it signals a maturing ecosystem where therapeutic value, dosing convenience, and real-world adherence are increasingly decisive commercial factors.
Follicle Stimulating Hormone Market
Market Snapshot and Core Challenges
The revenue trajectory across the 2020–2025 historical period demonstrates consistent expansion, with growth accelerating as therapeutic indications broaden and formulation innovations begin to translate into clinical adoption. The current market size and forward projections suggest that demand is not solely dependent on population growth or diagnostic expansion; rather, it is being reshaped by product lifecycle decisions, regulatory milestones, and shifting treatment paradigms. At the same time, the competitive structure remains moderately concentrated, with a handful of multinational manufacturers accounting for a significant share of total revenue—an environment that creates both stability and pressure for differentiation.
Several structural challenges are redefining how companies approach commercialization and portfolio strategy:
- Formulation and adherence friction continue to influence treatment persistence. Daily injection regimens have historically created logistical and compliance burdens for patients and caregivers. Even as manufacturing capabilities improve, the practical reality of long-term therapy means that dosing frequency, device usability, and training support remain central to real-world outcomes.
- Regulatory pathways are becoming more nuanced, not simply more permissive. Recent approval activity has expanded indications in both pediatric and adult populations, but each new label extension introduces new evidence requirements, competition dynamics, and reimbursement scrutiny. Companies must navigate a landscape where clinical differentiation and post-market data generation are increasingly tied to market access.
- Supply continuity is emerging as a commercial vulnerability. Intermittent constraints on established products highlight how demand surges, manufacturing complexity, and distribution readiness can intersect to create availability gaps. In a therapeutic category where treatment disruption can affect patient outcomes and provider trust, supply resilience is a strategic asset rather than an operational afterthought.
For decision-makers, the implication is straightforward: growth potential exists, but it is increasingly contingent on execution quality across formulation strategy, indication expansion, and supply reliability. Market momentum alone will not guarantee share performance if product design or access readiness lags behind competitor offerings.
Key Drivers Reshaping the Growth Hormone Landscape
Technology Innovation and Long-Acting Formulations
One of the most consequential shifts in the HGH market is the move toward less frequent dosing through long-acting and prodrug-based approaches. Weekly or extended-duration formulations are designed to address a practical bottleneck in chronic therapy: daily injection burden. By reducing dosing frequency, these products aim to improve adherence, simplify caregiver routines, and potentially enhance the patient experience across pediatric and adult use cases. The strategic importance of this innovation goes beyond convenience; it alters the commercial conversation by linking formulation science directly to persistence, which in turn influences therapeutic outcomes and provider preferences.
Recent regulatory activity underscores how rapidly this area is evolving. In mid-2025, regulators approved a long-acting product for adult growth hormone deficiency, extending the addressable population beyond pediatric care. Around the same period, a separate approval expanded pediatric indications for another long-acting therapy, including use in short stature born small for gestational age and Noonan syndrome. These milestones reflect a broader trend in which formulation innovation is being matched by indication expansion, creating multiple pathways for value creation. For manufacturers, the competitive question is no longer only whether a product works, but how well it fits into treatment routines, monitoring protocols, and long-term care plans.
Human Elisa Kits Market
Regulatory Evolution and Indication Expansion
The regulatory environment is facilitating broader use of growth hormone therapies while simultaneously raising the bar for evidence and differentiation. Approvals that extend treatment to new patient subgroups create commercially meaningful opportunities, but they also intensify scrutiny around comparative efficacy, safety profiles, and real-world performance. The result is a market in which regulatory success is increasingly linked to robust clinical development, clear therapeutic positioning, and post-approval data strategies that support reimbursement and adoption.
The expansion of pediatric indications illustrates this dynamic well. As labels grow to encompass additional diagnoses, manufacturers must demonstrate relevance across varied clinical contexts, each with distinct patient needs and provider expectations. At the same time, companies are pursuing supplemental applications to extend the reach of existing products. This pattern suggests a market where lifecycle management is becoming as important as initial launch performance. For strategic planners, regulatory momentum should be interpreted not just as a milestone, but as a trigger for downstream operational readiness: payer engagement, clinical support, and supply planning must align with the pace of label expansion.
Demand-Side Shifts Toward Broader Patient Populations
Demand is being shaped by a widening view of who benefits from growth hormone therapy. Historically, the category has been closely associated with pediatric deficiency and specific syndromic conditions. Today, growing recognition of adult growth hormone deficiency and expanded pediatric indications is broadening the commercial canvas. This shift carries several implications. First, it increases the long-term value of therapies that can serve patients across life stages or transition pathways. Second, it encourages providers to think beyond short-term treatment goals toward continuity of care, monitoring, and individualized dosing. Third, it elevates the importance of educational support and clinical service infrastructure, particularly where treatment decisions involve complex diagnosis or multidisciplinary care.
PW Consulting Health Care Research Center
Behaviorally, this means that procurement and clinical teams are increasingly evaluating products not only on unit economics, but also on how well a therapy integrates into care workflows and patient support programs. Companies that anticipate these demand-side expectations—through device design, educational materials, and service models—can differentiate even in a category with established therapeutic standards.
Supply Chain Sensitivity and Manufacturing Complexity
The HGH market also illustrates how supply-side dynamics can influence commercial reputation and market access. High-demand products have experienced intermittent availability constraints, reminding the industry that formulation complexity, production scale-up, and distribution readiness can become bottlenecks under growth conditions. These episodes matter because they intersect with patient reliance on continuous therapy. When supply is disrupted, the consequences extend beyond short-term lost volume; they can affect provider confidence and create openings for competitors with more resilient operations.
As demand broadens and long-acting options gain traction, manufacturers will need to treat supply chain resilience as part of product strategy. This includes capacity planning, redundancy in critical production steps, and proactive communication with procurement and clinical partners. In a concentrated market, operational reliability can become a competitive advantage as meaningful as formulation or indication breadth.
Competitive Landscape and Leading Strategies
The competitive environment is anchored by a mix of global pharmaceutical companies with established biosimilar and innovator portfolios, alongside specialized firms pursuing differentiated delivery technologies. Several players have built their positioning around long-acting or extended-dosing platforms, while others continue to compete on established daily formulations, manufacturing scale, and franchise breadth. The market’s moderate concentration suggests that incumbents hold meaningful share, but not to the degree that new formulations or indication-based differentiation cannot shift commercial dynamics.
Leading strategies in this space tend to converge around a few themes:
- Lifecycle extension through indication expansion. Companies are pursuing additional labels that widen the population eligible for therapy, often extending into pediatric subgroups or adult deficiency. This strategy increases the commercial relevance of existing products while requiring sustained clinical evidence and regulatory execution.
- Formulation-led differentiation. Extended-dosing technologies are being used to create clearer product distinction, emphasizing reduced injection frequency and improved convenience. Where these formulations reach approval across multiple indications, they can reshape prescribing preferences by aligning therapeutic value with patient and caregiver burdens.
- Portfolio breadth and franchise strength. Some manufacturers compete by maintaining a range of products across daily and long-acting formats, allowing them to serve varied clinical needs and procurement preferences. This approach can be particularly valuable when supply continuity or regional access requirements differ across markets.
- Partnerships and co-development arrangements. In certain cases, collaboration models have been used to combine development capabilities, commercialize long-acting options, or share the commercial burden of specialized products. These arrangements reflect the reality that innovation in this category often requires coordinated regulatory, manufacturing, and market-access execution.
The competitive landscape is likely to continue evolving along two parallel tracks. Incumbents with strong franchises and manufacturing infrastructure will seek to defend share through indication expansion, supply reliability, and service-oriented commercialization. At the same time, companies with differentiated delivery technologies may gain relevance by addressing adherence and convenience pain points more directly. New entrants and biosimilar-focused players can also influence pricing dynamics and availability, especially where multiple products compete in similar therapeutic niches. The result is a market that rewards both scientific innovation and execution discipline.
Forward Outlook: Three Trends to Watch
Trend 1: Extended-Dosing Formulations Will Reshape Adoption Patterns
Over the next several years, long-acting and weekly formulations are likely to occupy an increasingly prominent position in treatment discussions, particularly where adherence and caregiver burden are central concerns. If regulatory momentum continues and real-world evidence supports persistence benefits, these products could shift prescribing norms and expand the commercial relevance of convenience-driven differentiation. The opportunity for manufacturers lies in pairing formulation advantage with strong clinical support, device usability, and patient education. The risk is that benefit expectations outpace demonstrated outcomes or that access and reimbursement frameworks lag behind clinical approval, limiting the speed of adoption.
Trend 2: Adult and Expanded Pediatric Indications Will Broaden the Addressable Market
Growth in the category is expected to be supported not only by volume increases but also by broader indication use. Adult growth hormone deficiency and additional pediatric subpopulations represent commercially meaningful avenues, especially if diagnosis, referral, and treatment initiation pathways become more efficient. This trend suggests that companies should prepare for more diverse patient profiles and more varied care settings. Commercial strategies that rely on a narrow view of the patient journey may underutilize the market’s full potential. At the same time, expanded indications raise the importance of real-world data, safety monitoring, and payer alignment, since broader use invites closer scrutiny of cost-effectiveness and treatment protocols.
Trend 3: Supply Continuity and Operational Resilience Will Become Differentiators
As demand grows and product options multiply, supply reliability may emerge as a more visible competitive factor. Intermittent constraints on established products have already demonstrated how availability issues can affect provider trust and patient continuity. In the near term, companies that invest in capacity planning, production redundancy, and transparent communication may be better positioned to protect franchise value. This trend also carries a caution: scaling growth without sufficient operational readiness can create reputational and commercial risks that outweigh the benefits of rapid volume gains. For procurement and planning teams, this underscores the importance of evaluating supplier stability alongside price and product features.
Strategic Implications for Decision-Makers
The growth hormone market is offering a mix of therapeutic expansion, formulation innovation, and execution-driven competition. Different stakeholders will need to prioritize different aspects of this landscape.
For Manufacturers and Product Developers
- Evaluate lifecycle strategies that combine formulation innovation with indication expansion, ensuring that regulatory milestones are matched by supply readiness and market-access planning.
- Invest in patient and provider support infrastructure that reinforces adherence value, particularly for long-acting or less familiar treatment regimens.
- Treat manufacturing resilience as a strategic priority, not just an operational task, especially when pursuing growth in high-demand segments.
For Investors and Portfolio Strategists
- Focus on companies that can convert regulatory progress into durable commercial traction through real-world performance, access alignment, and reliable supply.
- Track the pace of adoption for extended-dosing products as an indicator of whether convenience-led differentiation translates into share movement.
- Monitor indication expansion timelines and reimbursement developments, since these often determine whether label breadth becomes revenue breadth.
For Procurement, Payer, and Clinical Leaders
- Assess products on a broader set of criteria, including dosing convenience, device usability, support programs, and supply reliability, alongside acquisition cost.
- Anticipate variability in availability and build contingency approaches for high-dependency therapies where interruptions can affect continuity of care.
- Align procurement strategy with clinical needs so that product selection reflects both economic and treatment-persistence considerations.
Across these roles, the recurring theme is that market opportunity is expanding, but capturing it depends on readiness across regulatory, commercial, and operational dimensions. Companies and buyers that evaluate the landscape with this integrated lens are better positioned to translate market growth into durable value.
For stakeholders seeking a more granular view of segmentation dynamics, regional revenue distribution, company-level positioning, and forward scenario analysis, the full market research report provides deeper detail across the metrics and sub-segments that support planning and investment decisions. Exploring that level of detail can help translate broad market direction into specific, actionable strategy.
For detailed analysis of this topic, please visit the official page: Human Growth Hormone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
RF Switches Market 2026: Beyond the 5.6% CAGR Story – PIN, GaAs, and MEMS Drivers
By pmarketresearch, 2026-09-21
Navigating the RF Switches Market: Strategic Trends and Commercial Opportunities Through 2032
The RF switches market has entered a phase of methodical expansion, underpinned by steady revenue growth from 2020 through 2025 and a projected compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. By 2025, total market revenue reached approximately 4.48 billion USD, with a clear trajectory toward 6.57 billion USD by 2032. This growth is not merely a reflection of incremental demand; it signals a structural shift in how radio frequency signal routing is designed, manufactured, and integrated across connected systems. The market’s expansion is broad-based, spanning mature telecommunications infrastructure, defense and aerospace platforms, industrial automation, and emerging satellite-linked communication networks. Yet beneath the headline numbers lies a more nuanced reality: technology transitions, regulatory pressures, and supply chain recalibration are simultaneously reshaping competitive positioning and creating asymmetric opportunities for firms that can anticipate rather than react to market shifts.
Pinpointing the Core Challenges and Market Inflection Points
Despite the favorable growth outlook, the industry is navigating several critical inflection points that will determine which players capture disproportionate value over the next five years. First, the coexistence of competing RF switch technologies is forcing design teams and procurement leaders to make increasingly complex trade-offs. PIN diode switches remain widely deployed for cost-sensitive and high-power applications, while GaAs and SOI/SOS platforms continue to dominate where isolation, linearity, and insertion loss are paramount. MEMS switches and emerging silicon-based alternatives are gradually gaining traction in scenarios where power consumption, footprint, and reliability must be optimized simultaneously. The absence of a single dominant architecture means that technology selection is becoming increasingly application-specific, raising integration complexity and lengthening qualification cycles for OEMs.
Second, the rapid expansion of low Earth orbit satellite constellations is introducing both demand tailwinds and spectrum management friction. Regulatory filings and policy analyses indicate that satellite production growth is outpacing existing coordination frameworks, creating heightened concerns over radio interference and orbital slot allocation. As operators scale constellations from thousands to tens of thousands of satellites, the RF front-end ecosystem—including switching, filtering, and amplification subsystems—must accommodate higher throughput, broader frequency coverage, and tighter thermal and reliability constraints. This dynamic is simultaneously opening new procurement pipelines for aerospace and defense suppliers while forcing terrestrial and wireless communication vendors to navigate increasingly crowded spectral environments.
Third, infrastructure deployment strategies are evolving in ways that reshape regional demand patterns. Broadband expansion initiatives are increasingly emphasizing microtrenching, surface-level deployments, and hybrid fiber-wireless architectures, which influence the mix of RF components required for last-mile and mid-mile connectivity. At the same time, sovereign spectrum rights and orbit governance frameworks are reinforcing the strategic importance of localized component sourcing, testing, and compliance. Together, these forces are pushing the market away from commoditized volume plays and toward differentiated, application-engineered solutions where switching performance, environmental ruggedness, and lifecycle support carry greater commercial weight.
Decoding the Key Demand Drivers Reshaping Revenue Trajectories
The market’s growth is being propelled by a convergence of technological, regulatory, and demand-side forces that reinforce one another rather than operate in isolation. Technological innovation remains the most direct catalyst. Recent product introductions from established manufacturers illustrate how switch architectures are being refined to meet the stringent requirements of radar, electronic warfare, broadband infrastructure, and high-reliability communications. Advancements in SOI-based SPDT platforms, high-isolation SPST/SPDT series, reflective antenna tuning switches, flip-chip architectures, and GaN-enabled high-power switching solutions demonstrate a clear industry emphasis on improving isolation, reducing loss, and expanding frequency ranges. These improvements are not incremental refinements; they enable system designers to consolidate RF paths, reduce module count, and improve overall signal integrity in increasingly dense electromagnetic environments.
Policy and regulatory developments are simultaneously acting as both an enabler and a constraint. The broadening of LEO satellite constellations has triggered heightened scrutiny around spectrum allocation, interference mitigation, and orbital coordination. Regulatory bodies and government analyses are increasingly emphasizing careful spectrum management and sovereign rights over orbital and frequency resources. For RF switch suppliers, this translates into a dual dynamic: expanded opportunities in satellite-linked communication ecosystems and test-and-measurement infrastructure, alongside stricter qualification requirements and a growing premium on components that can operate reliably under congested spectral conditions. The regulatory environment is effectively raising the barrier to entry for generic switching solutions while rewarding vendors with documented compliance, robust testing protocols, and application-specific design support.
Demand-side behavior is shifting as well. Cellular and wireless communication networks continue to anchor a substantial share of RF switch consumption, but the nature of that demand is changing. Base station architectures, antenna tuning systems, and broadband access equipment are becoming more modular and software-defined, requiring switching components that can adapt to dynamic reconfiguration without sacrificing performance. At the same time, industrial and automotive applications are gaining prominence as connectivity expands beyond traditional telecom into factory automation, vehicle-to-infrastructure communication, and sensor-heavy environments. These sectors demand switches that can tolerate harsher operating conditions, sustain long service intervals, and integrate cleanly into mixed-signal architectures. The result is a broadening of the demand base that reduces reliance on any single vertical while increasing the need for segmented product strategies.
PW Consulting Information & Electronics Research Center
Supply chain and cost structure dynamics round out the driver set. The concentration of revenue among a relatively small group of leading suppliers indicates that scale, technology maturity, and strategic customer relationships continue to confer meaningful advantages. At the same time, the market’s evolution toward specialized high-reliability and high-isolation solutions is elevating the importance of production consistency, material sourcing, and qualification documentation. Cost pressures persist, particularly in consumer-facing and mass-market wireless applications, but they are increasingly offset by value migration toward performance-critical segments where switching reliability, thermal handling, and integration flexibility directly influence system economics. The net effect is a market where cost leadership alone is no longer sufficient; competitive advantage is being redefined around design enablement, lifecycle support, and application-specific performance guarantees.
Competitive Landscape and the Strategies Defining Market Leadership
The competitive environment reflects a market that is neither fully consolidated nor fragmented beyond coherence. A concentrated core of established manufacturers anchors supply in defense, aerospace, telecommunications, and test-and-measurement applications, each pursuing distinct yet overlapping strategic positions. Leading players are differentiating not simply through product breadth, but through architecture specialization, application-specific tuning, and long-term ecosystem relationships that extend beyond component sales.
Network Switches Market
Companies focused on high-performance semiconductor-based switching are emphasizing platform continuity and portfolio expansion. Recent announcements in the first half of 2026 illustrate this pattern clearly. Qorvo introduced new X-Band amplifiers, GaN transistors, and SOI SPDT RF switches targeting defense, aerospace, radar, electronic warfare, communications, and DOCSIS 4.0 broadband applications, signaling a deliberate push to align switching solutions with high-growth, high-reliability segments. pSemi expanded its UltraCMOS+ portfolio with new high-isolation RF switches, reinforcing a strategy centered on isolation performance and integration simplicity for demanding RF front-end designs. Skyworks Solutions has continued to emphasize reflective antenna tuning switch architectures that support beamforming, coverage optimization, and adaptive impedance matching in advanced wireless systems. Analog Devices maintains a strong position in flip-chip SP4T switching for test and measurement and cellular applications, where repeatability, calibration stability, and signal path integrity are critical. MACOM’s reflective SPDT switches remain relevant across WiFi, Bluetooth, and base station ecosystems, particularly where rapid reconfiguration and compact integration are valued.
Parallel to these semiconductor-centric strategies, a cohort of suppliers is strengthening their position in electromechanical, coaxial, waveguide, and high-reliability switching for environments where solid-state alternatives face thermal, power-handling, or failure-mode constraints. Teledyne Microwave Solutions and Teledyne Relays & Coax Switches provide surface-mount and latching multi-throw coaxial switching that support communications systems and aerospace and defense deployments requiring extended lifecycle durability and deterministic switching behavior. JFW Industries’ absorptive failsafe switches and Dow-Key Microwave’s custom coaxial, waveguide, and space-grade switches highlight a persistent premium on tailored solutions for high-power and mission-critical scenarios. Narda-MITEQ and Pasternack Enterprises continue to serve wireless communication and test-and-measurement markets with reflective and electromechanical transfer switches that prioritize repeatability, isolation, and serviceability. Planar Monolithics Industries and Radiall reinforce the broader ecosystem with solid-state and microwave-component switching options that address military, industrial, and component-integration requirements.
The strategic lesson from this landscape is that leadership is increasingly defined by the ability to match switching technology to the failure modes, environmental constraints, and reconfiguration requirements of the end application. Firms that treat RF switches as interchangeable commodities risk margin erosion and displacement by suppliers offering integrated design support, application-specific qualification packages, and lifecycle reliability documentation. Conversely, suppliers that align product roadmaps with defense/aerospace ruggedness, broadband infrastructure scalability, satellite communication frequency expansion, and test infrastructure repeatability are positioning themselves to capture more resilient demand streams. The market is also showing signs of gradual consolidation pressure, as acquisition interest in specialized high-reliability portfolios and niche antenna-tuning platforms intensifies. At the same time, new entrants and smaller specialist firms can still find room in custom configurations, ultra-high isolation niches, and application-tailored electromechanical solutions where incumbents face limits in standard product coverage.
Forecasting the Next Phase: Three Trends to Watch Through 2032
The next three to five years will likely be shaped by a blend of technology migration, demand diversification, and ecosystem coordination challenges. The first trend is the continued broadening of application-specific switch architectures. As systems grow more software-defined and frequency-agile, RF switches will need to support dynamic reconfiguration, lower loss across wider bands, and improved robustness against interference. The commercial opportunity lies in developing modular switching families that can be rapidly adapted across cellular, broadband, satellite-linked, and industrial use cases without requiring full redesign cycles. Suppliers that can offer configurable isolation levels, compact integration footprints, and predictable thermal behavior will be better positioned to win in environments where system architects must balance performance, cost, and deployment speed.
Worldwide High Isolation RF Switches Market
The second trend is the deepening integration of RF switching into high-reliability and satellite-adjacent ecosystems. The scaling of LEO constellations and the growing emphasis on spectrum discipline are expanding the need for components that can operate across extended frequency ranges, withstand harsh environmental conditions, and satisfy rigorous qualification standards. This trend favors suppliers with documented aerospace and defense heritage, robust testing capabilities, and the ability to support long-lifecycle deployment models. Commercial upside will accrue to firms that can bridge the gap between terrestrial wireless demand and space-linked communication requirements, particularly where switching reliability directly affects link stability, interference resilience, and maintenance intervals.
The third trend is the gradual rebalancing of supply chain risk and regional procurement preferences. As regulatory frameworks reinforce sovereign rights over spectrum and orbital resources, and as infrastructure plans increasingly emphasize localized broadband expansion, procurement teams are placing greater weight on supply continuity, traceability, and compliance documentation. The commercial implication is a market where regional service capability, testing support, and component qualification transparency increasingly influence purchasing decisions alongside unit economics. Firms that can demonstrate consistent production quality, application engineering support, and resilient sourcing will be better positioned to retain strategic accounts and capture new programs that prioritize supply assurance over lowest-cost sourcing.
These trends carry embedded risks. Technology choices that appear advantageous today may face obsolescence pressure if network architectures shift toward new frequency plans, beamforming strategies, or integrated RF modules that reduce discrete switch count. Regulatory uncertainty around spectrum allocation and orbital coordination could delay program timing or alter component specifications mid-cycle. Cost pressure in high-volume wireless and consumer-adjacent applications could compress margins for suppliers that fail to differentiate on performance or lifecycle support. Finally, consolidation activity may accelerate, altering supplier relationships and forcing customers to reevaluate qualification pipelines, second-source strategies, and long-term roadmap alignment.
Strategic Actions for Decision-Makers Across the Value Chain
For manufacturers and product leaders, the priority is to align switch roadmaps with the applications where performance differentiation is both measurable and commercially rewarded. This means investing in architectures that improve isolation, reduce loss, and support broader frequency coverage while maintaining production consistency and qualification clarity. Teams should prioritize modular product families that can be adapted across cellular, broadband, satellite-adjacent, and industrial environments without fragmenting engineering resources. Equally important is strengthening design-in support: application notes, integration guidance, thermal and reliability documentation, and test-proven reference configurations can materially accelerate adoption in programs where switching performance affects overall system performance. Manufacturers should also evaluate second-source strategies and supply assurance capabilities early, since procurement teams increasingly weigh continuity and traceability alongside technical specifications.
For investors and corporate development teams, the market offers segmentation-specific opportunities rather than a uniform growth story. High-reliability aerospace and defense switching, broadband infrastructure expansion, and satellite-linked communication ecosystems represent segments where technical differentiation and qualification depth translate into more defensible revenue streams. In contrast, commoditized high-volume segments may deliver volume but limited margin expansion unless paired with integration advantages or platform-level partnerships. Due diligence should therefore focus on product roadmaps, technology ownership, qualification pipelines, customer concentration, and the ability to support long-lifecycle deployments. Portfolio construction should weigh the trade-off between scale-driven semiconductor platforms and specialized electromechanical or high-power solutions, recognizing that both can be attractive but require distinct execution models and customer engagement strategies.
For procurement and systems integration teams, the strategic emphasis should shift from unit price alone toward total cost of qualification, integration risk, and lifecycle reliability. Switching components that reduce design iterations, simplify calibration, and deliver predictable behavior under real-world thermal and interference conditions can lower program risk and shorten deployment timelines. Procurement strategies should incorporate supplier capability in application engineering, testing support, and documentation quality, particularly for programs where RF path integrity directly impacts throughput, coverage, or mission reliability. Where possible, qualification planning should account for regulatory evolution in spectrum management and orbital coordination, ensuring that selected components remain suitable as frequency plans, interference conditions, and system architectures evolve over the program lifecycle.
The RF switches market is expanding within a framework that rewards clarity of application focus, technical differentiation, and supply assurance. Executives who map their strategies to the segments where switching performance, reliability, and integration flexibility carry financial weight will be better positioned to capture value as the market moves from steady growth toward more segmented, performance-driven competition. For organizations seeking deeper segmentation data, region-specific demand patterns, detailed competitive benchmarking, and tailored scenario planning, the full research report provides the additional granularity required to translate these market-level insights into executable commercial decisions.
For detailed analysis of this topic, please visit the official page: RF Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PICV Market Growth at 4% CAGR: Commercial & APAC Drivers Redefining Pressure Control Strategy
By pmarketresearch, 2026-09-21
Strategic Horizons: Navigating the Pressure Independent Control Valves Market
The Pressure Independent Control Valves (PICV) market has transitioned from a specialized engineering niche to a critical component of modern hydronic system design. With a global market valuation of USD 295.0 Million in 2025, the sector reflects a broader shift toward energy-efficient building operations and variable-flow HVAC architectures. The market has demonstrated consistent growth, expanding from USD 220.0 Million in 2020 at a compound annual growth rate (CAGR) of 4.0 percent through the forecast period extending to 2032. While the historical trajectory shows steady expansion, reaching USD 387.0 Million by 2032, the market is not without its complexities. Investors and strategic planners must understand not just the headline figures, but the underlying structural dynamics, competitive positioning, and technological inflection points that will determine long-term value creation.
For enterprise decision-makers, the PICV market represents a convergence of regulatory pressure, technological advancement, and evolving operational performance expectations. The widespread adoption of PICVs is no longer merely a technical preference; it is increasingly a compliance and performance imperative. ASHRAE 90.1 standards, for instance, require a 50 percent reduction in energy consumption in initial building models, and PICV technology has proven capable of delivering 20-40 percent HVAC energy performance improvements through stable flow management and reduced system inefficiency. This regulatory backdrop creates a structural tailwind that transcends short-term economic cycles, anchoring demand in long-term building performance mandates rather than discretionary capital expenditure.
Diverter Valves Market
Market Context And Structural Challenges
A Market In Transition
The PICV market's expansion to a projected USD 387.0 Million by 2032 is underpinned by a 4.0 percent CAGR, yet this aggregate figure masks regional and application-level variations that demand careful strategic navigation. Asia Pacific represents the largest revenue contribution at USD 100.65 Million, followed by Europe at USD 75.83 Million and North America at USD 69.01 Million, with Latin America and the Middle East and Africa each contributing approximately USD 24.7 Million and USD 24.81 Million respectively. On the application side, commercial buildings account for USD 159.26 Million of total revenue, residential applications contribute USD 81.36 Million, and industrial use cases represent USD 54.38 Million. By product type, threaded PICVs generate USD 160.47 Million while flange PICVs account for USD 134.53 Million. The market exhibits moderate concentration, with the top three players holding 32.0 percent and the top five commanding 48.0 percent of total market share.
These figures point to a market that is broad-based but increasingly competitive at the margins. The commercial segment's dominance reflects the ongoing retrofit and modernization of office, retail, and institutional buildings where system balancing and energy accountability are paramount. Residential growth, while smaller in absolute terms, is being propelled by higher HVAC adoption rates in new housing developments and stricter energy codes in multiple jurisdictions. Industrial applications, though the smallest segment, are gaining attention due to the thermal control demands of data centers, manufacturing facilities, and processing plants where precise flow regulation translates directly into operational cost savings.
Key Challenges And Inflection Points
Despite favorable long-term demand drivers, the PICV market faces several structural challenges that will shape competitive outcomes over the next five years. First, installer and commissioning expertise remains a bottleneck. PICV technology delivers its full value only when properly sized, integrated, and calibrated within the broader hydronic system. In markets where skilled HVAC technicians are in short supply, the performance gap between theoretical efficiency gains and realized outcomes can undermine customer confidence and slow adoption. This operational dependency means that product innovation must be paired with training, documentation, and commissioning support to sustain market momentum.
Second, the market is navigating a tension between standardization and customization. End-users increasingly demand valves that can handle wider flow ranges, integrate with building automation platforms, and support variable-flow optimization without requiring separate balancing valves. However, engineering more versatile products can increase manufacturing complexity and cost. Companies that can streamline the balance between modular design, scalability, and application-specific performance will gain a significant advantage in both commercial and industrial segments.
Pinch Valve Market
Third, certification and compliance requirements are becoming more stringent across regions. UL certification and ISO 9001:2015 compliance are now baseline expectations for commercial and industrial PICV applications, and product documentation, including Environmental Product Declarations, is increasingly tied to procurement decisions in sustainability-driven markets. Firms that treat compliance as a strategic capability rather than a checkbox exercise will be better positioned to secure specifications in large-scale tenders and public-sector projects.
Key Drivers Of Market Change
Regulatory And Energy Performance Mandates
Policy and regulatory frameworks are the most durable demand driver for PICVs. Standards such as ASHRAE 90.1 impose rigorous energy performance thresholds on new construction and major renovations, creating a compliance pathway that favors variable-flow hydronic systems with pressure-independent control. The ability of PICVs to maintain stable flow irrespective of pressure fluctuations directly reduces pump energy consumption, improves delta-T performance, and minimizes inefficient operation during part-load conditions. These outcomes align directly with building energy codes and green building certification requirements, making PICVs a pragmatic solution for developers, facility managers, and engineering consultants seeking to meet mandated targets without overbuilding system capacity.
Technological Innovation And Smart Integration
Technological advancement is transforming PICVs from passive balancing devices into active, data-enabled components of the building control ecosystem. Leading manufacturers are embedding IoT connectivity, integrated energy measurement, and actuator interfaces that support seamless integration with building automation systems. Products such as Danfoss AB-QM 4.0 and AB-QM series with NovoCon actuators, Belimo PIQCV and Energy Valve™ IoT-connected PICVs, and Johnson Controls VP140 Series and XT-range valves illustrate this shift toward combined balancing, control, and monitoring functionality. Siemens' integrated PICVs that combine differential pressure control, regulation, and 2-port valve functions further demonstrate how multi-function design is reducing the number of components required for commissioning, simplifying installation, and improving system reliability.
Recent product activity underscores the pace of this innovation cycle. Danfoss released updated data sheets and brochures for its AB-QM 4.0 PICVs and actuators in early and mid-2026, alongside Environmental Product Declarations for multiple variants, signaling a strategic emphasis on both technical performance and sustainability documentation. Griswold Controls showcased its Energy FIT system and actuator integrations at the AHR Expo 2026, highlighting the growing importance of energy-focused commissioning and monitoring capabilities. ISMA Controlli's LIBRA PICV range update in May 2026 further illustrates how manufacturers are continuously refining dynamic circuit control performance to meet evolving application requirements. These developments are not isolated product updates; they reflect a broader industry move toward valves that support both hydraulic performance and operational visibility.
Demand-Side Shifts In Building Operations
Demand-side behavior is changing in ways that favor PICV adoption. Building automation infrastructure expansion is accelerating, driven by asset owners seeking to reduce operational expenditures, improve tenant comfort, and meet sustainability commitments. At the same time, smart building adoption and heightened indoor air quality awareness are increasing the role of precise environmental control in specification decisions. PICVs with integrated control and monitoring features are increasingly valued because they provide system-level visibility that supports predictive maintenance, fault detection, and performance optimization. This demand-side preference is particularly pronounced in commercial real estate, where energy intensity and occupancy variability make stable flow control a strategic operational asset.
Supply Chain And Material Considerations
Cost structures and material choices are becoming a more visible competitive dimension. Scaling- and clogging-resistant polymer components in PICV designs are increasingly favored because they support long lifetime and reliability under varying operating conditions, reducing maintenance interventions and extending service intervals. At the same time, manufacturers must manage raw material availability, production consistency, and lead-time volatility across global supply chains. Companies that can secure reliable sources of high-performance polymers, standardize insert and body geometries where feasible, and maintain quality assurance systems aligned with ISO 9001:2015 will be better positioned to manage cost volatility while preserving product performance.
Competitive Landscape And Strategic Positioning
Leading Players And Differentiation Strategies
The PICV market is characterized by a diverse competitive set spanning established multinational manufacturers, specialized valve producers, and regional specialists. Danfoss has built a strong position around its AB-QM 4.0 and AB-QM series, emphasizing stable flow, energy savings, and commissioning ease through actuator-compatible pressure-independent balancing and control valves for heating and cooling applications. Belimo competes with a focus on precision hydronic control and energy measurement, leveraging its PIQCV, EPIV, and Energy Valve™ IoT-connected PICVs to address variable-flow optimization and operational data integration. Johnson Controls differentiates through the VP140 Series and XT-range PICVs, which are designed to eliminate the need for separate balancing valves and streamline stable flow performance within building automation contexts. Siemens takes an integration-led approach, combining differential pressure control, regulation, and 2-port valve functions in a single device to optimize delta-T and commissioning outcomes.
In the Americas, Bray International offers the SS Series and SSM Series for threaded and flanged applications respectively, emphasizing dynamic balancing and high-rangeability control in hot and chilled water systems. Griswold Controls has built recognition around its PIC-V®, MVP®, Pinnacle, and PIM series designed to replace separate balancing and control pairs in HVAC, with strong exposure in data center and industrial applications through its Tiger Controls partnership ecosystem. Xylem contributes with Bell & Gossett Ultra Setter PICVs and Press Connect fittings aimed at simplifying balancing and control adjustments. In Europe, Frese A/S maintains specialized PICV lines for Nordic and broader European hydronic applications, while Caleffi's FLOWMATIC and other PICV series address residential and commercial HVAC balancing. IVAR's LIBRA range targets dynamic circuit control in Southern European markets, supported by recent product updates. IMI PLC, Cranfield, Pettinaroli, FAR, and Schneider Electric reinforce the diversity of the competitive field, each bringing distinct strengths in portfolio breadth, regional reach, or integration with building services and automation platforms.
This breadth of offerings creates a market where differentiation occurs along several axes: product range and size coverage, actuation and IoT compatibility, commissioning and documentation support, certification and sustainability credentials, and integration with wider building services ecosystems. Companies that can demonstrate consistent performance across these dimensions are increasingly favored in specification processes, particularly where multi-vendor or multi-building deployments require standardization and reliable technical support.
Market Evolution: Consolidation, Fragmentation, And New Entrants
The market's moderate concentration, with the top five players holding 48.0 percent of revenue, suggests room for both consolidation and continued fragmentation. Larger players with broad building automation or HVAC portfolios can leverage PICVs as part of integrated solutions that span valves, controllers, and system commissioning services. This integration advantage can be decisive in large commercial and institutional projects where single-point accountability and system-level optimization are valued. At the same time, specialized manufacturers with strong technical reputations in specific regions or applications can compete effectively by focusing on differentiated features such as wide flow coverage, insertion-based designs, high-rangeability control, or targeted industrial-grade performance.
PW Consulting Automotive & Machinery Research Center
The potential for further consolidation exists, particularly where manufacturers seek to expand product portfolios, geographic reach, or commissioning capabilities. Conversely, continued fragmentation is likely where regional standards, application requirements, and installer preferences diverge. New entrants may find opportunity by addressing underserved niches, such as data center thermal control, high-performance industrial hydronic systems, or application-specific PICVs optimized for quick commissioning and minimal maintenance. The strategic question for incumbents and entrants alike is whether to compete on portfolio breadth and integration or on focused technical excellence and service depth.
Future Trends And Commercial Opportunities
Trend 1: Energy Accountability As A Procurement Driver
Over the next three to five years, energy accountability will become a more explicit factor in procurement decisions. As building operators face rising energy costs and tighter performance reporting requirements, PICVs that deliver demonstrable flow stability, reduced pump energy, and improved delta-T performance will be prioritized in both new construction and retrofit projects. The opportunity lies in building specification support tools, performance documentation, and case-study evidence that translate technical performance into operational and financial outcomes for facility owners and engineering consultants. Companies that can connect PICV performance to energy modeling outputs, commissioning checklists, and ongoing monitoring will be better positioned to win specifications and reduce post-installation rejection risk.
Trend 2: Smart Hydronics And Data-Enabled Control
The integration of PICVs with building automation, energy measurement, and monitoring platforms will continue to deepen. This trend opens opportunities for manufacturers and solution providers to offer valves that are not just flow control devices but data-generating components within a broader operational intelligence framework. Features such as actuator compatibility, IoT readiness, and integrated energy measurement are likely to become standard expectations in commercial and increasingly in industrial applications. The commercial opportunity extends beyond hardware to include commissioning services, performance tuning, and software-enabled diagnostics that help operators sustain efficiency over the asset lifecycle. However, this trend also introduces risk if interoperability, data security, and support infrastructure are not addressed comprehensively.
Trend 3: Regional Divergence And Application Specialization
Regional and application-level divergence will create both opportunities and constraints. Asia Pacific's scale and ongoing infrastructure and building development activity present a large addressable market, but success there depends on local specification practices, distributor networks, and installer training. Europe's mature building stock and stringent energy standards support demand for retrofits and replacements, favoring manufacturers with strong technical documentation, certification, and service networks. North America's commercial segment remains a significant demand center, with data center and industrial applications gaining relevance as thermal control requirements intensify. In this environment, a one-size strategy is unlikely to succeed. Companies that align product ranges, certification, and support to regional requirements, and that develop application-specific offerings for sectors such as data centers, commercial high-rises, and industrial processing, will capture more defensible growth.
Risk Considerations
These opportunities are accompanied by risks that warrant strategic attention. Installer capability gaps can erode realized performance and weaken customer satisfaction, particularly in markets where technical training and commissioning support are under-resourced. Certification and compliance complexity may increase procurement timelines and raise costs for manufacturers operating across multiple jurisdictions. Material price volatility and supply chain disruptions can affect margins and lead times, especially for products relying on specialized polymers or insert technologies. Finally, as smart integration becomes more central, firms that fail to address interoperability, cybersecurity, and software support may face reputational and commercial consequences. Managing these risks will be as important as capturing the demand upside.
Strategic Guidance For Decision Makers
For Manufacturers
- Prioritize product architectures that balance flow range, sizing flexibility, and installation simplicity, reducing the need for separate balancing components while maintaining high rangeability and reliability.
- Invest in commissioning support, training assets, and clear documentation, including Environmental Product Declarations and certification alignment, to strengthen specification win rates and reduce post-installation performance gaps.
- Develop integration pathways with building automation and energy monitoring platforms that are transparent, interoperable, and supported by service commitments, turning hardware capability into long-term value.
For Investors
- Evaluate exposure not only by revenue scale but by alignment with structural demand drivers such as energy code tightening, smart building adoption, and application growth in data centers and industrial thermal control.
- Assess manufacturing resilience, material sourcing, and certification readiness as indicators of margin stability and risk management capability in a moderately concentrated market.
- Identify companies with credible technical differentiation, strong commissioning support, and regional execution strength, as these attributes tend to translate into more durable specification positions and customer retention.
For Procurement And Specification Teams
- Treat PICV selection as a system-level decision that should account for flow stability, commissioning ease, energy performance evidence, and integration requirements rather than unit price alone.
- Require robust performance documentation, certification alignment, and clear service commitments from suppliers to reduce variability across projects and improve long-term operational outcomes.
- Engage early with engineering and commissioning teams to ensure valve sizing, actuator compatibility, and building automation integration are addressed before procurement, minimizing rework and performance shortfalls.
The PICV market is moving through a phase where regulatory mandates, technological integration, and operational accountability are reshaping both demand and competition. For stakeholders seeking deeper segmentation, regional dynamics, application-level sizing, and customized strategic recommendations, PW Consulting's comprehensive PICV market report provides the detailed data and analysis needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Pressure Independent Control Valves (PICV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Overactive Bladder Treatment Market: Why 4.88% CAGR and Shifting Therapies Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Overactive Bladder Treatment Market
The overactive bladder treatment market has entered a phase of structural transition, moving beyond incremental drug innovation toward device-based interventions and more flexible care pathways. Total market revenue reached approximately $424 million in 2025, reflecting steady expansion from the $334 million recorded in 2020. Over the next seven years through 2032, the market is projected to grow at a compound annual growth rate of 4.88%, culminating in revenue of roughly $592 million. This trajectory signals a maturing landscape where value creation will increasingly depend on how well companies align product development, reimbursement positioning, and clinical adoption rather than on volume-driven generic substitution alone.
Despite the consistent upward revenue trend, the pace of growth and the distribution of value are being reshaped by several concurrent forces. Demographic aging continues to expand the addressable patient population, yet payer environments, guideline frameworks, and technology adoption patterns are introducing new decision points for manufacturers and investors. The market is no longer defined solely by pharmaceutical volume; it is becoming a contest over clinical differentiation, procedural convenience, and the ability to demonstrate clear patient and economic outcomes.
Three challenges are particularly prominent at this inflection point. First, the traditional reliance on anticholinergic therapies is being rebalanced by safety and tolerability considerations, prompting a slower but meaningful shift toward alternative mechanisms and procedural options. Second, reimbursement variability across care settings is influencing where and how treatments are delivered, especially for device-based therapies that require distinct coding, coverage, and site-of-care strategies. Third, the competitive field is consolidating around a smaller set of players with broad portfolios, even as targeted innovators continue to introduce niche solutions that test the boundaries of standard care models.
Key Drivers Reshaping Market Momentum
Several forces are driving the current evolution of the market, and their interplay is changing both the pace of adoption and the strategic priorities of participating companies.
Technology Innovation and Breakthroughs
Innovation momentum is strongest in two areas: refined pharmacologic options and minimally invasive neuromodulation. In pharmacotherapy, newer beta-3 adrenergic agonists have provided alternatives with more favorable tolerability profiles for patients who struggle with anticholinergic side effects. In device-based care, recent approvals and engineering improvements are reducing procedural burden and expanding access to sacral and tibial neuromodulation for urge incontinence and overactive bladder symptoms. These technologies are important not only because they offer additional treatment options, but because they create opportunities to segment patients by symptom severity, treatment history, and preference for drug-free management.
The practical implication is that clinical differentiation is becoming a more valuable asset than broad label coverage alone. Devices that simplify implantation, programming, or follow-up can accelerate adoption in clinical settings that previously hesitated due to complexity or resource requirements. Similarly, oral therapies that address specific patient subgroups, including those receiving concurrent treatment for benign prostatic hyperplasia, can unlock incremental demand in crowded therapeutic categories.
Policy and Regulatory Environment
Regulatory and guideline developments are actively reshaping treatment sequencing and payer behavior. Updated clinical guidelines from leading urology and pelvic floor societies have moved away from rigid step therapy requirements in favor of shared decision-making. This shift gives clinicians more latitude to select treatments based on patient profiles and preferences, which can accelerate the uptake of both newer drugs and procedural therapies in appropriate populations.
At the same time, reimbursement policy is exerting a powerful influence on site of care and technology uptake. Notably, CMS increased reimbursement by 40% in the ambulatory surgery center setting for a tibial nerve stimulation procedure, a change that can affect where patients receive care and how providers evaluate procedural investments. Regulatory milestones such as PMA approvals for integrated sacral neuromodulation systems also matter because they validate new device architectures and can expand the commercial footprint for companies pursuing differentiated procedural solutions.
Demand-Side Changes in Patient and Clinician Behavior
On the demand side, patients are increasingly seeking treatments that minimize systemic side effects and preserve quality of life. This preference is particularly relevant for long-term management, where adherence and tolerability determine real-world effectiveness. Clinicians, in turn, are responding to the combined influence of updated guidelines, richer outcome data, and practical workflow considerations. Shared decision-making is not merely a philosophical shift; it is changing the order in which therapies are discussed and selected, especially when patients present with comorbidities or prior treatment intolerance.
For commercial teams, this means that messaging and market access strategies must address real-world usability as much as efficacy. Treatments that are easier to initiate, monitor, and sustain are more likely to be prioritized in busy clinical environments, especially when they can be aligned with patient-centered goals and reimbursement realities.
Supply Chain and Cost Structure Dynamics
Cost structures across the market are being influenced by a combination of manufacturing complexity, procedural economics, and competitive pressure. Pharmaceutical segments face the usual balance between branded differentiation and eventual generic erosion, while device segments contend with the economics of implantation, training, service, and follow-up. In both cases, the value proposition increasingly depends on total cost of care rather than unit price alone.
This environment rewards strategies that can demonstrate downstream savings, reduce repeat interventions, or simplify the care pathway. For procedural technologies, site-of-care optimization and reimbursement alignment can be as important as the device itself. For drug therapies, lifecycle planning and patient-support programs can help protect share in categories where clinical alternatives are expanding.
Competitive Landscape and Leading Strategies
The market’s competitive structure reflects a blend of large established players, device specialists, and focused innovators. Market concentration remains moderate, with the top three companies accounting for roughly 40% of revenue and the top five approaching 50%, suggesting both the presence of influential incumbents and room for differentiated entrants.
Strategic Positioning of Leading Companies
Astellas Pharma has built a recognized position in overactive bladder pharmacotherapy through its marketed product for this indication. Its strategic emphasis has centered on brand presence in a therapeutic category where tolerability and adherence strongly influence long-term performance. In parallel, Sumitomo Pharma has advanced a newer oral branded option that received FDA approval in 2024 and was subsequently approved for men with overactive bladder symptoms receiving pharmacologic therapy for benign prostatic hyperplasia. This expansion illustrates a targeted approach to patient segmentation and label broadening rather than reliance on category-wide volume alone.
On the device side, Medtronic continues to underpin a substantial share of sacral neuromodulation offerings with SNM systems used in overactive bladder and urge incontinence care. The company’s recent FDA approval of a minimally invasive tibial neuromodulation device for urge incontinence broadens its procedural toolkit and reflects a strategy of addressing multiple points in the treatment pathway. Neuspera Medical has pursued a more focused device strategy, earning PMA approval in 2025 for an integrated sacral neuromodulation system for urinary urge incontinence. By combining system components into a more unified architecture, the company is attempting to differentiate on procedural integration and usability. BlueWind Medical contributes another device angle through its implantable tibial neuromodulation system, while Axonics Modulation Technologies has been recognized for its SNM system for overactive bladder and urge incontinence.
Recent Developments and What They Signal
Recent events point to a market that is consolidating at the high end while still encouraging specialized innovation. The acquisition of Axonics by Boston Scientific integrates sacral neuromodulation technology into a broader interventional portfolio, reinforcing the strategic value of neuromodulation as a platform rather than a standalone niche. At the same time, fresh regulatory approvals for tibial and integrated sacral neuromodulation devices indicate continued openness to new procedural options, particularly where they reduce complexity or expand patient access. The FDA approval milestones for vibegron in a BPH-adjacent population and for newer device architectures also suggest that label expansion and indication targeting are becoming central levers for growth.
Worldwide Hyperhidrosis Treatment Market
Market Structure Evolution
Three structural trends are shaping the competitive field. First, portfolio breadth is increasingly important, as companies that can offer both drug and procedural pathways, or multiple procedural modalities, are better positioned to serve varied patient needs and capture referrals across care settings. Second, differentiation through usability, integration, and clinical workflow is gaining importance alongside pure clinical performance. Third, focused innovators can still create value by solving specific adoption barriers, even in a market where larger players hold significant share. The overall direction is not toward a single dominant model, but toward a layered landscape in which pharmacological and device-based options coexist and compete on patient fit, reimbursement durability, and ease of implementation.
Worldwide Bladder Pump Market
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define where value is created and where risk accumulates.
Trend 1: Broader Use of Minimally Invasive Neuromodulation
Minimally invasive tibial and integrated sacral neuromodulation approaches are expected to play a larger role in treatment pathways, especially for patients seeking drug-free alternatives or those with insufficient response to medication. The commercial opportunity lies in simplifying adoption, aligning procedural economics with site-of-care realities, and demonstrating durable patient outcomes that support both clinical and payer acceptance. The key uncertainty is whether reimbursement and workflow advantages will be sufficient to drive broad, sustained uptake beyond early-adopter centers.
Trend 2: More Flexible Treatment Sequencing and Shared Decision-Making
Guideline shifts away from rigid step therapy toward shared decision-making are likely to persist, increasing the importance of patient-specific matching and clinician education. This creates opportunities for products that can be positioned as appropriate early options in selected patients, as well as for services that help providers navigate choice across drug and device pathways. The risk is that broader choice may also intensify comparison across therapies, making real-world evidence, tolerability, and total cost of care more central to purchase decisions.
PW Consulting Health Care Research Center
Trend 3: Portfolio Consolidation Paired with Targeted Innovation
The market is likely to continue seeing consolidation among larger device and pharmaceutical players seeking to assemble integrated portfolios, while smaller innovators pursue narrowly defined clinical or procedural problems. For investors and strategic planners, the important signal is that value will not be distributed uniformly. Companies that can combine differentiated technology with market access readiness, training support, and reimbursement strategy are more likely to convert innovation into durable share. The counterrisk is that promising technology may underperform commercially if adoption barriers, coverage gaps, or site-of-care economics are not addressed early.
Actionable Recommendations for Decision-Makers
Different stakeholders face distinct strategic priorities in this environment, but all benefit from a clear-eyed view of where adoption is likely to expand and where friction remains.
For Manufacturers and Product Developers
- Build differentiation around workflow and patient experience, not just mechanism of action. In device markets, procedural simplicity, programming burden, and follow-up requirements can influence adoption as much as clinical performance. In pharmacotherapy, tolerability, adherence support, and targeted label strategies can help defend position in competitive categories.
- Align market access and reimbursement planning with site-of-care realities. Reimbursement changes in ambulatory settings and variability across coverage environments can determine whether a technology scales quickly or remains limited to select centers. Early attention to coding, coverage, and site-of-care economics is essential.
- Invest in real-world evidence and clinician education that supports shared decision-making. As guidelines and practice patterns move toward more flexible treatment selection, providers will look for practical guidance on matching therapies to patient profiles and on comparing downstream outcomes and total cost of care.
For Investors and Strategy Teams
- Evaluate platforms as well as point products. Neuromodulation and drug-based care are both evolving toward broader pathway positioning. Companies that can span multiple patient segments or multiple modalities may have more resilient growth prospects than those dependent on a single indication or single procedural niche.
- Track regulatory and reimbursement catalysts as leading indicators of adoption speed. Recent approvals and reimbursement adjustments for procedural therapies demonstrate how quickly site of care and coverage changes can alter commercial potential. Monitoring these shifts can improve timing for diligence and partnership decisions.
- Differentiate between clinical promise and commercial readiness. Innovative devices and new oral therapies may address genuine unmet needs, but their trajectory will depend on reimbursement durability, training requirements, physician comfort, and competitive response. Due diligence should weigh adoption friction as closely as technology differentiation.
For Procurement and Payer Decision-Makers
- Assess total cost of care across options rather than focusing on unit price alone. For procedural interventions, consider training, follow-up, and site-of-care implications. For drug therapies, consider adherence, tolerability, and downstream utilization. A narrower price view can obscure the economic differences that matter most over the course of treatment.
- Prepare for more flexible treatment pathways. As guidelines and clinical practice move toward shared decision-making, evaluation frameworks should account for multiple appropriate treatment routes and the conditions under which each is likely to perform best.
- Monitor the interaction between coverage policy and technology adoption. Reimbursement changes can affect where care is delivered and which technologies become practical for broader use. Ongoing visibility into coding and coverage developments can improve planning for both access and budget forecasting.
Final Perspective
The overactive bladder treatment market is expanding at a steady pace, but the more important story is how value is being redistributed across therapies, platforms, and care settings. Revenue growth through 2032 will be supported by demographic demand and continued innovation, yet the companies and investors that benefit most will be those who can navigate reimbursement complexity, align products with practical workflow needs, and support more flexible, patient-centered treatment selection. Market concentration suggests that scale and portfolio breadth matter, but recent device approvals and targeted label expansions show that differentiated offerings can still create meaningful commercial traction.
For decision-makers seeking to act with confidence, the next step is to translate these directional signals into detailed, segment-level planning. Comprehensive segmentation data, regional comparisons, treatment-pathway dynamics, and company-specific positioning can sharpen strategic choices and reveal where to commit resources, where to partner, and where to watch for disruption. In a market where regulatory, reimbursement, and clinical-practice shifts can alter adoption trajectories quickly, deeper intelligence is not just helpful; it is a practical requirement for disciplined strategy.
For detailed analysis of this topic, please visit the official page: Overactive Bladder Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com