

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Power Take Off Market: Why 4.8% CAGR and Machinery Demand Change Everything

Power Take Off Market: Strategic Trends and Commercial Opportunities Through 2032
The Power Take Off (PTO) market operates at the intersection of mechanical engineering, industrial mobility, and downstream application demand. Over the past five years, the sector has transitioned from steady incremental growth to a phase defined by product innovation, regulatory tightening, and regional demand realignment. Current market valuation sits at approximately 430 million USD, with historical performance reflecting a compound annual growth rate of 4.8 percent across the 2026 to 2032 forecast window. The trajectory suggests a market that is expanding in absolute terms while simultaneously undergoing structural refinement, as end users demand higher efficiency, safer operating conditions, and more integrated drivetrain solutions.
This evolution is not merely a function of rising unit volumes. It reflects a broader shift in how mobile and stationary equipment operators approach auxiliary power transmission. PTO systems are no longer treated as interchangeable mechanical add-ons; they are being designed to withstand higher torque loads, operate with reduced vibration, and integrate more cleanly with hydraulic and electrified auxiliary circuits. The market’s maturation is visible in the way manufacturers are balancing volume growth with margin protection, particularly as raw material volatility and international trade dynamics continue to reshape cost structures.
Side Shaft Market
Core Challenges and Inflection Point
Three structural challenges define the current operating environment for PTO manufacturers, distributors, and end users. Understanding these friction points is essential for assessing where near-term value will be created and where exposure should be managed.
First, the regulatory environment has tightened around safety and durability specifications. Updated international standards now mandate enhanced guarding, higher shaft durability thresholds, and more rigorous testing protocols for power transmission assemblies. These requirements are not optional compliance checkpoints; they influence product architecture, validation cycles, and time-to-market. Companies that can embed compliance into design rather than retrofit it gain a meaningful advantage in procurement approvals and customer trust, particularly in agricultural and construction sectors where safety culture is increasingly tied to equipment purchasing decisions.
Second, input cost volatility remains a persistent margin pressure. Steel price fluctuations and tariff movements have been shown to affect PTO shaft manufacturing margins by a measurable range, compressing profitability for producers with limited hedging flexibility or constrained supplier diversification. This is not a transient procurement issue; it is a structural cost dynamic that forces manufacturers to reconsider bill-of-material strategies, regional sourcing, and product standardization. In practical terms, firms that rely on highly customized shafts and components face greater exposure than those with modular architectures and broader supplier networks.
Third, the market is experiencing a functional divergence between traditional mechanical PTO demand and emerging auxiliary power needs. In several application areas, end users are re-evaluating whether mechanical PTO is the most efficient path for powering secondary systems. That reconsideration is creating a split environment: one segment continues to expand on the back of durable machinery and fleet replacement cycles, while another segment is being reshaped by electrification, hybrid auxiliary systems, and integrated power management architectures. The companies that treat this divergence as a strategic choice rather than a generic market trend will be better positioned to allocate R&D and commercial resources.
Key Demand Drivers Reshaping the Market
The PTO market’s growth is being driven by a combination of technology adoption, regulatory pressure, demand-side behavior, and supply chain economics. These drivers do not operate in isolation; they reinforce each other and create distinct competitive implications for manufacturers and buyers.
Technology Innovation and Product Architecture
Product innovation is increasingly centered on reliability, ease of integration, and reduced operational interruption. Hot shift PTO solutions, soft start technology, and improved wet kit configurations are examples of engineering responses to real-world operational pain points. In work truck and commercial vehicle applications, the ability to engage or disengage power transmission without stopping the vehicle, or to reduce shock loading during connection, translates directly into uptime improvements and lower wear on drivetrain components. Likewise, constant mesh designs and refined bolt configurations are being used to improve torque handling and service life in demanding environments.
Recent product activity reflects this direction. In early 2026, Eaton highlighted market-first hot shift PTO solutions, soft start technology, and upgraded wet kits for the work truck segment. Around the same period, Bezares introduced a new constant mesh Series 500 PTO to expand its power take-off range. These moves are not isolated product launches; they indicate a broader industry push toward systems that reduce operational friction, improve installation flexibility, and address the needs of OEMs and aftermarket buyers simultaneously. For commercial decision-makers, the practical implication is that PTO selection is becoming less about baseline mechanical compatibility and more about total operating efficiency, maintenance intervals, and integration with vehicle or machine architecture.
Policy, Standards, and Safety-Driven Demand
Regulatory and standards activity is acting as a demand catalyst in specific segments. Updated safety expectations and guarding requirements are encouraging replacement cycles and upgrades, especially where older equipment lacks modern protective mechanisms. At the same time, occupational safety initiatives have contributed to a measurable reduction in PTO-related injuries in agricultural settings through mandatory guards and automatic clutch mechanisms. This is significant because it reframes PTO procurement from a purely mechanical purchase into a risk-management decision.
For manufacturers, this environment rewards products that make compliance easier to implement and verify. For fleet operators and equipment owners, it raises the importance of purchasing systems that align with evolving site safety requirements without requiring extensive retrofitting. In both cases, the market is moving toward solutions that combine mechanical performance with verifiable safety outcomes, which strengthens the value proposition of integrated PTO and drivetrain packages.
Worldwide Hydrostatic Transmission Market
Demand-Side Behavior and Application Expansion
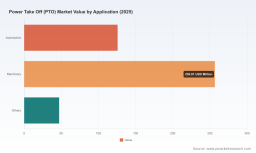
Demand is being shaped by a mix of replacement cycles, fleet modernization, and expanding use cases in off-highway and commercial vehicle environments. Machinery-driven applications remain a major demand center, reflecting the continued need for auxiliary power across construction, agriculture, and material handling equipment. At the same time, automotive-linked PTO demand continues to play a meaningful role, especially where commercial vehicles require integrated hydraulic and power transmission solutions for specialized operations.
What makes this demand environment strategically interesting is not just its size, but its sensitivity to operational economics. End users are increasingly evaluating PTO systems in the context of total cost of ownership, uptime, serviceability, and compatibility with broader vehicle or machine upgrades. That shift favors suppliers who can offer not only components, but also application-specific guidance, integration support, and after-sales service consistency. In practice, this means the commercial battleground is expanding from component performance alone to solution-level value.
Supply Chain and Cost Structure Dynamics
Supply chain conditions continue to influence both product design and pricing strategy. Material volatility and trade-related cost changes have made it more important for manufacturers to balance performance requirements with cost resilience. This has encouraged greater attention to component standardization, multi-source sourcing strategies, and design choices that reduce dependence on highly sensitive inputs. The strategic implication is straightforward: competitiveness is increasingly defined by the ability to maintain specification integrity while adapting to input cost shocks.
For buyers, this environment underscores the importance of long-term supplier relationships, clear specifications, and procurement plans that anticipate variability rather than react to it. For manufacturers, it rewards production strategies that combine engineering discipline with flexible sourcing and informed inventory planning. In a market where margins can be influenced by a notable percentage range due to material and tariff dynamics, cost structure management is not a back-office function; it is a competitive lever.
Competitive Landscape and Strategic Positioning
The PTO market features a mix of specialized manufacturers, broader motion-control companies, and large mobility technology providers. This mix creates a competitive environment where differentiation comes from application focus, product architecture, integration capability, and geographic reach. Rather than competing solely on price, leading players are building advantage through segment expertise, drivetrain integration, and the ability to meet increasingly demanding safety and performance expectations.
Differentiated Strategic Positions
Several company profiles illustrate how competitive advantage is being constructed in this market.
- Bezares has positioned itself as a global manufacturer spanning PTOs, hydraulic pumps, valves, tanks, and wet kits for trucks, industrial vehicles, and gearboxes. Its recent expansion into a constant mesh Series 500 PTO reflects a strategy centered on broadening the product range while maintaining a strong commercial vehicle and industrial vehicle footprint.
- Muncie Power Products focuses on power take-off units and parts alongside hydraulic components for work truck applications. Its strategic strength lies in serving a specialized commercial vehicle segment with a tightly aligned component and service ecosystem.
- Weasler Engineering targets high-performance drivelines and PTO systems for agricultural OEMs. This positioning emphasizes application-specific engineering and durability in demanding field environments.
- Walterscheid GmbH provides PTO driveshafts and drivetrain systems for agricultural, construction, and off-highway applications. Its relevance in off-highway segments gives it exposure to sectors where uptime, torque handling, and harsh-environment reliability are central purchase criteria.
- Eaton Corporation approaches the market from an intelligent power management perspective, offering mobile power solutions that include hot shift PTOs, wet kits, and drivetrain technologies. Its strategy is oriented toward integrated power management rather than isolated mechanical components.
- HYVA operates as a leading provider of hydraulic tipping systems, valves, pumps, and PTO solutions for commercial vehicles. Its positioning links PTO capability with broader hydraulic system functionality, which is valuable where tipping, lifting, and auxiliary operations are closely connected.
- Parker Hannifin Corporation brings a broad motion and control technology base, including hydraulic valves, pumps, and PTO components. Its scale and cross-product integration create advantages in projects that require coordinated hydraulic and power transmission solutions.
- ZF Friedrichshafen AG supplies advanced mobility products, including electrified PTO systems for commercial vehicles. Its presence signals the growing importance of electrification and next-generation drivetrain architectures in the PTO value chain.
- Interpump Group operates as a world leader in hydraulics and power transmission, including a division associated with Muncie Power Products for PTO and hydraulic components. Its structure illustrates how portfolio breadth and divisional specialization can coexist within a larger hydraulics and power transmission ecosystem.
Taken together, these players reveal a landscape where specialization and integration both matter. Some competitors win by deeply serving a specific application segment; others win by offering broader motion-control and power-management portfolios that reduce integration complexity for OEMs and end users. The strategic lesson is that the market does not reward a single winning formula. It rewards alignment between product architecture, application expertise, and the ability to respond to safety and performance expectations.
Market Structure and Evolution
Market concentration remains moderately consolidated, with the top three players accounting for roughly half of market revenue and the top five capturing a slightly larger share. This level of concentration suggests that scale, distribution reach, and portfolio breadth provide meaningful advantages, but it also leaves room for specialized leaders to compete effectively in focused segments. The market is not so concentrated that new ideas or application-specific innovations cannot gain traction, yet it is structured enough that broader portfolios and established supplier relationships influence procurement decisions.
The likely evolution over the next several years is not a simple shakeout. It is more plausibly a combination of selective consolidation in segments where integration and scale matter most, alongside continued differentiation in niches where application engineering, durability, and safety compliance create defensible positions. New entrants and adjacent players may find opportunity not by competing broadly, but by targeting specific drivetrain needs, regional demand pockets, or specialized electrified and hybrid auxiliary power applications.
Forward-Looking Trends and Commercial Implications
Looking toward the 2026 to 2032 horizon, the PTO market is likely to be shaped by three interconnected trends. Each has direct implications for product strategy, commercial planning, and risk management.
1. Integration will increasingly define value. PTO systems are moving from standalone mechanical components toward integrated power transmission and auxiliary systems. Hot shift capability, soft start behavior, wet kit improvements, and electrified PTO concepts all point in the same direction: end users want systems that reduce interruption, improve control, and fit cleanly into broader vehicle or machine architectures. Commercially, this means winning solutions will be those that combine component reliability with integration ease, application guidance, and service continuity. Manufacturers that can offer a coherent package rather than a discrete part will have stronger positioning in both OEM and aftermarket channels.
2. Compliance and safety will become purchase criteria, not side considerations. Updated guarding and durability expectations, together with the demonstrated impact of safety mechanisms on reducing injuries in agricultural environments, are making safety a more visible part of procurement reasoning. This trend supports demand for upgraded systems and creates a differentiation path for products that make compliance straightforward. For buyers, the opportunity lies in selecting PTO solutions that lower operational risk while maintaining performance. For suppliers, the opportunity lies in designing for verifiable safety outcomes and communicating them clearly.
3. Cost resilience and sourcing strategy will separate durable competitors from vulnerable ones. Material price volatility and trade-related cost shifts are likely to remain part of the operating environment. Companies that can manage input exposure through standardization, diversified sourcing, and disciplined product architecture will protect margins more effectively than those dependent on narrow supply chains or highly customized parts. This trend favors organizations that treat cost structure as a strategic variable and build flexibility into both design and procurement. It also means buyers should evaluate suppliers not only on specification and price, but also on supply continuity and ability to navigate cost shocks without compromising delivery quality.
Associated Risks and Uncertainties
These trends come with meaningful uncertainties. Electrification and hybrid auxiliary architectures could redistribute demand away from traditional mechanical PTO in certain segments, creating both opportunity and displacement risk depending on how quickly end users adopt new power layouts. Regulatory expectations may continue to tighten, increasing validation effort and affecting time-to-market for new designs. Input cost volatility could persist or intensify, especially if trade policy and material markets remain unstable. Finally, regional demand patterns may shift as fleet modernization, infrastructure investment, and off-highway activity evolve at different speeds across geographies. Companies that monitor these signals continuously will be better able to adjust product plans, procurement strategies, and commercial messaging before changes become disruptive.
PW Consulting
Strategic Actions for Decision-Makers
The PTO market’s next phase will reward participants who combine engineering discipline with commercial agility. The following actions are most relevant depending on role and exposure.
For Manufacturers and Product Leaders
- Prioritize integration-ready architectures that support hot shift operation, reduced shock loading, and cleaner fitment with hydraulic and drivetrain systems.
- Embed safety and durability requirements into design cycles rather than treating them as late-stage compliance tasks, reducing rework and accelerating customer acceptance.
- Strengthen sourcing flexibility and component standardization to protect margins against material and tariff volatility without sacrificing specification integrity.
For Investors and Strategic Planners
- Focus on companies with clear application specialization, integration capability, and evidence of cost-resilient manufacturing strategies, since these attributes are likely to matter more as the market matures.
- Watch for shifts in electrified and hybrid auxiliary power adoption, as these changes can alter demand patterns for traditional PTO systems and create new plays in integrated power management.
- Monitor M&A and portfolio realignment activity, particularly where broader motion-control or hydraulics players seek to strengthen PTO-related capabilities or application coverage.
For Procurement and Fleet Operators
- Evaluate PTO solutions on total operating impact, including uptime, serviceability, safety compliance, and compatibility with existing or planned vehicle and machine architectures.
- Build supplier relationships that emphasize specification clarity, delivery continuity, and support for replacement and upgrade cycles, especially where older equipment needs modernization.
- Plan procurement with cost variability in mind, using longer-term agreements, clear technical specifications, and diversified sourcing where feasible to reduce exposure to input shocks.
The strategic value of the PTO market lies not only in its growth trajectory, but in the way it is being reshaped by product innovation, safety expectations, and cost dynamics. Participants that treat these forces as interconnected will be better equipped to allocate resources, choose partners, and position for the 2026 to 2032 period with greater confidence. For decision-makers seeking deeper segmentation detail, regional demand patterns, and customized strategic recommendations, PW Consulting’s full research report provides a more granular view of the market and its commercial implications.
For detailed analysis of this topic, please visit the official page: Power Take Off (PTO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com