

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Peptide Synthesis Market 2026: How 7.85% CAGR and Therapeutics Dominance Reshape Growth Strategy

Strategic Trends and Commercial Opportunities in the Global Peptide Synthesis Market
Beyond the 7.85% CAGR: Navigating a Maturing and Consolidating Peptide Synthesis Ecosystem
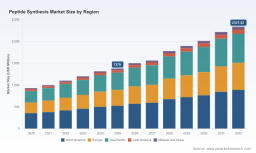
The global peptide synthesis market has transitioned from a niche supporting segment into a central pillar of modern biopharmaceutical manufacturing. From 2020 through 2025, the market expanded from approximately USD 930 million to USD 1.38 billion, reflecting steady compound annual growth that is expected to accelerate into the 2032 forecast horizon, reaching an estimated USD 2.34 billion. This trajectory is underpinned by a projected CAGR of 7.85% across the 2026 to 2032 period, signaling that demand drivers are not cyclical but structural. The expansion is not merely a function of incremental volume growth; it reflects a fundamental shift in how peptides are designed, manufactured, and positioned across therapeutic, diagnostic, and research applications. For executives and investors, the market is no longer defined by isolated laboratory workflows but by integrated, scale-ready supply chains that must balance regulatory rigor, cost efficiency, and technological divergence.
At a high level, the market is characterized by moderate concentration, with the top three firms accounting for roughly 39.5% of revenue and the top five capturing approximately 48.2%. This structure suggests that while scale players dominate commercial endpoints, meaningful differentiation persists through specialized capabilities, regional footprints, and technology choices. The revenue composition shows that reagents and consumables continue to represent the largest share within the product segment, equipment contributes a substantial but secondary portion, and services form a meaningful third pillar that increasingly blurs the line between pure supplier and integrated partner. Technologically, solid-phase peptide synthesis remains the dominant approach, though solution-phase and hybrid or recombinant methods occupy distinct niches that are expanding as manufacturers confront scale and purity requirements. By application, therapeutics command the largest share, followed by diagnosis and research and development, reflecting the pipeline’s growing reliance on peptide-based modalities for targeted interventions and precision diagnostics.
The Structural Inflection: Where the Market Stands Today
The current market environment is shaped by a convergence of scaling capacity, regulatory formalization, and technology adoption that is reshaping competitive dynamics. The most immediate reality is that demand growth is pressuring legacy manufacturing models. Traditional batch-oriented solid-phase workflows, while mature and broadly deployed, face limits when applied to multi-kilogram and commercial-scale production without substantial re-engineering of solvent handling, purification, and waste management. This has forced both incumbents and new entrants to evaluate process intensification, automation, and liquid-phase alternatives as practical necessities rather than optional upgrades. The result is a market in which operational capability has become as strategic as scientific know-how.
A second inflection lies in the regulatory environment. Over the past year, regulatory bodies have moved from general expectations to more explicit, peptide-specific guidance. The adoption of dedicated manufacturing and development guidelines has raised the bar for process documentation, impurity control, and consistency across batches. This formalization has two implications: it creates a higher barrier to entry for manufacturers that lack quality systems and data integrity infrastructure, and it strengthens the positioning of established players who can demonstrate traceability, validation, and regulatory readiness across clinical and commercial stages. For the market as a whole, the shift reduces ambiguity but also compresses timelines for those still building compliance maturity.
The third challenge is commercial scale and cost structure. Peptides remain cost-sensitive relative to small molecules and antibodies, particularly when complex sequences, challenging purifications, or stringent impurity thresholds are involved. As therapeutic programs advance toward commercialization, the economics of goods sold become a decisive factor, especially for chronic indications or large patient populations. This pressure has intensified interest in yield optimization, solvent recovery, convergent synthesis routes, and contract development and manufacturing partnerships that can de-risk scale-up. The market is therefore entering a phase where technical feasibility and commercial viability must be designed in tandem from early development rather than resolved retrospectively at the manufacturing stage.
Core Drivers Shaping the Peptide Synthesis Landscape
Technology Innovation and Process Intensification
The dominant force in the market remains the continued refinement of synthesis technology, especially within solid-phase workflows, but with growing attention to complementary methods. Microwave-assisted synthesis has expanded the practical toolkit for accelerating coupling steps and improving reproducibility for difficult sequences. More importantly, automation is moving from laboratory convenience to industrial necessity, with instrument platforms and integrated process controls becoming central to ensuring lot-to-lot consistency. As programs move from discovery to late-stage development, the ability to standardize cycle times, reduce manual variability, and monitor reaction progress in-line is increasingly tied to readiness for regulated manufacturing.
Parallel to automation, liquid-phase peptide synthesis and hybrid approaches are gaining traction where scale and cost matter most. These methods are not replacing solid-phase synthesis but are being positioned as alternatives for specific use cases, particularly when longer sequences, large-scale production, or cost-efficient impurity management are priorities. The market is witnessing a pragmatic bifurcation: solid-phase synthesis continues to anchor clinical and commercial supply for many programs, while solution-phase and hybrid pathways carve out opportunities where throughput and economics are decisive. This divergence creates an environment in which technology selection is increasingly application-driven, with manufacturers expected to justify their choice based on sequence complexity, target scale, and purity requirements.
A notable real-world indicator of this technological push is the recent expansion of synthesis capacity across multiple manufacturing sites. Facilities have been adding pre-built module installations, commissioning new large-scale solid-phase lines, and integrating upstream and downstream capabilities in a single site. These moves are not simply about adding square footage; they are designed to increase throughput while maintaining process control, and in several cases to enable faster tech transfer between regions. For decision-makers, this signals that capacity is becoming more modular and more regionally distributed, which affects lead times, supply resilience, and the speed at which clinical programs can progress to commercial supply.
Policy and Regulatory Environment as a Competitive Filter
Regulatory evolution is now a meaningful driver of market structure. The introduction of peptide-specific manufacturing guidance, combined with heightened expectations around documentation and quality data integrity, has effectively acted as a competitive filter. Companies with mature GMP systems, robust analytical capabilities, and established drug master file infrastructure are better positioned to support advanced development and commercialization. Recent regulatory milestones, such as filings and acknowledgments tied to major peptide active pharmaceutical ingredients, illustrate how regulatory readiness is becoming a prerequisite rather than an afterthought. These events have also drawn attention to the importance of characterization, stability data, and clear demonstration of process control, especially for complex sequences.
The regulatory momentum has also elevated the strategic value of analytical support. Full-service characterization and synthesis support that align with IND/NDA expectations are increasingly viewed as essential components of a development plan. This is not simply about generating data; it is about designing a regulatory narrative that connects synthesis strategy, impurity profiles, and process consistency to clinical and safety outcomes. In practice, this means that manufacturers and service providers that can integrate synthesis, analytics, and documentation into a coherent package gain a measurable advantage in both speed and credibility.
For the market broadly, regulatory clarity reduces uncertainty but increases the premium on compliance maturity. Organizations that treat regulatory alignment as an ongoing capability rather than a one-time milestone are better positioned to manage the transition from early development to commercial launch, especially as guidance continues to mature across regions.
Demand-Side Shifts and Therapeutic Momentum
Demand is being reshaped by the expanding therapeutic footprint of peptides. The approval landscape for peptide-based interventions has widened, with notable regulatory actions that extend indications and reinforce long-term usage patterns. These developments have reinforced peptide therapeutics as a meaningful category, particularly where receptor targeting, metabolic pathways, or disease-specific pathways can be addressed with high selectivity. As a result, the demand base is no longer confined to early-stage research; it increasingly includes clinical supply and commercial manufacturing that must meet larger volumes, tighter schedules, and more demanding quality thresholds.
Beyond treatments, diagnostic applications continue to contribute to demand, especially where peptide ligands, biomarkers, and targeted detection tools are deployed. Research and development demand remains active as well, though its growth is increasingly tied to translational programs rather than exploratory academic work. The broader implication is that the demand profile is maturing into multiple layers: exploratory research, proof-of-concept clinical work, late-stage development, and commercial supply. Each layer carries different requirements, and the ability to serve across these layers without compromising quality or turnaround has become a defining strength for leading providers.
This multi-layer demand is also changing procurement behavior. Developers are looking for partners that can provide flexible scale, clear technical communication, and predictable quality systems, especially when programs move quickly toward pivotal studies or commercialization. The desire for reduced handoffs and clearer accountability is driving interest in integrated service models, where synthesis, purification, analytics, and regulatory support are coordinated within a single framework.
Gene Synthesis Market
Supply Chain Realignment and Cost Structure Pressures
Cost and supply chain dynamics are reshaping where and how peptides are produced. Reagent and consumable costs, solvent handling, purification efficiency, and yield losses all contribute to the economics of peptide manufacturing, and these factors become more pronounced as programs scale. In response, manufacturers are reassessing process design with a focus on resource efficiency and waste reduction. Where feasible, this has led to investments in closed-system workflows, improved recovery strategies, and more disciplined material usage, all of which contribute to cost control without sacrificing quality.
Regional supply considerations are also gaining importance. Organizations are weighing the benefits of regionalized manufacturing against the traditional model of concentrated production. Recent site expansions and commissioning in multiple geographies reflect a desire to build redundancy, reduce logistics complexity, and support closer interactions with development teams and regulatory authorities. At the same time, consolidation activity has begun to reshape the supply base, with larger players acquiring additional manufacturing capabilities to broaden geographic reach and strengthen capacity across regions. These moves suggest a market that is moving toward integrated networks rather than fragmented point solutions.
For commercial strategy, the supply chain shift has direct consequences. Manufacturers that can demonstrate reliable supply, transparent cost drivers, and scalable processes will have stronger negotiating positions as demand increases. Conversely, providers that cannot manage cost escalation or maintain consistency at scale risk losing share to more capable competitors or to alternative synthesis routes better suited to the program’s economics.
Competitive Landscape and Leading Strategies
Established Strengths and Differentiation Paths
The competitive field includes a mix of instrument and reagent specialists, custom synthesis providers, and large-scale peptide API manufacturers and CDMOs. These players are not competing on a single axis; rather, each is building differentiation around a distinct value proposition. One group centers on automation, instrument platforms, and enabling technologies that support reproducible synthesis workflows, particularly for research and development and early clinical work. Another group focuses on custom synthesis, GMP manufacturing, and commercial-scale peptide API production using established solid-phase and liquid-phase methods, often supporting programs from gram-scale to multi-ton operations. A third group emphasizes fully integrated services, including characterization, regulatory documentation, and compliance support aligned with development filings and commercial requirements.
What distinguishes the more successful players is the ability to connect scientific capability with operational scale and regulatory readiness. Firms that have built strong reputations typically do so by combining domain expertise with disciplined process control, transparent quality systems, and a willingness to invest in the infrastructure needed to support later-stage programs. In several cases, differentiation is also geographic, with multiple sites enabling regional support, faster transfer, and supply flexibility. This multi-site approach is increasingly relevant as programs seek resilience and faster response times without sacrificing compliance standards.
The competitive positioning of leading organizations reflects a broader market truth: in peptide synthesis, credibility is built on both technical performance and operational execution. A strong method or instrument alone is insufficient if it cannot be translated into consistent, documented, and scalable production. Likewise, manufacturing capacity is most valuable when paired with analytical depth and regulatory expertise. As a result, the most resilient companies are those that treat synthesis, analytics, and compliance as interdependent capabilities rather than separate functions.
Consolidation, Integration, and New Entrant Dynamics
The market is showing signs of consolidation through both facility investment and corporate action. Large expansions across multiple manufacturing sites have increased the available capacity for solid-phase synthesis and related services, while targeted acquisitions have extended geographic reach and manufacturing breadth. These developments point toward a landscape in which scale and geographic coverage are becoming more important, particularly for companies that want to support clients across regions and across the development continuum. At the same time, consolidation does not imply homogeneity. Differentiated capabilities remain critical because programs vary widely in sequence complexity, scale requirements, and regulatory pathways.
New entrants and specialized players continue to find space by targeting underserved needs. Some focus on niche synthesis technologies, others on analytical services, and others on regional service models that offer close collaboration and responsiveness. Their presence has the effect of raising the bar on service quality and encouraging more established players to improve flexibility and technical communication. For the market overall, this creates a dynamic environment in which incumbents must continually invest to maintain advantage, while newer players must demonstrate clear differentiation to secure sustained demand.
Strategic positioning is therefore increasingly about integration and optionality. Leading firms are building platforms that can accommodate different synthesis strategies, support multiple geographies, and provide analytical and regulatory support as part of a broader development partnership. This integrated posture is not only a growth strategy; it is a risk-management strategy, enabling providers to adapt as programs move from research to clinical to commercial stages without forcing the client to re-qualify multiple partners at each transition.
Looking Ahead: Three Strategic Trends for 2026 to 2032
Trend One: Process Scale and Modular Capacity as Standard Expectations
Over the next several years, scale-ready manufacturing and modular capacity will move from differentiators to baseline expectations. As more peptide programs advance toward commercialization, the demand for reliable multi-kilogram and commercial-scale supply will increase, and manufacturers will need to demonstrate that they can manage throughput, purification, and solvent management in a controlled and repeatable manner. The trend will favor organizations that can combine automation, process control, and capacity flexibility with strong quality systems. For buyers, this means that selection criteria will increasingly emphasize operational resilience and proven scale-up capability alongside scientific expertise.
The commercial opportunity here lies in service models that reduce friction across the development-to-commercial transition. Providers that can offer predictable timelines, clear scale-up pathways, and integrated analytics will be well positioned to capture demand from programs that want to avoid late-stage surprises. The risk, however, is that over-investment in capacity without corresponding demand realization could pressure utilization rates, especially if therapeutic programs face clinical setbacks or regulatory delays. Balancing capacity growth with disciplined demand forecasting will be essential.
Worldwide Customized Peptide Synthesis Market
Trend Two: Regulatory Maturity Becoming a Market Gatekeeper
Regulatory readiness will continue to act as a structural filter. As peptide-specific guidance matures and enforcement expectations become more consistent, the market will likely see a widening gap between organizations that treat compliance as a core capability and those that treat it as an administrative burden. The strategic implication is that regulatory alignment will increasingly influence partnership decisions, vendor selection, and long-term supply arrangements. Companies able to demonstrate robust documentation, characterization, and process control will have an advantage in supporting advanced development and commercial supply.
This trend creates opportunities for organizations that embed regulatory thinking early in the synthesis strategy, rather than layering it on later. Early alignment can reduce rework, accelerate transitions between development stages, and strengthen confidence for internal and external stakeholders. The uncertainty is that regulatory expectations may continue to evolve, which could require ongoing adjustment in analytical methods, documentation, and process controls. Market participants should therefore treat regulatory strategy as iterative, not static.
Trend Three: Technology Diversification and Sequence-Specific Sourcing
The next phase of market growth will likely be characterized by more deliberate technology selection rather than uniform reliance on a single synthesis method. As programs become more diverse in sequence length, complexity, and production requirements, the market will increasingly reward providers that can match the synthesis approach to the specific demands of the molecule. This includes the practical use of solid-phase synthesis for many applications, the selective use of solution-phase or hybrid methods where scale and economics justify them, and the use of automation or microwave-enabled workflows where speed and reproducibility are priorities.
PW Consulting Health Care Research Center
The commercial opportunity is in creating decision frameworks that help clients choose the right route earlier, reducing wasted effort and improving time to material. Providers that can articulate when and why a particular technology is appropriate, backed by demonstrated performance, will differentiate themselves in a crowded field. The risk is that technology claims outpace operational reality; credible differentiation will require consistent execution, not just capability descriptions. In practice, the winners will be those who can combine technical flexibility with disciplined delivery and transparent communication.
Strategic Actions for Decision-Makers
For Manufacturers and Service Providers
Focus on building integrated capability across synthesis, analytics, and regulatory readiness, rather than competing solely on price or instrument features. The market increasingly rewards providers that can guide programs through technical transitions with minimal handoffs and clear accountability. Invest in process control, solvent handling efficiency, and quality systems that can support both clinical and commercial requirements. At the same time, maintain technology optionality so that the most appropriate synthesis route can be selected for each program, rather than standardizing prematurely on one method. Regional presence and capacity modularity should also be treated as strategic assets, especially if they shorten timelines, improve resilience, and support faster responses to client needs.
For Investors
Evaluate exposure not only to current revenue but to the market’s structural drivers: capacity expansion aligned with realistic demand, regulatory maturity, and technology flexibility. The most durable investment cases will likely belong to organizations that can demonstrate the ability to serve multiple stages of development and to scale without compromising quality. Watch for consolidation activity that improves geographic reach or technical breadth, but scrutinize whether acquisitions are integrated in a way that strengthens execution rather than simply adding facilities. Be mindful of the risk that capacity built ahead of demand realization may create short-term pressure, particularly if clinical or regulatory timelines shift.
For Procurement and Development Teams
Prioritize partners that can show consistent performance across the stages your programs are likely to encounter. Evaluate providers based on their ability to manage scale-up, maintain quality documentation, and provide analytical support that aligns with development and regulatory needs. Ask explicitly about process control, turnaround predictability, and the degree to which synthesis and analytics are coordinated. Where possible, favor partnerships that reduce fragmentation and create clearer accountability across synthesis, purification, and characterization. Given the cost sensitivity of peptide manufacturing, also assess the economic logic of the chosen synthesis route and whether the provider’s approach is sustainable at the volumes and quality levels you expect to require.
Closing Perspective
The peptide synthesis market is entering a phase where growth is no longer driven by novelty alone but by the ability to deliver complex molecules with reliability, compliance, and commercial discipline. The data trajectory points to sustained expansion, but the real strategic story lies in how the market is reorganizing around scale, regulation, technology choice, and integrated service models. For executives, investors, and procurement leaders, the most valuable questions are shifting from whether peptides will matter to how to source, build, and partner in a way that matches the specific demands of each program. Detailed segmentation data, regional nuance, and company-level capability mapping can sharpen those decisions significantly, and a comprehensive market intelligence perspective can help translate broad trends into specific sourcing, investment, and development strategies.
For detailed analysis of this topic, please visit the official page: Peptide Synthesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com