

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
RF Switches Market 2026: Beyond the 5.6% CAGR Story – PIN, GaAs, and MEMS Drivers

Navigating the RF Switches Market: Strategic Trends and Commercial Opportunities Through 2032
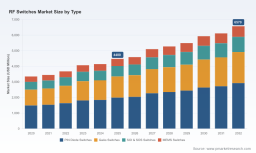
The RF switches market has entered a phase of methodical expansion, underpinned by steady revenue growth from 2020 through 2025 and a projected compound annual growth rate of 5.6 percent across the 2026–2032 forecast period. By 2025, total market revenue reached approximately 4.48 billion USD, with a clear trajectory toward 6.57 billion USD by 2032. This growth is not merely a reflection of incremental demand; it signals a structural shift in how radio frequency signal routing is designed, manufactured, and integrated across connected systems. The market’s expansion is broad-based, spanning mature telecommunications infrastructure, defense and aerospace platforms, industrial automation, and emerging satellite-linked communication networks. Yet beneath the headline numbers lies a more nuanced reality: technology transitions, regulatory pressures, and supply chain recalibration are simultaneously reshaping competitive positioning and creating asymmetric opportunities for firms that can anticipate rather than react to market shifts.
Pinpointing the Core Challenges and Market Inflection Points
Despite the favorable growth outlook, the industry is navigating several critical inflection points that will determine which players capture disproportionate value over the next five years. First, the coexistence of competing RF switch technologies is forcing design teams and procurement leaders to make increasingly complex trade-offs. PIN diode switches remain widely deployed for cost-sensitive and high-power applications, while GaAs and SOI/SOS platforms continue to dominate where isolation, linearity, and insertion loss are paramount. MEMS switches and emerging silicon-based alternatives are gradually gaining traction in scenarios where power consumption, footprint, and reliability must be optimized simultaneously. The absence of a single dominant architecture means that technology selection is becoming increasingly application-specific, raising integration complexity and lengthening qualification cycles for OEMs.
Second, the rapid expansion of low Earth orbit satellite constellations is introducing both demand tailwinds and spectrum management friction. Regulatory filings and policy analyses indicate that satellite production growth is outpacing existing coordination frameworks, creating heightened concerns over radio interference and orbital slot allocation. As operators scale constellations from thousands to tens of thousands of satellites, the RF front-end ecosystem—including switching, filtering, and amplification subsystems—must accommodate higher throughput, broader frequency coverage, and tighter thermal and reliability constraints. This dynamic is simultaneously opening new procurement pipelines for aerospace and defense suppliers while forcing terrestrial and wireless communication vendors to navigate increasingly crowded spectral environments.
Third, infrastructure deployment strategies are evolving in ways that reshape regional demand patterns. Broadband expansion initiatives are increasingly emphasizing microtrenching, surface-level deployments, and hybrid fiber-wireless architectures, which influence the mix of RF components required for last-mile and mid-mile connectivity. At the same time, sovereign spectrum rights and orbit governance frameworks are reinforcing the strategic importance of localized component sourcing, testing, and compliance. Together, these forces are pushing the market away from commoditized volume plays and toward differentiated, application-engineered solutions where switching performance, environmental ruggedness, and lifecycle support carry greater commercial weight.
Decoding the Key Demand Drivers Reshaping Revenue Trajectories
The market’s growth is being propelled by a convergence of technological, regulatory, and demand-side forces that reinforce one another rather than operate in isolation. Technological innovation remains the most direct catalyst. Recent product introductions from established manufacturers illustrate how switch architectures are being refined to meet the stringent requirements of radar, electronic warfare, broadband infrastructure, and high-reliability communications. Advancements in SOI-based SPDT platforms, high-isolation SPST/SPDT series, reflective antenna tuning switches, flip-chip architectures, and GaN-enabled high-power switching solutions demonstrate a clear industry emphasis on improving isolation, reducing loss, and expanding frequency ranges. These improvements are not incremental refinements; they enable system designers to consolidate RF paths, reduce module count, and improve overall signal integrity in increasingly dense electromagnetic environments.
Policy and regulatory developments are simultaneously acting as both an enabler and a constraint. The broadening of LEO satellite constellations has triggered heightened scrutiny around spectrum allocation, interference mitigation, and orbital coordination. Regulatory bodies and government analyses are increasingly emphasizing careful spectrum management and sovereign rights over orbital and frequency resources. For RF switch suppliers, this translates into a dual dynamic: expanded opportunities in satellite-linked communication ecosystems and test-and-measurement infrastructure, alongside stricter qualification requirements and a growing premium on components that can operate reliably under congested spectral conditions. The regulatory environment is effectively raising the barrier to entry for generic switching solutions while rewarding vendors with documented compliance, robust testing protocols, and application-specific design support.
Demand-side behavior is shifting as well. Cellular and wireless communication networks continue to anchor a substantial share of RF switch consumption, but the nature of that demand is changing. Base station architectures, antenna tuning systems, and broadband access equipment are becoming more modular and software-defined, requiring switching components that can adapt to dynamic reconfiguration without sacrificing performance. At the same time, industrial and automotive applications are gaining prominence as connectivity expands beyond traditional telecom into factory automation, vehicle-to-infrastructure communication, and sensor-heavy environments. These sectors demand switches that can tolerate harsher operating conditions, sustain long service intervals, and integrate cleanly into mixed-signal architectures. The result is a broadening of the demand base that reduces reliance on any single vertical while increasing the need for segmented product strategies.
PW Consulting Information & Electronics Research Center
Supply chain and cost structure dynamics round out the driver set. The concentration of revenue among a relatively small group of leading suppliers indicates that scale, technology maturity, and strategic customer relationships continue to confer meaningful advantages. At the same time, the market’s evolution toward specialized high-reliability and high-isolation solutions is elevating the importance of production consistency, material sourcing, and qualification documentation. Cost pressures persist, particularly in consumer-facing and mass-market wireless applications, but they are increasingly offset by value migration toward performance-critical segments where switching reliability, thermal handling, and integration flexibility directly influence system economics. The net effect is a market where cost leadership alone is no longer sufficient; competitive advantage is being redefined around design enablement, lifecycle support, and application-specific performance guarantees.
Competitive Landscape and the Strategies Defining Market Leadership
The competitive environment reflects a market that is neither fully consolidated nor fragmented beyond coherence. A concentrated core of established manufacturers anchors supply in defense, aerospace, telecommunications, and test-and-measurement applications, each pursuing distinct yet overlapping strategic positions. Leading players are differentiating not simply through product breadth, but through architecture specialization, application-specific tuning, and long-term ecosystem relationships that extend beyond component sales.
Network Switches Market
Companies focused on high-performance semiconductor-based switching are emphasizing platform continuity and portfolio expansion. Recent announcements in the first half of 2026 illustrate this pattern clearly. Qorvo introduced new X-Band amplifiers, GaN transistors, and SOI SPDT RF switches targeting defense, aerospace, radar, electronic warfare, communications, and DOCSIS 4.0 broadband applications, signaling a deliberate push to align switching solutions with high-growth, high-reliability segments. pSemi expanded its UltraCMOS+ portfolio with new high-isolation RF switches, reinforcing a strategy centered on isolation performance and integration simplicity for demanding RF front-end designs. Skyworks Solutions has continued to emphasize reflective antenna tuning switch architectures that support beamforming, coverage optimization, and adaptive impedance matching in advanced wireless systems. Analog Devices maintains a strong position in flip-chip SP4T switching for test and measurement and cellular applications, where repeatability, calibration stability, and signal path integrity are critical. MACOM’s reflective SPDT switches remain relevant across WiFi, Bluetooth, and base station ecosystems, particularly where rapid reconfiguration and compact integration are valued.
Parallel to these semiconductor-centric strategies, a cohort of suppliers is strengthening their position in electromechanical, coaxial, waveguide, and high-reliability switching for environments where solid-state alternatives face thermal, power-handling, or failure-mode constraints. Teledyne Microwave Solutions and Teledyne Relays & Coax Switches provide surface-mount and latching multi-throw coaxial switching that support communications systems and aerospace and defense deployments requiring extended lifecycle durability and deterministic switching behavior. JFW Industries’ absorptive failsafe switches and Dow-Key Microwave’s custom coaxial, waveguide, and space-grade switches highlight a persistent premium on tailored solutions for high-power and mission-critical scenarios. Narda-MITEQ and Pasternack Enterprises continue to serve wireless communication and test-and-measurement markets with reflective and electromechanical transfer switches that prioritize repeatability, isolation, and serviceability. Planar Monolithics Industries and Radiall reinforce the broader ecosystem with solid-state and microwave-component switching options that address military, industrial, and component-integration requirements.
The strategic lesson from this landscape is that leadership is increasingly defined by the ability to match switching technology to the failure modes, environmental constraints, and reconfiguration requirements of the end application. Firms that treat RF switches as interchangeable commodities risk margin erosion and displacement by suppliers offering integrated design support, application-specific qualification packages, and lifecycle reliability documentation. Conversely, suppliers that align product roadmaps with defense/aerospace ruggedness, broadband infrastructure scalability, satellite communication frequency expansion, and test infrastructure repeatability are positioning themselves to capture more resilient demand streams. The market is also showing signs of gradual consolidation pressure, as acquisition interest in specialized high-reliability portfolios and niche antenna-tuning platforms intensifies. At the same time, new entrants and smaller specialist firms can still find room in custom configurations, ultra-high isolation niches, and application-tailored electromechanical solutions where incumbents face limits in standard product coverage.
Forecasting the Next Phase: Three Trends to Watch Through 2032
The next three to five years will likely be shaped by a blend of technology migration, demand diversification, and ecosystem coordination challenges. The first trend is the continued broadening of application-specific switch architectures. As systems grow more software-defined and frequency-agile, RF switches will need to support dynamic reconfiguration, lower loss across wider bands, and improved robustness against interference. The commercial opportunity lies in developing modular switching families that can be rapidly adapted across cellular, broadband, satellite-linked, and industrial use cases without requiring full redesign cycles. Suppliers that can offer configurable isolation levels, compact integration footprints, and predictable thermal behavior will be better positioned to win in environments where system architects must balance performance, cost, and deployment speed.
Worldwide High Isolation RF Switches Market
The second trend is the deepening integration of RF switching into high-reliability and satellite-adjacent ecosystems. The scaling of LEO constellations and the growing emphasis on spectrum discipline are expanding the need for components that can operate across extended frequency ranges, withstand harsh environmental conditions, and satisfy rigorous qualification standards. This trend favors suppliers with documented aerospace and defense heritage, robust testing capabilities, and the ability to support long-lifecycle deployment models. Commercial upside will accrue to firms that can bridge the gap between terrestrial wireless demand and space-linked communication requirements, particularly where switching reliability directly affects link stability, interference resilience, and maintenance intervals.
The third trend is the gradual rebalancing of supply chain risk and regional procurement preferences. As regulatory frameworks reinforce sovereign rights over spectrum and orbital resources, and as infrastructure plans increasingly emphasize localized broadband expansion, procurement teams are placing greater weight on supply continuity, traceability, and compliance documentation. The commercial implication is a market where regional service capability, testing support, and component qualification transparency increasingly influence purchasing decisions alongside unit economics. Firms that can demonstrate consistent production quality, application engineering support, and resilient sourcing will be better positioned to retain strategic accounts and capture new programs that prioritize supply assurance over lowest-cost sourcing.
These trends carry embedded risks. Technology choices that appear advantageous today may face obsolescence pressure if network architectures shift toward new frequency plans, beamforming strategies, or integrated RF modules that reduce discrete switch count. Regulatory uncertainty around spectrum allocation and orbital coordination could delay program timing or alter component specifications mid-cycle. Cost pressure in high-volume wireless and consumer-adjacent applications could compress margins for suppliers that fail to differentiate on performance or lifecycle support. Finally, consolidation activity may accelerate, altering supplier relationships and forcing customers to reevaluate qualification pipelines, second-source strategies, and long-term roadmap alignment.
Strategic Actions for Decision-Makers Across the Value Chain
For manufacturers and product leaders, the priority is to align switch roadmaps with the applications where performance differentiation is both measurable and commercially rewarded. This means investing in architectures that improve isolation, reduce loss, and support broader frequency coverage while maintaining production consistency and qualification clarity. Teams should prioritize modular product families that can be adapted across cellular, broadband, satellite-adjacent, and industrial environments without fragmenting engineering resources. Equally important is strengthening design-in support: application notes, integration guidance, thermal and reliability documentation, and test-proven reference configurations can materially accelerate adoption in programs where switching performance affects overall system performance. Manufacturers should also evaluate second-source strategies and supply assurance capabilities early, since procurement teams increasingly weigh continuity and traceability alongside technical specifications.
For investors and corporate development teams, the market offers segmentation-specific opportunities rather than a uniform growth story. High-reliability aerospace and defense switching, broadband infrastructure expansion, and satellite-linked communication ecosystems represent segments where technical differentiation and qualification depth translate into more defensible revenue streams. In contrast, commoditized high-volume segments may deliver volume but limited margin expansion unless paired with integration advantages or platform-level partnerships. Due diligence should therefore focus on product roadmaps, technology ownership, qualification pipelines, customer concentration, and the ability to support long-lifecycle deployments. Portfolio construction should weigh the trade-off between scale-driven semiconductor platforms and specialized electromechanical or high-power solutions, recognizing that both can be attractive but require distinct execution models and customer engagement strategies.
For procurement and systems integration teams, the strategic emphasis should shift from unit price alone toward total cost of qualification, integration risk, and lifecycle reliability. Switching components that reduce design iterations, simplify calibration, and deliver predictable behavior under real-world thermal and interference conditions can lower program risk and shorten deployment timelines. Procurement strategies should incorporate supplier capability in application engineering, testing support, and documentation quality, particularly for programs where RF path integrity directly impacts throughput, coverage, or mission reliability. Where possible, qualification planning should account for regulatory evolution in spectrum management and orbital coordination, ensuring that selected components remain suitable as frequency plans, interference conditions, and system architectures evolve over the program lifecycle.
The RF switches market is expanding within a framework that rewards clarity of application focus, technical differentiation, and supply assurance. Executives who map their strategies to the segments where switching performance, reliability, and integration flexibility carry financial weight will be better positioned to capture value as the market moves from steady growth toward more segmented, performance-driven competition. For organizations seeking deeper segmentation data, region-specific demand patterns, detailed competitive benchmarking, and tailored scenario planning, the full research report provides the additional granularity required to translate these market-level insights into executable commercial decisions.
For detailed analysis of this topic, please visit the official page: RF Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com