

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
HGH Market to Hit $9.72B by 2032: The Structural Shifts Behind 8.52% CAGR

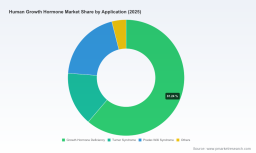
Navigating the Human Growth Hormone Market: Strategic Trends and Commercial Opportunities Through 2032
The human growth hormone (HGH) market has entered a phase of deliberate expansion, characterized by steady revenue growth, evolving therapeutic applications, and a competitive landscape that rewards innovation in delivery mechanisms and patient-centric design. As procurement, R&D, and commercial strategy teams evaluate their positioning, understanding the structural forces shaping demand, regulatory pathways, and competitive differentiation becomes essential. The market is projected to grow from 5,530 million in 2025 to approximately 9,720 million by 2032, implying a compound annual growth rate of 8.52 percent across the 2026–2032 forecast horizon. This trajectory reflects more than incremental volume increases; it signals a maturing ecosystem where therapeutic value, dosing convenience, and real-world adherence are increasingly decisive commercial factors.
Follicle Stimulating Hormone Market
Market Snapshot and Core Challenges
The revenue trajectory across the 2020–2025 historical period demonstrates consistent expansion, with growth accelerating as therapeutic indications broaden and formulation innovations begin to translate into clinical adoption. The current market size and forward projections suggest that demand is not solely dependent on population growth or diagnostic expansion; rather, it is being reshaped by product lifecycle decisions, regulatory milestones, and shifting treatment paradigms. At the same time, the competitive structure remains moderately concentrated, with a handful of multinational manufacturers accounting for a significant share of total revenue—an environment that creates both stability and pressure for differentiation.
Several structural challenges are redefining how companies approach commercialization and portfolio strategy:
- Formulation and adherence friction continue to influence treatment persistence. Daily injection regimens have historically created logistical and compliance burdens for patients and caregivers. Even as manufacturing capabilities improve, the practical reality of long-term therapy means that dosing frequency, device usability, and training support remain central to real-world outcomes.
- Regulatory pathways are becoming more nuanced, not simply more permissive. Recent approval activity has expanded indications in both pediatric and adult populations, but each new label extension introduces new evidence requirements, competition dynamics, and reimbursement scrutiny. Companies must navigate a landscape where clinical differentiation and post-market data generation are increasingly tied to market access.
- Supply continuity is emerging as a commercial vulnerability. Intermittent constraints on established products highlight how demand surges, manufacturing complexity, and distribution readiness can intersect to create availability gaps. In a therapeutic category where treatment disruption can affect patient outcomes and provider trust, supply resilience is a strategic asset rather than an operational afterthought.
For decision-makers, the implication is straightforward: growth potential exists, but it is increasingly contingent on execution quality across formulation strategy, indication expansion, and supply reliability. Market momentum alone will not guarantee share performance if product design or access readiness lags behind competitor offerings.
Key Drivers Reshaping the Growth Hormone Landscape
Technology Innovation and Long-Acting Formulations
One of the most consequential shifts in the HGH market is the move toward less frequent dosing through long-acting and prodrug-based approaches. Weekly or extended-duration formulations are designed to address a practical bottleneck in chronic therapy: daily injection burden. By reducing dosing frequency, these products aim to improve adherence, simplify caregiver routines, and potentially enhance the patient experience across pediatric and adult use cases. The strategic importance of this innovation goes beyond convenience; it alters the commercial conversation by linking formulation science directly to persistence, which in turn influences therapeutic outcomes and provider preferences.
Recent regulatory activity underscores how rapidly this area is evolving. In mid-2025, regulators approved a long-acting product for adult growth hormone deficiency, extending the addressable population beyond pediatric care. Around the same period, a separate approval expanded pediatric indications for another long-acting therapy, including use in short stature born small for gestational age and Noonan syndrome. These milestones reflect a broader trend in which formulation innovation is being matched by indication expansion, creating multiple pathways for value creation. For manufacturers, the competitive question is no longer only whether a product works, but how well it fits into treatment routines, monitoring protocols, and long-term care plans.
Human Elisa Kits Market
Regulatory Evolution and Indication Expansion
The regulatory environment is facilitating broader use of growth hormone therapies while simultaneously raising the bar for evidence and differentiation. Approvals that extend treatment to new patient subgroups create commercially meaningful opportunities, but they also intensify scrutiny around comparative efficacy, safety profiles, and real-world performance. The result is a market in which regulatory success is increasingly linked to robust clinical development, clear therapeutic positioning, and post-approval data strategies that support reimbursement and adoption.
The expansion of pediatric indications illustrates this dynamic well. As labels grow to encompass additional diagnoses, manufacturers must demonstrate relevance across varied clinical contexts, each with distinct patient needs and provider expectations. At the same time, companies are pursuing supplemental applications to extend the reach of existing products. This pattern suggests a market where lifecycle management is becoming as important as initial launch performance. For strategic planners, regulatory momentum should be interpreted not just as a milestone, but as a trigger for downstream operational readiness: payer engagement, clinical support, and supply planning must align with the pace of label expansion.
Demand-Side Shifts Toward Broader Patient Populations
Demand is being shaped by a widening view of who benefits from growth hormone therapy. Historically, the category has been closely associated with pediatric deficiency and specific syndromic conditions. Today, growing recognition of adult growth hormone deficiency and expanded pediatric indications is broadening the commercial canvas. This shift carries several implications. First, it increases the long-term value of therapies that can serve patients across life stages or transition pathways. Second, it encourages providers to think beyond short-term treatment goals toward continuity of care, monitoring, and individualized dosing. Third, it elevates the importance of educational support and clinical service infrastructure, particularly where treatment decisions involve complex diagnosis or multidisciplinary care.
PW Consulting Health Care Research Center
Behaviorally, this means that procurement and clinical teams are increasingly evaluating products not only on unit economics, but also on how well a therapy integrates into care workflows and patient support programs. Companies that anticipate these demand-side expectations—through device design, educational materials, and service models—can differentiate even in a category with established therapeutic standards.
Supply Chain Sensitivity and Manufacturing Complexity
The HGH market also illustrates how supply-side dynamics can influence commercial reputation and market access. High-demand products have experienced intermittent availability constraints, reminding the industry that formulation complexity, production scale-up, and distribution readiness can become bottlenecks under growth conditions. These episodes matter because they intersect with patient reliance on continuous therapy. When supply is disrupted, the consequences extend beyond short-term lost volume; they can affect provider confidence and create openings for competitors with more resilient operations.
As demand broadens and long-acting options gain traction, manufacturers will need to treat supply chain resilience as part of product strategy. This includes capacity planning, redundancy in critical production steps, and proactive communication with procurement and clinical partners. In a concentrated market, operational reliability can become a competitive advantage as meaningful as formulation or indication breadth.
Competitive Landscape and Leading Strategies
The competitive environment is anchored by a mix of global pharmaceutical companies with established biosimilar and innovator portfolios, alongside specialized firms pursuing differentiated delivery technologies. Several players have built their positioning around long-acting or extended-dosing platforms, while others continue to compete on established daily formulations, manufacturing scale, and franchise breadth. The market’s moderate concentration suggests that incumbents hold meaningful share, but not to the degree that new formulations or indication-based differentiation cannot shift commercial dynamics.
Leading strategies in this space tend to converge around a few themes:
- Lifecycle extension through indication expansion. Companies are pursuing additional labels that widen the population eligible for therapy, often extending into pediatric subgroups or adult deficiency. This strategy increases the commercial relevance of existing products while requiring sustained clinical evidence and regulatory execution.
- Formulation-led differentiation. Extended-dosing technologies are being used to create clearer product distinction, emphasizing reduced injection frequency and improved convenience. Where these formulations reach approval across multiple indications, they can reshape prescribing preferences by aligning therapeutic value with patient and caregiver burdens.
- Portfolio breadth and franchise strength. Some manufacturers compete by maintaining a range of products across daily and long-acting formats, allowing them to serve varied clinical needs and procurement preferences. This approach can be particularly valuable when supply continuity or regional access requirements differ across markets.
- Partnerships and co-development arrangements. In certain cases, collaboration models have been used to combine development capabilities, commercialize long-acting options, or share the commercial burden of specialized products. These arrangements reflect the reality that innovation in this category often requires coordinated regulatory, manufacturing, and market-access execution.
The competitive landscape is likely to continue evolving along two parallel tracks. Incumbents with strong franchises and manufacturing infrastructure will seek to defend share through indication expansion, supply reliability, and service-oriented commercialization. At the same time, companies with differentiated delivery technologies may gain relevance by addressing adherence and convenience pain points more directly. New entrants and biosimilar-focused players can also influence pricing dynamics and availability, especially where multiple products compete in similar therapeutic niches. The result is a market that rewards both scientific innovation and execution discipline.
Forward Outlook: Three Trends to Watch
Trend 1: Extended-Dosing Formulations Will Reshape Adoption Patterns
Over the next several years, long-acting and weekly formulations are likely to occupy an increasingly prominent position in treatment discussions, particularly where adherence and caregiver burden are central concerns. If regulatory momentum continues and real-world evidence supports persistence benefits, these products could shift prescribing norms and expand the commercial relevance of convenience-driven differentiation. The opportunity for manufacturers lies in pairing formulation advantage with strong clinical support, device usability, and patient education. The risk is that benefit expectations outpace demonstrated outcomes or that access and reimbursement frameworks lag behind clinical approval, limiting the speed of adoption.
Trend 2: Adult and Expanded Pediatric Indications Will Broaden the Addressable Market
Growth in the category is expected to be supported not only by volume increases but also by broader indication use. Adult growth hormone deficiency and additional pediatric subpopulations represent commercially meaningful avenues, especially if diagnosis, referral, and treatment initiation pathways become more efficient. This trend suggests that companies should prepare for more diverse patient profiles and more varied care settings. Commercial strategies that rely on a narrow view of the patient journey may underutilize the market’s full potential. At the same time, expanded indications raise the importance of real-world data, safety monitoring, and payer alignment, since broader use invites closer scrutiny of cost-effectiveness and treatment protocols.
Trend 3: Supply Continuity and Operational Resilience Will Become Differentiators
As demand grows and product options multiply, supply reliability may emerge as a more visible competitive factor. Intermittent constraints on established products have already demonstrated how availability issues can affect provider trust and patient continuity. In the near term, companies that invest in capacity planning, production redundancy, and transparent communication may be better positioned to protect franchise value. This trend also carries a caution: scaling growth without sufficient operational readiness can create reputational and commercial risks that outweigh the benefits of rapid volume gains. For procurement and planning teams, this underscores the importance of evaluating supplier stability alongside price and product features.
Strategic Implications for Decision-Makers
The growth hormone market is offering a mix of therapeutic expansion, formulation innovation, and execution-driven competition. Different stakeholders will need to prioritize different aspects of this landscape.
For Manufacturers and Product Developers
- Evaluate lifecycle strategies that combine formulation innovation with indication expansion, ensuring that regulatory milestones are matched by supply readiness and market-access planning.
- Invest in patient and provider support infrastructure that reinforces adherence value, particularly for long-acting or less familiar treatment regimens.
- Treat manufacturing resilience as a strategic priority, not just an operational task, especially when pursuing growth in high-demand segments.
For Investors and Portfolio Strategists
- Focus on companies that can convert regulatory progress into durable commercial traction through real-world performance, access alignment, and reliable supply.
- Track the pace of adoption for extended-dosing products as an indicator of whether convenience-led differentiation translates into share movement.
- Monitor indication expansion timelines and reimbursement developments, since these often determine whether label breadth becomes revenue breadth.
For Procurement, Payer, and Clinical Leaders
- Assess products on a broader set of criteria, including dosing convenience, device usability, support programs, and supply reliability, alongside acquisition cost.
- Anticipate variability in availability and build contingency approaches for high-dependency therapies where interruptions can affect continuity of care.
- Align procurement strategy with clinical needs so that product selection reflects both economic and treatment-persistence considerations.
Across these roles, the recurring theme is that market opportunity is expanding, but capturing it depends on readiness across regulatory, commercial, and operational dimensions. Companies and buyers that evaluate the landscape with this integrated lens are better positioned to translate market growth into durable value.
For stakeholders seeking a more granular view of segmentation dynamics, regional revenue distribution, company-level positioning, and forward scenario analysis, the full market research report provides deeper detail across the metrics and sub-segments that support planning and investment decisions. Exploring that level of detail can help translate broad market direction into specific, actionable strategy.
For detailed analysis of this topic, please visit the official page: Human Growth Hormone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com