

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Nut Ingredients Market 2026: Decoding the 6.39% CAGR Growth Drivers & Shifts

Strategic Trends and Commercial Opportunities in the Nut Ingredients Market
The global nut ingredients market has moved from a niche category to a foundational layer in modern food manufacturing. Over the 2020 to 2025 period, revenue grew from approximately 16.05 billion USD to 23.12 billion USD, reflecting a steady acceleration as processors, formulators, and brand owners expanded beyond whole nuts into flours, butters, pastes, and protein isolates. The forward trajectory points to 24.17 billion USD in 2026, rising to 35.73 billion USD by 2032, with a compound annual growth rate of 6.39 percent. This is not a simple extension of snack consumption; it is a structural shift in how nuts are sourced, processed, and embedded into mainstream product architectures.
For decision-makers, this expansion matters because nut ingredients now sit at the intersection of taste, texture, protein delivery, and clean-label formulation. The category is no longer just about almonds, cashews, or walnuts as finished snacks. It is about ingredient-ready outputs that behave predictably in industrial baking, confectionery, beverages, functional nutrition, and personal care. That breadth creates value, but it also introduces tradeoffs in supply consistency, regulatory handling, and formulation precision. The companies that can balance volume, quality, and traceability are positioned to capture a larger share of downstream growth.
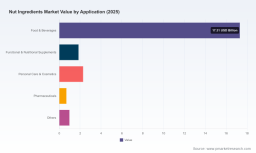
At the same time, the market is not uniformly distributed in its value pools. Europe and Asia Pacific together account for the largest regional shares of current revenue, while North America remains a highly active innovation and processing hub. In terms of ingredient forms, whole nuts continue to represent the largest segment, but processed formats such as butters, flours, and other specialty preparations are increasingly important in industrial applications. On the application side, food and beverage remains the dominant destination for nut ingredients, while smaller but strategically important demand comes from functional supplements, personal care formulations, and pharmaceutical uses. Conventional products still dominate total volume, though organic and clean-label lines are gaining relevance among premium and health-oriented buyers.
The concentration profile also tells a strategic story. The market structure is relatively consolidated, with the top three players holding roughly 65 percent and the top five holding about 75 percent of total market value. This level of concentration suggests that scale, relationships with grower groups, and processing capabilities remain powerful advantages. Yet it also indicates room for targeted entry by specialists offering differentiated formats, new cultivars, and regionally tailored supply chains. The competitive battleground is no longer just price per pound. It is consistency, functionality, sourcing narrative, and speed of reformulation.
Core Challenges and Inflection Points
Several overlapping pressures are reshaping how the nut ingredients market creates value, and each one has direct operational implications.
Raw material volatility remains a central challenge for producers and purchasers alike. Recent crop data indicates that California almond production reached approximately 3.0 billion pounds in 2025, the second largest on record, while walnut output was forecasted at 710,000 tons, up 18 percent from the prior year. Large harvests can ease short-term availability, but they also place downward pressure on prices and complicate margin planning for processors who have already locked in long-term contracts or invested in capacity. For buyers, this volatility creates a need for more flexible procurement strategies and stronger diversification across origins and nut types.
Regulatory compliance is another inflection point. Nut allergens require mandatory labeling under US FDA rules and comparable EU requirements, which affects product development, line management, and consumer communication. At the same time, sourcing increasingly has to account for traceability and due diligence expectations under frameworks such as the EU Deforestation Regulation. For global ingredient supply chains, this means that origin documentation, chain-of-custody practices, and supplier transparency are moving from compliance overhead to core commercial requirements. Companies that cannot demonstrate credible sourcing may find themselves excluded from certain buyers, formulations, or export channels.
A third challenge is the tension between scale and specificity. Demand is rising for clean-label, natural, and plant-based applications in bakery, confectionery, and snacks, but industrial customers want repeatable functionality, predictable viscosity, controlled particle size, and consistent flavor profiles. That combination favors processors who can standardize outputs across batches while still meeting clean-label and allergen-management expectations. The market is therefore caught between two pulls: the need for large-scale supply efficiency and the need for precision ingredient performance. Those who can resolve that tension are likely to command stronger buyer loyalty and better pricing power.
Key Drivers Shaping the Market
The expansion of the nut ingredients market is not being driven by a single force. It is the cumulative effect of technology, regulation, demand behavior, and supply economics. Understanding how these drivers interact is essential for positioning product portfolios and sourcing strategies.
Processing Innovation and Functional Ingredient Design
Technology is reshaping what nut ingredients can do in finished products. Modern processing is increasingly focused on producing bakery-friendly flours, stable butters and pastes, protein isolates, and value-added blends that perform reliably across a range of formulations. This matters because formulation teams are under pressure to reduce synthetic additives, improve texture with fewer stabilizers, and increase protein density without compromising taste. Nut-based ingredients align well with these goals, especially when they are supplied in consistent, ingredient-ready formats.
The industry context reinforces this direction. Recent product activity includes new mixed nut blends, organic and non-GMO lines covering cashew and pecan pieces, and expanded ranges of hazelnut and almond pastes for confectionery and bakery use. These introductions are not isolated launches. They reflect a broader pattern in which processors are building ingredient portfolios that can be integrated directly into industrial production lines. The strategic payoff is clear: when a supplier can offer both raw material reliability and formulation-ready specifications, it becomes a development partner rather than a simple commodity vendor.
Policy, Labeling, and Sourcing Expectations
Policy and regulatory evolution is shaping both product design and supply chain architecture. On the labeling side, allergen disclosure requirements push manufacturers toward stricter separation, clearer ingredient specifications, and more disciplined documentation. On the sourcing side, traceability expectations are becoming a baseline requirement, especially for buyers with global footprints or retail customers who demand deforestation-related due diligence for key inputs.
This does not simply raise compliance costs. It changes the competitive filter. Ingredient suppliers that can provide traceable origin data, allergen-managed processing environments, and consistent documentation are better positioned to serve regulated categories and export markets. It also creates an opportunity for differentiation through sourcing narratives, especially where growers and processors can demonstrate responsible farm management, water stewardship, and supply chain transparency. In practice, the regulatory conversation is becoming part of the commercial conversation, not a separate back-office function.
Dairy Ingredients Market
Demand-Side Shifts in Food, Beverage, and Adjacent Categories
The strongest structural driver remains demand behavior, particularly the rise of plant-based, protein-forward, and clean-label formulations. Nut ingredients are increasingly chosen not only for flavor but also for functional contribution: mouthfeel in sauces and dressings, richness in confectionery fillings, texturizing in baked goods, and protein density in nutritional products. This marks a shift from treating nuts as flavor accents to treating them as structural ingredients.
This trend is visible across bakery, confectionery, snacks, and adjacent sectors such as functional supplements and personal care. In food and beverage, the largest application pool, ingredient buyers are seeking formats that integrate efficiently into high-volume production. In functional nutrition, there is growing interest in nut-based proteins and nutrient-dense formulations. In personal care and cosmetics, nut oils and butters continue to hold relevance in premium skin-care applications. The common thread is demand for ingredients that are both desirable to consumers and practical for manufacturers.
Supply Economics and Procurement Strategy
Cost structures and supply availability are becoming more strategic rather than purely logistical. Changes in crop size, geographic concentration, and processing capacity influence price stability and negotiating power. When harvests are large, buyers may benefit from shorter-term price relief, but long-term planning remains complicated by weather variability, labor constraints, and transportation dynamics. For processors, the challenge is to maintain throughput and margin while managing uneven raw material inflows.
This environment favors procurement strategies that combine multi-origin sourcing, forward contracting, and ingredient flexibility. It also rewards companies that can convert variable raw inputs into consistent finished outputs. In other words, value is increasingly created by the ability to manage variability, not simply to buy cheaply. That is why supply chain design is now a competitive differentiator in the nut ingredients market, not just an operational function.
Competitive Landscape and Leading Strategies
The market’s concentration profile means that scale players can exert significant influence over pricing, supply, and category direction. At the same time, several recent moves show that competition is being waged through specialization, acquisitions, and targeted product expansion rather than broad commodity positioning alone.
Large integrated players are leveraging broad ingredient capabilities and strong food-manufacturing relationships. Companies with almond, nut butter, protein isolate, and processed nut ingredient offerings are well positioned to serve bakery, confectionery, and foodservice applications at scale. Their advantage lies in the ability to connect raw supply with standardized ingredient formats and to support large customers who need reliable volume and repeat specifications. Where these players also invest in protein-rich and plant-based ingredient development, they can address multiple formulation goals simultaneously.
Other participants are competing through narrower but deeper positioning. Some suppliers focus on roasted, seasoned, and private-label-ready tree nuts and peanuts for industrial food manufacturers. Others concentrate on premium nut butters, custom formulations, or bakery-specific fillings and pastes. This fragmentation matters because industrial buyers increasingly need inputs that are tailored to specific end uses rather than generic bulk supply. A supplier that understands how a nut paste behaves in a confectionery filling or how a nut flour interacts with gluten-free systems can command more strategic relevance than a supplier competing only on volume.
Recent industry activity illustrates how these strategies are evolving. Puratos Group expanded its clean-label positioning through an acquisition that strengthened nut butter and paste offerings for baking innovation. Separately, Guardian Capital Partners acquired a California-based developer of specialty nut-based ingredient solutions, signaling investor interest in formulation-focused capabilities. On the product side, Blue Diamond Growers introduced mixed nut blends under an expanded portfolio, Barry Callebaut rolled out new hazelnut and almond pastes for confectionery and bakery, and another processor launched organic and non-GMO nut ingredients for snacks and cereals. These moves are consistent with a market that is moving toward differentiated formats, clean-label credibility, and application-specific performance.
PW Consulting
The competitive trend is therefore dual. Consolidation continues to matter at the top end, but differentiation is intensifying across the rest of the field. Scale gives credibility and supply security. Specialty gives responsiveness, formulation depth, and niche access. The most resilient players are those that can manage both: enough scale to be reliable, and enough specificity to support innovation. For new entrants, the opportunity lies not in trying to out-scale incumbents, but in solving a concrete formulation or sourcing problem better than the current alternatives.
Future Trajectory: What to Expect Over the Next Three to Five Years
Based on current momentum and the structure of demand, a few trends are likely to define the next stage of market development.
First, ingredient functionality will become a more important battleground than nominal categorization. Buyers will increasingly evaluate nut ingredients by performance attributes such as emulsification behavior, viscosity stability, particle size consistency, and compatibility with clean-label systems. As a result, suppliers that can deliver technical documentation, application support, and repeatable batch quality will gain leverage. This will push more processors toward value-added processing and closer collaboration with R&D teams.
Dried Fruit Ingredients Market
Second, traceability and origin transparency will move from “important for compliance” to “important for commercialization.” As buyers expand export activity and retail partners demand stronger due diligence, ingredient suppliers with demonstrable sourcing records and allergen-managed processes will have a practical advantage. The market is likely to see more emphasis on supply chain mapping, documentation, and responsible sourcing narratives as part of the core product proposition.
Third, the category will continue to diversify across forms and applications, with processed ingredients gaining relative importance. Butters, flours, pastes, and protein-rich formats should continue to attract formulation investment because they can be integrated more easily into higher-value food and beverage systems. At the same time, organic, non-GMO, and clean-label lines will likely keep growing in premium segments, even if conventional products remain the volume backbone. This dual structure creates a market where overall growth is steady, but the most attractive margins may shift toward specialized, application-ready offerings.
These trends carry risk as well. Crop variability can still disrupt supply and pricing. Regulatory changes may increase documentation burden and raise the cost of market access. Clean-label expectations may conflict with the need for long shelf life or cost-efficient large-scale production. And consumer preferences can shift quickly, especially in snack, confectionery, and wellness categories. Companies that build flexibility into sourcing, product format, and formulation support will be better placed to absorb these shocks.
Strategic Actions for Decision-Makers
For manufacturers and ingredient suppliers, the priority is to strengthen application-level value rather than compete solely on bulk supply. That means investing in consistent processing outputs, improving technical support for bakery, confectionery, and snack formulators, and building portfolio breadth across whole nuts, flours, butters, pastes, and protein-oriented ingredients. Suppliers should also treat traceability and allergen management as integral to product design, not as separate compliance tasks, because these capabilities increasingly influence buyer selection and market access.
For investors, the most durable value may lie in capabilities that connect sourcing reliability with differentiated ingredient formats. Scale businesses with strong grower relationships and processing infrastructure remain relevant, but specialist assets that offer clean-label positioning, formulation depth, or application-specific performance may command premium strategic value. Diversification across nut types and end markets can also help reduce exposure to single-crop volatility. In this environment, the key question is whether a company can convert raw supply variability into repeatable commercial value.
For procurement teams and product developers, the practical move is to diversify both supplier base and ingredient formats. Relying too heavily on one origin or one nut type increases exposure to price swings and supply interruptions. At the same time, evaluating ingredient options by functional performance and documentation quality can reduce reformulation risk and speed time to market. Where possible, procurement should align with R&D early so that sourcing decisions support long-term formulation goals rather than short-term cost minimization alone.
For organizations planning deeper market entry or portfolio changes, the most useful next step is to ground decisions in detailed segment-level data. Market-level figures tell the direction of travel, but the actionable choices sit in the specifics: which forms are expanding fastest in which applications, how concentration varies by segment, where clean-label premiums are most defensible, and how sourcing constraints differ by region and crop cycle. Accessing comprehensive market intelligence can help validate assumptions before capital or capacity is committed, and it can support more precise prioritization across product lines, geographies, and customer segments. For teams that need tailored views of subsegments, competitive positioning, or sourcing implications, a full research report can provide the level of detail required to move from strategic direction to execution planning.
For detailed analysis of this topic, please visit the official page: Nut Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com