

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PICV Market Growth at 4% CAGR: Commercial & APAC Drivers Redefining Pressure Control Strategy

Strategic Horizons: Navigating the Pressure Independent Control Valves Market
The Pressure Independent Control Valves (PICV) market has transitioned from a specialized engineering niche to a critical component of modern hydronic system design. With a global market valuation of USD 295.0 Million in 2025, the sector reflects a broader shift toward energy-efficient building operations and variable-flow HVAC architectures. The market has demonstrated consistent growth, expanding from USD 220.0 Million in 2020 at a compound annual growth rate (CAGR) of 4.0 percent through the forecast period extending to 2032. While the historical trajectory shows steady expansion, reaching USD 387.0 Million by 2032, the market is not without its complexities. Investors and strategic planners must understand not just the headline figures, but the underlying structural dynamics, competitive positioning, and technological inflection points that will determine long-term value creation.
For enterprise decision-makers, the PICV market represents a convergence of regulatory pressure, technological advancement, and evolving operational performance expectations. The widespread adoption of PICVs is no longer merely a technical preference; it is increasingly a compliance and performance imperative. ASHRAE 90.1 standards, for instance, require a 50 percent reduction in energy consumption in initial building models, and PICV technology has proven capable of delivering 20-40 percent HVAC energy performance improvements through stable flow management and reduced system inefficiency. This regulatory backdrop creates a structural tailwind that transcends short-term economic cycles, anchoring demand in long-term building performance mandates rather than discretionary capital expenditure.
Diverter Valves Market
Market Context And Structural Challenges
A Market In Transition
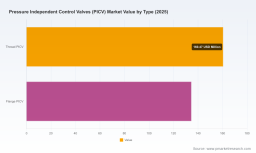
The PICV market's expansion to a projected USD 387.0 Million by 2032 is underpinned by a 4.0 percent CAGR, yet this aggregate figure masks regional and application-level variations that demand careful strategic navigation. Asia Pacific represents the largest revenue contribution at USD 100.65 Million, followed by Europe at USD 75.83 Million and North America at USD 69.01 Million, with Latin America and the Middle East and Africa each contributing approximately USD 24.7 Million and USD 24.81 Million respectively. On the application side, commercial buildings account for USD 159.26 Million of total revenue, residential applications contribute USD 81.36 Million, and industrial use cases represent USD 54.38 Million. By product type, threaded PICVs generate USD 160.47 Million while flange PICVs account for USD 134.53 Million. The market exhibits moderate concentration, with the top three players holding 32.0 percent and the top five commanding 48.0 percent of total market share.
These figures point to a market that is broad-based but increasingly competitive at the margins. The commercial segment's dominance reflects the ongoing retrofit and modernization of office, retail, and institutional buildings where system balancing and energy accountability are paramount. Residential growth, while smaller in absolute terms, is being propelled by higher HVAC adoption rates in new housing developments and stricter energy codes in multiple jurisdictions. Industrial applications, though the smallest segment, are gaining attention due to the thermal control demands of data centers, manufacturing facilities, and processing plants where precise flow regulation translates directly into operational cost savings.
Key Challenges And Inflection Points
Despite favorable long-term demand drivers, the PICV market faces several structural challenges that will shape competitive outcomes over the next five years. First, installer and commissioning expertise remains a bottleneck. PICV technology delivers its full value only when properly sized, integrated, and calibrated within the broader hydronic system. In markets where skilled HVAC technicians are in short supply, the performance gap between theoretical efficiency gains and realized outcomes can undermine customer confidence and slow adoption. This operational dependency means that product innovation must be paired with training, documentation, and commissioning support to sustain market momentum.
Second, the market is navigating a tension between standardization and customization. End-users increasingly demand valves that can handle wider flow ranges, integrate with building automation platforms, and support variable-flow optimization without requiring separate balancing valves. However, engineering more versatile products can increase manufacturing complexity and cost. Companies that can streamline the balance between modular design, scalability, and application-specific performance will gain a significant advantage in both commercial and industrial segments.
Pinch Valve Market
Third, certification and compliance requirements are becoming more stringent across regions. UL certification and ISO 9001:2015 compliance are now baseline expectations for commercial and industrial PICV applications, and product documentation, including Environmental Product Declarations, is increasingly tied to procurement decisions in sustainability-driven markets. Firms that treat compliance as a strategic capability rather than a checkbox exercise will be better positioned to secure specifications in large-scale tenders and public-sector projects.
Key Drivers Of Market Change
Regulatory And Energy Performance Mandates
Policy and regulatory frameworks are the most durable demand driver for PICVs. Standards such as ASHRAE 90.1 impose rigorous energy performance thresholds on new construction and major renovations, creating a compliance pathway that favors variable-flow hydronic systems with pressure-independent control. The ability of PICVs to maintain stable flow irrespective of pressure fluctuations directly reduces pump energy consumption, improves delta-T performance, and minimizes inefficient operation during part-load conditions. These outcomes align directly with building energy codes and green building certification requirements, making PICVs a pragmatic solution for developers, facility managers, and engineering consultants seeking to meet mandated targets without overbuilding system capacity.
Technological Innovation And Smart Integration
Technological advancement is transforming PICVs from passive balancing devices into active, data-enabled components of the building control ecosystem. Leading manufacturers are embedding IoT connectivity, integrated energy measurement, and actuator interfaces that support seamless integration with building automation systems. Products such as Danfoss AB-QM 4.0 and AB-QM series with NovoCon actuators, Belimo PIQCV and Energy Valve™ IoT-connected PICVs, and Johnson Controls VP140 Series and XT-range valves illustrate this shift toward combined balancing, control, and monitoring functionality. Siemens' integrated PICVs that combine differential pressure control, regulation, and 2-port valve functions further demonstrate how multi-function design is reducing the number of components required for commissioning, simplifying installation, and improving system reliability.
Recent product activity underscores the pace of this innovation cycle. Danfoss released updated data sheets and brochures for its AB-QM 4.0 PICVs and actuators in early and mid-2026, alongside Environmental Product Declarations for multiple variants, signaling a strategic emphasis on both technical performance and sustainability documentation. Griswold Controls showcased its Energy FIT system and actuator integrations at the AHR Expo 2026, highlighting the growing importance of energy-focused commissioning and monitoring capabilities. ISMA Controlli's LIBRA PICV range update in May 2026 further illustrates how manufacturers are continuously refining dynamic circuit control performance to meet evolving application requirements. These developments are not isolated product updates; they reflect a broader industry move toward valves that support both hydraulic performance and operational visibility.
Demand-Side Shifts In Building Operations
Demand-side behavior is changing in ways that favor PICV adoption. Building automation infrastructure expansion is accelerating, driven by asset owners seeking to reduce operational expenditures, improve tenant comfort, and meet sustainability commitments. At the same time, smart building adoption and heightened indoor air quality awareness are increasing the role of precise environmental control in specification decisions. PICVs with integrated control and monitoring features are increasingly valued because they provide system-level visibility that supports predictive maintenance, fault detection, and performance optimization. This demand-side preference is particularly pronounced in commercial real estate, where energy intensity and occupancy variability make stable flow control a strategic operational asset.
Supply Chain And Material Considerations
Cost structures and material choices are becoming a more visible competitive dimension. Scaling- and clogging-resistant polymer components in PICV designs are increasingly favored because they support long lifetime and reliability under varying operating conditions, reducing maintenance interventions and extending service intervals. At the same time, manufacturers must manage raw material availability, production consistency, and lead-time volatility across global supply chains. Companies that can secure reliable sources of high-performance polymers, standardize insert and body geometries where feasible, and maintain quality assurance systems aligned with ISO 9001:2015 will be better positioned to manage cost volatility while preserving product performance.
Competitive Landscape And Strategic Positioning
Leading Players And Differentiation Strategies
The PICV market is characterized by a diverse competitive set spanning established multinational manufacturers, specialized valve producers, and regional specialists. Danfoss has built a strong position around its AB-QM 4.0 and AB-QM series, emphasizing stable flow, energy savings, and commissioning ease through actuator-compatible pressure-independent balancing and control valves for heating and cooling applications. Belimo competes with a focus on precision hydronic control and energy measurement, leveraging its PIQCV, EPIV, and Energy Valve™ IoT-connected PICVs to address variable-flow optimization and operational data integration. Johnson Controls differentiates through the VP140 Series and XT-range PICVs, which are designed to eliminate the need for separate balancing valves and streamline stable flow performance within building automation contexts. Siemens takes an integration-led approach, combining differential pressure control, regulation, and 2-port valve functions in a single device to optimize delta-T and commissioning outcomes.
In the Americas, Bray International offers the SS Series and SSM Series for threaded and flanged applications respectively, emphasizing dynamic balancing and high-rangeability control in hot and chilled water systems. Griswold Controls has built recognition around its PIC-V®, MVP®, Pinnacle, and PIM series designed to replace separate balancing and control pairs in HVAC, with strong exposure in data center and industrial applications through its Tiger Controls partnership ecosystem. Xylem contributes with Bell & Gossett Ultra Setter PICVs and Press Connect fittings aimed at simplifying balancing and control adjustments. In Europe, Frese A/S maintains specialized PICV lines for Nordic and broader European hydronic applications, while Caleffi's FLOWMATIC and other PICV series address residential and commercial HVAC balancing. IVAR's LIBRA range targets dynamic circuit control in Southern European markets, supported by recent product updates. IMI PLC, Cranfield, Pettinaroli, FAR, and Schneider Electric reinforce the diversity of the competitive field, each bringing distinct strengths in portfolio breadth, regional reach, or integration with building services and automation platforms.
This breadth of offerings creates a market where differentiation occurs along several axes: product range and size coverage, actuation and IoT compatibility, commissioning and documentation support, certification and sustainability credentials, and integration with wider building services ecosystems. Companies that can demonstrate consistent performance across these dimensions are increasingly favored in specification processes, particularly where multi-vendor or multi-building deployments require standardization and reliable technical support.
Market Evolution: Consolidation, Fragmentation, And New Entrants
The market's moderate concentration, with the top five players holding 48.0 percent of revenue, suggests room for both consolidation and continued fragmentation. Larger players with broad building automation or HVAC portfolios can leverage PICVs as part of integrated solutions that span valves, controllers, and system commissioning services. This integration advantage can be decisive in large commercial and institutional projects where single-point accountability and system-level optimization are valued. At the same time, specialized manufacturers with strong technical reputations in specific regions or applications can compete effectively by focusing on differentiated features such as wide flow coverage, insertion-based designs, high-rangeability control, or targeted industrial-grade performance.
PW Consulting Automotive & Machinery Research Center
The potential for further consolidation exists, particularly where manufacturers seek to expand product portfolios, geographic reach, or commissioning capabilities. Conversely, continued fragmentation is likely where regional standards, application requirements, and installer preferences diverge. New entrants may find opportunity by addressing underserved niches, such as data center thermal control, high-performance industrial hydronic systems, or application-specific PICVs optimized for quick commissioning and minimal maintenance. The strategic question for incumbents and entrants alike is whether to compete on portfolio breadth and integration or on focused technical excellence and service depth.
Future Trends And Commercial Opportunities
Trend 1: Energy Accountability As A Procurement Driver
Over the next three to five years, energy accountability will become a more explicit factor in procurement decisions. As building operators face rising energy costs and tighter performance reporting requirements, PICVs that deliver demonstrable flow stability, reduced pump energy, and improved delta-T performance will be prioritized in both new construction and retrofit projects. The opportunity lies in building specification support tools, performance documentation, and case-study evidence that translate technical performance into operational and financial outcomes for facility owners and engineering consultants. Companies that can connect PICV performance to energy modeling outputs, commissioning checklists, and ongoing monitoring will be better positioned to win specifications and reduce post-installation rejection risk.
Trend 2: Smart Hydronics And Data-Enabled Control
The integration of PICVs with building automation, energy measurement, and monitoring platforms will continue to deepen. This trend opens opportunities for manufacturers and solution providers to offer valves that are not just flow control devices but data-generating components within a broader operational intelligence framework. Features such as actuator compatibility, IoT readiness, and integrated energy measurement are likely to become standard expectations in commercial and increasingly in industrial applications. The commercial opportunity extends beyond hardware to include commissioning services, performance tuning, and software-enabled diagnostics that help operators sustain efficiency over the asset lifecycle. However, this trend also introduces risk if interoperability, data security, and support infrastructure are not addressed comprehensively.
Trend 3: Regional Divergence And Application Specialization
Regional and application-level divergence will create both opportunities and constraints. Asia Pacific's scale and ongoing infrastructure and building development activity present a large addressable market, but success there depends on local specification practices, distributor networks, and installer training. Europe's mature building stock and stringent energy standards support demand for retrofits and replacements, favoring manufacturers with strong technical documentation, certification, and service networks. North America's commercial segment remains a significant demand center, with data center and industrial applications gaining relevance as thermal control requirements intensify. In this environment, a one-size strategy is unlikely to succeed. Companies that align product ranges, certification, and support to regional requirements, and that develop application-specific offerings for sectors such as data centers, commercial high-rises, and industrial processing, will capture more defensible growth.
Risk Considerations
These opportunities are accompanied by risks that warrant strategic attention. Installer capability gaps can erode realized performance and weaken customer satisfaction, particularly in markets where technical training and commissioning support are under-resourced. Certification and compliance complexity may increase procurement timelines and raise costs for manufacturers operating across multiple jurisdictions. Material price volatility and supply chain disruptions can affect margins and lead times, especially for products relying on specialized polymers or insert technologies. Finally, as smart integration becomes more central, firms that fail to address interoperability, cybersecurity, and software support may face reputational and commercial consequences. Managing these risks will be as important as capturing the demand upside.
Strategic Guidance For Decision Makers
For Manufacturers
- Prioritize product architectures that balance flow range, sizing flexibility, and installation simplicity, reducing the need for separate balancing components while maintaining high rangeability and reliability.
- Invest in commissioning support, training assets, and clear documentation, including Environmental Product Declarations and certification alignment, to strengthen specification win rates and reduce post-installation performance gaps.
- Develop integration pathways with building automation and energy monitoring platforms that are transparent, interoperable, and supported by service commitments, turning hardware capability into long-term value.
For Investors
- Evaluate exposure not only by revenue scale but by alignment with structural demand drivers such as energy code tightening, smart building adoption, and application growth in data centers and industrial thermal control.
- Assess manufacturing resilience, material sourcing, and certification readiness as indicators of margin stability and risk management capability in a moderately concentrated market.
- Identify companies with credible technical differentiation, strong commissioning support, and regional execution strength, as these attributes tend to translate into more durable specification positions and customer retention.
For Procurement And Specification Teams
- Treat PICV selection as a system-level decision that should account for flow stability, commissioning ease, energy performance evidence, and integration requirements rather than unit price alone.
- Require robust performance documentation, certification alignment, and clear service commitments from suppliers to reduce variability across projects and improve long-term operational outcomes.
- Engage early with engineering and commissioning teams to ensure valve sizing, actuator compatibility, and building automation integration are addressed before procurement, minimizing rework and performance shortfalls.
The PICV market is moving through a phase where regulatory mandates, technological integration, and operational accountability are reshaping both demand and competition. For stakeholders seeking deeper segmentation, regional dynamics, application-level sizing, and customized strategic recommendations, PW Consulting's comprehensive PICV market report provides the detailed data and analysis needed to translate these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Pressure Independent Control Valves (PICV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com