

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Overactive Bladder Treatment Market: Why 4.88% CAGR and Shifting Therapies Redefine Growth

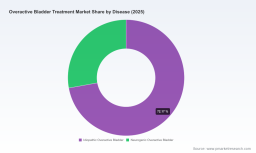
Strategic Shifts and Commercial Opportunities in the Overactive Bladder Treatment Market
The overactive bladder treatment market has entered a phase of structural transition, moving beyond incremental drug innovation toward device-based interventions and more flexible care pathways. Total market revenue reached approximately $424 million in 2025, reflecting steady expansion from the $334 million recorded in 2020. Over the next seven years through 2032, the market is projected to grow at a compound annual growth rate of 4.88%, culminating in revenue of roughly $592 million. This trajectory signals a maturing landscape where value creation will increasingly depend on how well companies align product development, reimbursement positioning, and clinical adoption rather than on volume-driven generic substitution alone.
Despite the consistent upward revenue trend, the pace of growth and the distribution of value are being reshaped by several concurrent forces. Demographic aging continues to expand the addressable patient population, yet payer environments, guideline frameworks, and technology adoption patterns are introducing new decision points for manufacturers and investors. The market is no longer defined solely by pharmaceutical volume; it is becoming a contest over clinical differentiation, procedural convenience, and the ability to demonstrate clear patient and economic outcomes.
Three challenges are particularly prominent at this inflection point. First, the traditional reliance on anticholinergic therapies is being rebalanced by safety and tolerability considerations, prompting a slower but meaningful shift toward alternative mechanisms and procedural options. Second, reimbursement variability across care settings is influencing where and how treatments are delivered, especially for device-based therapies that require distinct coding, coverage, and site-of-care strategies. Third, the competitive field is consolidating around a smaller set of players with broad portfolios, even as targeted innovators continue to introduce niche solutions that test the boundaries of standard care models.
Key Drivers Reshaping Market Momentum
Several forces are driving the current evolution of the market, and their interplay is changing both the pace of adoption and the strategic priorities of participating companies.
Technology Innovation and Breakthroughs
Innovation momentum is strongest in two areas: refined pharmacologic options and minimally invasive neuromodulation. In pharmacotherapy, newer beta-3 adrenergic agonists have provided alternatives with more favorable tolerability profiles for patients who struggle with anticholinergic side effects. In device-based care, recent approvals and engineering improvements are reducing procedural burden and expanding access to sacral and tibial neuromodulation for urge incontinence and overactive bladder symptoms. These technologies are important not only because they offer additional treatment options, but because they create opportunities to segment patients by symptom severity, treatment history, and preference for drug-free management.
The practical implication is that clinical differentiation is becoming a more valuable asset than broad label coverage alone. Devices that simplify implantation, programming, or follow-up can accelerate adoption in clinical settings that previously hesitated due to complexity or resource requirements. Similarly, oral therapies that address specific patient subgroups, including those receiving concurrent treatment for benign prostatic hyperplasia, can unlock incremental demand in crowded therapeutic categories.
Policy and Regulatory Environment
Regulatory and guideline developments are actively reshaping treatment sequencing and payer behavior. Updated clinical guidelines from leading urology and pelvic floor societies have moved away from rigid step therapy requirements in favor of shared decision-making. This shift gives clinicians more latitude to select treatments based on patient profiles and preferences, which can accelerate the uptake of both newer drugs and procedural therapies in appropriate populations.
At the same time, reimbursement policy is exerting a powerful influence on site of care and technology uptake. Notably, CMS increased reimbursement by 40% in the ambulatory surgery center setting for a tibial nerve stimulation procedure, a change that can affect where patients receive care and how providers evaluate procedural investments. Regulatory milestones such as PMA approvals for integrated sacral neuromodulation systems also matter because they validate new device architectures and can expand the commercial footprint for companies pursuing differentiated procedural solutions.
Demand-Side Changes in Patient and Clinician Behavior
On the demand side, patients are increasingly seeking treatments that minimize systemic side effects and preserve quality of life. This preference is particularly relevant for long-term management, where adherence and tolerability determine real-world effectiveness. Clinicians, in turn, are responding to the combined influence of updated guidelines, richer outcome data, and practical workflow considerations. Shared decision-making is not merely a philosophical shift; it is changing the order in which therapies are discussed and selected, especially when patients present with comorbidities or prior treatment intolerance.
For commercial teams, this means that messaging and market access strategies must address real-world usability as much as efficacy. Treatments that are easier to initiate, monitor, and sustain are more likely to be prioritized in busy clinical environments, especially when they can be aligned with patient-centered goals and reimbursement realities.
Supply Chain and Cost Structure Dynamics
Cost structures across the market are being influenced by a combination of manufacturing complexity, procedural economics, and competitive pressure. Pharmaceutical segments face the usual balance between branded differentiation and eventual generic erosion, while device segments contend with the economics of implantation, training, service, and follow-up. In both cases, the value proposition increasingly depends on total cost of care rather than unit price alone.
This environment rewards strategies that can demonstrate downstream savings, reduce repeat interventions, or simplify the care pathway. For procedural technologies, site-of-care optimization and reimbursement alignment can be as important as the device itself. For drug therapies, lifecycle planning and patient-support programs can help protect share in categories where clinical alternatives are expanding.
Competitive Landscape and Leading Strategies
The market’s competitive structure reflects a blend of large established players, device specialists, and focused innovators. Market concentration remains moderate, with the top three companies accounting for roughly 40% of revenue and the top five approaching 50%, suggesting both the presence of influential incumbents and room for differentiated entrants.
Strategic Positioning of Leading Companies
Astellas Pharma has built a recognized position in overactive bladder pharmacotherapy through its marketed product for this indication. Its strategic emphasis has centered on brand presence in a therapeutic category where tolerability and adherence strongly influence long-term performance. In parallel, Sumitomo Pharma has advanced a newer oral branded option that received FDA approval in 2024 and was subsequently approved for men with overactive bladder symptoms receiving pharmacologic therapy for benign prostatic hyperplasia. This expansion illustrates a targeted approach to patient segmentation and label broadening rather than reliance on category-wide volume alone.
On the device side, Medtronic continues to underpin a substantial share of sacral neuromodulation offerings with SNM systems used in overactive bladder and urge incontinence care. The company’s recent FDA approval of a minimally invasive tibial neuromodulation device for urge incontinence broadens its procedural toolkit and reflects a strategy of addressing multiple points in the treatment pathway. Neuspera Medical has pursued a more focused device strategy, earning PMA approval in 2025 for an integrated sacral neuromodulation system for urinary urge incontinence. By combining system components into a more unified architecture, the company is attempting to differentiate on procedural integration and usability. BlueWind Medical contributes another device angle through its implantable tibial neuromodulation system, while Axonics Modulation Technologies has been recognized for its SNM system for overactive bladder and urge incontinence.
Recent Developments and What They Signal
Recent events point to a market that is consolidating at the high end while still encouraging specialized innovation. The acquisition of Axonics by Boston Scientific integrates sacral neuromodulation technology into a broader interventional portfolio, reinforcing the strategic value of neuromodulation as a platform rather than a standalone niche. At the same time, fresh regulatory approvals for tibial and integrated sacral neuromodulation devices indicate continued openness to new procedural options, particularly where they reduce complexity or expand patient access. The FDA approval milestones for vibegron in a BPH-adjacent population and for newer device architectures also suggest that label expansion and indication targeting are becoming central levers for growth.
Worldwide Hyperhidrosis Treatment Market
Market Structure Evolution
Three structural trends are shaping the competitive field. First, portfolio breadth is increasingly important, as companies that can offer both drug and procedural pathways, or multiple procedural modalities, are better positioned to serve varied patient needs and capture referrals across care settings. Second, differentiation through usability, integration, and clinical workflow is gaining importance alongside pure clinical performance. Third, focused innovators can still create value by solving specific adoption barriers, even in a market where larger players hold significant share. The overall direction is not toward a single dominant model, but toward a layered landscape in which pharmacological and device-based options coexist and compete on patient fit, reimbursement durability, and ease of implementation.
Worldwide Bladder Pump Market
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define where value is created and where risk accumulates.
Trend 1: Broader Use of Minimally Invasive Neuromodulation
Minimally invasive tibial and integrated sacral neuromodulation approaches are expected to play a larger role in treatment pathways, especially for patients seeking drug-free alternatives or those with insufficient response to medication. The commercial opportunity lies in simplifying adoption, aligning procedural economics with site-of-care realities, and demonstrating durable patient outcomes that support both clinical and payer acceptance. The key uncertainty is whether reimbursement and workflow advantages will be sufficient to drive broad, sustained uptake beyond early-adopter centers.
Trend 2: More Flexible Treatment Sequencing and Shared Decision-Making
Guideline shifts away from rigid step therapy toward shared decision-making are likely to persist, increasing the importance of patient-specific matching and clinician education. This creates opportunities for products that can be positioned as appropriate early options in selected patients, as well as for services that help providers navigate choice across drug and device pathways. The risk is that broader choice may also intensify comparison across therapies, making real-world evidence, tolerability, and total cost of care more central to purchase decisions.
PW Consulting Health Care Research Center
Trend 3: Portfolio Consolidation Paired with Targeted Innovation
The market is likely to continue seeing consolidation among larger device and pharmaceutical players seeking to assemble integrated portfolios, while smaller innovators pursue narrowly defined clinical or procedural problems. For investors and strategic planners, the important signal is that value will not be distributed uniformly. Companies that can combine differentiated technology with market access readiness, training support, and reimbursement strategy are more likely to convert innovation into durable share. The counterrisk is that promising technology may underperform commercially if adoption barriers, coverage gaps, or site-of-care economics are not addressed early.
Actionable Recommendations for Decision-Makers
Different stakeholders face distinct strategic priorities in this environment, but all benefit from a clear-eyed view of where adoption is likely to expand and where friction remains.
For Manufacturers and Product Developers
- Build differentiation around workflow and patient experience, not just mechanism of action. In device markets, procedural simplicity, programming burden, and follow-up requirements can influence adoption as much as clinical performance. In pharmacotherapy, tolerability, adherence support, and targeted label strategies can help defend position in competitive categories.
- Align market access and reimbursement planning with site-of-care realities. Reimbursement changes in ambulatory settings and variability across coverage environments can determine whether a technology scales quickly or remains limited to select centers. Early attention to coding, coverage, and site-of-care economics is essential.
- Invest in real-world evidence and clinician education that supports shared decision-making. As guidelines and practice patterns move toward more flexible treatment selection, providers will look for practical guidance on matching therapies to patient profiles and on comparing downstream outcomes and total cost of care.
For Investors and Strategy Teams
- Evaluate platforms as well as point products. Neuromodulation and drug-based care are both evolving toward broader pathway positioning. Companies that can span multiple patient segments or multiple modalities may have more resilient growth prospects than those dependent on a single indication or single procedural niche.
- Track regulatory and reimbursement catalysts as leading indicators of adoption speed. Recent approvals and reimbursement adjustments for procedural therapies demonstrate how quickly site of care and coverage changes can alter commercial potential. Monitoring these shifts can improve timing for diligence and partnership decisions.
- Differentiate between clinical promise and commercial readiness. Innovative devices and new oral therapies may address genuine unmet needs, but their trajectory will depend on reimbursement durability, training requirements, physician comfort, and competitive response. Due diligence should weigh adoption friction as closely as technology differentiation.
For Procurement and Payer Decision-Makers
- Assess total cost of care across options rather than focusing on unit price alone. For procedural interventions, consider training, follow-up, and site-of-care implications. For drug therapies, consider adherence, tolerability, and downstream utilization. A narrower price view can obscure the economic differences that matter most over the course of treatment.
- Prepare for more flexible treatment pathways. As guidelines and clinical practice move toward shared decision-making, evaluation frameworks should account for multiple appropriate treatment routes and the conditions under which each is likely to perform best.
- Monitor the interaction between coverage policy and technology adoption. Reimbursement changes can affect where care is delivered and which technologies become practical for broader use. Ongoing visibility into coding and coverage developments can improve planning for both access and budget forecasting.
Final Perspective
The overactive bladder treatment market is expanding at a steady pace, but the more important story is how value is being redistributed across therapies, platforms, and care settings. Revenue growth through 2032 will be supported by demographic demand and continued innovation, yet the companies and investors that benefit most will be those who can navigate reimbursement complexity, align products with practical workflow needs, and support more flexible, patient-centered treatment selection. Market concentration suggests that scale and portfolio breadth matter, but recent device approvals and targeted label expansions show that differentiated offerings can still create meaningful commercial traction.
For decision-makers seeking to act with confidence, the next step is to translate these directional signals into detailed, segment-level planning. Comprehensive segmentation data, regional comparisons, treatment-pathway dynamics, and company-specific positioning can sharpen strategic choices and reveal where to commit resources, where to partner, and where to watch for disruption. In a market where regulatory, reimbursement, and clinical-practice shifts can alter adoption trajectories quickly, deeper intelligence is not just helpful; it is a practical requirement for disciplined strategy.
For detailed analysis of this topic, please visit the official page: Overactive Bladder Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com