

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aircraft Hangar Doors Market: Why 6.2% CAGR & $2.74B Shift Reshape Airports

Strategic Trends and Commercial Opportunities in the Aircraft Hangar Doors Market
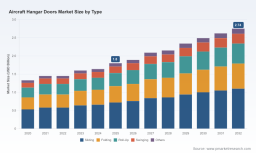
The aircraft hangar doors market has matured into a specialized infrastructure sector where engineering precision, regulatory compliance, and capital intensity converge. Valued at approximately 1.8 billion USD in 2025, the market has grown from 1.33 billion USD in 2020, reflecting a compound annual growth rate of 6.2 percent through the forecast period extending to 2032. At that horizon, revenue is projected to reach 2.74 billion USD. This trajectory is not merely a function of expanded aviation activity; it signals a structural shift in how hangar infrastructure is specified, manufactured, and integrated into broader airport and defense logistics ecosystems. For executives, investors, and procurement teams operating in aviation infrastructure, the market presents a clear opportunity space, but one that demands careful navigation of technical, regulatory, and supply chain complexities.
Market Snapshot and Core Challenges
The revenue trajectory outlined above reflects steady expansion rather than explosive growth, which is consistent with the capital-heavy, project-driven nature of hangar door installations. The market has moved from a post-pandemic recovery phase into a period of normalized demand, with civil aviation hubs driving the bulk of activity while military and private facilities contribute steady, specification-led procurement cycles. The overall picture points to an industry that is scaling incrementally, with growth increasingly tied to fleet modernization, facility upgrades, and the need for higher clearance envelopes as aircraft geometries evolve.
High Speed Doors Market
Several structural challenges define the current operating environment. First, the engineering envelope for hangar doors is being redefined by updated safety and construction standards. Recent revisions to NFPA 409 have raised the height limit for Group II hangars from 28 feet to 35 feet, creating a direct implication for door design, structural support, and clearance planning. This is not a marginal adjustment; it requires revised engineering approaches for facilities accommodating larger aircraft, and it pushes manufacturers and installers to adapt product lines, load calculations, and installation protocols.
Second, material inputs remain a persistent pressure point. Steel constitutes roughly 44.6 percent of hangar door material inputs, with hot-dip galvanizing and powder coating serving as the primary corrosion-resistant treatments for aviation environments. Supply chain disruptions for steel and aluminum components, which together comprise the majority of hangar door materials, continue to affect manufacturer margins and delivery schedules. In a market where custom engineering and installation of large-span doors demand specialized labor and long lead times for structural components, material volatility translates directly into project timeline risk and cost uncertainty.
Third, the market is characterized by meaningful concentration, with the top three players accounting for approximately 55 percent of revenue and the top five reaching roughly 72 percent. This concentration creates a dual dynamic. Incumbents benefit from established specifications, repeat contracts, and deep relationships with airport authorities and defense procurement channels. At the same time, it raises the barrier for new entrants who must demonstrate not only product capability but also compliance credibility, installation reliability, and the ability to meet specialized military and civil standards such as UFC 4-211-02, which specifies design requirements for steel sliding hangar doors in military facilities, including corrosion control and operational safety standards.
Key Demand Drivers
Technological Innovation and Engineering Differentiation
Technology differentiation in this market is less about digital novelty and more about mechanical reliability, clearance optimization, and corrosion management. Manufacturers are increasingly focused on door architectures that reduce operational friction, improve seal integrity, and accommodate larger aircraft footprints without compromising structural performance. Hydraulic and self-supporting systems with patented cam mechanisms have gained attention because they address the practical needs of facilities that require smooth, repeatable operations over large spans. Vertical lifting and sliding configurations are also being positioned as versatile options for aviation MRO environments and infrastructure projects where floor space, traffic flow, and maintenance access must be carefully managed.
Recent activity illustrates how companies are translating engineering capability into market visibility. Gandhi Automations showcased advanced vertical lifting and sliding aircraft hangar doors at MRO Americas 2026 in Orlando, following a similar presence at MRO Americas 2025 in Atlanta. These appearances are not merely promotional; they signal a strategic emphasis on MRO-adjacent infrastructure, where door performance directly affects turnaround efficiency, safety, and maintenance workflow. In parallel, AeroDoor International published analysis highlighting 35-foot height limits enabled by NFPA 409 updates, underscoring how manufacturers are using regulatory change as a platform to demonstrate readiness for larger aircraft clearances. This blend of engineering communication and event-based engagement reflects a market where technical credibility is a primary commercial asset.
Regulatory and Standards-Driven Specification Shifts
Regulatory and standards environments are shaping demand in ways that go beyond compliance. NFPA 409 updates and active military standards such as UFC 4-211-02 create specification anchors that influence procurement decisions long before a door is ordered. For civil airports, these standards interact with local building codes, airfield safety requirements, and operational clearance expectations. For military facilities, the emphasis on corrosion control, operational safety, and material durability means that specification cycles are often longer and more rigorous, but they also create sticky demand once a system is qualified.
PW Consulting
The practical implication is that regulatory change is becoming a demand catalyst rather than a static constraint. As height limits and clearance expectations rise, facilities planning expansions or replacements must revisit door selection earlier in the design process. This creates a window for manufacturers that can demonstrate compliant, scalable solutions and for procurement teams that align specification planning with anticipated regulatory trajectories. It also increases the importance of documentation, testing evidence, and installation track records, since specification decisions in this category are rarely made on price alone.
Demand-Side Shifts in Aviation Infrastructure Usage
Demand is being reshaped by how aviation facilities are used and upgraded. Civil airports continue to be the largest application segment, driven by terminal expansions, apron reorganizations, and the need to accommodate mixed fleets with varying aircraft sizes. Military airports contribute a substantial share of demand, often tied to facility modernization, readiness requirements, and the need for durable, standardized door systems that perform under demanding conditions. Private airports represent a smaller but strategically important segment, where customization, aesthetics, and operational flexibility often carry greater weight than in large-scale public facilities.
Beyond segment mix, the broader demand story is about operational intensity. Hangars are no longer treated as static storage spaces; they are increasingly integrated into maintenance, staging, and turnaround workflows. That shift raises the importance of door systems that support frequent operation, reliable sealing, and minimal downtime. It also reinforces interest in solutions that can be tailored to specific facility layouts, whether for airplane, floatplane, or helicopter hangars. In this environment, door selection is becoming part of a broader infrastructure strategy rather than a standalone purchase.
Supply Chain, Material Economics, and Project Execution
Supply chain and cost structure dynamics remain central to market behavior. Because steel and aluminum dominate material inputs, manufacturers are exposed to fluctuations in commodity availability, processing capacity, and treatment timelines for galvanizing and coating. These inputs are not easily substituted without affecting performance or certification expectations, which limits short-term flexibility. At the same time, custom engineering and installation require specialized labor, and long lead times for structural components can cascade into broader project delays.
This combination creates a market where execution capability is a competitive differentiator. Manufacturers that can stabilize supply arrangements, manage treatment workflows, and coordinate installation resources gain an advantage that extends beyond product design. For buyers, the lesson is that total project risk is shaped as much by lead times, labor availability, and treatment quality as by the door mechanism itself. In practice, this elevates the importance of supplier reliability, project planning discipline, and early alignment between specification, fabrication, and installation phases.
Fixed Drone Hangar Market
Competitive Landscape and Leading Strategies
The competitive environment is defined by a handful of established manufacturers with strong regional footprints, specialized product architectures, and deep installation capabilities. AeroDoor International operates as a manufacturer and installer of custom steel sliding aircraft hangar doors for military, commercial, and private aviation applications, with a profile that emphasizes tailored construction and broad application coverage. Diamond Doors focuses on custom bifold aircraft hangar doors for private, commercial, and aviation hangar buildings, positioning itself around configuration flexibility. Higher Power Doors manufactures self-supporting hydraulic aircraft hangar doors with a patented cam system, highlighting mechanical differentiation and operational reliability.
Schweiss Doors is a leading manufacturer of hydraulic aircraft hangar doors for airplane, floatplane, and helicopter hangars, with a clear focus on hydraulic systems and diversified aircraft types. Norco Manufacturing produces custom bi-parting, one-way, and 90-degree aircraft hangar doors for military, corporate, and large-scale aviation facilities, suggesting strength in specialized configurations and larger facility projects. Gandhi Automations manufactures premium vertical lifting and sliding aircraft hangar doors for global aviation MRO and infrastructure projects, indicating a strategic orientation toward international project work and MRO-linked demand. Champion Door Oy produces fabric fold-up aircraft hangar doors for military to jumbo jet applications, offering a distinct material approach that can suit specific operational and transport requirements. Vortex Doors provides specialized maintenance, repair, and installation services for aircraft hangar doors, including vertical lift and large-scale systems, which positions the company around service continuity and lifecycle support rather than manufacturing alone.
The strategic positioning across these players reveals several differentiation paths. One is product architecture: sliding, folding, roll-up, swinging, and specialized hydraulic or vertical lifting systems each address different facility constraints, clearance needs, and operational preferences. Another is application focus, with some firms leaning into military specifications and large-scale facilities, while others emphasize private aviation, floatplane and helicopter hangars, or MRO-related infrastructure. A third is service integration, where maintenance, repair, and installation capabilities become part of the commercial value proposition, especially for large-span systems where ongoing performance and downtime avoidance matter.
Market structure appears to be evolving along two overlapping trends. Consolidation pressure exists because scale, specification relationships, and installation networks create advantages that are difficult to replicate quickly. At the same time, differentiation remains viable for firms that can claim a clear technical niche, such as fabric-based fold-up systems, patented hydraulic mechanisms, or specialized vertical lifting solutions. New entry is possible but challenging, particularly where military standards, corrosion control expectations, and large-span installation expertise raise the bar for credibility. The more likely evolution is a mix of continued concentration among incumbents serving major civil and military programs, alongside targeted competition in specialized sub-segments and service-led growth for firms with strong installation and maintenance footprints.
Forward-Looking Trends and Commercial Implications
Expansion of Clearance Envelopes and Redesigned Door Systems
Over the next three to five years, one of the most consequential trends will be the continued adjustment of door systems to accommodate higher clearance requirements and larger aircraft footprints. The NFPA 409-driven shift toward 35-foot height limits for Group II hangars is a leading indicator of how standards can reshape product expectations. As facilities plan for mixed fleets, expanded aprons, and modernized maintenance layouts, door systems will need to balance span, structural support, and operational smoothness without sacrificing safety or durability.
The commercial opportunity here lies in early specification alignment and engineering readiness. Manufacturers that can document compliant designs, provide clear guidance on clearance planning, and demonstrate installation experience for larger envelopes will be better positioned to capture projects at the design stage. For procurement teams, the opportunity is to reduce rework and delay by integrating door selection into facility planning earlier, rather than treating it as a downstream procurement item. The risk is that standards interpretation, structural adaptation, and installation sequencing can become complex, especially where existing site conditions constrain redesign.
Service, Lifecycle Support, and MRO-Linked Demand
A second trend is the growing commercial relevance of service and lifecycle support. As hangar doors become more integrated into operational workflows, maintenance reliability, repair responsiveness, and installation quality gain importance. This is visible in the activity of firms that emphasize maintenance, repair, and installation services alongside product offerings, and in the broader MRO context where infrastructure performance affects turnaround efficiency. Vertical lifting and sliding systems, in particular, are being showcased in MRO-adjacent settings, suggesting that door performance is increasingly evaluated in relation to maintenance operations rather than static storage alone.
For manufacturers, this trend opens a path to differentiated value through service contracts, replacement component availability, and installation expertise that reduces operational risk. For investors and strategic buyers, it suggests that businesses with strong service networks and repeat maintenance relationships may command durable revenue characteristics, provided they can scale service delivery without compromising quality. The uncertainty lies in labor specialization and geographic coverage; service-led models depend on skilled crews and responsive logistics, which can be difficult to replicate across broad regions.
Material Strategy, Cost Management, and Regional Demand Shifts
A third trend is the continued emphasis on material strategy and cost management amid ongoing supply chain pressure for steel and aluminum components. With steel representing a significant share of material inputs and corrosion-resistant treatments playing a critical role in aviation applications, manufacturers will keep optimizing sourcing, treatment workflows, and inventory planning to protect margins and delivery reliability. At the same time, regional demand patterns will continue to shape project pipelines, with North America, Europe, and Asia Pacific representing substantial activity, while Latin America and the Middle East and Africa contribute more selective but growing opportunities tied to infrastructure investment and aviation expansion.
The commercial implication is that resilience in material planning and project execution will be a competitive advantage. Manufacturers that can manage treatment lead times, stabilize component supply, and communicate realistic delivery expectations will be better placed to protect margins and customer relationships. Buyers benefit from early engagement, clear specification alignment, and contracting structures that account for material and installation risk. The uncertainty is that commodity volatility and specialized labor constraints can still disrupt timelines, particularly for large, customized projects where structural components and treatment requirements extend lead times.
Actionable Guidance for Decision Makers
For manufacturers and product leaders, the priority is to strengthen engineering differentiation while ensuring that regulatory and standards readiness is visible and verifiable. That means investing in door architectures that address larger clearances, corrosion control, and operational reliability, and making compliance evidence, installation track records, and service capability easy to evaluate. Companies should also treat supply chain and treatment workflows as strategic assets, since margin protection and delivery reliability increasingly depend on how well material inputs and specialized labor are coordinated. Where possible, expanding service and lifecycle support can create a more resilient commercial model, especially for large-span and hydraulic systems where ongoing performance matters.
For investors and strategic acquirers, the market rewards businesses with specification relationships, installation credibility, and the ability to serve regulated or large-scale programs. Due diligence should look beyond unit economics to assess how well a company navigates military and civil standards, manages steel and aluminum supply exposure, and delivers customized engineering without excessive lead-time risk. Service-oriented capabilities and MRO-adjacent positioning may add durability to revenue streams, but only if supported by skilled labor and reliable project execution. Regional exposure is also worth evaluating carefully, since demand intensity and specification requirements vary meaningfully across civil, military, and private applications.
For procurement teams and airport or defense facility planners, the most effective approach is to move door specification earlier in the planning cycle and treat it as part of the broader infrastructure design rather than a final-fit purchase. Early alignment with manufacturers on clearance expectations, material treatments, and installation sequencing can reduce rework and delay, particularly as standards evolve and aircraft footprints expand. Contracting and project planning should account for specialized labor availability, structural component lead times, and corrosion-control requirements, since these factors often shape total project risk more than headline product cost. Where facilities anticipate frequent operation or integrated maintenance workflows, prioritizing systems with strong service and repair support can help protect operational continuity.
The aircraft hangar doors market is entering a phase where growth is increasingly tied to engineering adaptation, standards evolution, and execution reliability. For organizations operating in aviation infrastructure, the most valuable insights are those that connect regulatory change, material economics, and competitive positioning to specific project and investment decisions. Detailed segmentation data, regional demand breakdowns, company-level comparisons, and customized scenario analysis can sharpen those decisions further. To explore the full segmentation structure, regional dynamics, and forward estimates in greater depth, the complete PW Consulting market report provides the supporting detail and tailored frameworks needed for strategic planning.
For detailed analysis of this topic, please visit the official page: Aircraft Hangar Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com