

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Intravenous Solutions Market: Why 7.1% CAGR Redefines 2026-2032

Intravenous Solutions Market: Strategic Trends and Commercial Opportunities Through 2032
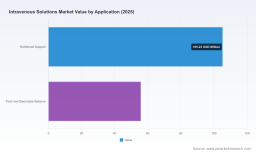
The intravenous solutions market has entered a phase of sustained expansion, driven by evolving clinical needs, regulatory interventions, and structural shifts in manufacturing and distribution. Valued at approximately 161 million USD in 2025, the market has demonstrated consistent growth from 2020 through 2025, and forward projections indicate a compound annual growth rate of 7.1 percent across the 2026 to 2032 forecast period. By the end of the decade, revenue trajectories point toward a market size exceeding 260 million USD. This growth is not merely a function of demographic expansion or incremental volume increases; it reflects deeper transformations in how intravenous therapies are formulated, delivered, reimbursed, and secured against supply chain volatility. For executives, investors, and procurement leaders, the market presents both operational complexities and strategic openings that demand forward-looking positioning.
Market Snapshot and Core Challenges
The revenue trajectory across the 2020 to 2025 historical window shows steady compounding, with growth accelerating in the latter years as clinical demand stabilized and supply constraints began to ease. The forecast period from 2026 to 2032 suggests a market that will continue to expand, though the pace and composition of growth will vary depending on regional adoption, product mix, and regulatory outcomes. While the market is broadly diversified across geographies and clinical applications, concentration remains a defining structural feature. The top three players account for roughly 48.6 percent of market share, and the top five collectively hold about 61.2 percent. This concentration signals an industry where scale, regulatory compliance, and manufacturing reliability confer meaningful advantages, yet it also leaves room for specialized entrants and regional players to capture niche demand.
Key Challenges and Inflection Points
Several structural challenges are reshaping how companies approach product development, capacity planning, and risk management. First, the industry continues to navigate the aftermath of supply disruptions that exposed fragilities in concentrated manufacturing footprints and single-source dependencies. Second, input cost pressures have persisted over the past two decades, with pharmaceutical ingredients and plastics used in solution production experiencing upward cost trends, further compounded by regulatory and quality maintenance requirements. These cost dynamics squeeze margins and force manufacturers to balance pricing strategies with volume commitments and long-term supply agreements. Third, reimbursement and billing frameworks create operational complexity, as intravenous administration sets and related components are billed under specific coding structures that influence hospital purchasing behavior and vendor contracting. Together, these factors point to an industry at an inflection point where resilience, regulatory agility, and cost discipline are becoming competitive differentiators.
Key Drivers Reshaping the Market
Technological Innovation and Formulation Advances
Innovation in intravenous solutions is moving beyond volume production toward formulation precision, material science improvements, and delivery compatibility. Manufacturers are increasingly focused on flexible container designs, non-PVC and non-DEHP alternatives, and multi-electrolyte formulations that better align with clinical requirements and patient safety considerations. These advances are not purely technical; they directly influence procurement decisions, as healthcare providers seek products that reduce compatibility risks, simplify storage and handling, and support broader therapeutic applications. The push toward smarter infusion compatibility and specialized formulations also creates opportunities for companies that can integrate product development with clinical workflow optimization, rather than competing solely on unit price.
Regulatory Environment and Policy Interventions
Regulatory actions have become a central force shaping market dynamics, particularly in response to supply shortages and quality concerns. Recent regulatory clearance resolved a nationwide shortage of sodium chloride 0.9 percent injection products, enabling removal of the product from the FDA Drug Shortages Database. This outcome was supported by a combination of temporary importation facilitation, expedited reviews to increase manufacturing capacity, and scientific assessments that extended shelf life for more than 50 intravenous and irrigation products. In parallel, temporary policies for compounding certain parenteral drug products were implemented to help fill gaps from manufacturing disruptions. These interventions demonstrate a regulatory environment willing to use flexibility and accelerated pathways to stabilize supply, but they also introduce uncertainty for manufacturers that must align production planning, expiry management, and compliance documentation with shifting policy windows.
Demand-Side Shifts in Clinical Care
Demand patterns are being reshaped by changes in hospital care models, outpatient transitions, and the growing use of nutritional support and fluid and electrolyte balance therapies across diverse patient populations. The increasing complexity of patient care, including longer stays for chronic conditions and greater reliance on parenteral nutrition in specialized settings, is expanding the addressable market beyond acute care volume alone. Providers are also prioritizing supply reliability and product consistency, which influences purchasing decisions and long-term contracting. As clinical protocols evolve and patient acuity profiles shift, demand is becoming more segmented, rewarding manufacturers that can tailor portfolios to specific care settings and therapeutic needs.
Supply Chain and Cost Structure Dynamics
The cost structure of intravenous solutions continues to be influenced by raw material trends, regulatory compliance costs, and logistics complexity. Pharmaceutical ingredients and plastics have experienced increasing costs over extended periods, and regulatory quality requirements add further operational expense. At the same time, reimbursement coding for administration sets creates a billing environment where procurement teams weigh total cost of ownership, compatibility, and supply continuity rather than focusing exclusively on per-unit pricing. These dynamics are encouraging manufacturers to invest in supply chain diversification, long-term supplier agreements, and production efficiency initiatives. For buyers, this environment underscores the importance of contractual flexibility and multi-source strategies to mitigate cost volatility and availability risk.
PW Consulting Health Care Research Center
Competitive Landscape and Leading Strategies
The market is anchored by a set of globally active manufacturers with distinct strategic positioning. Baxter International Inc., based in Deerfield, Illinois, remains a major producer of intravenous solutions, including sodium chloride 0.9 percent injection and multi-electrolyte formulations, with manufacturing capabilities across North America and international sites. Its scale and breadth of formulation options support a positioning centered on reliability, product range, and integration with broader hospital supply needs. Fresenius Kabi AG, headquartered in Bad Homburg vor der Höhe, Germany, provides a comprehensive IV fluids portfolio that includes freeflex bags, electrolyte solutions, and parenteral nutrition products. Its strategy emphasizes portfolio completeness and clinical alignment, appealing to procurement teams that value integrated product availability and consistent supply.
Intravenous Fluid Bags Market
B. Braun Melsungen AG, located in Melsungen, Germany, offers a broad portfolio of IV fluids, irrigation solutions, and smart infusion products with full supply availability. Its differentiation lies in combining fluid products with infusion technology and irrigation applications, creating cross-product value for clinical settings that seek operational efficiency across multiple use cases. ICU Medical, Inc., based in San Clemente, California, manufactures and distributes intravenous solutions in flexible containers, including non-PVC and non-DEHP alternatives, through a joint venture with Otsuka. This partnership structure gives ICU Medical access to specialized formulations and multi-site manufacturing flexibility, while allowing it to focus on material innovation and container design. Otsuka Pharmaceutical Co., Ltd., headquartered in Tokyo, Japan, supplies pediatric intravenous solutions and supports multi-site manufacturing for IV fluids under the same joint venture, bringing formulation expertise and a focus on specialized patient populations.
Strategic Positioning and Differentiation
Across these players, differentiation is increasingly defined by supply resilience, formulation specialization, and material science capabilities rather than price competition alone. Scale manufacturers leverage broad portfolios and international production footprints to support continuity of supply and large-volume contracts. Specialized and partnership-driven players compete on formulation alternatives, container technology, and targeted clinical segments such as pediatric care or non-PVC preferences. The strategic implication is clear: companies that can demonstrate both supply reliability and product-specific advantages are better positioned to secure long-term contracts and navigate regulatory or shortage-driven disruptions.
Market Evolution Trends
The competitive landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Concentration among leading players suggests that scale advantages will continue to matter, particularly in regulatory compliance, quality systems, and cost management. At the same time, the demand for specialized formulations and alternative materials creates openings for focused competitors and partnership models that can move faster in niche segments. New entrants may find opportunity not by matching the full breadth of incumbent portfolios, but by addressing specific pain points such as material safety, pediatric formulations, or regional supply gaps. Over time, the market is expected to remain concentrated at the top while becoming more differentiated in the middle and lower tiers, where agility and clinical alignment can compensate for smaller scale.
Future Trends and Commercial Opportunities
Supply Resilience as a Strategic Priority
Over the next three to five years, supply resilience is expected to move from an operational concern to a strategic differentiator. Regulatory actions have already demonstrated that shortage resolution can involve temporary importation, expedited reviews, expiry extensions, and compounding policy flexibility. Manufacturers that invest in diversified production capacity, multi-source ingredient procurement, and robust expiry and quality management will be better positioned to capture demand during periods of disruption. For commercial teams, resilience creates opportunities to strengthen contracts, build trust with procurement organizations, and command preference in procurement evaluations where continuity of supply is weighted heavily.
Formulation and Material Innovation Driving Segmentation
Innovation in formulations and container materials is likely to deepen market segmentation and create premium opportunities in specific clinical categories. Non-PVC and non-DEHP alternatives, multi-electrolyte solutions, and pediatric-focused formulations are examples of product areas where clinical preference and safety considerations can support differentiated positioning. Companies that align product development with evolving hospital protocols and patient safety priorities can build defensible niches, even in a market where overall growth is broad-based. The commercial opportunity lies in translating clinical advantages into procurement value, such as reduced handling complexity, improved compatibility, or lower risk of supply disruption for specialized therapies.
Reimbursement and Procurement Complexity Shaping Buying Behavior
Reimbursement and billing frameworks will continue to influence purchasing behavior, particularly where administration sets and solution components are billed under specific coding structures. This environment encourages buyers to evaluate total cost, compatibility, and supply reliability rather than focusing on isolated unit prices. For manufacturers and distributors, the implication is that value propositions must address procurement workflows, contracting flexibility, and integration with hospital cost management. Companies that can provide clear documentation, predictable availability, and compliant product structures will have an advantage in procurement negotiations, especially in settings where reimbursement constraints make cost predictability a priority.
Risks and Uncertainties
Despite the positive growth trajectory, several risks could alter market outcomes. Regulatory flexibility used to resolve shortages may shift as supply conditions improve, potentially changing the competitive dynamics that temporary policies created. Raw material cost pressures and quality maintenance requirements may continue to challenge margin stability, especially for manufacturers with limited pricing power or concentrated supplier exposure. In addition, reimbursement and coding frameworks can evolve in ways that affect purchasing patterns and product valuation. Finally, concentration in the market means that supply disruptions at a small number of major sites can have outsized effects, reinforcing the need for contingency planning and diversification. Companies that treat these risks as strategic variables rather than isolated operational issues will be better prepared to navigate uncertainty.
Actionable Recommendations for Decision Makers
For Manufacturers
Manufacturers should prioritize supply chain resilience and formulation differentiation as complementary growth levers. Diversifying production capacity and ingredient sourcing can reduce exposure to localized disruptions, while targeted innovation in materials and formulations can create preference in specific clinical segments. It is also important to align compliance and quality systems with the regulatory pathways that have recently been used to stabilize supply, including expiry management and compounding-related guidance, so that opportunities for shelf-life extension and policy-supported continuity can be captured efficiently. Pricing and contracting strategies should reflect total cost of ownership and supply reliability, not just per-unit economics, particularly when procurement teams weigh continuity and compatibility alongside price.
IV Bags Market
For Investors
Investors should focus on companies that demonstrate a credible combination of scale, regulatory agility, and product specialization. Market concentration suggests that incumbents with broad portfolios and international manufacturing footprints are well placed to benefit from demand growth and supply stabilization, but differentiation in materials, pediatric formulations, and flexible container technology can create valuable niches. When evaluating opportunities, it is important to assess exposure to raw material cost trends, reimbursement dynamics, and the ability to adapt to regulatory changes that affect expiry, importation, and compounding. Companies with clear contingency planning and diversified supply chains are likely to offer more durable value in an environment where disruption risk remains a central market factor.
For Procurement and Supply Chain Leaders
Procurement leaders should treat intravenous solution sourcing as a resilience and total-cost decision rather than a purely transactional purchase. Multi-source strategies, contractual flexibility around volume and expiry, and clear evaluation criteria for material safety and compatibility can reduce vulnerability to shortage-driven pricing and availability swings. It is also valuable to engage suppliers on continuity planning, quality documentation, and regulatory compliance, given the recent emphasis on expiry extensions and temporary importation pathways. By aligning procurement criteria with clinical priorities and supply risk management, organizations can improve both cost predictability and patient care continuity.
The intravenous solutions market is entering a period where growth, regulation, and supply resilience intersect in ways that reward strategic foresight. Companies and investors that understand the interplay between formulation innovation, regulatory dynamics, and procurement behavior will be better positioned to capture opportunity while managing risk. For decision makers seeking deeper segmentation data, regional nuance, and customized strategic guidance, the full research report provides detailed breakdowns and scenario-based analysis to support more precise planning.
For detailed analysis of this topic, please visit the official page: Intravenous Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com