

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Beryllium Copper Market 2026: The Real Drivers Behind 7.85% CAGR Growth

Strategic Trends and Commercial Opportunities in the Beryllium Copper Market
The beryllium copper market has evolved from a niche specialty alloys sector into a strategically critical component of global industrial and defense supply chains. With total market revenue reaching approximately 506.35 million in 2025 and a projected compound annual growth rate of 7.85 percent through 2032, the market trajectory reflects a convergence of technological demand, supply chain recalibration, and regulatory stability. This growth pattern is not merely a function of incremental expansion. It signals a structural shift where high-performance copper-beryllium alloys are increasingly positioned as enablers of miniaturization, reliability, and mission-critical performance across multiple industries.
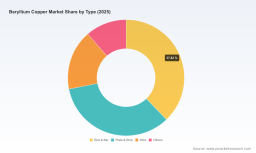
The market's historical progression from 347.02 million in 2020 to 506.35 million in 2025 demonstrates consistent upward momentum, with notable acceleration in recent years. The forecast period extending to 859.39 million by 2032 underscores sustained demand fundamentals. This expansion is distributed across multiple forms and applications, with rod and bar products, plate and strip configurations, wire, and other specialized formats each serving distinct manufacturing requirements. Application demand spans automotive systems, aerospace and defense platforms, electronics and connector markets, oil and gas equipment, industrial machinery, and additional niche segments. Regional dynamics further reflect a diversified footprint, with North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each contributing to demand patterns shaped by local industrial priorities and supply chain architectures.
Market concentration remains moderately fragmented, with the top three players holding approximately 38 percent share and the top five reaching 45 percent. This structure indicates that while established producers maintain strong positions, there is meaningful room for differentiated strategies, regional specialization, and technology-led competition. Understanding the current landscape requires looking beyond headline figures to the underlying forces reshaping how beryllium copper is sourced, engineered, and deployed.
PW Consulting
1. Market Context and Core Challenges
A Market at an Inflection Point
The beryllium copper market is navigating a period where growth momentum intersects with structural tensions. The consistent revenue expansion from 2020 through 2025 reflects durable demand, yet several challenges define the current operating environment and will influence how companies capture value over the next several years.
One of the most significant challenges lies in balancing performance expectations with processing complexity. Beryllium copper alloys deliver exceptional strength, conductivity, and fatigue resistance, but realizing these properties requires controlled fabrication, precise heat treatment, and specialized handling. For manufacturers, this creates a trade-off between material performance and production efficiency. The need for in-house processing capabilities, skilled technical support, and consistent quality control can constrain adoption in applications where lead time, cost sensitivity, or fabrication flexibility are paramount. This dynamic is particularly relevant as downstream industries increasingly seek pre-engineered solutions that reduce processing burden while preserving alloy performance.
A second challenge involves supply chain concentration and raw material visibility. Beryllium is a relatively scarce material with specialized sourcing pathways, and apparent consumption levels underscore the niche but essential nature of the supply base. The materiality of beryllium within the broader copper alloy ecosystem means that any disruption in ore supply, refining capacity, or logistics can reverberate through downstream product availability. At the same time, the strategic importance of beryllium copper in defense, aerospace, and high-reliability electronics has elevated supply assurance from a procurement concern to a resilience priority. This shift is reshaping how producers and end users think about inventory, vertical integration, and long-term supply commitments.
A third challenge emerges from the regulatory and compliance landscape. While beryllium copper benefits from a comparatively favorable regulatory status in major markets, the broader industrial environment is characterized by increasing scrutiny of materials, substances, and manufacturing practices. Companies must navigate differing regional frameworks, maintain documentation, and ensure that product claims align with evolving standards. The presence of regulatory certainty in some jurisdictions does not eliminate the operational burden of compliance management, especially for organizations operating across multiple markets or serving customers with strict material specifications.
These challenges do not undermine the market's growth outlook. Instead, they highlight where strategic differentiation is possible. Producers and suppliers that can reduce processing friction, strengthen supply assurance, and streamline compliance navigation are well positioned to capture share in a market where performance and reliability remain non-negotiable.
Worldwide Beryllium Copper Probe Tips Market
2. Key Demand Drivers and Structural Forces
Innovation in Alloys and Pre-Engineered Solutions
Technological innovation continues to be a primary driver of market evolution, particularly in the direction of alloys and product formats that simplify downstream manufacturing. The push toward pre-engineered strip alloys optimized for stamping and forming reflects a broader industry preference for reducing cycle time, minimizing in-house processing, and accelerating time to market. This trend is especially relevant for connector OEMs and precision component manufacturers, where form complexity, tolerance requirements, and production throughput directly affect competitiveness.
The introduction of product lines that bring engineered characteristics closer to the point of fabrication represents a meaningful shift in value creation. Rather than selling only standard alloy formats, producers are increasingly offering solutions that embed processing guidance, consistency, and performance predictability into the material itself. This approach addresses a practical pain point: customers want the mechanical and electrical advantages of beryllium copper without shouldering the full burden of secondary processing. As a result, innovation is not only about composition but also about how alloys are delivered, supported, and integrated into customer workflows.
In parallel, advances in casting, forging, and precision fabrication expand the range of applications that can leverage beryllium copper's properties. Components requiring high strength-to-weight ratios, corrosion resistance, and reliable contact performance benefit from these capabilities. The combination of alloy development and manufacturing refinement creates a feedback loop: improved material formats enable new design possibilities, which in turn stimulate demand in sectors where performance margins are tight.
Policy and Regulatory Environment as a Stabilizing Force
Policy and regulatory dynamics are shaping the market in ways that are more stabilizing than restrictive. Beryllium copper's classification as a critical material in certain jurisdictions reinforces its strategic significance and supports attention to supply continuity. At the same time, regulatory assessments in major markets have generally not recommended broad restrictions on beryllium in commercial alloys, helping preserve the material's role in electronics, industrial equipment, and other applications.
This regulatory context matters because it influences purchasing confidence. When manufacturers and procurement teams evaluate materials for long-lifecycle products, regulatory clarity reduces uncertainty. For beryllium copper, the combination of critical material recognition and the absence of restrictive recommendations in key regulatory reviews supports continued use in high-reliability applications. It also encourages producers to maintain documentation, compliance alignment, and transparent communication with customers who need to validate material suitability across different standards regimes.
Trade and tariff conditions further influence market accessibility. Favorable tariff treatment under normal trade relations for certain imports can reduce cost friction and support cross-border supply of beryllium copper products. While trade policy can shift, the current environment illustrates how regulatory and trade frameworks can either facilitate or constrain market flow. Producers with diversified manufacturing footprints and distribution networks are better equipped to adapt to changes in trade conditions while preserving supply reliability.
Demand-Side Shifts in Automotive, Electronics, Aerospace, and Industrial Sectors
Demand-side behavior is changing as end-use industries pursue higher performance in more compact and energy-efficient designs. In electronics and connector markets, the drive toward miniaturization, higher contact reliability, and durability under repeated cycling favors materials that combine strength with conductivity. Beryllium copper's properties align with these requirements, making it relevant for applications where failure is costly and performance consistency is essential.
In automotive and aerospace contexts, the emphasis on weight reduction, durability, and system reliability continues to support demand for advanced alloys. Components exposed to mechanical stress, thermal cycling, or demanding service conditions can benefit from beryllium copper's engineering characteristics. The defense and aerospace supply chain, in particular, places a premium on material assurance and long-term availability, which strengthens the role of established producers with vertically integrated or strategically managed beryllium sourcing.
Industrial machinery and oil and gas applications also contribute to demand, especially where wear resistance, corrosion performance, and operational reliability are priorities. These sectors often operate with long equipment lifecycles and strict procurement standards, meaning that material selection decisions are less about short-term cost and more about total cost of ownership and risk mitigation. As a result, demand in these segments tends to be stable and less sensitive to minor price fluctuations, provided that product quality and supply consistency are maintained.
A notable shift in demand-side behavior is the growing expectation for supplier partnership. Customers increasingly look for technical support, application guidance, and responsive service rather than treating suppliers as transactional sources of material. This expectation elevates the importance of companies that can combine product availability with engineering insight and consistent quality.
Supply Chain and Cost Structure Dynamics
Supply chain and cost dynamics remain central to market competitiveness. Beryllium copper's value proposition is tied to both material performance and the efficiency with which it can be produced, distributed, and processed. Cost structures are influenced by raw material availability, manufacturing complexity, and the scale of production runs. Because beryllium is a specialized input, supply chain resilience depends on reliable sourcing, controlled processing, and effective inventory management.
Investments in capacity and supply assurance reflect the strategic weight of these considerations. When defense and industrial priorities increase the need for replenished inventory and expanded capability, producers that can respond with targeted capacity investments gain a competitive edge. Such investments are not only about volume; they also signal reliability to customers who depend on continuous supply for mission-critical programs. This dynamic reinforces the importance of vertical integration, strategic procurement, and long-term planning in a market where shortages or delays can have outsized consequences.
At the same time, cost pressures in downstream manufacturing encourage innovation in product formats that reduce processing steps. Pre-engineered strip and rod products that simplify forming and stamping can lower total production cost for customers, even if the base material carries a premium relative to less specialized alternatives. In this sense, the cost conversation is increasingly about total system cost and productivity rather than material price alone.
3. Competitive Landscape and Leading Strategies
Established Leaders and Strategic Positioning
The competitive landscape features a mix of vertically integrated producers, specialty manufacturers, and distributors that serve distinct segments of the market. Leading companies differentiate themselves through combinations of material expertise, product breadth, regulatory alignment, and supply chain reliability. While share concentration is moderate, the market rewards companies that can combine technical capability with consistent delivery and application support.
Materion Corporation stands out for its vertically integrated beryllium supply from U.S. bertrandite ore and its broad portfolio of high-strength copper-beryllium alloys. Its product range includes well-known alloy families and specialty series used in aerospace, defense, connectors, and industrial applications. The company's recent capacity expansion supported by a major defense prime contractor underscores the strategic importance of supply assurance in high-priority programs. The launch of pre-engineered strip alloys for stamping and forming further illustrates a strategy centered on reducing customer processing burden and accelerating time to market. This dual emphasis on supply resilience and product engineering positions Materion as a comprehensive solutions provider rather than a commodity supplier.
Worldwide Copper-beryllium Alloys Market
NGK Metals Corporation, known for its Berylco-branded alloys, maintains a strong global presence with production capability in Japan, the United States, and Europe. Its focus on precision strip, rod, sheet, and ingot products serves electronics, telecommunications, and high-reliability industrial markets. ISO-certified operations and a commitment to regulatory compliance across multiple frameworks reinforce its positioning as a dependable supplier for customers who require consistent quality and documentation. The company's long-standing brand recognition in beryllium-copper alloys contributes to trust in applications where material provenance and specification compliance matter.
IBC Advanced Alloys Corp. concentrates on castings, forgings, and plates for the aerospace supply chain, precision connectors, and defense contractors. This focus on engineered forms and mission-relevant customers reflects a strategy aligned with high-specification demand. Belmont Metals Inc. operates as a specialty metals distributor with technical support across aerospace, electronics, and industrial sectors, emphasizing accessibility and application assistance for standard-format alloys.
European players such as Wieland-Werke AG and AMPCO METAL S.A. contribute regional depth and industrial application expertise. Wieland's role as a European producer and supplier of beryllium-copper alloys and semi-finished products supports industrial customers seeking regional supply and technical compatibility. AMPCO METAL's focus on high-performance industrial uses, combined with European manufacturing and distribution, adds another layer of regional capability. These companies illustrate how geographic presence and application specialization can support competitive differentiation even in a globally connected market.
Japanese manufacturer Mitsubishi Materials Corporation and U.S.-based specialty suppliers such as Aviva Metals Inc., CDA Metals, and Smiths Metal Centres Limited further broaden the competitive field. Mitsubishi Materials serves electronics, telecommunications, and industrial applications, while the distributor and fabricator segment provides accessibility, standard formats, and technical support to downstream customers. Together, these players show that the market is served not only by large integrated producers but also by specialized distributors and fabricators that enable adoption through service, flexibility, and regional proximity.
Market Evolution: Integration, Differentiation, and Entry Points
The competitive landscape is evolving along several lines. Vertical integration remains a powerful advantage where beryllium sourcing and alloy production are closely linked, particularly for customers in defense and aerospace who value supply continuity. At the same time, product-level differentiation is becoming increasingly important. Companies that offer pre-engineered formats, application-specific guidance, and reduced processing complexity are creating value beyond traditional alloy supply.
The market also shows signs of regional specialization. Producers with manufacturing and distribution footprints in multiple regions can better serve local customer requirements, adapt to trade conditions, and provide responsive technical support. This regional dimension matters as customers increasingly weigh supply resilience alongside material performance.
New entry or expansion is challenging but not impossible, especially for companies that can bring a clear differentiator. The barrier is not only technical; it is also commercial. Success often depends on building trust with high-specification customers, maintaining compliance documentation, and offering the combination of product consistency and service that downstream manufacturers expect. As a result, the market is likely to see continued emphasis on strengthening existing positions, deepening application relationships, and expanding capabilities in high-priority segments rather than broad-based commoditization.
4. Forward Outlook: Trends and Commercial Implications
Trend 1: Rising Demand for Pre-Engineered and Processing-Optimized Alloys
Over the next three to five years, demand is expected to increasingly favor alloys and product formats that reduce downstream processing effort. Connector manufacturers, electronics producers, and precision component makers are likely to seek materials that combine performance with ease of fabrication. This trend creates opportunities for suppliers that can deliver engineered strip, rod, and sheet products with consistent characteristics and clear processing support. Commercially, it shifts competition toward value-added solutions rather than base material pricing alone.
For businesses, the implication is clear: the ability to shorten production cycles, reduce scrap, and simplify fabrication will become a stronger purchasing criterion. Companies that invest in product formats aligned with these priorities can capture preference in segments where time to market and manufacturing efficiency are critical.
Trend 2: Supply Assurance as a Strategic Procurement Priority
Supply assurance is likely to remain a defining theme, particularly in defense, aerospace, and high-reliability industrial applications. As customers place greater weight on continuity of supply and inventory resilience, producers with integrated sourcing, expanded capacity, and long-term commitments will be better positioned to win and retain strategic contracts. Investments tied to replenishment and capability expansion reflect this priority and are likely to influence purchasing decisions.
The commercial opportunity lies in building supply relationships that go beyond transactional procurement. Customers may be willing to align with suppliers that can demonstrate reliability, transparency, and the ability to scale with program needs. In this environment, supply chain credibility becomes a competitive asset.
Trend 3: Regulatory Clarity Supporting Continued Adoption in Key Applications
The regulatory environment is expected to continue supporting beryllium copper's role in major applications, provided that compliance documentation and material stewardship remain robust. Regulatory assessments that do not recommend broad restrictions, combined with critical material recognition in some jurisdictions, create a favorable backdrop for sustained adoption. This does not eliminate the need for compliance management, but it reduces the risk of disruptive restrictions that could otherwise reshape material selection.
For commercial strategy, the implication is to maintain strong documentation practices, stay aligned with regional requirements, and communicate compliance status clearly to customers. In sectors where material qualification cycles are long, regulatory consistency can be a meaningful advantage.
Risks and Uncertainties
Despite positive fundamentals, several uncertainties warrant attention. Raw material availability and pricing can affect cost structures and supply confidence, especially if consumption patterns shift or sourcing challenges arise. Trade policy changes could alter tariff conditions and cross-border supply dynamics, influencing competitiveness in specific regions. In addition, downstream demand can be sensitive to broader industrial cycles, particularly in sectors such as electronics and industrial machinery where investment timing and production volumes fluctuate.
Another source of uncertainty is the pace of product format adoption. While pre-engineered and processing-optimized solutions offer clear benefits, adoption depends on customer readiness, existing fabrication capabilities, and the cost calculus of changing supply chains. Companies should monitor where adoption accelerates and where traditional formats remain preferred, as this will shape demand patterns across product types.
5. Strategic Considerations for Decision Makers
For Manufacturers and Fabricators
Manufacturers should evaluate how beryllium copper product formats align with production efficiency and application requirements. Where possible, explore pre-engineered strip, rod, and plate solutions that reduce in-house processing and shorten lead times. Building closer technical collaboration with suppliers can improve yield, consistency, and time to market, especially for complex stampings, precision connectors, and high-reliability components. It is also advisable to review supply contingency planning, particularly for programs where material availability directly affects delivery commitments.
For Investors and Strategic Planners
Investment decisions should account for the market's combination of steady growth, specialized supply dynamics, and increasing value placed on supply assurance. Capacity expansion tied to defense and high-reliability demand, along with product engineering that reduces processing burden, points to areas where competitive advantage can be strengthened. When assessing opportunities, consider not only volume growth but also the concentration of demand in high-value applications, the importance of regional supply footprints, and the role of compliance and documentation in customer selection. Diversification of supply and manufacturing presence can mitigate exposure to regional or trade-related disruptions.
For Procurement and Supply Chain Leaders
Procurement teams should prioritize suppliers that offer a balance of material performance, reliability, and technical support. In high-specification applications, qualification lead time, documentation quality, and supply continuity can be as important as unit price. Establishing multi-source strategies where feasible, maintaining visibility into inventory and capacity commitments, and aligning material choices with long-term regulatory and compliance expectations can reduce risk. For programs with extended lifecycles, early coordination with suppliers on specification, availability, and processing requirements can prevent downstream delays.
Closing Perspective
The beryllium copper market is advancing through a combination of steady demand growth, product-level innovation, and heightened attention to supply resilience and regulatory alignment. The trajectory from 2020 to 2032 reflects more than incremental expansion; it points to a market where performance, reliability, and processing efficiency increasingly determine competitive success. For organizations operating in or adjacent to this market, the strategic imperative is to look beyond base material characteristics and evaluate how alloys are engineered, supplied, and supported across the value chain.
As demand becomes more application-specific and supply assurance gains strategic weight, detailed segmentation data, regional demand patterns, and company-level capability assessments become essential for precise planning. For decision makers seeking a deeper operational view, including granular segmentation, competitive benchmarking, and customized scenario analysis, the full PW Consulting market research report provides expanded data and tailored guidance to support more targeted strategy development.
For detailed analysis of this topic, please visit the official page: Beryllium Copper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com