

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Polyimide Tubing Market: Why 8.1% CAGR and Medical Demand Redefine Growth By 2032
By pmarketresearch, 2026-09-21
Navigating the Polyimide Tubing Market: Strategic Trends and Commercial Opportunities
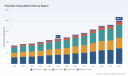
The polyimide tubing market has entered a phase of sustained expansion, driven by an increasingly demanding set of performance requirements across high-stakes industries. From 2020 through 2025, the market moved from a relatively modest base into a consistent double-digit growth trajectory, with the most recent annual figures signaling that demand is no longer cyclical but structurally reinforced. Looking ahead to the end of the decade, the expansion is expected to accelerate further, with a compound annual growth rate that places polyimide tubing among the more compelling specialty materials segments in advanced manufacturing and life sciences. The revenue scale now sits well into the triple-digit range, and the forward projection suggests the market will more than double its current size within the coming forecast window.
This trajectory is not merely a function of volume growth. It reflects a deeper shift in how engineers and procurement leaders think about tubing materials. Polyimide has transitioned from a niche solution for extreme thermal or chemical environments into a default consideration for applications where reliability, miniaturization, and regulatory compliance intersect. That shift has rewritten the competitive rules, forcing suppliers to compete on more than price or basic availability. The market is now rewarding precision, material innovation, and the ability to navigate an increasingly complex compliance landscape.
Market Current State and Core Challenges
The current market environment is defined by strong demand momentum, but that momentum is colliding with operational and structural constraints that will shape who wins in the next cycle. The first challenge is the widening gap between specification requirements and manufacturing capability. As applications move toward smaller diameters, tighter tolerances, and more complex reinforcement architectures, the bar for process control has risen sharply. Not every producer can consistently deliver the wall uniformity, surface finish, and mechanical predictability that advanced medical, electronics, and aerospace programs now demand. This has effectively raised the barrier to entry and concentrated value creation among suppliers with mature process engineering and robust quality systems.
A second challenge lies in cost volatility and input pressure. Polyimide is a performance material, and its production economics are sensitive to precursor availability, energy costs, and processing intensity. Recent producer price trends have shown upward pressure on input costs, which can compress margins for suppliers that lack pricing power or differentiated value propositions. In a market where many end-users are accustomed to treating tubing as a commoditized component, the ability to justify premium pricing increasingly depends on proving measurable performance gains rather than simply pointing to material grade.
The third challenge is regulatory and documentation intensity. As polyimide tubing penetrates more regulated end-use sectors, compliance has become a commercial prerequisite rather than a back-office function. Suppliers must demonstrate material traceability, biocompatibility support where relevant, and alignment with evolving regional requirements. This is especially true in European markets and in medical-adjacent applications, where the cost of noncompliance can be far greater than the cost of qualifying new materials. Companies that treat compliance as a strategic capability rather than a checkbox are gaining a structural advantage in customer evaluations.
Key Drivers Shaping Market Direction
Innovation in Material Performance and Processing Precision
Material innovation remains one of the most powerful demand catalysts. The latest wave of product development is not just about incremental refinement; it is about rethinking the performance envelope of polyimide tubing in ways that directly enable new applications. Recent announcements from leading suppliers point to formulations that significantly increase tensile and column strength compared with traditional grades, addressing long-standing tradeoffs between flexibility, pushability, and mechanical reliability. In parallel, tailored surface and lubrication variants are reducing friction and improving handling characteristics, which is especially valuable in interventional and micro-catheter applications where operator control and device navigation are critical.
These advances matter commercially because they expand the addressable use space. When tubing can withstand higher loads, maintain dimensional stability under stress, or offer more predictable lubricity, designers can adopt polyimide in configurations that were previously impractical. That creates a virtuous cycle: stronger performance justification supports broader specification, which increases volume, which in turn funds further process improvement. For suppliers, the strategic implication is clear. The winners will be those who connect material science improvements to measurable application outcomes rather than competing solely on catalog breadth.
Regulatory Alignment as a Commercial Accelerator
Regulatory and compliance dynamics have evolved from a constraint into a competitive differentiator. In the medical and certain industrial segments, buyers increasingly evaluate suppliers based on their ability to deliver materials aligned with REACH and EU MDR expectations, alongside robust documentation and traceability. This has shifted the procurement conversation. Technical compliance is now part of commercial credibility, and suppliers that can demonstrate a consistent compliance posture are often shortlisted more quickly than those that require extensive qualification support.
The market is also seeing a degree of positioning around this theme. Some suppliers have emphasized that their polyimide tubing portfolios are designed with these regulatory expectations in mind, signaling that compliance capability is being used as a trust signal in sensitive applications. Others have claimed distinctive compliance status within their product lines. Regardless of the specifics of any single claim, the broader pattern is that regulatory readiness is becoming a meaningful filter in customer selection, particularly for programs with long qualification cycles and high switching costs. For manufacturers, this means that compliance infrastructure, documentation practices, and material transparency are now part of the core commercialization strategy.
Demand-Side Shifts Toward Miniaturization and High-Reliability Systems
On the demand side, the most persistent driver is the continuing push toward smaller, more precise, and more reliable systems. In medical device development, the trend toward minimally invasive and endovascular procedures has increased the need for tubing that can navigate complex anatomy while maintaining delivery precision. In electronics and advanced assembly contexts, miniaturization and heat management requirements have elevated the value of materials that combine dimensional stability with thermal resilience. Aerospace and automotive applications, meanwhile, continue to prioritize weight reduction and durability in high-stress subsystems.
Polyimide Foam Market
What ties these demand shifts together is an expectation of consistency. As systems become more integrated and tolerances tighter, tubing is no longer evaluated in isolation. It is judged as part of a system-level reliability equation. This has made end-users more selective and more willing to engage with suppliers that can support application-specific engineering, co-development, and longer-term supply assurance. For suppliers, the commercial opportunity lies in moving up the value chain: from selling standard tubing to participating earlier in design cycles, where specification decisions are still fluid and switching costs are lower.
Supply Chain Dispersion and Cost Structure Evolution
Supply chain and cost dynamics are reshaping how value is captured across the market. Polyimide tubing production depends on specialized manufacturing know-how, controlled process environments, and increasingly on reliable access to qualified input streams. As input cost pressures have risen, the ability to manage cost structure without eroding performance has become a defining capability. Suppliers that can maintain quality at scale, optimize yield, and manage working capital effectively are better positioned to absorb cost variability and protect customer relationships.
At the same time, supply chain considerations are influencing sourcing behavior. Buyers in regulated and high-reliability applications often prioritize continuity and auditability over marginal price differences. This has strengthened the position of established manufacturers with documented processes and predictable capacity. It has also created incentives for strategic collaboration, where tubing suppliers work more closely with medical device manufacturers, electronics assemblers, and system integrators to align specifications, reduce rework, and stabilize delivery. The emerging pattern is a market in which cost competitiveness is increasingly tied to process discipline and customer integration rather than to simple scale arbitrage.
Competitive Landscape and Leading Strategies
The competitive field is concentrated enough that a relatively small set of established players accounts for a substantial share of revenue, yet diverse enough that specialization remains a viable path. Market concentration suggests that scale, reputation, and compliance capability matter, but it does not eliminate room for differentiated mid-tier suppliers that can serve demanding niches with high precision and responsive engineering support. The key strategic question is not simply who is largest, but who can most reliably convert technical capability into commercial trust.
Several manufacturers illustrate the strategic paths currently shaping the market. Some are leaning into ultra-precision medical tubing, building reputations around tight tolerances and application-specific customization for catheter and interventional use. Others emphasize reinforcement architectures and high-lubricity variants, targeting performance requirements that standard geometries cannot easily meet. A further group positions itself around industrial and medical versatility, offering broad ranges of dimensional control and heat-resistant performance for customers that need flexible specification options. Across these approaches, the common thread is a move away from generic supply toward solution-oriented engagement.
Recent product activity supports this interpretation. One prominent supplier expanded its material portfolio with a polyimide formulation engineered to deliver substantially higher tensile and column strength than traditional options, a move that directly targets applications where mechanical integrity and handling control are paramount. Shortly afterward, the same company broadened its product line to enable more tailored performance in PTFE and polyimide tubing configurations. These launches are not isolated innovations; they reflect a deliberate strategy of raising the performance floor and increasing configurational flexibility so that the supplier can address a wider range of demanding applications without diluting its technical positioning.
The competitive landscape appears to be evolving along two tracks. On one track, larger or more established players are consolidating their advantage through compliance readiness, process maturity, and broad application coverage. On the other, specialized entrants and focused product line extensions are carving out defensible positions by solving specific performance problems or serving highly specialized procedural needs. Full-scale horizontal consolidation is not inevitable in the near term, but selective consolidation in high-growth segments is likely as buyers prefer fewer, more capable partners. New entrants will need either a genuine process advantage, a compliance edge, or a clearly defined application niche to break through.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interlinked trends.
- Performance-driven specification will deepen. As new formulations and reinforced variants mature, polyimide tubing will be selected for more applications on the basis of measurable mechanical and handling benefits rather than thermal resistance alone. This will increase the importance of application-level validation and supplier-supported testing in winning new business.
- Compliance and qualification readiness will become table stakes in regulated segments. Buyers will continue to favor suppliers that can bring documentation, material transparency, and regulatory alignment into the conversation early. Suppliers that still treat these as after-the-fact requirements will face longer sales cycles and higher disqualification risk.
- Application-adjacent integration will grow in value. The commercial battleground will increasingly be at the design interface, where tubing suppliers are expected to contribute to configuration choices, tolerance planning, and reliability trade-offs. Companies that can engage earlier and reduce downstream iteration will capture more wallet share and more durable relationships.
These trends translate into concrete opportunities. Manufacturers that invest in differentiated material grades, precision processing, and documented compliance will be better placed to command value and reduce price sensitivity. Investors and strategic partners should look for suppliers with a clear link between product innovation and end-use adoption, especially where new formulations enable previously constrained procedures or device concepts. Procurement and engineering leaders should treat supplier selection as a long-term risk management decision, weighting validation support, documentation quality, and application engineering capability alongside unit economics.
PW Consulting Chemical & Energy Research Center
The primary uncertainties to monitor are cost trajectory, regulatory evolution, and the pace at which new performance claims translate into qualified adoption. Input cost pressure could narrow margins for suppliers that cannot pass through value or optimize cost structure. Regulatory expectations may continue to tighten or shift across regions, altering the compliance burden and the speed of qualification. Finally, not every technical enhancement will convert into commercial uptake; some advances will require lengthy validation or may prove over-specified for certain use cases. Market participants should track these variables as leading indicators of where share and margin will migrate.
Strategic Recommendations for Decision-Makers
Manufacturers and suppliers should prioritize the conversion of technical capability into reliable commercial outcomes. That means investing in process control that supports tight tolerances at scale, documenting compliance and material traceability in ways that simplify customer qualification, and designing product portfolios around real application pain points rather than catalog breadth alone. Where possible, moving earlier into the design process and offering co-development support can reduce the risk of late-stage redesign and strengthen customer lock-in without resorting to price competition.
Investors and corporate strategists should assess market opportunities through the lens of defensibility. The most attractive positions are likely to be those where a supplier can demonstrate a repeatable advantage in performance, compliance readiness, or application specialization. Volume growth is important, but durability of demand depends on whether the supplier is solving a hard problem that customers are willing to pay for and cannot easily replicate elsewhere. Track record in regulated environments, the ability to sustain process improvement, and evidence of growing specification share are all signals worth weighting heavily.
Procurement and engineering buyers should treat polyimide tubing sourcing as a strategic decision with long consequences. Evaluate suppliers on more than nominal material grade or lead-time promises. Ask how they handle tolerance control, how they support qualification and documentation, how they manage cost volatility, and whether they can engage constructively in application development. In high-reliability or regulated programs, the cheapest option today can become the most expensive option tomorrow if it introduces qualification delays, variability, or compliance gaps.
Worldwide Polyimide Engineering Plastics Market
For organizations that need a deeper, segment-specific view of where growth is concentrating, which application roads are widening fastest, and how supplier positioning is evolving at the subsegment level, a more detailed research synthesis can help translate these trends into targeted plans. The broader market signals are clear, but the actionable details often depend on how each segment is moving and which performance or compliance capabilities matter most in a given context.
For detailed analysis of this topic, please visit the official page: Polyimide Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Molybdenum Powder Market: Why 5.8% CAGR and 3D Printing Reshape Growth to 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Molybdenum Powder Market (2025–2032)
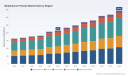
The global molybdenum powder market has entered a phase of structural expansion, driven by a convergence of industrial demand, technological adoption, and shifting supply chain dynamics. From a base valuation of approximately 163.15 million USD in 2020, the market has grown steadily to reach 215.0 million USD in 2025, reflecting a compound annual growth rate of 5.8 percent across the 2026 to 2032 forecast horizon. This trajectory signals more than a cyclical upturn; it points to a recalibration of how specialized metal powders are sourced, processed, and deployed across advanced manufacturing sectors. Understanding the underlying drivers, competitive positioning, and regulatory inflections is essential for executives and investors navigating this evolving landscape.
Market Overview and Contemporary Challenges
The market's expansion over the past five years has been characterized by steady revenue growth, with annual figures climbing from 168.81 million USD in 2021 to 207.98 million USD in 2024, before stabilizing at 215.0 million USD in 2025. Looking ahead, the forecast period projects consistent upward momentum, reaching 233.48 million USD in 2026 and scaling to 344.8 million USD by 2032. This growth is not uniform across all segments, nor is it insulated from macroeconomic and geopolitical friction. Several structural challenges and inflection points are reshaping how stakeholders approach procurement, production, and capacity planning.
- Regulatory volatility and supply chain realignment. Export controls and trade policy shifts have introduced pronounced uncertainty into cross-border flows of molybdenum powder. The imposition of restrictions in early 2025 prompted importers in North America and Europe to accelerate diversification strategies, while a temporary suspension of those controls extended through late 2026 created a window of adjustment rather than a permanent resolution. This regulatory back-and-forth has forced buyers to weigh short-term availability against long-term sourcing resilience.
- Raw material price transmission and margin pressure. Cost dynamics in the upstream concentrate market flow directly into powder pricing, with price increases of approximately 8 to 10 yuan per kilogram observed for every 100 yuan per ton-unit rise in molybdenum concentrate costs. This sensitivity compresses margins for producers who lack vertical integration or long-term feedstock agreements, while simultaneously testing the price tolerance of downstream manufacturers who rely on predictable input costs.
- Segment divergence and capability gaps. Demand is not growing evenly across product types or applications. Regular molybdenum powder continues to anchor the market, but spherical variants and other specialized grades are gaining traction in high-value use cases. Similarly, traditional powder metallurgy applications remain the dominant demand center, while additive manufacturing and other emerging applications are expanding at a faster pace from a smaller base. Companies that cannot bridge the gap between commodity-grade production and precision-grade specifications risk losing share to more technologically agile competitors.
Market concentration remains relatively moderate, with the top three players holding roughly 24.6 percent of total revenue and the top five capturing approximately 26.2 percent. This fragmentation suggests room for consolidation, but it also indicates that no single entity commands disproportionate pricing power. The competitive arena is therefore shaped less by market dominance and more by differentiation in purity, particle morphology, integration depth, and regional supply reliability.
Key Drivers Shaping Market Trajectory
Several interconnected forces are propelling the market forward, each reinforcing the others in ways that create both opportunities and structural shifts.
Technological Innovation and Material Performance Requirements
Advancements in powder production and application engineering are redefining what buyers expect from molybdenum powder. Spherical molybdenum powder, produced through controlled hydrogen reduction and precision milling, offers improved flowability, packing density, and consistency for additive manufacturing and high-performance coating processes. Grain size control in the 0.8 to 6.0 micrometer range, coupled with purity levels reaching 3N and beyond, enables manufacturers to meet tighter tolerances for aerospace components, semiconductor tooling, and high-temperature alloy applications. These technical capabilities are not merely incremental improvements; they open doors to applications where conventional irregular powders fall short, particularly in laser-based powder bed fusion and precision sintering workflows.
The broader trend toward miniaturization, weight reduction, and thermal management in advanced industrial equipment further amplifies the value of high-performance molybdenum powders. As engineers design components that must endure extreme temperatures, corrosive environments, or repeated thermal cycling, the material's intrinsic properties become a critical enabler rather than a substituteable input. This shift elevates the importance of supplier technical support, custom grading, and application-specific formulation capabilities.
Policy, Regulation, and Trade Dynamics
Policy interventions have become a defining factor in market behavior. Export controls introduced in early 2025 on molybdenum-related items, including powder, disrupted established trade routes and prompted procurement teams in the United States and other importing regions to identify alternative sources. The subsequent suspension of the one-year implementation window, effective through November 2026, provided temporary relief but did not eliminate the underlying strategic reorientation. Import volumes in the United States rose by 18 percent in 2025, reflecting both stronger apparent consumption and a deliberate effort to secure supply outside restricted channels.
This regulatory environment encourages a dual-track sourcing strategy: maintaining relationships with established suppliers while building redundancy through regional partnerships, inventory buffering, and qualification of alternative grades. For producers, the landscape rewards transparency, traceability, and the ability to demonstrate compliance with evolving export and import requirements. Companies that can navigate regulatory complexity without compromising delivery reliability are positioned to capture premium contracts and longer-term agreements.
Demand-Side Shifts in Manufacturing and Advanced Applications
End-user behavior is evolving as industries adopt more intensive material specifications and higher-value processing methods. Traditional powder metallurgy remains the largest application domain, supported by steady demand from components used in automotive, industrial machinery, and structural hardware. However, the growth narrative is increasingly shaped by additive manufacturing, where molybdenum powders are evaluated for their suitability in complex geometries, thermal stability, and post-processing performance. Research and commercial quantities of molybdenum powder are also being consumed by semiconductor manufacturing and high-temperature application sectors, where purity and consistency directly influence yield and reliability.
This demand-side evolution pushes suppliers to think beyond volume pricing and toward value-added services. Technical consultation, sample programs, grade customization, and joint development with end-users are becoming differentiators. Buyers are increasingly willing to pay for predictability and performance assurance, especially when production downtime or component failure carries significant cost.
Ferrochrome Powder Market
Supply Chain and Cost Structure Realignment
The link between upstream concentrate pricing and downstream powder costs creates a continuous pressure point that shapes procurement timing, inventory strategy, and contract structuring. When concentrate prices rise, powder prices follow with measurable lag and sensitivity, forcing producers to manage feedstock exposure carefully. Vertically integrated operations that control reduction capabilities and raw material inputs gain a structural advantage in margin stability, while non-integrated suppliers must rely on hedging, long-term agreements, or strategic stockpiling to mitigate volatility.
At the same time, global production volumes have expanded, with total molybdenum production reaching 672.6 million pounds in 2025, a 4 percent increase from the prior year, while usage rose 3 percent to 671.8 million pounds. This near-balance between production and consumption indicates a market that is tightening at the margin, where small disruptions or demand spikes can translate into price movement and allocation challenges. Supply chain resilience is therefore not just a regulatory response but a commercial necessity.
Competitive Landscape and Leading Strategies
The competitive environment features a mix of integrated producers, specialty suppliers, and research-oriented distributors, each pursuing distinct strategic positioning.
- Elmet Technologies operates through fully integrated powder reduction capabilities in the United States, serving alloys, stainless steel, and superalloy applications. This integration supports consistent feedstock control and tailored output for industrial alloy markets, positioning the company as a reliability-focused supplier for demanding metallurgical applications.
- Sumitomo Electric Industries manufactures 3N-purity molybdenum powder with grain sizes ranging from 0.8 to 6.0 micrometers via hydrogen reduction of high-quality raw material. The emphasis on controlled grain size and purity aligns with customers requiring repeatable performance for specialized processing, particularly where particle morphology influences flow and sintering behavior.
- American Elements supplies both commercial and research quantities of molybdenum powder and related metal powders, catering to a broad customer base that spans production-scale buyers and laboratory-scale developers. This dual-channel approach enables the company to capture early-stage demand signals and transition research-grade interest into commercial supply relationships.
- Goodfellow Corporation provides high-purity molybdenum powder up to 5N for semiconductor manufacturing, aerospace, and high-temperature applications. The focus on ultra-high purity and application-specific support targets segments where contamination control and material consistency are non-negotiable, allowing the company to compete on performance rather than volume.
- Stanford Advanced Materials supplies molybdenum metal powder for fabricated metal processing and industrial applications, emphasizing accessibility and broad industrial coverage. This positioning supports customers who need dependable supply for standard processing workflows and volume-oriented procurement.
- G K Min Met Alloys Co manufactures pure molybdenum powder as a core product for industrial use, anchoring its offering in purity and industrial applicability. The company's focus on pure-grade powder serves buyers seeking a straightforward, performance-reliable input for conventional powder metallurgy and related processes.
These players illustrate a market where differentiation is achieved through purity tiers, particle engineering, integration depth, and application specialization rather than sheer scale. The moderate concentration levels suggest that consolidation is possible, particularly as buyers seek fewer, more reliable supply partners amid regulatory and cost volatility. At the same time, new entrants with capabilities in spherical powder production, advanced hydrogen reduction, or niche high-purity segments can carve out positions by addressing unmet specifications. The trend is therefore one of selective convergence: larger, integrated players may absorb specialized capabilities, while focused suppliers compete on technical precision and customer proximity.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, several trends are likely to shape the market's evolution and create distinct commercial opportunities.
Worldwide Ammonium Molybdate Market
- Additive manufacturing and high-purity specialization will accelerate premium segment growth. As 3D printing and advanced coating processes mature, demand for spherical and high-purity molybdenum powders is expected to outpace the broader market average. Suppliers that can guarantee tight grain size distributions, low contamination, and reproducible batch performance will capture higher-margin contracts. The commercial opportunity lies in building application-specific grade portfolios, offering technical co-development, and establishing qualification pathways that reduce customer adoption friction.
- Regional supply diversification will become a standard procurement posture. Regulatory controls, import volume increases, and concentrate cost sensitivity are pushing buyers to construct multi-region sourcing strategies. Over the next few years, this will favor suppliers with transparent compliance records, flexible logistics, and the ability to provide alternative grades without compromising performance. Companies that invest in regional inventory hubs, long-term offtake agreements, and clear traceability will be better positioned to secure supply in volatile conditions.
- Vertical integration and feedstock control will separate margin performers from price-takers. The direct transmission of concentrate price movements into powder pricing means that companies with integrated reduction capabilities or secured feedstock channels will enjoy greater margin stability. This dynamic encourages strategic partnerships, capacity expansion in integrated facilities, and long-term contracts that lock in raw material economics. For buyers, it means evaluating supplier resilience as part of total cost of ownership, not just unit price.
These trends carry inherent risks and uncertainties. Regulatory timelines may shift again, altering the pace of diversification and the cost of alternative sourcing. Concentrate price volatility can compress margins unexpectedly, especially for producers without hedging mechanisms. Technical adoption in additive manufacturing and high-purity applications may progress faster or slower than anticipated, depending on downstream equipment compatibility, certification requirements, and total cost comparisons with conventional alternatives. Stakeholders should therefore treat these trends as directional signals rather than fixed forecasts, and build flexibility into capacity, inventory, and supplier qualification strategies.
Strategic Recommendations for Decision-Makers
Different stakeholder groups can extract actionable value from the current market dynamics by aligning strategy with the underlying drivers.
For manufacturers and producers:
PW Consulting
- Evaluate vertical integration or long-term feedstock arrangements to reduce exposure to concentrate price swings and stabilize margin profiles.
- Invest in spherical and high-purity grade capabilities where application demand is growing faster than the commodity segment, and build technical support infrastructure to accelerate customer qualification.
- Develop multi-region supply options and transparent compliance documentation to meet buyer expectations for resilience and traceability amid regulatory uncertainty.
For investors and strategic planners:
- Focus due diligence on suppliers with differentiated technical capabilities, integration advantages, and demonstrated ability to navigate regulatory shifts without supply disruption.
- Monitor segment-level demand signals, particularly in additive manufacturing and high-purity applications, as leading indicators of margin expansion and premium pricing potential.
- Assess consolidation opportunities where fragmented supply bases and buyer demand for reliability create conditions for strategic acquisitions or partnerships.
For procurement and supply chain leaders:
- Adopt dual-track sourcing strategies that balance cost efficiency with resilience, including qualified alternative suppliers, strategic inventory buffers, and flexible grade substitutions where performance allows.
- Incorporate total cost of ownership metrics that account for regulatory risk, delivery reliability, and technical support, rather than relying solely on unit price comparisons.
- Engage suppliers early in qualification and joint development processes to secure capacity, lock in specifications, and reduce lead-time exposure during periods of demand acceleration.
The molybdenum powder market is moving through a period where technical differentiation, regulatory agility, and supply chain resilience determine competitive outcomes. Stakeholders who align their strategies with these forces can capture growth in premium segments, stabilize margins amid cost volatility, and build sourcing postures that withstand policy shifts. For executives and investors seeking deeper segmentation data, regional dynamics, and customized strategic scenarios, comprehensive research reports provide the granularity needed to translate these directional insights into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Molybdenum Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aftermarket TPMS Market: Why 6.64% CAGR Signals a Structural Profit Shift
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Aftermarket Tire Pressure Monitoring System (TPMS) Market
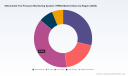
The global aftermarket TPMS market has evolved from a post-recall compliance niche into a structured growth segment driven by vehicle aging, regulatory tailwinds, and sensor technology maturation. Valued at approximately USD 4.06 billion in the base year 2025, the market has expanded steadily from 3.1 billion in 2020, reflecting a consistent upward trajectory through the 2020–2025 historical window. Forward projections indicate the segment will reach 6.27 billion by 2032, with a compound annual growth rate of 6.64 percent across the 2026–2032 forecast period. This expansion is not evenly distributed across the value chain; rather, it reflects a market where sensor replacement cycles, fleet maintenance economics, and diagnostic tooling are reshaping revenue flows. The aftermarket TPMS space operates with moderate concentration—top three players collectively hold a 42 percent share, while the top five account for 55 percent—leaving meaningful room for specialized entrants, regional distributors, and technology-focused innovators.
The market's current shape is defined by a blend of mature replacement demand and emerging connectivity expectations. Aging vehicle populations in developed regions continue to drive sensor replacement, while commercial operators increasingly view tire pressure management as a fuel-efficiency and safety lever rather than a regulatory checkbox. At the same time, the aftermarket channel is navigating a transition from purely mechanical replacement to programmable, multi-protocol sensors that must interface with evolving vehicle electronics. This shift is compressing traditional replacement cycles and forcing service networks to invest in updated diagnostic capabilities.
Key Challenges and Inflection Points
The aftermarket TPMS segment is currently navigating a set of structural tensions that will determine which participants capture durable margin over the next decade. First, interoperability has become a central friction point. As vehicle manufacturers expand protocol variants and integrate proximity or NFC-based programming, aftermarket sensors and diagnostic tools must continuously expand coverage libraries. Services and distributors face the cost of keeping tooling and sensor catalogs synchronized with new vehicle models, while end users encounter compatibility questions during retrofits.
Second, regulatory assurance is tightening around function and fit verification. Aftermarket TPMS sensors increasingly require third-party registration to meet federal motor vehicle safety standards, creating a compliance layer that separates generic replacements from certified offerings. This dynamic is reshaping procurement decisions, particularly for fleets and service networks that must document compliance across large vehicle populations.
Automatic Tire Inflation System Market
Third, the battery lifecycle and replacement economics introduce a recurring cost consideration that influences both consumer behavior and fleet budgeting. Sensor batteries typically operate for roughly 6 to 10 years, or between 90,000 and 120,000 miles, with replacement commonly performed using alkaline button cells such as the CR2032. As vehicles and fleets age beyond initial warranty periods, battery depletion becomes a recurring service event that interacts with labor scheduling, parts availability, and total cost of ownership calculations.
Key Drivers Shaping Market Trajectory
The expansion of aftermarket TPMS is not the result of a single catalyst; it is being pulled forward by overlapping technological, regulatory, demand-side, and supply-side forces that reinforce one another.
Technology Innovation and Programmable Sensor Architectures
The most decisive driver is the shift toward universal, programmable sensor platforms that can be configured across multiple protocols and vehicle coverage lists. Retrofit kits and OE-replacement sensors are increasingly offered with expanded coverage for passenger vehicles and light-duty segments, while heavy-duty truck portfolios add dedicated sensor and valve assemblies alongside specialized diagnostic tools. In February 2026, a major North American sensor provider introduced an AirCheck BLE universal retrofit TPMS kit for light-duty vehicles, signaling how connectivity features are being folded into retrofit offerings to improve installation flexibility and post-installation monitoring.
Parallel tooling updates are reducing the friction of fitting sensors to newer vehicle platforms. In April 2026, an aftermarket sensor supplier updated its coverage for EU-Pro Hybrid variants, including hybrid and NFC-enabled configurations, within diagnostic tool software. These updates matter because they extend the practical usability of existing tool investments and reduce the probability of mismatch failures during installation. Combined with BLE-enabled sensors that broaden coverage for passenger vehicles, the technology trajectory is moving from static replacement parts to adaptable, software-defined hardware.
Regulatory Environment and Safety Compliance
Policy and standards frameworks continue to shape both demand and channel behavior. Aftermarket TPMS sensors require NSF International registration to meet federal motor vehicle safety standards for third-party assurance on function and fit, a requirement that effectively filters the field toward suppliers capable of demonstrating verified performance. At the same time, regulatory guidance requires aftermarket TPMS devices to detect and warn drivers of system malfunction for vehicles equipped with factory systems, reinforcing the need for reliable post-installation diagnostics rather than simple part swaps.
These requirements do not simply impose compliance costs; they alter how service providers structure their offerings. Workshops and fleet maintenance teams increasingly bundle sensor replacement with relearn procedures, malfunction checks, and diagnostic verification. This creates a more service-intensive revenue model and raises the importance of compatible diagnostic software and relearn capabilities in the aftermarket tool set.
Demand-Side Behavior and Fleet Economics
On the demand side, the market is benefiting from two reinforcing trends. Consumer and fleet operators are increasingly aware that tire pressure management influences fuel consumption, tire wear, and safety outcomes. For passenger vehicles, the replacement cycle is supported by aging registrations and the ongoing need to service factory-equipped TPMS after battery depletion or sensor damage. For commercial vehicles, tire pressure management is being treated as an operational efficiency measure, especially where route optimization and total cost of ownership are under scrutiny.
Average replacement costs for TPMS sensors generally fall between $50 and $250 per unit, depending on whether the system is direct or indirect. When combined with shop labor charges that typically range from $50 to $100 per sensor, the total per-vehicle cost becomes material enough to influence purchasing behavior but not prohibitive for most fleets and consumers. This cost band supports steady demand while giving differentiated providers room to compete on coverage certainty, installation speed, and diagnostic confidence.
PW Consulting
Supply Chain Dynamics and Cost Structure
The supply side is influenced by battery dependency, sensor component standardization, and the economics of diagnostic tooling. The reliance on replaceable alkaline button cells creates a predictable aftermarket parts stream, but it also ties sensor longevity to a commodity component whose availability and pricing can fluctuate. Tooling and software updates add another layer to the cost structure: service centers must maintain current diagnostic capabilities, and suppliers must continue investing in coverage libraries that keep pace with vehicle model introductions. These dynamics reward suppliers and distributors that can reduce incompatibility risk and streamline relearn workflows, while pressuring players who depend on static part numbers and outdated tool compatibility.
Competitive Landscape and Leading Strategies
The competitive field blends established global specialists with regional and China-based suppliers that have expanded their aftermarket coverage. The market's moderate concentration suggests that scale advantages exist, but differentiation remains achievable through coverage breadth, diagnostic software maturity, and commercial channel relationships.
Strategic Positioning of Leading Participants
The competitive set reflects distinct strategic postures rather than a single winning formula. One U.S.-based specialist has centered its aftermarket value proposition on OE replacement sensors, universal retrofit kits, a heavy-duty truck portfolio, and BLE-enabled sensors with expanded passenger-vehicle coverage. Its recent February 2026 launch of a BLE universal retrofit kit for light-duty vehicles and its October 2025 heavy-duty OE replacement portfolio with sensors, valves, and a truck diagnostic tool point to a strategy that pairs hardware breadth with commercial fleet relevance.
A China-based supplier has built an aftermarket focus around OE-R and retrofit TPMS sensors, truck BMS sensors, universal bundles, and compatible diagnostic tools for aftermarket installation. Its April 2026 update of aftermarket sensor coverage across EU-Pro Hybrid configurations within diagnostic tool software demonstrates a focus on tool compatibility and regional coverage expansion, an approach that can accelerate adoption in service networks seeking broad-fit solutions.
A U.S. manufacturer has emphasized its Rite-Sensor TPMS line alongside diagnostic tools with relearn software for aftermarket service and programming. Its May 2026 promotion combining the Tech600Pro TPMS tool with 30 rubber stem Rite Sensors, and its May 2026 announcement of a SEMA Show booth to showcase aftermarket TPMS innovations, indicate a strategy oriented toward service-channel visibility, bundled tool-and-sensor offerings, and hands-on installer engagement.
A German supplier has positioned itself with universal programmable TPMS sensors offering expanded coverage for aftermarket and retrofit applications, a strategy aligned with reducing fit uncertainty across diverse vehicle populations. A France-based provider has concentrated on TPMS activation tools, diagnostic software, and sensor programming solutions for aftermarket workshops and service centers, effectively targeting the service-enablement layer of the market rather than hardware alone.
Differentiation Levers in a Moderate-Concentration Market
Across these players, several differentiation levers are emerging as commercially significant. Coverage certainty is increasingly valuable: universal sensors and diagnostic tools that can be updated to accommodate hybrid, NFC, and newer protocol variants reduce install failures and rework. Tool-and-sensor bundling is also gaining traction, as service centers seek predictable installation workflows and reduced dependency on multiple vendors. For fleet-facing participants, heavy-duty portfolios that combine sensors, valves, and dedicated diagnostic tools create a more complete aftermarket solution and can improve repeat-purchase dynamics.
Service enablement remains a powerful differentiator. Providers that pair hardware with relearn software, activation tools, and updated coverage libraries help workshops reduce time-per-vehicle and improve diagnostic confidence. This is especially relevant where regulatory expectations require malfunction detection and third-party registration assurance, because verified fit and functional checks become part of the commercial offer rather than an optional add-on.
Market Evolution: Integration, Fragmentation, and New Entry
The landscape appears to be moving toward selective integration at the top, paired with continued fragmentation in niche coverage and regional service channels. Larger specialists are strengthening portfolios that span passenger and heavy-duty segments, leveraging diagnostic software and connectivity features to widen their aftermarket reach. At the same time, the universal-programmable sensor trend lowers barriers for specialized entrants that can deliver strong coverage updates, tool compatibility, or competitive installation workflows. Regional distributors and service networks can also gain share by aggregating compatible tooling, sensor bundles, and compliance documentation, particularly where local installation practices and vehicle mixes differ from global averages.
Tire Pressure Monitoring System (TPMS) Market
The net effect is a market in which scale supports brand trust and channel relationships, but technical responsiveness—fast coverage updates, robust relearn support, and clear compliance positioning—can still create durable differentiation.
Future Trends and Commercial Opportunities
Looking ahead three to five years, two to three trends are likely to shape where value accrues in the aftermarket TPMS segment.
Trend One: Software-Defined Sensor Coverage as a Service Standard
As vehicle electronics diversify and hybrid and NFC configurations become more common, the ability to update diagnostic coverage quickly and reliably will increasingly define aftermarket competitiveness. Suppliers and service networks that treat sensor coverage as a continuously updated asset—supported by tool software updates and clear compatibility documentation—are better positioned to reduce install failures and maintain trust with workshop customers.
Commercial opportunity: Toolmakers and sensor suppliers can monetize coverage updates, subscription-style diagnostic software, and bundled sensor-and-tool kits that simplify procurement. Service centers can differentiate on installation speed and compatibility certainty, especially in markets where vehicle model diversity is high.
Trend Two: Fleet-Oriented Aftermarket Bundles and Total-Cost Positioning
Commercial vehicle operators are likely to continue treating TPMS as part of a broader tire and fleet maintenance strategy. Heavy-duty aftermarket portfolios that combine sensors, valves, and truck-specific diagnostics support this shift and create opportunities for bundled procurement, preventive maintenance scheduling, and fleet-wide coverage planning.
Commercial opportunity: Suppliers with strong heavy-duty coverage can build fleet relationships around replacement cycles, battery lifecycle planning, and tool access. Fleet buyers can reduce total cost variability by standardizing on compatible sensor and tool combinations that minimize rework and downtime.
Trend Three: Compliance-Driven Procurement and Verification as a Competitive Filter
Regulatory expectations around function, fit, and malfunction warnings are likely to deepen the role of verified compliance in purchasing decisions. Third-party registration requirements and malfunction-detection expectations increase the importance of documented performance, especially for large fleets and service networks that must demonstrate consistency across many installations.
Commercial opportunity: Participants that clearly communicate compliance positioning and provide reliable relearn and diagnostic workflows can capture procurement preference in regulated environments. Buyers can use compliance assurance as a risk-reduction lever, not merely a legal requirement.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Coverage fragmentation across vehicle protocols may raise installation complexity if updates lag behind new model introductions. Battery replacement economics and component availability could affect perceived sensor longevity, particularly in high-mileage commercial use. Labor cost variability and shop throughput constraints may influence how quickly fleets and consumers adopt full replacement-plus-diagnostic service bundles. Finally, if regulatory documentation requirements become more cumbersome for some market participants, compliance readiness may become a stronger barrier to entry in certain channels.
Actionable Recommendations for Decision-Makers
The aftermarket TPMS market rewards participants who align product strategy, service workflows, and procurement practices with the shift toward programmable coverage, compliance assurance, and fleet-oriented value.
For Sensor and Tool Manufacturers
- Prioritize universal, programmable sensor platforms with continuously updated coverage libraries, especially for hybrid and NFC configurations, to reduce install mismatch risk.
- Invest in diagnostic tooling and relearn software that supports fast, repeatable service workflows, and consider bundled sensor-and-tool offerings that simplify procurement for service centers.
- Build clear compliance and registration positioning into product communications, particularly where third-party assurance and malfunction detection expectations influence purchasing decisions.
For Investors and Strategic Partners
- Evaluate opportunities where coverage responsiveness, tool compatibility, and fleet-facing portfolios create stronger repeat-purchase potential than hardware-only replacement models.
- Watch for consolidation signals among specialists seeking broader coverage and heavier commercial-vehicle exposure, while also monitoring regional distributors that aggregate compatible tools and sensor bundles.
- Assess exposure to battery lifecycle dynamics and labor cost variability, since these factors influence replacement frequency and total-service economics.
For Fleet Operators and Procurement Teams
- Standardize on sensor and diagnostic tool combinations that minimize compatibility risk and rework, and document compliance assurance to support consistent procurement across vehicle populations.
- Treat TPMS replacement as part of a fleet maintenance workflow that includes battery lifecycle planning, malfunction checks, and relearn procedures rather than a one-time part swap.
- Evaluate total per-vehicle cost in context of labor, coverage certainty, and installation speed, since the gap between component price and shop labor can shape the economics of different sourcing choices.
Closing Perspective
The aftermarket TPMS market is entering a phase in which durable advantage depends less on being a generic parts supplier and more on delivering verified fit, updated coverage, and efficient service workflows. The growth path to 2032 reflects a market where technology updates, regulatory expectations, and fleet economics all reinforce the same direction: more programmable hardware, more diagnostics-intensive service, and more procurement emphasis on compatibility and compliance. For decision-makers, the practical question is no longer whether the segment will expand, but which participants will capture margin by reducing installation risk and supporting repeatable, compliant service.
The dynamics outlined here provide a directional view of the market, but the most consequential choices—segment-level positioning, tool-and-sensor bundling strategies, fleet procurement standards, and regional coverage priorities—require deeper segmentation detail and operational context. A full research report can provide granular breakdowns across region, type, and application, along with company-specific profiles and competitive benchmarking that support more precise planning. For teams evaluating product roadmaps, channel strategy, or investment exposure in aftermarket TPMS, that level of detail is the difference between a broad market narrative and a usable execution plan.
For detailed analysis of this topic, please visit the official page: Aftermarket Tire Pressure Monitoring System (TPMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Foam Roller Market: Why 10.7% CAGR Signals Commercial & Regional Shifts Through 2032
By pmarketresearch, 2026-09-21
Foam Roller Market Outlook: Strategic Trends and Commercial Opportunities Through 2032
Market Present: Scale, Trajectory, and Core Challenges
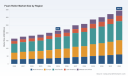
The global foam roller industry has transitioned from a niche recovery accessory into a mainstream wellness and fitness hardware category. Between 2020 and 2025, the market expanded from approximately USD 163.15 million to USD 215.0 million, reflecting a sustained uptake across both professional and consumer environments. Projections extending through the 2026–2032 forecast period point to continued momentum, with the market expected to reach roughly USD 344.8 million by the end of the horizon. This growth translates to a compound annual growth rate of 10.7%, a trajectory that signals both healthy demand expansion and periodic structural shifts rather than linear continuation of baseline sales.
It is useful to frame this expansion in terms of underlying pressure points rather than headline figures. The segment is no longer defined solely by volume of units sold; pricing architecture, material preferences, and end-user expectations are all moving in directions that reshape how manufacturers, distributors, and commercial buyers approach the category. The data indicates that total revenue is accumulating at a pace that outstrips simple population growth or gym membership expansion, implying that value capture is migrating toward higher-performing products, differentiated recovery protocols, and institutional procurement programs. At the same time, several discrete challenges are emerging that will determine which participants capture disproportionate share of the upside.
The Foam Roller Market's Core Challenges
Cartridge-level maturity in the basic consumer segment is one immediate constraint. Standard solid and hollow configurations, sold in default densities and generic dimensions, increasingly function as low-margin entry points. Buyers in price-sensitive channels treat these as interchangeable commodities, compressing the room for pure volume-driven growth. Companies that remain anchored in undifferentiated product lines risk being outflanked by competitors who bundle recovery applications, professional endorsements, or material claims into a more defensible value proposition.
Second, the cost backdrop tied to material inputs introduces structurally higher operating uncertainty. Pricing for key raw materials such as EVA has shown notable variance across geographies, with recent benchmarks in China and the United States indicating meaningful divergence in per-ton costs, while regional kg-level pricing has reflected similar dispersion between North America and Northeast Asia. Volatility of this type complicates both margin planning and inventory strategy, particularly for brands that operate multilayered distribution networks across multiple manufacturing origins. A firm that cannot hedge material exposure or flex sourcing quickly enough can see its price competitiveness erode even when end demand remains strong.
Third, the sustainability and regulatory conversation is moving from a peripheral marketing claim to a procurement-level requirement in certain commercial and institutional channels. The adoption of recycled and bio-based foam formulations is increasingly tied not only to product positioning but also to purchasing criteria in organizations that have committed to reduced virgin plastic usage and circular material targets. Players with legacy material architectures face a dual pressure: either invest in reformulation and supplier qualification, or accept narrowing access to contracts where material credentials are weighted alongside unit economics.
Key Drivers Reshaping the Segment
Innovation at the Intersection of Recovery and Automation
The most visible strategic shift is the migration from passive texture-based rollers toward products that embed measurable recovery benefits, guided usage patterns, or hands-free operation. Companies in the space are increasingly framing foam rollers as components within a broader recovery workflow rather than isolated stretching accessories. This is visible in product architectures that emphasize deeper tissue access, structured myofascial release, and mobility-oriented tension relief, as well as in newer automation efforts where AI-controlled or robotic rollers are being introduced to guide motion and pressure without direct hand operation. At the higher end of innovation, the category is beginning to accommodate devices that blend mechanical assistance with user programming, moving the foam roller closer to a service-like experience rather than a static consumable.
PW Consulting
The commercial significance of this shift is not simply product differentiation. It changes the economics of engagement. When a product offers a more repeatable, measurable, or guided recovery experience, it can justify premium positioning, recurring accessory sales, or stronger integration into clinical, athletic, and supervised wellness settings. That, in turn, creates a path to defend against price compression in the standard consumer tier.
Policy, Material Standards, and Sustainability Expectations
Regulatory and procurement environments are shaping demand in ways that are sometimes indirect but strategically important. The category is experiencing a gradual normalization of recycled content expectations, particularly for foam-based products where material sourcing decisions can influence whether an offering qualifies for certain institutional and sustainability-driven programs. Recycled EPP architectures and bio-based foam options are gaining traction as manufacturers align product development with internal environmental targets and external stakeholder expectations.
This dynamic does not simply reward environmental storytelling. It introduces a procurement sieve. In commercial gyms, rehabilitation settings, and corporate wellness facilities, purchase decisions increasingly privilege suppliers that can document material provenance, recycling rates, or reduced virgin polymer usage. Over time, these preferences harden into buying standards. Manufacturers that can speak credibly to material credentials while maintaining performance benchmarks are positioned to access channels that become more selective as the category matures.
Demand-Side Evolution: Aging Populations, Wellness Culture, and Non-Invasive Recovery
Longer-term demographic and behavioral shifts reinforce the category’s expansion beyond a purely athletic user base. An aging population and a broader consumer orientation toward non-invasive recovery tools are expanding the pool of potential users who seek mobility support, circulation comfort, and routine muscle care without clinical intervention. Health-conscious consumption is no longer restricted to dedicated fitness enthusiasts; it spans home users, older adults, and individuals managing routine stiffness or post-activity recovery. This broadens the application canvas and makes the product relevant in both family and commercial environments, though the value drivers differ by context.
In practice, the strategic implication is that the category’s growth is not solely reliant on the expansion of gym footfall or athletic participation. It is also supported by self-care routines, home fitness investments, and an increasing recognition of mobility maintenance as a daily habit. This diversification of user intent gives manufacturers multiple expansion paths, but it also requires clearer product-to-use-case alignment because the needs of a home fitness user, a physical therapy clinic, and a performance facility do not fully overlap.
Supply Chain and Cost Structure Realities
The material cost environment remains a central strategic constraint. Recent observations on EVA and foam pricing point to meaningful geographic dislocation: input benchmarks vary by region and by month, which affects landed cost, logistics planning, and the feasibility of aggressive price moves. In an environment where demand continues to grow but raw material pricing can shift the profitability equation quickly, supply chain flexibility becomes a competitive lever.
Yoga Mat Market
Companies that can coordinate sourcing across regions, qualify alternative material grades, or structure procurement contracts to reduce exposure to short-term pricing spikes gain more room to protect margins or to pass value-based pricing through without losing channel acceptance. Conversely, businesses that rely on static sourcing assumptions are more exposed to margin compression and to the temptation of discounting that can damage brand positioning.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of specialized recovery brands, established fitness and equipment players, and emerging technology-forward entrants. Each is pursuing a different route to relevance, and the strategic variance is instructive.
TriggerPoint, based in Durham, North Carolina, anchors part of its positioning around patented self-massage patterns and a focus on deep tissue recovery and performance-oriented use. Its emphasis is less about generic rolling surfaces and more about structured texture and recovery specificity. That approach suits users who want a repeatable mechanical effect and supports premium positioning within performance and rehabilitation conversations.
RumbleRoller, operating from Baton Rouge, Louisiana, has built recognition around textured knobs intended for myofascial release and athlete recovery. Its most recent activity reinforces a continued focus on athletic, trainer, and physical therapy audiences, indicating a deliberate concentration on deep tissue utility and end-user credibility rather than broad consumer dilution. Recent marketing emphasis on deep tissue recovery for athletes and professionals underlines a positioning strategy that leans on functional differentiation and domain trust.
Yes4All, headquartered in Ho Chi Minh City, illustrates a different strategic logic: breadth, density options, and institutional accessibility. Its portfolio spans multiple sizes and densities using high-density EVA and EPP materials, aiming at both home fitness and institutional procurement. This orientation reflects a volume-aware strategy that prioritizes utility, specification flexibility, and cost-competitive offerings for buyers who want reliable product in varied context settings.
Technogym, from Cesena, approaches the category through a more system-integrated lens, presenting recovery rollers in the context of mobility, circulation, and personalized tension relief. As a broader equipment and wellness ecosystem player, Technogym is positioned to connect foam rollers to larger facility, programming, and user-experience narratives, which can be valuable in commercial environments that seek cohesive recovery arrangements rather than standalone accessories.
Adidas, based in Herzogenaurach, demonstrates how a major sportswear and fitness brand treats sustainability as a product identity. Its foam roller offering has been developed using recycled EPP materials with the explicit goal of reducing virgin plastic waste. This positions the brand at the intersection of material innovation and brand credibility, useful in channels where environmental commitments influence purchasing or where the product must align with broader corporate sustainability narratives.
RheoFit represents the most distinct strategic entry point: a move toward automation. Its recently introduced automatic foam roller with AI control targets hands-free deep tissue massage and recovery, signaling an attempt to shift the category from manual application toward guided or automated treatment. The product trajectory suggests a bet on convenience, repeatability, and a more technology-rich user experience, even if the category is still in early adoption for such models.
Market Structure Trends: Convergence, Fragmentation, and Increment Entrants
Taken together, the field suggests a market in which segments are simultaneously converging and diverging. On one side, the basic consumer tier faces commodity pressure and potential consolidation around players who can either manufacture efficiently at scale or reliably supply institutional channels. On the other side, differentiated recovery features, material credentials, commercial-system integration, and automation are opening pockets where distinct advantage can be built and defended.
This points toward a future in which the market structure is less uniform than it appears. Some players will compete through engineering and material performance; others through branding and ecosystem integration; others through cost-efficient product breadth; and others through automation and service-anchored experiences. The result is likely to be a more layered competitive environment in which winning depends on which layer a company chooses to dominate and how effectively it can align product, channel, and messaging accordingly.
Outlook for the Next Three to Five Years
Trend 1: Recovery as a Structured Behavior, Not an Occasional Tool
Over the next few years, foam rollers are likely to be used less as an occasional stretching accessory and more as a structured element in mobility and recovery routines. As non-invasive recovery tools gain wider acceptance across older demographics, home fitness users, and professionals seeking accessible muscle care, products that support repeatable routines and clearer use protocols will gain traction. The commercial opportunity lies in designing not only the product but the surrounding guidance, accessory ecosystems, and channel support that make usage consistent and outcome-oriented.
Worldwide Facial Roller Market
The risk is that this trend rewards only a subset of participants. If usage guidance, ergonomics, and perceived efficacy do not improve, consumers may cycle through low-differentiation products without forming durable loyalty. Brands that rely purely on surface-level features may find retention harder to sustain.
Trend 2: Sustainability Credentials as Procurement Gatekeepers
Material sourcing and environmental alignment will continue to move from a favorable brand attribute to a qualifying factor in select procurement environments. Recycled and bio-based foam architectures are gaining relevance because they can satisfy internal targets for organizations committed to lower virgin plastic usage. Over time, this could affect contract access, retailer preferences, and institutional demand, especially where sustainability criteria are formally weighted in purchasing decisions.
The upside is clear: manufacturers that can combine performance with credible material claims open doors to more selective and often higher-value channels. The uncertainty lies in how quickly standards harden and how consistently they are enforced across regions and buyer types. Premature assumptions about universal adoption can create misplaced investment, but lagging too far behind can narrow future access.
Trend 3: Technology-Enabled Recovery as a Differentiator and Price-Defense Mechanism
Automation and AI-controlled application are unlikely to replace conventional foam rollers across the entire market, but they can become a meaningful differentiator in premium and professional contexts. Hands-free or guided recovery devices address convenience, repeatability, and user experience considerations that manual tools do not. In practice, such offerings can help justify higher price points, attract early adopters, and create a stronger narrative around recovery precision.
At the same time, technology-driven products introduce their own risks: higher development cost, more complex manufacturing or service requirements, uncertain mainstream adoption curves, and potential fragility in the value proposition if the device experience does not match expectations. The strategic opportunity is to use technology where it solves a genuine pain point rather than as a generic premium label.
Strategic Actions for Decision-Makers
For Manufacturers
- Align product development with clearly defined use cases instead of broadening generically. Performance-oriented, home-care-oriented, and institutional-oriented needs differ enough to justify separate engineering priorities, density choices, and accessory strategies rather than a single line attempting to capture every buyer.
- Treat material sourcing flexibility as a strategic asset. Geographic pricing variance in raw materials means that sourcing, supplier qualification, and contract structures should be designed to reduce exposure to short-term cost swings and to support reformulation where sustainability requirements are becoming procurement-relevant.
- Use differentiation that connects to measurable user benefit. If a product relies on texture, density, recovery guidance, automation, or material claims, the benefit should be understandable and demonstrable to the intended buyer, because vague differentiation is quickly eroded by price competition.
For Investors
- Evaluate exposure by layer of the value chain. A company’s prospects may depend less on overall category growth than on whether it competes in a defensible niche, whether it has sustainable cost structures, and whether it can access channels that increasingly value performance or sustainability credentials.
- Watch for consolidation pressure in the commodity-adjacent end of the market and for technology or differentiation-driven models that may command stronger positioning. The most attractive opportunities are likely to sit at the intersection of real user value and clearer procurement or usage alignment rather than broad commodity exposure alone.
- Assess scalability carefully in technology-forward offerings. Automation and AI-connected devices can open premium pathways, but their investment case depends on adoption curves, service complexity, and whether the product solves a friction point that buyers will pay to remove.
For Procurement and Commercial Buyers
- Define selection criteria beyond unit price. In commercial and institutional settings, product durability, material credentials, recovery utility, and supplier reliability can matter as much as purchase cost, especially where program goals include sustainability or repeatable user outcomes.
- Shortlist suppliers that can demonstrate material and performance alignment with the intended environment. The relevance of EVA, EPP, recycled content, density options, and texture architecture depends on the setting, so procurement should match the specification to the actual use case rather than default to the lowest headline price.
- Monitor supplier roadmaps for reformulation, automation, and ecosystem integration. Buyers that understand which suppliers are investing in credible product evolution will be better positioned to negotiate multi-period agreements that balance cost, performance, and future-proofing.
The market environment through the forecast period will likely reward organizations that can connect product strategy to the forces actually shaping demand: structured recovery behavior, material and sustainability expectations, and selective technology adoption. The most resilient plans will be the ones that account for cost volatility, channel specificity, and the growing premium on credible differentiation rather than uniform volume expansion. For decision-makers who require a deeper breakdown of regional dynamics, segmentation detail, and competitive movement across the full 2026–2032 horizon, PW Consulting’s comprehensive market assessment provides a structured foundation for scenario planning and procurement strategy.
For detailed analysis of this topic, please visit the official page: Foam Roller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Intermittent Catheters Market Beyond 5.77% CAGR: Coating & Home Care Surge
By pmarketresearch, 2026-09-21
Intermittent Catheters Market: Strategic Trends and Commercial Opportunities Through 2032
The global intermittent catheters market is navigating a period of structural transformation. Moving from a base of approximately 210.0 million USD in 2025, the market is projected to expand at a compound annual growth rate of 5.77 percent across the 2026-2032 forecast horizon, ultimately approaching 306.64 million USD by 2032. This trajectory is not simply a function of demographic tailwinds. It reflects a convergence of reimbursement restructuring, technological breakthroughs in coating and device architecture, and a sustained shift in care delivery from institutional settings to home and community-based environments. For executives, investors, and procurement leaders, the critical question is no longer whether the market will grow, but how value will be redistributed as the competitive and regulatory landscape matures.
Historical data from 2020 through 2025 shows a market that has consistently expanded, recovering from modest post-pandemic normalization and accelerating through 2023-2025 as hospitals and home care providers recalibrated supply chains and patient management protocols. The forward-looking numbers indicate a step-up in growth momentum beginning around 2027, suggesting that late-cycle innovation adoption and reimbursement clarity will begin to compound. This blog post examines the forces shaping that trajectory, the competitive positions that will define market leadership, and the strategic moves that will separate winners from laggards in the next five years.
Market Landscape and Core Challenges
At a macro level, the intermittent catheters market operates with a moderately concentrated structure. The top three players command roughly 42.0 percent of total revenue, while the top five control approximately 52.0 percent. This level of concentration signals a market where scale, reimbursement navigation, and clinician trust matter significantly, but where there remains ample room for specialized differentiation and regional or application-focused entrants. The revenue base is currently split across coated and uncoated product lines, with coated technologies commanding a larger share of the market. From an application perspective, urinary incontinence, spinal cord injury, urinary retention, and broader urological management collectively drive demand, each requiring distinct product performance characteristics and user-experience considerations. The end-user landscape spans hospitals, home care settings, and specialty clinics, with institutional volumes remaining substantial but home care and specialty channels gaining relative weight as chronic bladder management shifts toward decentralized care models.
Despite the positive growth trajectory, the industry faces three interrelated challenges that will determine which companies capture disproportionate value.
The first challenge centers on reimbursement architecture and coding transitions. The introduction of new HCPCS codes A4295, A4296, and A4297 for hydrophilic intermittent catheters, effective January 1, 2026, requires suppliers to discontinue legacy codes A4351, A4352, and A4353 for hydrophilic products. This is not merely an administrative adjustment. It reshapes formulary eligibility, prior authorization workflows, and patient access pathways. Companies that have historically relied on broad-coded billing structures must now demonstrate clinical differentiation and cost-effectiveness within narrower reimbursement categories, or risk margin compression as payers scrutinize claim patterns under the new framework.
The second challenge is the tension between user adherence and product ergonomics. Intermittent catheterization is a routine that patients perform independently, often multiple times per day. Friction, discomfort, infection anxiety, and the psychological burden of self-catheterization directly influence compliance. Products that reduce insertion resistance, minimize mess, and support discreet use consistently outperform legacy designs in real-world retention metrics. The market will increasingly reward designs that align with daily-life constraints rather than clinical specifications alone.
The third challenge is supply chain resilience and input cost volatility. Catheter manufacturing depends on specialized polymers, coating chemistries, and precision extrusion processes. Disruptions in raw material availability, regulatory scrutiny of biocompatibility, and the cost of quality assurance testing can compress margins for manufacturers that lack scale flexibility or diversified sourcing. As coated and closed-system designs become more prevalent, the cost profile of production shifts, creating a competitive divide between companies that can amortize advanced manufacturing investments and those that operate at narrower throughput windows.
Key Drivers of Market Evolution
Several converging forces are shaping the trajectory of the intermittent catheters market. Understanding these drivers is essential for anticipating where demand will intensify, where margins will shift, and which product architectures will define the next cycle.
Technological Innovation and Material Science
Coating technology remains the central battleground for product differentiation. Hydrophilic coatings reduce friction during insertion, lower the risk of urethral trauma, and improve patient comfort, which directly supports adherence in chronic use cases. The market has moved beyond simple lubrication toward engineered coatings that balance durability, glide performance, and compatibility with single-use disposal requirements. For coated intermittent catheters, the value proposition is increasingly tied to clinical outcomes and user retention rather than novelty. Companies that can demonstrate consistent coating performance across temperature ranges, humidity variations, and shelf-life constraints will secure stronger formulary positions and clinician recommendation patterns.
At the device level, the emergence of reusable intermittent catheter systems marks a notable inflection point. In May 2026, the FDA granted de novo authorization for a reusable intermittent catheter system, establishing a new device classification category for reusable intermittent technology. This decision signals a regulatory opening for architectures that reduce waste, lower per-use costs over time, and appeal to environmentally conscious procurement standards. While adoption will depend on cleaning protocols, patient education, and reimbursement alignment, the authorization creates a pathway for a product archetype that was previously constrained by classification uncertainty. Manufacturers that can pair reusable platforms with robust sterilization, tracking, and durability validation will be positioned to contest share in segments where total cost of ownership matters more than upfront unit price.
Policy and Regulatory Environment
Regulatory and reimbursement dynamics are actively reconfiguring market access. The 2026 HCPCS code restructuring for hydrophilic intermittent catheters is a structural change rather than a transitional adjustment. By requiring suppliers to transition away from legacy codes, the policy environment is pushing the market toward greater specificity in product coding. This specificity can benefit manufacturers with clearly differentiated hydrophilic portfolios, but it also raises the bar for documentation, claim accuracy, and payer communication. Suppliers that invest early in coding transition support, clinician education, and reimbursement navigation tools will reduce friction for customers and protect volume during the code sunset period.
Beyond coding, the broader regulatory posture around single-use medical devices, biocompatibility testing, and environmental footprint is tightening. Manufacturers must balance performance claims with documented safety profiles and, increasingly, with sustainability considerations that influence procurement decisions in health systems and DME suppliers. The FDA classification developments around reusable systems further illustrate how regulatory clarity can unlock new commercial categories that were previously constrained by ambiguity. Companies that treat regulatory engagement as a strategic capability, rather than a compliance function, will be faster to capture emerging opportunities.
Demand-Side Shifts in Care Delivery
Care delivery is steadily moving from inpatient and clinic-heavy models toward home-based and community-managed bladder care. This shift is driven by cost pressures on hospitals, patient preferences for convenience and autonomy, and the growing availability of user-friendly catheter designs that support safe self-management. Home care settings and specialty clinics are gaining relative importance as end-user channels because they align with the chronic, recurring nature of intermittent catheterization. In these settings, product attributes such as compactness, ease of handling, discreet packaging, and clear user instructions can be as commercially decisive as raw clinical performance.
Patient behavior is also becoming more informed and more demanding. Users are comparing products not only on clinical outcomes but on everyday practicality: how quickly a catheter can be prepared, whether it requires manual lubrication, how it fits into work, travel, and social routines, and how the disposal experience aligns with environmental preferences. This demand-side evolution favors manufacturers that design for the full user journey rather than for the moment of insertion alone.
PW Consulting
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by the growing share of coated and closed-system products, the complexity of coating supply chains, and the financial implications of single-use versus reusable architectures. Manufacturers that can secure reliable access to specialty polymers and coating inputs, while maintaining consistent quality across production runs, will hold a structural advantage. At the same time, the economics of reusable systems introduce a different cost logic: higher initial engineering and validation investment, offset by lower recurring material consumption and waste handling costs over the device lifecycle. This divergence creates distinct strategic paths. Some companies will compete on volume, consistency, and reimbursement alignment in single-use coated lines. Others will pursue total-cost-of-ownership positioning through reusable or hybrid platforms. Both paths can be viable, but they require different capabilities and partner ecosystems.
Competitive Landscape and Leading Strategies
The market is populated by a mix of globally scaled urology and continence care players and specialized manufacturers that compete on design, coating technology, and targeted user segments. Understanding how these companies position themselves clarifies where competitive advantage is being built and where vulnerabilities may emerge.
Coloplast has built a strong reputation around hydrophilic-coated lines such as SpeediCath and Self-Cath, emphasizing no-touch insertion and user-friendly designs for male, female, and pediatric patients. This positioning aligns closely with the market's shift toward adherence, ease of use, and reduced handling complexity. By centering product design around the patient experience and reducing contamination risk through no-touch architectures, Coloplast has reinforced clinician trust and user familiarity, which are critical in a category where repeat purchases and recommendation patterns matter.
Medical Catheters Market
Becton Dickinson, through its Bard portfolio, offers a broad range of intermittent catheters including uncoated, hydrophilic, and closed-system options for urological care. This breadth allows BD to serve diverse clinical and reimbursement scenarios, from cost-sensitive settings to cases where closed-system designs are preferred for infection-control reasons. The strategic advantage here is optionality: the ability to match product architecture to specific procurement and clinical requirements across multiple end-user channels.
Hollister Incorporated provides a full line of intermittent catheters tailored for continence care and bladder management. Its positioning reflects deep familiarity with the continence care ecosystem and a focus on products that integrate into broader bladder management routines. In markets where continuity of supply, clinician relationships, and patient education support drive loyalty, this holistic approach can strengthen retention and reduce switching.
B. Braun Melsungen AG supplies urinary catheters, including intermittent types, with an emphasis on quality and safety. This positioning suits healthcare environments where procedural reliability and compliance documentation are paramount. By leaning into quality assurance and safety credentials, B. Braun reinforces its eligibility in institutional procurement where risk management and standards adherence influence purchasing decisions.
ConvaTec Group Plc's GentleCath line, including Glide and advanced coating technologies, underscores the industry's focus on reducing insertion friction and improving user comfort. Advanced coating claims are increasingly scrutinized, so companies that can support performance with consistent manufacturing and credible user feedback are better positioned to defend premium positioning within hydrophilic segments.
Teleflex Incorporated manufactures Rüsch Tiemann and other uncoated and hydrophilic intermittent catheters, including options for difficult catheterization cases. This focus on challenging clinical scenarios creates a niche advantage: products that address specific anatomical or procedural difficulties can secure strong clinician endorsement in segments where standard designs are insufficient.
Medtronic maintains a portfolio of intermittent catheters supporting urological applications. Its presence illustrates how broader medical technology companies can leverage existing urology relationships and distribution networks to sustain intermittent catheter sales without necessarily leading with category-specific innovation. The strategic value lies in cross-selling and channel leverage rather than standalone product differentiation.
Wellspect HealthCare specializes in hydrophilic and closed-system intermittent catheters. This specialization allows the company to concentrate resources on coating performance, closed-system convenience, and the user groups that value those features most. In a market where hydrophilic and closed-system designs are gaining relative importance, focused specialization can be a strong response to the reimbursement and user-experience shifts described earlier.
Cure Medical produces eco-friendly, single-use intermittent catheters with hydrophilic and uncoated options. This positioning ties product design to environmental considerations, an increasingly relevant factor in procurement decisions and patient preference. Sustainability messaging is most effective when paired with genuine material choices and disposal outcomes rather than symbolic claims, and manufacturers that can substantiate eco-friendly positioning will find receptive audiences among health systems and DME suppliers facing their own sustainability mandates.
CompactCath, Inc. develops compact, pre-lubricated, no-touch intermittent catheters designed for active and discreet use. This is a clear example of design-led differentiation aimed at lifestyle compatibility. For users who prioritize portability, privacy, and minimal routine disruption, compact and pre-lubricated architectures can drive strong brand loyalty even in a market where clinical performance requirements are broadly met by multiple competitors.
BEVER Medical operates as an OEM and direct manufacturer of hydrophilic intermittent catheters and suction catheters. This model highlights the growing role of manufacturing partners and private-label supply in the market. Companies that can deliver consistent coating quality, scalable production, and flexible specification support enable brand owners to expand portfolios without bearing full manufacturing capital intensity. The OEM channel is particularly relevant as coding transitions and reimbursement specificity increase the need for tailored product configurations and documentation support.
Market Structure Trajectories
The competitive landscape is evolving along several axes. First, there is a continuing pull toward integration among larger players who can combine coated product lines, closed-system options, reimbursement navigation, and broad distribution. Scale helps in managing coding transitions, maintaining consistent supply, and funding coating and design innovation. Second, there is parallel fragmentation through specialized entrants that compete on compactness, reusable architectures, eco-friendly positioning, or difficult-case clinical performance. These entrants often grow by serving underserved user needs or by partnering with established distributors and OEMs. Third, regulatory developments such as the reusable device classification and hydrophilic coding changes are likely to accelerate portfolio rationalization. Companies with products that do not fit cleanly into new coding or classification structures may face pressure to reposition, license, or divest. The net effect is a market where strategic clarity about which segment to serve, and with which product architecture, becomes more important than broad coverage alone.
Future Trends and Commercial Opportunities
Trend 1: Hydrophilic and Coated Platforms Will Anchor Premium Segments
Over the next three to five years, hydrophilic and advanced coated intermittent catheters are likely to hold an expanding share of revenue, particularly in home care and specialty clinic channels where user comfort and adherence drive repeat usage. The commercial opportunity lies not only in coating performance but in the surrounding ecosystem: reimbursement documentation that aligns with the new hydrophilic-specific codes, clinician and patient education that supports correct use, and packaging and disposal solutions that reduce friction in daily routines. Companies that treat coating as one component of a broader user-retention strategy will capture more durable share than those that compete on glide claims alone.
Microcatheter Market
Trend 2: Reusable and Hybrid Architectures Will Gain a Footing Where Total Cost Matters
The FDA de novo authorization for a reusable intermittent catheter system opens a pathway for architectures that can demonstrate durability, safe reprocessing, and favorable total-cost economics. The near-term opportunity is strongest in settings where procurement evaluates lifecycle cost, where environmental mandates influence purchasing, and where patient education and follow-up can be structured to support safe reuse. The uncertainty is adoption speed. Cleaning behavior, sterilization confidence, and reimbursement parity for reusable platforms will determine whether this trend remains niche or expands into a meaningful alternative within specific user segments. Manufacturers that invest early in validation, user onboarding, and payer dialogue will be better positioned to shape the category rather than react to it.
Trend 3: Reimbursement Navigation Will Become a Core Commercial Capability
With HCPCS code changes effective in 2026 and intermittent urinary catheters reimbursed as DME under updated coding structures, the ability to help suppliers, clinicians, and patients navigate reimbursement will increasingly differentiate commercial performance. The opportunity is to reduce claim friction through clear coding guidance, accurate product classification, and proactive communication with DME payers and procurement teams. Companies that build reimbursement support into their go-to-market model can protect volume during code transitions, reduce denials-related leakage, and strengthen relationships with customers who face their own compliance pressures.
Risks and Uncertainties
Several factors could alter the pace or shape of growth. Faster-than-expected reimbursement tightening could compress margins for products that cannot demonstrate differentiated value within the new hydrophilic codes. Conversely, slower adoption of reusable systems could limit the upside of that category if reprocessing concerns or reimbursement gaps persist. Input cost volatility, particularly in specialty polymers and coating materials, may pressure manufacturers without scale flexibility. Finally, the market's moderate concentration leaves room for competitive disruption if a new entrant successfully combines coating performance with packaging, reimbursement support, or sustainability claims that resonate strongly in key channels.
Strategic Implications for Decision-Makers
The market's direction is clear enough to warrant action, but the precise moves required depend on where a company sits in the value chain. The following recommendations are intended to translate the broader trends into practical priorities.
For Manufacturers and Brand Owners
Align product portfolios with the new hydrophilic coding framework before the transition creates claim friction. Prioritize coating consistency, no-touch or reduced-touch handling, and packaging designs that support discreet, portable use. Evaluate whether a reusable or hybrid architecture fits your capabilities and target segments, and invest early in validation and payer communication if it does. For companies relying on OEM partners, ensure specification flexibility, quality documentation, and coding alignment are built into the supply relationship so that product changes can be executed without disrupting claim eligibility.
For Investors
Focus due diligence on companies that demonstrate three things: credible coating and manufacturing consistency, a clear reimbursement navigation strategy for the 2026 HCPCS changes, and a user-experience design that supports adherence in home and community care. The most attractive opportunities are likely in firms that can defend premium positioning through differentiated coatings and user-centric design, or that can unlock lifecycle cost advantages through reusable platforms with robust validation. Watch for portfolio rationalization signals as coding and classification changes take effect, since these often reveal which assets are strategically aligned and which are carrying hidden compliance or claim risk.
For Procurement and DME Operators
Treat the coding transition as a supply-chain and claim-accuracy project, not just an administrative update. Map current product lines against the new hydrophilic codes, confirm documentation requirements, and identify suppliers that can support a clean transition. Where applicable, evaluate reusable or hybrid options against total cost of ownership rather than unit price alone, and consider pilot programs that include structured patient education and tracking. Supplier partnerships that provide coding guidance, consistent coating quality, and strong user support will reduce operational risk during the transition period.
The intermittent catheters market is entering a phase where reimbursement specificity, user-experience design, and architectural innovation will determine competitive outcomes more than historical scale alone. The companies that act early on coding alignment, coating consistency, and lifecycle economics will be best positioned to capture the next wave of growth through 2032. For decision-makers seeking detailed segmentation data, channel-level revenue splits, and customized competitive assessment across specific product and application categories, the full PW Consulting research report provides the granular analysis needed to translate these market-level insights into precise strategic plans.
For detailed analysis of this topic, please visit the official page: Intermittent Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Semiconductor Lasers Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The semiconductor lasers market has evolved from a specialized component niche into a foundational enabler across multiple high-growth industries. With the total market valuation reaching approximately $9.5 billion in 2025 and projected to expand toward $17.2 billion by 2032, the sector is tracking a compound annual growth rate of 8.8 percent. This trajectory reflects sustained demand from communications infrastructure, industrial processing, consumer electronics, and emerging applications in automotive sensing and medical technologies. The revenue progression from the early 2020s through the mid-2020s demonstrates consistent upward momentum, with incremental acceleration as downstream industries scale their adoption of laser-based solutions.
Despite this growth narrative, the market operates within a complex environment shaped by several structural tensions. Understanding these challenges is essential for executives evaluating entry points, expansion strategies, or capital allocation decisions.
Supply Chain Vulnerability and Geopolitical Realignment
The semiconductor lasers supply chain is deeply intertwined with broader semiconductor manufacturing ecosystems. Recent regulatory initiatives, including proposed restrictions under the Federal Acquisition Regulation Council targeting federal procurement of electronic products reliant on semiconductors, have introduced compliance complexity for component suppliers. Concurrently, NIST has launched initiatives to address measurement gaps in semiconductor supply chain visibility, with direct implications for optical frequency-related devices and laser components. These regulatory movements, combined with SEMI's ongoing efforts to benchmark supply chain resilience metrics, signal a structural shift toward greater scrutiny of component provenance, manufacturing location, and technology transfer pathways.
For laser manufacturers and their customers, this environment creates a dual pressure: maintaining production efficiency while navigating an increasingly fragmented regulatory landscape. Companies with concentrated supply chains or single-source dependencies face heightened exposure to disruption.
Technology Convergence and Application Fragmentation
The market is experiencing simultaneous convergence and fragmentation. On one hand, advances in complementary technologies such as high-precision optics, advanced packaging, and photonic integration are expanding the technical boundaries of what semiconductor lasers can achieve. On the other hand, end-use applications are diversifying rapidly, with communications, industrial processing, medical procedures, consumer electronics, and automotive sensing each imposing distinct performance requirements, reliability standards, and cost constraints.
This fragmentation challenges manufacturers to balance breadth of portfolio against depth of specialization. Companies that spread resources too thinly across incompatible application segments risk diluted competitive positioning, while those that over-index on a single vertical may miss cross-sector technology transfer opportunities.
Concentration Dynamics and Competitive Pressure
Market concentration remains notable, with the top three participants accounting for approximately 48.5 percent of revenue and the top five representing roughly 67.2 percent. This level of concentration reflects the technical barriers to entry, capital intensity of manufacturing, and the value of established customer relationships in precision applications. However, it also masks underlying shifts, including the emergence of specialized players targeting niche wavelengths, packaging formats, and application-specific configurations.
The presence of both large diversified photonics companies and focused specialists creates a dynamic competitive environment where differentiation increasingly depends on application expertise, supply chain agility, and the ability to co-develop solutions with end customers rather than competing solely on component specifications.
Key Drivers Analysis
The growth trajectory of the semiconductor lasers market is not accidental; it is being pulled by interconnected forces across technology, policy, demand behavior, and supply chain economics. Examining these drivers reveals where momentum is strongest and where strategic positioning will matter most.
Technology Innovation and Wavelength Expansion
Technological progress in semiconductor lasers continues to center on three dimensions: wavelength diversification, power scaling, and form-factor optimization. Recent developments illustrate this trajectory clearly. In early 2026, IPG Photonics introduced new high-power laser platforms on a rack-integrated architecture and demonstrated Deep UV at 266 nm alongside green laser sources targeted at precision micro-machining in semiconductor manufacturing. This expansion into shorter wavelengths and integrated packaging reflects a broader industry push toward laser solutions capable of finer feature resolution and more complex material processing.
Simultaneously, Nuvoton Technology has moved aggressively into high-power violet and UV laser diodes. The company commenced mass production of a 402 nm, 4.5 W violet laser diode in a TO-9 package for advanced semiconductor packaging and lithography systems, followed by the introduction of a 379 nm, 1.0 W UV device in a compact 9.0 mm CAN package for maskless lithography. These product milestones underscore a growing emphasis on UV and violet wavelengths for semiconductor packaging applications, where finer patterning, improved edge quality, and reduced thermal impact are driving adoption.
Beyond wavelength expansion, innovation in packaging and integration is enabling new deployment models. Compact packages, higher wall-plug efficiency, and improved thermal management are making semiconductor lasers more viable in space-constrained or thermally sensitive environments, including automotive sensing modules and portable medical devices.
Policy and Regulatory Environment
Policy developments are shaping both the cost structure and the strategic calculus for semiconductor laser participants. The CHIPS-related R&D initiatives and supply chain visibility programs introduced by NIST are creating new frameworks for measurement, standardization, and documentation that affect optical frequency devices and laser components. While these programs aim to strengthen overall ecosystem resilience, they also impose additional compliance and documentation requirements that can raise the cost of participation, particularly for smaller manufacturers.
At the same time, federal procurement restrictions proposed by the FAR Council are influencing purchasing behavior among government-dependent customers and their downstream suppliers. Companies that serve segments with significant government exposure must factor compliance requirements into product design, supply chain configuration, and customer engagement strategies. The broader implication is that regulatory alignment is becoming a competitive consideration, not merely a legal obligation.
Geopolitical dynamics are also filtering into the market. Germany-based TRUMPF Group, a key supplier of advanced laser technology components used in EUV lithography systems, faces potential collateral exposure from US semiconductor supply chain controls affecting complex manufacturing ecosystems. This illustrates how policies directed at broader semiconductor trade can have cascading effects on specialized laser and photonic component producers, even when those producers are not the direct target of restrictions.
Demand-Side Shifts Across End-Use Segments
Demand for semiconductor lasers is being reshaped by evolving requirements in several key segments. In communications, the expansion of optical networking capacity and the deployment of higher-density datacom infrastructure are driving continued reliance on laser diodes for signal transmission. Coherent's demonstration of a broad range of InP technology innovations, including semiconductor lasers for datacom and optical networking at OFC 2026, highlights how material platform advancements are aligning with the performance demands of next-generation networking architectures.
In industrial applications, the push toward finer feature sizes, higher throughput, and more versatile material processing is expanding the role of semiconductor lasers in cutting, welding, marking, and micro-machining. The trend toward automation and precision manufacturing in sectors ranging from electronics assembly to advanced materials processing is reinforcing demand for laser sources that combine high power with tight beam control and repeatability.
Consumer electronics and automotive sensing represent additional demand vectors. The proliferation of sensing functions in vehicles, including LiDAR and advanced driver assistance systems, is creating sustained interest in laser diodes optimized for ranging and environmental perception. In consumer electronics, applications spanning AR/VR display technologies, facial recognition, and haptic feedback are contributing to demand for compact, wavelength-specific laser solutions. Medical applications, including surgical procedures, diagnostic imaging, and therapeutic devices, continue to expand as laser reliability, safety, and cost profiles improve.
Supply Chain and Cost Structure Dynamics
The economics of semiconductor laser production are being influenced by shifts in raw material availability, manufacturing localization, and the cost of compliance. As regulatory frameworks increasingly emphasize supply chain visibility and resilience, companies are re-evaluating the tradeoffs between efficiency and redundancy. Some manufacturers are diversifying sourcing strategies, qualifying alternative suppliers, or investing in more transparent documentation processes to reduce vulnerability to disruption.
Worldwide Semiconductor Military Laser Market
At the same time, the cost of achieving performance targets in specialized wavelengths and packaging formats is rising for certain segments, particularly where materials, epitaxial growth, or precision packaging require specialized capabilities. This cost pressure is reinforcing the advantage of players with established process expertise and integrated manufacturing capabilities, while also creating opportunities for companies that can deliver application-specific solutions with lower total cost of ownership through improved reliability, reduced integration complexity, or longer service life.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
The competitive environment in the semiconductor lasers market is characterized by a mix of large diversified photonics companies, focused specialists, and regional champions. Understanding the strategic positioning of these players provides insight into where differentiation is being created and how the competitive frontier is shifting.
Diversified Leaders and Systems-Level Positioning
Companies such as IPG Photonics, Coherent, TRUMPF Group, and nLIGHT occupy positions that emphasize scale, application breadth, and systems-level integration. IPG Photonics manufactures high-power fiber lasers, diode laser systems, and ultrafast laser sources for industrial semiconductor processing, material cutting, and welding. Its recent platform introductions and demonstration of Deep UV and green lasers for micro-machining reflect a strategy centered on expanding wavelength coverage and integrating laser sources into more complete solutions for precision manufacturing.
Coherent develops and supplies laser diodes, VCSELs, and semiconductor laser systems spanning datacom, industrial precision manufacturing, semiconductor capital equipment, and LiDAR applications. The company's demonstration of InP technology innovations at OFC 2026 illustrates a focus on material platform advancement and alignment with high-growth communications and networking markets. Coherent's breadth across multiple application verticals positions it to capture technology transfer opportunities and cross-sell into adjacent segments.
nLIGHT develops high-power semiconductor fiber lasers and diode laser systems for defense, advanced manufacturing, and industrial processing. Its emphasis on high-power semiconductor fiber lasers reflects a strategy of combining semiconductor efficiency with fiber delivery benefits for demanding industrial and defense applications. TRUMPF Group offers semiconductor laser systems and solutions for industrial material processing, laser welding, and cutting, leveraging its broader reputation in industrial laser systems to reinforce customer relationships and integrate laser sources into complete processing setups.
Specialists and Application-Focused Players
A second tier of competitors competes through depth in specific wavelengths, package formats, or application domains. ams-OSRAM provides edge-emitting laser diodes, VCSELs, and semiconductor laser solutions for automotive LiDAR, advanced driver assistance systems, and high-performance sensing. Its positioning reflects a focus on sensing applications where reliability, wavelength stability, and integration compatibility with automotive-grade systems are critical.
Nichia offers high-power laser diodes and semiconductor laser products for industrial, automotive, and consumer applications including AR/VR and material processing. The company's presence across both industrial and consumer segments highlights the value of wavelength expertise and manufacturing scale in serving diverse end markets. Furukawa Electric manufactures high-output DFB laser diodes and semiconductor laser chips for signal light sources and optical communications, emphasizing performance in communications applications where wavelength precision and signal integrity are paramount.
Nuvoton's recent moves into high-power violet and UV laser diodes for semiconductor packaging and lithography illustrate a strategy of targeting specific application gaps with tailored wavelength and package solutions. By introducing devices in compact CAN and TO-9 packages optimized for packaging and lithography systems, Nuvoton is building a position in an application segment where wavelength, power, and form factor must align closely with equipment design requirements.
Sheaumann Laser designs and manufactures single-mode and multimode continuous-wave diode lasers and modules for medical, industrial, defense, and space applications. Excelitas Technologies manufactures pulsed laser diodes and arrays for industrial, medical, and defense illumination and sensing applications. RPMC Lasers supplies laser diodes, pulsed lasers, and semiconductor laser modules for medical, defense, research, and industrial OEM applications. These companies illustrate how focused portfolios can create defensible positions in applications where performance consistency, qualification history, and customer support are valued as highly as raw component specifications.
Sacher Lasertechnik provides narrow-linewidth and tunable semiconductor laser systems for scientific, industrial, and quantum applications, representing a niche oriented toward precision and flexibility in demanding research and specialized industrial contexts. Hamamatsu Photonics supplies laser diodes, VCSELs, and semiconductor laser modules for scientific, industrial, and medical applications, leveraging its broader photonics expertise to serve segments that require tightly integrated component and module solutions.
Strategic Positioning and Differentiation
Across this landscape, several differentiation themes are emerging. One is wavelength and package specialization, where companies build advantage by optimizing for specific performance envelopes rather than competing broadly. A second is application co-development, where manufacturers engage closely with equipment makers and end users to shape laser specifications around real-world processing, sensing, or transmission requirements. A third is vertical integration and supply chain control, where companies reduce dependency on external suppliers for critical materials, epitaxial growth, or packaging to improve quality consistency and mitigate disruption risk.
The competitive frontier is also shaped by the tension between consolidation and specialization. Larger players may pursue acquisitions or partnerships to fill wavelength gaps, expand into adjacent application segments, or strengthen regional supply chain presence. At the same time, specialized entrants continue to find opportunities in underserved niches, particularly where emerging applications create demand for wavelengths, package formats, or reliability profiles that are not the primary focus of mainstream suppliers.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the semiconductor lasers market and create distinct commercial opportunities for participants that align their strategies with these dynamics.
Trend One: Expansion of UV and Violet Wavelength Applications
The progression of high-power violet and UV laser diodes into semiconductor packaging, maskless lithography, and precision micro-machining points to a broader trend of shorter-wavelength adoption in manufacturing and processing applications. As feature sizes continue to shrink and process requirements demand finer control, reduced thermal 영향, and improved edge quality, UV and violet sources are likely to see increased penetration in packaging, lithography, and micro-machining workflows. This trend creates opportunities for manufacturers that can deliver reliable high-power devices in compact packages, as well as for equipment makers that integrate these sources into optimized processing platforms.
A related implication is that wavelength-specific expertise will become more valuable. Companies that can combine epitaxial growth, packaging, and application engineering for UV and violet wavelengths may capture premium positioning relative to generalist suppliers.
Trend Two: Integration and Co-Development as Competitive Levers
The increasing complexity of end-use applications is elevating the importance of integration and co-development. Semiconductor lasers are increasingly deployed not as isolated components but as part of systems that combine laser sources, beam delivery, control electronics, and application-specific optics. This shift favors manufacturers that can engage early in customer design cycles, offer reference architectures, and provide support for qualification and reliability testing. It also favors equipment and system makers that can differentiate through optimized integration rather than competing solely on individual component specifications.
For commercial players, this trend suggests that value capture is moving toward solution-level positioning. Companies that can reduce integration complexity, improve system-level reliability, or accelerate time-to-qualification may gain advantage even if component-level margins face pressure.
Trend Three: Supply Chain Reconfiguration and Regionalization
Regulatory developments, geopolitical tensions, and resilience benchmarking initiatives are likely to continue driving supply chain reconfiguration. Companies may increasingly evaluate manufacturing location, supplier diversification, and documentation transparency as strategic variables rather than purely operational decisions. This trend could create opportunities for regional suppliers that can offer localized production, faster responsiveness, and alignment with customer compliance requirements.
At the same time, the cost of managing a more complex supply chain environment may increase, particularly for smaller players with limited compliance and qualification resources. This dynamic could contribute to selective consolidation or partnership activity, as companies seek to share the burden of regulatory alignment and supply chain visibility.
Risks and Uncertainties
Several uncertainties could alter the trajectory of these trends. Regulatory scope and enforcement intensity remain variable, and the full impact of procurement restrictions and supply chain visibility requirements on component pricing and market access is still unfolding. Technology substitution risk persists, particularly if alternative light sources, integrated photonic approaches, or competing wavelength strategies gain traction in key applications. Demand momentum in specific segments, such as automotive sensing or consumer electronics, may fluctuate with product cycles, economic conditions, or changes in end-user adoption patterns. Finally, concentration in certain parts of the supply chain creates exposure to disruption if key materials, processes, or manufacturing nodes encounter constraints.
Strategic Recommendations for Decision Makers
For executives navigating this market, the priority is to align strategy with the forces that are most likely to shape value creation over the next several years. The following recommendations are intended to provide a starting point for more detailed planning.
UV Lasers Market
For Manufacturers and Component Suppliers
Focus on depth in high-growth wavelength and application segments where performance requirements are tightening and differentiation is achievable. Evaluate whether your portfolio balances breadth with enough specialization to command premium positioning in priority verticals. Invest in integration support, reference designs, and co-development capabilities that reduce the friction for customers adopting your laser sources in system-level applications. Review supply chain configuration with an eye toward resilience and compliance readiness, particularly if your customer base includes segments exposed to government procurement requirements or complex qualification processes.
For Investors and Strategic Allocators
Assess opportunities based on the alignment of technology positioning with demand momentum in communications, industrial processing, sensing, and packaging applications. Differentiated wavelength expertise, application-specific packaging, and integration capabilities are likely to be more durable sources of value than commodity positioning in crowded segments. Pay attention to regulatory exposure and supply chain resilience as factors that can affect long-term viability, particularly for companies serving government-adjacent markets or reliant on concentrated sourcing. Monitor the pace of specialization versus consolidation, as both pathways can create attractive entry or exit points depending on the segment and the player's strategic posture.
For Procurement and Sourcing Leaders
Prioritize suppliers that can demonstrate not only component specifications but also application support, qualification documentation, and supply chain transparency. In an environment where regulatory alignment and resilience are increasingly scrutinized, the total cost of ownership may depend as much on integration risk, qualification speed, and continuity assurance as on unit price. Engage early with laser suppliers during equipment or system design to optimize wavelength, package, and performance tradeoffs rather than specifying components in isolation. Build multi-source strategies where feasible, particularly for mission-critical or high-volume applications, to reduce exposure to single-supplier disruption.
Closing Perspective
The semiconductor lasers market is entering a phase where growth is being reinforced by technology diversification, application expansion, and a reconfiguration of supply chain and regulatory expectations. The companies that capture the most value will be those that can combine wavelength and application expertise with integration capability, supply chain resilience, and the agility to respond to shifting regulatory and geopolitical conditions. For decision makers seeking a more granular understanding of segment-level dynamics, regional nuances, competitive benchmarks, and customized strategic pathways, a deeper examination of the full research report can provide the detailed data and structured analysis needed to inform precise action.
For detailed analysis of this topic, please visit the official page: Semiconductor Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Lifeboat Market 4.5% CAGR Outlook: How Concentration and Regional Dynamics Reshape Growth to 2032
By pmarketresearch, 2026-09-21
The Lifeboat Market: Strategic Shifts and Commercial Opportunities in a Maturing Industry
The global lifeboat market has evolved from a compliance-driven segment into a strategically significant component of marine safety infrastructure. After growing from approximately USD 170.0 million in 2020 to an estimated USD 220.0 million in 2025, the market is projected to expand at a compound annual growth rate of 4.5 percent through 2032. While the growth trajectory is steady, the real story lies in the structural shifts reshaping how lifeboats are designed, regulated, serviced, and integrated into broader vessel safety systems. For executives, investors, and operations leaders, understanding these dynamics is no longer optional; it is a prerequisite for making informed capital allocation, procurement, and product development decisions.
At a high level, the market is characterized by concentrated demand, increasingly stringent safety standards, and a growing emphasis on reliability over nominal compliance. The revenue base is anchored by lifeboat equipment itself, with passenger transportation representing the dominant end-use context. Regionally, demand is distributed across established maritime hubs and emerging safety-conscious markets, reflecting both regulatory maturity and varying fleet modernization cycles. What matters most, however, is not the headline figures alone, but the way these figures are being reshaped by technology, regulation, and operational expectations.
Core Challenges at the Current Inflection Point
The industry is navigating a set of overlapping pressures that are redefining competitive advantage and operational risk.
- Regulatory tightening around safety performance. Recent amendments to release mechanism standards and operational speed requirements are forcing manufacturers and operators to revalidate existing designs. Compliance is no longer a checkbox exercise; it is becoming a continuous validation challenge that affects design architecture, service protocols, and liability exposure.
- Performance validation under real-world conditions. Independent testing has raised concerns about stability and flooding risks in certain configurations when lifeboats are not fully loaded or are occupied under specific seating arrangements. This creates a broader market implication: design claims must be supported by reproducible testing, and procurement teams are increasingly scrutinizing evidence beyond baseline certification.
- Service and maintenance complexity. Guidance emphasizing manufacturer-certified personnel for the examination and operational testing of launching appliances and release gear is raising the bar for after-sales support. The market is shifting toward controlled service ecosystems, which affects cost structures, supplier relationships, and the economics of fleet maintenance over a vessel’s lifecycle.
Together, these challenges point to a market that is maturing rapidly. The winners will be those who can translate regulatory and performance pressure into product reliability, service competence, and transparent engineering evidence.
Key Drivers Reshaping the Lifeboat Market
The market’s direction is being shaped by four interconnected drivers. Each one carries implications for product strategy, procurement planning, and investment timing.
Technology Innovation and Design Evolution
Engineering improvements are steadily raising the bar for launch reliability, Structural resilience, and operator control. Advances in release mechanisms, hull configurations, and integration with davit systems are reducing failure modes that historically complicated launch operations. Equally important, the industry is seeing a stronger focus on designs that perform consistently across load conditions rather than only meeting minimum test scenarios. This matters because lifeboat performance is increasingly judged on operational reliability, not just certification compliance.
Regulatory and Standards Environment
Regulatory momentum is accelerating. New requirements addressing release mechanisms and lowering operational speeds are prompting redesigns and re-verification campaigns. In parallel, stronger expectations around maintenance and servicing are formalizing who can inspect and test launching appliances and release gear, and under what conditions. These changes are raising the importance of traceable service records, manufacturer-aligned maintenance pathways, and documented component integrity. The regulatory environment is effectively tightening both the design and service sides of the market.
Demand-Side Behavior and Fleet Expectations
Operators are increasingly treating lifeboats as part of an integrated safety system rather than isolated equipment. This is driven by a broader mindset in which passenger transport operators, offshore operators, and naval customers want assurance that evacuation assets will perform under stress, with predictable handling and reduced risk of flooding or instability. Procurement decisions are therefore placing greater weight on demonstrated performance, support coverage, and the ability to align lifeboat selection with vessel-specific operating profiles. The result is a more discerning buyer environment in which reputation for reliability and evidence of testing can influence selection as much as price.
Cost Structure and Service Economics
Lifecycle economics are becoming more important as service requirements become more specialized. When maintenance and testing must be performed by certified personnel or through authorized service pathways, operators face stronger incentives to plan for total cost of ownership rather than purchase price alone. For manufacturers, this creates opportunities to build value around service contracts, parts availability, and predictable maintenance schedules, while also increasing the importance of supply chain reliability for critical components. Cost structures are shifting from a one-time equipment transaction toward a longer-term service relationship.
Competitive Landscape and Leading Strategies
The market remains heavily concentrated, with a small group of established players holding a substantial share of revenue and technical influence. This concentration reflects the high barriers associated with certification, engineering expertise, service networks, and long-standing customer relationships in maritime and naval segments.
Strategic Positioning of Key Players
- VIKING Life-Saving Equipment A/S has built a strong reputation around integrated survival solutions, including free-fall lifeboats, fast rescue boats, and davit systems suited to merchant and offshore vessels. Its positioning emphasizes engineered reliability and the ability to deliver coordinated equipment packages rather than standalone products.
- Survitec Group Limited brings breadth across survival craft technology, including lifeboats, liferafts, and evacuation systems. Its strategic value lies in offering a wider safety ecosystem, which can simplify procurement and support for customers seeking multiple evacuation assets from a coordinated supplier base.
- Fassmer GmbH & Co. KG is recognized for lifeboats, rescue boats, and life-saving equipment tailored to cruise, ferry, and offshore applications. Its approach often centers on application-specific engineering and long-cycle project execution, with recent activity reinforcing its role in specialized training and operational boat programs.
- Zodiac Nautic Group contributes expertise in inflatable and rigid-inflatable boats alongside life rafts and safety equipment. Its competitive advantage is rooted in adaptable hull technologies and a strong association with versatile watercraft platforms that can support different operational needs.
- Ningbo New Marine Lifesaving Equipment Co., Ltd. participates through fast rescue boats, lifeboats, davits, and launching appliances, reflecting the growing presence of capable manufacturers in the broader marine safety supply chain. Its relevance lies in expanding manufacturing capacity and offering competitive equipment solutions across launch and support components.
Market Evolution and Strategic Trends
Several patterns are becoming visible in how the competitive landscape is evolving.
- Consolidation of service value. As maintenance and testing expectations tighten, suppliers that can offer credible, manufacturer-aligned service coverage are gaining strategic importance. The market is increasingly rewarding integrated product-and-service propositions over fragmented equipment sales.
- Differentiation through evidence and engineering. In an environment where performance questions are being raised through testing and regulatory scrutiny, transparency in design rationale, validation data, and service qualifications becomes a competitive asset.Providers that can demonstrate robust engineering support are better positioned to win demanding contracts.
- Selective new entry and regional expansion. While the top tier remains concentrated, broader manufacturing capacity and regional supply options are expanding. Newer or regional participants can compete by addressing specific cost, lead-time, or application needs, but they must also meet rising expectations for certification, service competence, and long-term support reliability.
- Project-driven cycles and institutional demand. Award activity in specialized segments, such as training boat programs, illustrates how institutional demand can create targeted growth opportunities. These projects often require strong execution credibility and can reinforce a supplier’s standing in demanding markets.
For buyers and investors, the practical implication is that competitive advantage is shifting from product presence alone to a broader combination of engineering credibility, service readiness, and the ability to reduce operational risk across the equipment lifecycle.
Future Trends and Commercial Implications for 2026–2032
Looking ahead, the market is likely to be shaped by a small number of high-impact trends. Each trend carries both opportunity and uncertainty.
Trend 1: Performance Standards Will Drive Redesign and Revalidation Activity
Regulatory amendments focused on release mechanisms and operational speed, combined with testing findings related to stability and flooding risk in certain conditions, are likely to sustain a wave of design refinement and verification work. This creates near-term demand for engineering support, testing coordination, and product updates, while also encouraging longer-term investment in more robust launch and stability characteristics. Commercially, this favors organizations that can respond quickly with credible engineering changes and clear documentation.
Trend 2: Service and Maintenance Will Become a Central Commercial Battleground
As servicing expectations increasingly emphasize certified personnel and manufacturer-aligned examination and testing, the after-sales segment will grow in strategic importance. Operators will look for predictable maintenance pathways, component availability, and support coverage that reduces downtime and compliance risk. For manufacturers and service providers, this means revenue and customer loyalty will depend more on lifecycle support quality than on initial equipment sales alone.
Worldwide Wafer Boat Market
Trend 3: Procurement Will Shift Toward Integrated Safety Assurance
Buyers are expected to place greater value on coordinated solutions that combine lifeboats, launching appliances, and related evacuation elements with consistent support standards. The trend is toward fewer, more trusted procurement relationships for safety-critical assets, especially where operators seek to simplify accountability and reduce integration risk. This benefits suppliers that can offer end-to-end assurance and penalizes those that are seen as strong on product but weaker on systemic support.
Floating Dock Market
Risks and Uncertainties
Despite the constructive outlook, several uncertainties deserve attention.
- Regulatory interpretation and enforcement may vary by region and flag state, creating uneven compliance timelines and different speed of adoption across markets.
- Testing-related scrutiny could accelerate redesign costs for certain product lines and create short-term margin pressure while validation cycles are completed.
- Service qualification requirements may constrain the supply base if certified capacity does not expand in step with demand, potentially increasing turnaround times and support costs.
- Demand cyclicality in shipping, offshore, and naval programs can influence the pace of new equipment orders, even as retrofit and service demand remains more resilient.
Actionable Guidance for Decision-Makers
The market’s next phase will reward organizations that align strategy with the direction of regulation, performance expectations, and service economics. The following priorities are most relevant for different stakeholder groups.
PW Consulting Automotive & Machinery Research Center
For Manufacturers and Equipment Suppliers
- Strengthen engineering evidence packages that address stability, release behavior, and performance across load conditions. Transparent validation support is becoming a differentiator in competitive procurements.
- Invest in certified service capacity and clear maintenance pathways. Lifecycle support is increasingly a commercial prerequisite, not an optional add-on.
- Prepare for redesign and revalidation workloads triggered by updated release mechanism and speed requirements. Early readiness can convert regulatory pressure into share gains.
For Investors and Capital Allocators
- Focus on companies with credible service ecosystems and strong engineering reputations, since lifecycle support and compliance readiness are becoming central to long-term value creation.
- Monitor project-driven demand signals, especially in specialized training and institutional programs, as indicators of execution capability and market access.
- Assess exposure to redesign costs and certification cycles, which can affect short-term margins even when medium-term demand remains healthy.
For Procurement Teams and Vessel Operators
- Evaluate total cost of ownership with greater weight on service coverage, testing qualifications, and parts availability rather than purchase price alone.
- Request evidence of performance validation under conditions relevant to your operating profile, particularly where stability and flooding risk have become points of scrutiny.
- Simplify accountability by favoring suppliers that can support integrated evacuation systems and provide consistent maintenance standards across equipment types.
Effective decisions in this market require more than headline market size or broad growth estimates. Segmentation behavior, regional demand patterns, pricing dynamics, service economics, and company-level execution all influence who captures value as the market matures. Detailed breakdowns of these variables can help translate the strategic directions outlined here into procurement planning, product roadmap choices, and investment screening with greater precision. For decision-makers seeking a sharper view of market segments, competitive positioning, and forward demand scenarios, the full research report offers a more granular basis for action.
For detailed analysis of this topic, please visit the official page: Lifeboat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
FCC Catalyst Market: Why Top Players’ 5.5% CAGR Strategy Reveals New Growth Paths
By pmarketresearch, 2026-09-21
FCC Catalyst Market: Strategic Trends and Commercial Opportunities in a Transforming Refining Landscape
The global Fluid Catalytic Cracking (FCC) catalyst market has entered a phase of measured but purposeful growth, driven by a complex interplay of refinery economics, feedstock evolution, and tightening environmental standards. From a base of approximately $2.45 billion in 2020, the market expanded to around $3.0 billion by 2025, reflecting an average compound annual growth rate of roughly 5.5 percent over the historical period. This trajectory is expected to continue through 2032, with the market crossing the $4.3 billion threshold by the end of the forecast horizon. The growth is not uniform, nor is it guaranteed by volume alone. It is being shaped by strategic decisions around catalyst selection, unit configuration, and the shifting economics of heavy feedstock conversion.
PW Consulting Chemical & Energy Research Center
For decision-makers operating in or adjacent to the refining and petrochemical value chains, the FCC catalyst segment represents both a critical operational input and a strategic lever. Catalyst performance directly influences yield structures, unit reliability, and compliance costs. At the same time, the market's underlying dynamics are evolving rapidly, introducing new risks and opportunities that demand a clear-eyed view of where the industry is headed.
The current market environment is characterized by three interconnected challenges that are reshaping how refiners and catalyst suppliers approach FCC operations. First, feedstock volatility and the increasing use of opportunity crudes are testing the limits of conventional catalyst formulations. As refineries pursue margin advantages by processing heavier, more complex feeds, they encounter contaminants such as iron that can degrade catalyst activity and accelerate deactivation. This reality is pushing the industry toward mitigation technologies and more resilient catalyst designs, but it also increases the operational and economic stakes of catalyst selection.
Second, the regulatory landscape is tightening at a pace that outstrips incremental process adjustments. Environmental standards are increasingly focused on sulfur reduction, product quality, and the overall emissions footprint of refining operations. These requirements are not merely compliance checkboxes; they are changing the economics of FCC unit design and catalyst performance optimization. Refiners are being compelled to adopt advanced catalysts and additive packages that can deliver cleaner product slates without sacrificing conversion efficiency or unit stability. The cost of non-compliance, including operational disruptions and potential penalties, is becoming a material factor in catalyst investment decisions.
Third, the end-of-life management of spent catalysts is emerging as a significant cost and sustainability pressure point. Landfilling restrictions, disposal fees, and rising environmental liabilities are adding to the total cost of ownership for FCC catalysts. In several regions, the disposal cost for spent catalyst has climbed substantially, turning what was once a backward-looking operational issue into a forward-looking strategic concern. Refiners are increasingly recognizing that catalyst lifecycle economics, including regeneration, recycling, and disposal, must be integrated into unit planning and vendor selection.
Technology Innovation as a Competitive Imperative
Technological advancement is no longer a nice-to-have in the FCC catalyst market; it is a core determinant of unit profitability and strategic flexibility. Recent product launches illustrate how suppliers are responding to the dual pressures of feedstock complexity and product quality requirements. One notable example is the introduction of a catalyst technology designed to address iron poisoning, a growing challenge as refiners process iron-rich opportunity crudes. Commercial trials have demonstrated significant improvements in accessibility and the ability to handle heavier, more problematic feedstocks without compromising unit performance. This type of innovation directly attacks a key operational risk, reducing unplanned downtime and extending effective catalyst life.
At the same time, other developments are targeting the yield side of the equation. New catalyst platforms are being engineered to maximize high-octane gasoline blending stocks from gasoil and mild resid feeds, aligning FCC output with downstream fuel specification demands. These solutions reflect a broader trend: catalyst suppliers are moving beyond generic performance improvements to deliver tailored responses to specific refinery configurations, feed characteristics, and product slate objectives. The competitive advantage increasingly lies in the ability to match catalyst chemistry with the precise operational and regulatory context of the end user.
FCC Catalyst Additive; FCC Catalyst and Additives Market
Regulatory and Environmental Pressures Reshaping Demand
Policy and regulatory developments are acting as both a constraint and a catalyst for innovation. Updated testing and evaluation standards are formalizing how catalyst activity and selectivity are measured, creating a more rigorous framework for performance comparison and compliance. These standards matter because they influence procurement decisions, unit optimization strategies, and the credibility of supplier claims. In parallel, broader environmental regulations are pushing refiners toward catalysts and processes that can more effectively convert heavy feeds into cleaner products, reducing sulfur and other emissions-linked components.
The regulatory trajectory also intersects with feedstock economics. As environmental rules become more stringent, the economic case for processing heavy feedstocks depends increasingly on the ability to manage contaminants, maintain catalyst activity, and achieve target product specifications. This creates a feedback loop: regulation raises the bar for performance, which in turn incentivizes technology development and more sophisticated catalyst selection. For refiners, the implication is clear. Compliance is not a separate function from catalyst strategy; it is a central input into how FCC units are configured, operated, and upgraded.
Feedstock Economics and Cost Structure Dynamics
The cost structure of FCC operations is being reshaped by both feedstock trends and catalyst procurement economics. Refiners are navigating a landscape where crude differentials, opportunity crude availability, and contaminant levels can shift rapidly, affecting unit behavior and catalyst consumption rates. At the same time, the average cost of catalyst material remains a significant line item in refinery operating budgets. Optimized catalyst selection and usage patterns can deliver substantial annual savings per unit, underscoring the fact that catalyst economics are not just about price per ton but about total lifecycle value.
Disposal and recycling costs further complicate the picture. In markets where spent catalyst landfilling has become more expensive, the total cost of ownership rises, and the economic incentive to extend catalyst life or improve regeneration and recycling pathways becomes stronger. This is pushing attention toward solutions that reduce waste generation, improve metal trapping efficiency, and support more sustainable end-of-life options. For suppliers, it opens a strategic avenue: value propositions that combine performance, longevity, and lifecycle cost reduction are increasingly compelling in a cost-conscious environment.
Competitive Landscape and Strategic Positioning
The FCC catalyst market remains concentrated, with a small group of leading players accounting for a dominant share of revenue and technology offerings. This concentration reflects the high barriers to entry associated with catalyst chemistry, process integration expertise, and long-term refinery relationships. The competitive field includes globally recognized specialists in FCC catalysis, major chemical and catalyst companies with broad refinery portfolios, and integrated producers with strong regional presence and supply chain advantages.
Leading suppliers are differentiating themselves along several axes. Some are emphasizing proprietary catalyst platforms that address specific operational challenges, such as heavy feed processing, iron poisoning mitigation, or high-octane gasoline maximization. Others are leveraging integrated technology offerings that combine catalyst products with process licensing, unit optimization services, and post-treatment solutions. This bundling reflects a strategic shift from product-centric competition to solution-centric engagement, where the value delivered is tied to overall refinery economics rather than catalyst performance in isolation.
Regional dynamics also shape competitive positioning. Suppliers with strong local presence, technical support networks, and understanding of regional feedstock and regulatory contexts can gain advantages in key markets. At the same time, integrated producers participating in national refining ecosystems often benefit from coordinated supply chains and captive demand, allowing them to scale rapidly and influence regional market structures. The result is a landscape where global technology leadership and regional execution capabilities both matter, and where competitive success depends on aligning product strategy with local market realities.
Recent developments underscore how quickly the competitive dynamics can shift. New product introductions targeting iron-rich feedstocks and high-octane gasoline production illustrate the pace of innovation and the willingness of established players to invest in differentiated solutions. These launches are not incremental; they respond directly to operational pain points and regulatory pressures that are reshaping refinery priorities. In this environment, incumbents that can translate technical capability into measurable unit-level benefits are well positioned, while slower-moving competitors risk erosion in segments where performance and reliability are becoming increasingly decisive.
Market Evolution: Consolidation Pressures and Emerging Entrants
The market's concentration profile suggests continued pressure toward consolidation among smaller or less differentiated players, particularly in segments where feedstock flexibility, environmental compliance, and lifecycle cost management are becoming table stakes. Suppliers that cannot articulate a clear technical or economic advantage may find it harder to compete for specification-driven contracts, especially as refiners become more sophisticated in evaluating total cost of ownership and performance risk.
Continuous Catalyst Regeneration (CCR) Catalyst Market
At the same time, there are pathways for differentiation that do not require blanket market leadership. Niche expertise in specific catalyst functions, regional service excellence, or innovative approaches to spent catalyst management can create defensible positions. New entrants and smaller specialists may find opportunity by targeting particular pain points, such as contaminant mitigation, additive optimization, or sustainability-linked lifecycle services, rather than attempting to compete head-to-head across the full product spectrum. The overall trend is toward a more segmented competitive environment in which broad scale and deep specialization coexist, and where partnerships, technical service, and integrated offerings increasingly determine market outcomes.
Near-Term Trends and Strategic Implications
Looking ahead over the next three to five years, several trends are likely to define the FCC catalyst market's trajectory. First, catalyst formulations that can reliably handle heavier, more contaminated feeds while maintaining activity and selectivity will become increasingly central to procurement decisions. Iron poisoning mitigation, metal trapping efficiency, and robust performance across feed variations will move from specialized concerns to mainstream requirements as opportunity crude usage persists and refinery margin strategies continue to favor flexible feedstock handling.
Second, the link between catalyst selection and environmental compliance will tighten further. As product specifications and emissions expectations evolve, catalysts and additive packages that support sulfur reduction, cleaner product slates, and efficient conversion of heavy feeds will command greater attention. This trend favors suppliers who can demonstrate measurable compliance benefits and help refiners navigate an increasingly complex regulatory environment without sacrificing unit economics.
Third, lifecycle economics will gain prominence in catalyst decision-making. Disposal costs, recycling pathways, and the total cost of catalyst ownership will be evaluated more holistically, especially in regions where landfilling expenses are rising. Solutions that extend catalyst life, improve regeneration outcomes, or reduce waste volumes will have a stronger commercial case. This shift creates opportunities for suppliers and service providers who can integrate performance, sustainability, and cost management into a coherent value proposition.
These trends translate into tangible commercial opportunities. For catalyst manufacturers and technology licensors, there is room to grow by targeting refineries that are reconfiguring units for heavier feeds or facing specific contaminant challenges. Differentiated technologies that deliver clear operational improvements can support premium positioning and stronger customer retention. For investors, the market's steady growth profile and the centrality of catalysts to refinery economics suggest durable demand, but success will depend on identifying players with genuine technical differentiation and the ability to execute in a concentrated, relationship-driven market. For refiners and procurement teams, the opportunity lies in moving beyond unit price to evaluate total lifecycle value, contaminant handling, compliance support, and service capabilities when selecting catalyst partners.
Risks and uncertainties remain. Feedstock availability and quality can shift quickly, altering the relative attractiveness of different catalyst strategies. Regulatory timelines and enforcement intensity may vary by region, creating uneven demand signals. Economic cycles, refining margin compression, and capital expenditure constraints can delay unit upgrades or catalyst transitions. In addition, the concentration of the market means that supply disruptions or strategic moves by a small number of key players can have outsized effects on pricing and availability. Decision-makers need to monitor these variables closely and maintain flexibility in catalyst strategy and supplier relationships.
Strategic Recommendations for Decision-Makers
For manufacturers and technology suppliers, the priority is to align innovation with the operational realities that refiners face today. This means investing in catalyst capabilities that address iron poisoning, heavy feed conversion, and product quality targets, while also building the service and technical support infrastructure needed to prove value in real-world units. Suppliers should also consider how lifecycle economics, including disposal and recycling considerations, can be integrated into their offerings to strengthen customer partnerships and differentiate from commodity-focused competitors.
For investors and strategic financiers, the market offers a growth profile supported by regulatory pressure, feedstock complexity, and the ongoing need for refinery yield optimization. The key diligence question is differentiation: which companies have proprietary technologies, credible performance data, and the service capacity to capture value in a concentrated market? Investment theses should account for regional demand patterns, the pace of regulatory change, and the extent to which a player's portfolio is tied to specific feedstock or product trends that may evolve over time.
For refiners, procurement leaders, and operations teams, the strategic imperative is to treat catalyst selection as a unit-level economic decision rather than a routine procurement exercise. Evaluating candidates through the lens of total cost of ownership, contaminant handling, compliance support, and lifecycle services can reveal opportunities to reduce operating costs and improve unit reliability. Building vendor relationships that include technical collaboration, performance monitoring, and continuous optimization can help refineries adapt more quickly to feedstock shifts and regulatory changes.
The breadth of factors shaping the FCC catalyst market makes it difficult to navigate with generic assumptions or high-level market summaries alone. Feedstock strategies, regulatory trajectories, catalyst chemistry, and lifecycle economics all interact in ways that vary by refinery configuration, region, and operational priorities. Detailed segmentation data, unit-level cost modeling, and tailored scenario analysis can help decision-makers translate broad trends into specific actions, whether that involves choosing a catalyst platform, prioritizing investment in mitigation technology, or evaluating supplier partnerships. For organizations seeking to move from market awareness to concrete planning, deeper research and customized analysis can provide the granularity needed to align catalyst strategy with commercial objectives and operational risk tolerance.
For detailed analysis of this topic, please visit the official page: FCC Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com