

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Intermittent Catheters Market Beyond 5.77% CAGR: Coating & Home Care Surge

Intermittent Catheters Market: Strategic Trends and Commercial Opportunities Through 2032
The global intermittent catheters market is navigating a period of structural transformation. Moving from a base of approximately 210.0 million USD in 2025, the market is projected to expand at a compound annual growth rate of 5.77 percent across the 2026-2032 forecast horizon, ultimately approaching 306.64 million USD by 2032. This trajectory is not simply a function of demographic tailwinds. It reflects a convergence of reimbursement restructuring, technological breakthroughs in coating and device architecture, and a sustained shift in care delivery from institutional settings to home and community-based environments. For executives, investors, and procurement leaders, the critical question is no longer whether the market will grow, but how value will be redistributed as the competitive and regulatory landscape matures.
Historical data from 2020 through 2025 shows a market that has consistently expanded, recovering from modest post-pandemic normalization and accelerating through 2023-2025 as hospitals and home care providers recalibrated supply chains and patient management protocols. The forward-looking numbers indicate a step-up in growth momentum beginning around 2027, suggesting that late-cycle innovation adoption and reimbursement clarity will begin to compound. This blog post examines the forces shaping that trajectory, the competitive positions that will define market leadership, and the strategic moves that will separate winners from laggards in the next five years.
Market Landscape and Core Challenges
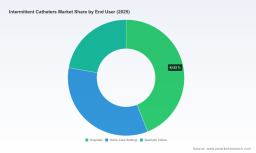
At a macro level, the intermittent catheters market operates with a moderately concentrated structure. The top three players command roughly 42.0 percent of total revenue, while the top five control approximately 52.0 percent. This level of concentration signals a market where scale, reimbursement navigation, and clinician trust matter significantly, but where there remains ample room for specialized differentiation and regional or application-focused entrants. The revenue base is currently split across coated and uncoated product lines, with coated technologies commanding a larger share of the market. From an application perspective, urinary incontinence, spinal cord injury, urinary retention, and broader urological management collectively drive demand, each requiring distinct product performance characteristics and user-experience considerations. The end-user landscape spans hospitals, home care settings, and specialty clinics, with institutional volumes remaining substantial but home care and specialty channels gaining relative weight as chronic bladder management shifts toward decentralized care models.
Despite the positive growth trajectory, the industry faces three interrelated challenges that will determine which companies capture disproportionate value.
The first challenge centers on reimbursement architecture and coding transitions. The introduction of new HCPCS codes A4295, A4296, and A4297 for hydrophilic intermittent catheters, effective January 1, 2026, requires suppliers to discontinue legacy codes A4351, A4352, and A4353 for hydrophilic products. This is not merely an administrative adjustment. It reshapes formulary eligibility, prior authorization workflows, and patient access pathways. Companies that have historically relied on broad-coded billing structures must now demonstrate clinical differentiation and cost-effectiveness within narrower reimbursement categories, or risk margin compression as payers scrutinize claim patterns under the new framework.
The second challenge is the tension between user adherence and product ergonomics. Intermittent catheterization is a routine that patients perform independently, often multiple times per day. Friction, discomfort, infection anxiety, and the psychological burden of self-catheterization directly influence compliance. Products that reduce insertion resistance, minimize mess, and support discreet use consistently outperform legacy designs in real-world retention metrics. The market will increasingly reward designs that align with daily-life constraints rather than clinical specifications alone.
The third challenge is supply chain resilience and input cost volatility. Catheter manufacturing depends on specialized polymers, coating chemistries, and precision extrusion processes. Disruptions in raw material availability, regulatory scrutiny of biocompatibility, and the cost of quality assurance testing can compress margins for manufacturers that lack scale flexibility or diversified sourcing. As coated and closed-system designs become more prevalent, the cost profile of production shifts, creating a competitive divide between companies that can amortize advanced manufacturing investments and those that operate at narrower throughput windows.
Key Drivers of Market Evolution
Several converging forces are shaping the trajectory of the intermittent catheters market. Understanding these drivers is essential for anticipating where demand will intensify, where margins will shift, and which product architectures will define the next cycle.
Technological Innovation and Material Science
Coating technology remains the central battleground for product differentiation. Hydrophilic coatings reduce friction during insertion, lower the risk of urethral trauma, and improve patient comfort, which directly supports adherence in chronic use cases. The market has moved beyond simple lubrication toward engineered coatings that balance durability, glide performance, and compatibility with single-use disposal requirements. For coated intermittent catheters, the value proposition is increasingly tied to clinical outcomes and user retention rather than novelty. Companies that can demonstrate consistent coating performance across temperature ranges, humidity variations, and shelf-life constraints will secure stronger formulary positions and clinician recommendation patterns.
At the device level, the emergence of reusable intermittent catheter systems marks a notable inflection point. In May 2026, the FDA granted de novo authorization for a reusable intermittent catheter system, establishing a new device classification category for reusable intermittent technology. This decision signals a regulatory opening for architectures that reduce waste, lower per-use costs over time, and appeal to environmentally conscious procurement standards. While adoption will depend on cleaning protocols, patient education, and reimbursement alignment, the authorization creates a pathway for a product archetype that was previously constrained by classification uncertainty. Manufacturers that can pair reusable platforms with robust sterilization, tracking, and durability validation will be positioned to contest share in segments where total cost of ownership matters more than upfront unit price.
Policy and Regulatory Environment
Regulatory and reimbursement dynamics are actively reconfiguring market access. The 2026 HCPCS code restructuring for hydrophilic intermittent catheters is a structural change rather than a transitional adjustment. By requiring suppliers to transition away from legacy codes, the policy environment is pushing the market toward greater specificity in product coding. This specificity can benefit manufacturers with clearly differentiated hydrophilic portfolios, but it also raises the bar for documentation, claim accuracy, and payer communication. Suppliers that invest early in coding transition support, clinician education, and reimbursement navigation tools will reduce friction for customers and protect volume during the code sunset period.
Beyond coding, the broader regulatory posture around single-use medical devices, biocompatibility testing, and environmental footprint is tightening. Manufacturers must balance performance claims with documented safety profiles and, increasingly, with sustainability considerations that influence procurement decisions in health systems and DME suppliers. The FDA classification developments around reusable systems further illustrate how regulatory clarity can unlock new commercial categories that were previously constrained by ambiguity. Companies that treat regulatory engagement as a strategic capability, rather than a compliance function, will be faster to capture emerging opportunities.
Demand-Side Shifts in Care Delivery
Care delivery is steadily moving from inpatient and clinic-heavy models toward home-based and community-managed bladder care. This shift is driven by cost pressures on hospitals, patient preferences for convenience and autonomy, and the growing availability of user-friendly catheter designs that support safe self-management. Home care settings and specialty clinics are gaining relative importance as end-user channels because they align with the chronic, recurring nature of intermittent catheterization. In these settings, product attributes such as compactness, ease of handling, discreet packaging, and clear user instructions can be as commercially decisive as raw clinical performance.
Patient behavior is also becoming more informed and more demanding. Users are comparing products not only on clinical outcomes but on everyday practicality: how quickly a catheter can be prepared, whether it requires manual lubrication, how it fits into work, travel, and social routines, and how the disposal experience aligns with environmental preferences. This demand-side evolution favors manufacturers that design for the full user journey rather than for the moment of insertion alone.
PW Consulting
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by the growing share of coated and closed-system products, the complexity of coating supply chains, and the financial implications of single-use versus reusable architectures. Manufacturers that can secure reliable access to specialty polymers and coating inputs, while maintaining consistent quality across production runs, will hold a structural advantage. At the same time, the economics of reusable systems introduce a different cost logic: higher initial engineering and validation investment, offset by lower recurring material consumption and waste handling costs over the device lifecycle. This divergence creates distinct strategic paths. Some companies will compete on volume, consistency, and reimbursement alignment in single-use coated lines. Others will pursue total-cost-of-ownership positioning through reusable or hybrid platforms. Both paths can be viable, but they require different capabilities and partner ecosystems.
Competitive Landscape and Leading Strategies
The market is populated by a mix of globally scaled urology and continence care players and specialized manufacturers that compete on design, coating technology, and targeted user segments. Understanding how these companies position themselves clarifies where competitive advantage is being built and where vulnerabilities may emerge.
Coloplast has built a strong reputation around hydrophilic-coated lines such as SpeediCath and Self-Cath, emphasizing no-touch insertion and user-friendly designs for male, female, and pediatric patients. This positioning aligns closely with the market's shift toward adherence, ease of use, and reduced handling complexity. By centering product design around the patient experience and reducing contamination risk through no-touch architectures, Coloplast has reinforced clinician trust and user familiarity, which are critical in a category where repeat purchases and recommendation patterns matter.
Medical Catheters Market
Becton Dickinson, through its Bard portfolio, offers a broad range of intermittent catheters including uncoated, hydrophilic, and closed-system options for urological care. This breadth allows BD to serve diverse clinical and reimbursement scenarios, from cost-sensitive settings to cases where closed-system designs are preferred for infection-control reasons. The strategic advantage here is optionality: the ability to match product architecture to specific procurement and clinical requirements across multiple end-user channels.
Hollister Incorporated provides a full line of intermittent catheters tailored for continence care and bladder management. Its positioning reflects deep familiarity with the continence care ecosystem and a focus on products that integrate into broader bladder management routines. In markets where continuity of supply, clinician relationships, and patient education support drive loyalty, this holistic approach can strengthen retention and reduce switching.
B. Braun Melsungen AG supplies urinary catheters, including intermittent types, with an emphasis on quality and safety. This positioning suits healthcare environments where procedural reliability and compliance documentation are paramount. By leaning into quality assurance and safety credentials, B. Braun reinforces its eligibility in institutional procurement where risk management and standards adherence influence purchasing decisions.
ConvaTec Group Plc's GentleCath line, including Glide and advanced coating technologies, underscores the industry's focus on reducing insertion friction and improving user comfort. Advanced coating claims are increasingly scrutinized, so companies that can support performance with consistent manufacturing and credible user feedback are better positioned to defend premium positioning within hydrophilic segments.
Teleflex Incorporated manufactures Rüsch Tiemann and other uncoated and hydrophilic intermittent catheters, including options for difficult catheterization cases. This focus on challenging clinical scenarios creates a niche advantage: products that address specific anatomical or procedural difficulties can secure strong clinician endorsement in segments where standard designs are insufficient.
Medtronic maintains a portfolio of intermittent catheters supporting urological applications. Its presence illustrates how broader medical technology companies can leverage existing urology relationships and distribution networks to sustain intermittent catheter sales without necessarily leading with category-specific innovation. The strategic value lies in cross-selling and channel leverage rather than standalone product differentiation.
Wellspect HealthCare specializes in hydrophilic and closed-system intermittent catheters. This specialization allows the company to concentrate resources on coating performance, closed-system convenience, and the user groups that value those features most. In a market where hydrophilic and closed-system designs are gaining relative importance, focused specialization can be a strong response to the reimbursement and user-experience shifts described earlier.
Cure Medical produces eco-friendly, single-use intermittent catheters with hydrophilic and uncoated options. This positioning ties product design to environmental considerations, an increasingly relevant factor in procurement decisions and patient preference. Sustainability messaging is most effective when paired with genuine material choices and disposal outcomes rather than symbolic claims, and manufacturers that can substantiate eco-friendly positioning will find receptive audiences among health systems and DME suppliers facing their own sustainability mandates.
CompactCath, Inc. develops compact, pre-lubricated, no-touch intermittent catheters designed for active and discreet use. This is a clear example of design-led differentiation aimed at lifestyle compatibility. For users who prioritize portability, privacy, and minimal routine disruption, compact and pre-lubricated architectures can drive strong brand loyalty even in a market where clinical performance requirements are broadly met by multiple competitors.
BEVER Medical operates as an OEM and direct manufacturer of hydrophilic intermittent catheters and suction catheters. This model highlights the growing role of manufacturing partners and private-label supply in the market. Companies that can deliver consistent coating quality, scalable production, and flexible specification support enable brand owners to expand portfolios without bearing full manufacturing capital intensity. The OEM channel is particularly relevant as coding transitions and reimbursement specificity increase the need for tailored product configurations and documentation support.
Market Structure Trajectories
The competitive landscape is evolving along several axes. First, there is a continuing pull toward integration among larger players who can combine coated product lines, closed-system options, reimbursement navigation, and broad distribution. Scale helps in managing coding transitions, maintaining consistent supply, and funding coating and design innovation. Second, there is parallel fragmentation through specialized entrants that compete on compactness, reusable architectures, eco-friendly positioning, or difficult-case clinical performance. These entrants often grow by serving underserved user needs or by partnering with established distributors and OEMs. Third, regulatory developments such as the reusable device classification and hydrophilic coding changes are likely to accelerate portfolio rationalization. Companies with products that do not fit cleanly into new coding or classification structures may face pressure to reposition, license, or divest. The net effect is a market where strategic clarity about which segment to serve, and with which product architecture, becomes more important than broad coverage alone.
Future Trends and Commercial Opportunities
Trend 1: Hydrophilic and Coated Platforms Will Anchor Premium Segments
Over the next three to five years, hydrophilic and advanced coated intermittent catheters are likely to hold an expanding share of revenue, particularly in home care and specialty clinic channels where user comfort and adherence drive repeat usage. The commercial opportunity lies not only in coating performance but in the surrounding ecosystem: reimbursement documentation that aligns with the new hydrophilic-specific codes, clinician and patient education that supports correct use, and packaging and disposal solutions that reduce friction in daily routines. Companies that treat coating as one component of a broader user-retention strategy will capture more durable share than those that compete on glide claims alone.
Microcatheter Market
Trend 2: Reusable and Hybrid Architectures Will Gain a Footing Where Total Cost Matters
The FDA de novo authorization for a reusable intermittent catheter system opens a pathway for architectures that can demonstrate durability, safe reprocessing, and favorable total-cost economics. The near-term opportunity is strongest in settings where procurement evaluates lifecycle cost, where environmental mandates influence purchasing, and where patient education and follow-up can be structured to support safe reuse. The uncertainty is adoption speed. Cleaning behavior, sterilization confidence, and reimbursement parity for reusable platforms will determine whether this trend remains niche or expands into a meaningful alternative within specific user segments. Manufacturers that invest early in validation, user onboarding, and payer dialogue will be better positioned to shape the category rather than react to it.
Trend 3: Reimbursement Navigation Will Become a Core Commercial Capability
With HCPCS code changes effective in 2026 and intermittent urinary catheters reimbursed as DME under updated coding structures, the ability to help suppliers, clinicians, and patients navigate reimbursement will increasingly differentiate commercial performance. The opportunity is to reduce claim friction through clear coding guidance, accurate product classification, and proactive communication with DME payers and procurement teams. Companies that build reimbursement support into their go-to-market model can protect volume during code transitions, reduce denials-related leakage, and strengthen relationships with customers who face their own compliance pressures.
Risks and Uncertainties
Several factors could alter the pace or shape of growth. Faster-than-expected reimbursement tightening could compress margins for products that cannot demonstrate differentiated value within the new hydrophilic codes. Conversely, slower adoption of reusable systems could limit the upside of that category if reprocessing concerns or reimbursement gaps persist. Input cost volatility, particularly in specialty polymers and coating materials, may pressure manufacturers without scale flexibility. Finally, the market's moderate concentration leaves room for competitive disruption if a new entrant successfully combines coating performance with packaging, reimbursement support, or sustainability claims that resonate strongly in key channels.
Strategic Implications for Decision-Makers
The market's direction is clear enough to warrant action, but the precise moves required depend on where a company sits in the value chain. The following recommendations are intended to translate the broader trends into practical priorities.
For Manufacturers and Brand Owners
Align product portfolios with the new hydrophilic coding framework before the transition creates claim friction. Prioritize coating consistency, no-touch or reduced-touch handling, and packaging designs that support discreet, portable use. Evaluate whether a reusable or hybrid architecture fits your capabilities and target segments, and invest early in validation and payer communication if it does. For companies relying on OEM partners, ensure specification flexibility, quality documentation, and coding alignment are built into the supply relationship so that product changes can be executed without disrupting claim eligibility.
For Investors
Focus due diligence on companies that demonstrate three things: credible coating and manufacturing consistency, a clear reimbursement navigation strategy for the 2026 HCPCS changes, and a user-experience design that supports adherence in home and community care. The most attractive opportunities are likely in firms that can defend premium positioning through differentiated coatings and user-centric design, or that can unlock lifecycle cost advantages through reusable platforms with robust validation. Watch for portfolio rationalization signals as coding and classification changes take effect, since these often reveal which assets are strategically aligned and which are carrying hidden compliance or claim risk.
For Procurement and DME Operators
Treat the coding transition as a supply-chain and claim-accuracy project, not just an administrative update. Map current product lines against the new hydrophilic codes, confirm documentation requirements, and identify suppliers that can support a clean transition. Where applicable, evaluate reusable or hybrid options against total cost of ownership rather than unit price alone, and consider pilot programs that include structured patient education and tracking. Supplier partnerships that provide coding guidance, consistent coating quality, and strong user support will reduce operational risk during the transition period.
The intermittent catheters market is entering a phase where reimbursement specificity, user-experience design, and architectural innovation will determine competitive outcomes more than historical scale alone. The companies that act early on coding alignment, coating consistency, and lifecycle economics will be best positioned to capture the next wave of growth through 2032. For decision-makers seeking detailed segmentation data, channel-level revenue splits, and customized competitive assessment across specific product and application categories, the full PW Consulting research report provides the granular analysis needed to translate these market-level insights into precise strategic plans.
For detailed analysis of this topic, please visit the official page: Intermittent Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com