

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aftermarket TPMS Market: Why 6.64% CAGR Signals a Structural Profit Shift

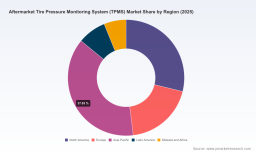
Strategic Trends and Commercial Opportunities in the Aftermarket Tire Pressure Monitoring System (TPMS) Market
The global aftermarket TPMS market has evolved from a post-recall compliance niche into a structured growth segment driven by vehicle aging, regulatory tailwinds, and sensor technology maturation. Valued at approximately USD 4.06 billion in the base year 2025, the market has expanded steadily from 3.1 billion in 2020, reflecting a consistent upward trajectory through the 2020–2025 historical window. Forward projections indicate the segment will reach 6.27 billion by 2032, with a compound annual growth rate of 6.64 percent across the 2026–2032 forecast period. This expansion is not evenly distributed across the value chain; rather, it reflects a market where sensor replacement cycles, fleet maintenance economics, and diagnostic tooling are reshaping revenue flows. The aftermarket TPMS space operates with moderate concentration—top three players collectively hold a 42 percent share, while the top five account for 55 percent—leaving meaningful room for specialized entrants, regional distributors, and technology-focused innovators.
The market's current shape is defined by a blend of mature replacement demand and emerging connectivity expectations. Aging vehicle populations in developed regions continue to drive sensor replacement, while commercial operators increasingly view tire pressure management as a fuel-efficiency and safety lever rather than a regulatory checkbox. At the same time, the aftermarket channel is navigating a transition from purely mechanical replacement to programmable, multi-protocol sensors that must interface with evolving vehicle electronics. This shift is compressing traditional replacement cycles and forcing service networks to invest in updated diagnostic capabilities.
Key Challenges and Inflection Points
The aftermarket TPMS segment is currently navigating a set of structural tensions that will determine which participants capture durable margin over the next decade. First, interoperability has become a central friction point. As vehicle manufacturers expand protocol variants and integrate proximity or NFC-based programming, aftermarket sensors and diagnostic tools must continuously expand coverage libraries. Services and distributors face the cost of keeping tooling and sensor catalogs synchronized with new vehicle models, while end users encounter compatibility questions during retrofits.
Second, regulatory assurance is tightening around function and fit verification. Aftermarket TPMS sensors increasingly require third-party registration to meet federal motor vehicle safety standards, creating a compliance layer that separates generic replacements from certified offerings. This dynamic is reshaping procurement decisions, particularly for fleets and service networks that must document compliance across large vehicle populations.
Automatic Tire Inflation System Market
Third, the battery lifecycle and replacement economics introduce a recurring cost consideration that influences both consumer behavior and fleet budgeting. Sensor batteries typically operate for roughly 6 to 10 years, or between 90,000 and 120,000 miles, with replacement commonly performed using alkaline button cells such as the CR2032. As vehicles and fleets age beyond initial warranty periods, battery depletion becomes a recurring service event that interacts with labor scheduling, parts availability, and total cost of ownership calculations.
Key Drivers Shaping Market Trajectory
The expansion of aftermarket TPMS is not the result of a single catalyst; it is being pulled forward by overlapping technological, regulatory, demand-side, and supply-side forces that reinforce one another.
Technology Innovation and Programmable Sensor Architectures
The most decisive driver is the shift toward universal, programmable sensor platforms that can be configured across multiple protocols and vehicle coverage lists. Retrofit kits and OE-replacement sensors are increasingly offered with expanded coverage for passenger vehicles and light-duty segments, while heavy-duty truck portfolios add dedicated sensor and valve assemblies alongside specialized diagnostic tools. In February 2026, a major North American sensor provider introduced an AirCheck BLE universal retrofit TPMS kit for light-duty vehicles, signaling how connectivity features are being folded into retrofit offerings to improve installation flexibility and post-installation monitoring.
Parallel tooling updates are reducing the friction of fitting sensors to newer vehicle platforms. In April 2026, an aftermarket sensor supplier updated its coverage for EU-Pro Hybrid variants, including hybrid and NFC-enabled configurations, within diagnostic tool software. These updates matter because they extend the practical usability of existing tool investments and reduce the probability of mismatch failures during installation. Combined with BLE-enabled sensors that broaden coverage for passenger vehicles, the technology trajectory is moving from static replacement parts to adaptable, software-defined hardware.
Regulatory Environment and Safety Compliance
Policy and standards frameworks continue to shape both demand and channel behavior. Aftermarket TPMS sensors require NSF International registration to meet federal motor vehicle safety standards for third-party assurance on function and fit, a requirement that effectively filters the field toward suppliers capable of demonstrating verified performance. At the same time, regulatory guidance requires aftermarket TPMS devices to detect and warn drivers of system malfunction for vehicles equipped with factory systems, reinforcing the need for reliable post-installation diagnostics rather than simple part swaps.
These requirements do not simply impose compliance costs; they alter how service providers structure their offerings. Workshops and fleet maintenance teams increasingly bundle sensor replacement with relearn procedures, malfunction checks, and diagnostic verification. This creates a more service-intensive revenue model and raises the importance of compatible diagnostic software and relearn capabilities in the aftermarket tool set.
Demand-Side Behavior and Fleet Economics
On the demand side, the market is benefiting from two reinforcing trends. Consumer and fleet operators are increasingly aware that tire pressure management influences fuel consumption, tire wear, and safety outcomes. For passenger vehicles, the replacement cycle is supported by aging registrations and the ongoing need to service factory-equipped TPMS after battery depletion or sensor damage. For commercial vehicles, tire pressure management is being treated as an operational efficiency measure, especially where route optimization and total cost of ownership are under scrutiny.
Average replacement costs for TPMS sensors generally fall between $50 and $250 per unit, depending on whether the system is direct or indirect. When combined with shop labor charges that typically range from $50 to $100 per sensor, the total per-vehicle cost becomes material enough to influence purchasing behavior but not prohibitive for most fleets and consumers. This cost band supports steady demand while giving differentiated providers room to compete on coverage certainty, installation speed, and diagnostic confidence.
PW Consulting
Supply Chain Dynamics and Cost Structure
The supply side is influenced by battery dependency, sensor component standardization, and the economics of diagnostic tooling. The reliance on replaceable alkaline button cells creates a predictable aftermarket parts stream, but it also ties sensor longevity to a commodity component whose availability and pricing can fluctuate. Tooling and software updates add another layer to the cost structure: service centers must maintain current diagnostic capabilities, and suppliers must continue investing in coverage libraries that keep pace with vehicle model introductions. These dynamics reward suppliers and distributors that can reduce incompatibility risk and streamline relearn workflows, while pressuring players who depend on static part numbers and outdated tool compatibility.
Competitive Landscape and Leading Strategies
The competitive field blends established global specialists with regional and China-based suppliers that have expanded their aftermarket coverage. The market's moderate concentration suggests that scale advantages exist, but differentiation remains achievable through coverage breadth, diagnostic software maturity, and commercial channel relationships.
Strategic Positioning of Leading Participants
The competitive set reflects distinct strategic postures rather than a single winning formula. One U.S.-based specialist has centered its aftermarket value proposition on OE replacement sensors, universal retrofit kits, a heavy-duty truck portfolio, and BLE-enabled sensors with expanded passenger-vehicle coverage. Its recent February 2026 launch of a BLE universal retrofit kit for light-duty vehicles and its October 2025 heavy-duty OE replacement portfolio with sensors, valves, and a truck diagnostic tool point to a strategy that pairs hardware breadth with commercial fleet relevance.
A China-based supplier has built an aftermarket focus around OE-R and retrofit TPMS sensors, truck BMS sensors, universal bundles, and compatible diagnostic tools for aftermarket installation. Its April 2026 update of aftermarket sensor coverage across EU-Pro Hybrid configurations within diagnostic tool software demonstrates a focus on tool compatibility and regional coverage expansion, an approach that can accelerate adoption in service networks seeking broad-fit solutions.
A U.S. manufacturer has emphasized its Rite-Sensor TPMS line alongside diagnostic tools with relearn software for aftermarket service and programming. Its May 2026 promotion combining the Tech600Pro TPMS tool with 30 rubber stem Rite Sensors, and its May 2026 announcement of a SEMA Show booth to showcase aftermarket TPMS innovations, indicate a strategy oriented toward service-channel visibility, bundled tool-and-sensor offerings, and hands-on installer engagement.
A German supplier has positioned itself with universal programmable TPMS sensors offering expanded coverage for aftermarket and retrofit applications, a strategy aligned with reducing fit uncertainty across diverse vehicle populations. A France-based provider has concentrated on TPMS activation tools, diagnostic software, and sensor programming solutions for aftermarket workshops and service centers, effectively targeting the service-enablement layer of the market rather than hardware alone.
Differentiation Levers in a Moderate-Concentration Market
Across these players, several differentiation levers are emerging as commercially significant. Coverage certainty is increasingly valuable: universal sensors and diagnostic tools that can be updated to accommodate hybrid, NFC, and newer protocol variants reduce install failures and rework. Tool-and-sensor bundling is also gaining traction, as service centers seek predictable installation workflows and reduced dependency on multiple vendors. For fleet-facing participants, heavy-duty portfolios that combine sensors, valves, and dedicated diagnostic tools create a more complete aftermarket solution and can improve repeat-purchase dynamics.
Service enablement remains a powerful differentiator. Providers that pair hardware with relearn software, activation tools, and updated coverage libraries help workshops reduce time-per-vehicle and improve diagnostic confidence. This is especially relevant where regulatory expectations require malfunction detection and third-party registration assurance, because verified fit and functional checks become part of the commercial offer rather than an optional add-on.
Market Evolution: Integration, Fragmentation, and New Entry
The landscape appears to be moving toward selective integration at the top, paired with continued fragmentation in niche coverage and regional service channels. Larger specialists are strengthening portfolios that span passenger and heavy-duty segments, leveraging diagnostic software and connectivity features to widen their aftermarket reach. At the same time, the universal-programmable sensor trend lowers barriers for specialized entrants that can deliver strong coverage updates, tool compatibility, or competitive installation workflows. Regional distributors and service networks can also gain share by aggregating compatible tooling, sensor bundles, and compliance documentation, particularly where local installation practices and vehicle mixes differ from global averages.
Tire Pressure Monitoring System (TPMS) Market
The net effect is a market in which scale supports brand trust and channel relationships, but technical responsiveness—fast coverage updates, robust relearn support, and clear compliance positioning—can still create durable differentiation.
Future Trends and Commercial Opportunities
Looking ahead three to five years, two to three trends are likely to shape where value accrues in the aftermarket TPMS segment.
Trend One: Software-Defined Sensor Coverage as a Service Standard
As vehicle electronics diversify and hybrid and NFC configurations become more common, the ability to update diagnostic coverage quickly and reliably will increasingly define aftermarket competitiveness. Suppliers and service networks that treat sensor coverage as a continuously updated asset—supported by tool software updates and clear compatibility documentation—are better positioned to reduce install failures and maintain trust with workshop customers.
Commercial opportunity: Toolmakers and sensor suppliers can monetize coverage updates, subscription-style diagnostic software, and bundled sensor-and-tool kits that simplify procurement. Service centers can differentiate on installation speed and compatibility certainty, especially in markets where vehicle model diversity is high.
Trend Two: Fleet-Oriented Aftermarket Bundles and Total-Cost Positioning
Commercial vehicle operators are likely to continue treating TPMS as part of a broader tire and fleet maintenance strategy. Heavy-duty aftermarket portfolios that combine sensors, valves, and truck-specific diagnostics support this shift and create opportunities for bundled procurement, preventive maintenance scheduling, and fleet-wide coverage planning.
Commercial opportunity: Suppliers with strong heavy-duty coverage can build fleet relationships around replacement cycles, battery lifecycle planning, and tool access. Fleet buyers can reduce total cost variability by standardizing on compatible sensor and tool combinations that minimize rework and downtime.
Trend Three: Compliance-Driven Procurement and Verification as a Competitive Filter
Regulatory expectations around function, fit, and malfunction warnings are likely to deepen the role of verified compliance in purchasing decisions. Third-party registration requirements and malfunction-detection expectations increase the importance of documented performance, especially for large fleets and service networks that must demonstrate consistency across many installations.
Commercial opportunity: Participants that clearly communicate compliance positioning and provide reliable relearn and diagnostic workflows can capture procurement preference in regulated environments. Buyers can use compliance assurance as a risk-reduction lever, not merely a legal requirement.
Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Coverage fragmentation across vehicle protocols may raise installation complexity if updates lag behind new model introductions. Battery replacement economics and component availability could affect perceived sensor longevity, particularly in high-mileage commercial use. Labor cost variability and shop throughput constraints may influence how quickly fleets and consumers adopt full replacement-plus-diagnostic service bundles. Finally, if regulatory documentation requirements become more cumbersome for some market participants, compliance readiness may become a stronger barrier to entry in certain channels.
Actionable Recommendations for Decision-Makers
The aftermarket TPMS market rewards participants who align product strategy, service workflows, and procurement practices with the shift toward programmable coverage, compliance assurance, and fleet-oriented value.
For Sensor and Tool Manufacturers
- Prioritize universal, programmable sensor platforms with continuously updated coverage libraries, especially for hybrid and NFC configurations, to reduce install mismatch risk.
- Invest in diagnostic tooling and relearn software that supports fast, repeatable service workflows, and consider bundled sensor-and-tool offerings that simplify procurement for service centers.
- Build clear compliance and registration positioning into product communications, particularly where third-party assurance and malfunction detection expectations influence purchasing decisions.
For Investors and Strategic Partners
- Evaluate opportunities where coverage responsiveness, tool compatibility, and fleet-facing portfolios create stronger repeat-purchase potential than hardware-only replacement models.
- Watch for consolidation signals among specialists seeking broader coverage and heavier commercial-vehicle exposure, while also monitoring regional distributors that aggregate compatible tools and sensor bundles.
- Assess exposure to battery lifecycle dynamics and labor cost variability, since these factors influence replacement frequency and total-service economics.
For Fleet Operators and Procurement Teams
- Standardize on sensor and diagnostic tool combinations that minimize compatibility risk and rework, and document compliance assurance to support consistent procurement across vehicle populations.
- Treat TPMS replacement as part of a fleet maintenance workflow that includes battery lifecycle planning, malfunction checks, and relearn procedures rather than a one-time part swap.
- Evaluate total per-vehicle cost in context of labor, coverage certainty, and installation speed, since the gap between component price and shop labor can shape the economics of different sourcing choices.
Closing Perspective
The aftermarket TPMS market is entering a phase in which durable advantage depends less on being a generic parts supplier and more on delivering verified fit, updated coverage, and efficient service workflows. The growth path to 2032 reflects a market where technology updates, regulatory expectations, and fleet economics all reinforce the same direction: more programmable hardware, more diagnostics-intensive service, and more procurement emphasis on compatibility and compliance. For decision-makers, the practical question is no longer whether the segment will expand, but which participants will capture margin by reducing installation risk and supporting repeatable, compliant service.
The dynamics outlined here provide a directional view of the market, but the most consequential choices—segment-level positioning, tool-and-sensor bundling strategies, fleet procurement standards, and regional coverage priorities—require deeper segmentation detail and operational context. A full research report can provide granular breakdowns across region, type, and application, along with company-specific profiles and competitive benchmarking that support more precise planning. For teams evaluating product roadmaps, channel strategy, or investment exposure in aftermarket TPMS, that level of detail is the difference between a broad market narrative and a usable execution plan.
For detailed analysis of this topic, please visit the official page: Aftermarket Tire Pressure Monitoring System (TPMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com