

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Molybdenum Powder Market: Why 5.8% CAGR and 3D Printing Reshape Growth to 2032

Strategic Trends and Commercial Opportunities in the Molybdenum Powder Market (2025–2032)
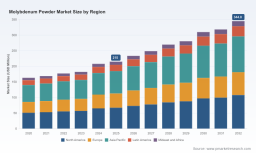
The global molybdenum powder market has entered a phase of structural expansion, driven by a convergence of industrial demand, technological adoption, and shifting supply chain dynamics. From a base valuation of approximately 163.15 million USD in 2020, the market has grown steadily to reach 215.0 million USD in 2025, reflecting a compound annual growth rate of 5.8 percent across the 2026 to 2032 forecast horizon. This trajectory signals more than a cyclical upturn; it points to a recalibration of how specialized metal powders are sourced, processed, and deployed across advanced manufacturing sectors. Understanding the underlying drivers, competitive positioning, and regulatory inflections is essential for executives and investors navigating this evolving landscape.
Market Overview and Contemporary Challenges
The market's expansion over the past five years has been characterized by steady revenue growth, with annual figures climbing from 168.81 million USD in 2021 to 207.98 million USD in 2024, before stabilizing at 215.0 million USD in 2025. Looking ahead, the forecast period projects consistent upward momentum, reaching 233.48 million USD in 2026 and scaling to 344.8 million USD by 2032. This growth is not uniform across all segments, nor is it insulated from macroeconomic and geopolitical friction. Several structural challenges and inflection points are reshaping how stakeholders approach procurement, production, and capacity planning.
- Regulatory volatility and supply chain realignment. Export controls and trade policy shifts have introduced pronounced uncertainty into cross-border flows of molybdenum powder. The imposition of restrictions in early 2025 prompted importers in North America and Europe to accelerate diversification strategies, while a temporary suspension of those controls extended through late 2026 created a window of adjustment rather than a permanent resolution. This regulatory back-and-forth has forced buyers to weigh short-term availability against long-term sourcing resilience.
- Raw material price transmission and margin pressure. Cost dynamics in the upstream concentrate market flow directly into powder pricing, with price increases of approximately 8 to 10 yuan per kilogram observed for every 100 yuan per ton-unit rise in molybdenum concentrate costs. This sensitivity compresses margins for producers who lack vertical integration or long-term feedstock agreements, while simultaneously testing the price tolerance of downstream manufacturers who rely on predictable input costs.
- Segment divergence and capability gaps. Demand is not growing evenly across product types or applications. Regular molybdenum powder continues to anchor the market, but spherical variants and other specialized grades are gaining traction in high-value use cases. Similarly, traditional powder metallurgy applications remain the dominant demand center, while additive manufacturing and other emerging applications are expanding at a faster pace from a smaller base. Companies that cannot bridge the gap between commodity-grade production and precision-grade specifications risk losing share to more technologically agile competitors.
Market concentration remains relatively moderate, with the top three players holding roughly 24.6 percent of total revenue and the top five capturing approximately 26.2 percent. This fragmentation suggests room for consolidation, but it also indicates that no single entity commands disproportionate pricing power. The competitive arena is therefore shaped less by market dominance and more by differentiation in purity, particle morphology, integration depth, and regional supply reliability.
Key Drivers Shaping Market Trajectory
Several interconnected forces are propelling the market forward, each reinforcing the others in ways that create both opportunities and structural shifts.
Technological Innovation and Material Performance Requirements
Advancements in powder production and application engineering are redefining what buyers expect from molybdenum powder. Spherical molybdenum powder, produced through controlled hydrogen reduction and precision milling, offers improved flowability, packing density, and consistency for additive manufacturing and high-performance coating processes. Grain size control in the 0.8 to 6.0 micrometer range, coupled with purity levels reaching 3N and beyond, enables manufacturers to meet tighter tolerances for aerospace components, semiconductor tooling, and high-temperature alloy applications. These technical capabilities are not merely incremental improvements; they open doors to applications where conventional irregular powders fall short, particularly in laser-based powder bed fusion and precision sintering workflows.
The broader trend toward miniaturization, weight reduction, and thermal management in advanced industrial equipment further amplifies the value of high-performance molybdenum powders. As engineers design components that must endure extreme temperatures, corrosive environments, or repeated thermal cycling, the material's intrinsic properties become a critical enabler rather than a substituteable input. This shift elevates the importance of supplier technical support, custom grading, and application-specific formulation capabilities.
Policy, Regulation, and Trade Dynamics
Policy interventions have become a defining factor in market behavior. Export controls introduced in early 2025 on molybdenum-related items, including powder, disrupted established trade routes and prompted procurement teams in the United States and other importing regions to identify alternative sources. The subsequent suspension of the one-year implementation window, effective through November 2026, provided temporary relief but did not eliminate the underlying strategic reorientation. Import volumes in the United States rose by 18 percent in 2025, reflecting both stronger apparent consumption and a deliberate effort to secure supply outside restricted channels.
This regulatory environment encourages a dual-track sourcing strategy: maintaining relationships with established suppliers while building redundancy through regional partnerships, inventory buffering, and qualification of alternative grades. For producers, the landscape rewards transparency, traceability, and the ability to demonstrate compliance with evolving export and import requirements. Companies that can navigate regulatory complexity without compromising delivery reliability are positioned to capture premium contracts and longer-term agreements.
Demand-Side Shifts in Manufacturing and Advanced Applications
End-user behavior is evolving as industries adopt more intensive material specifications and higher-value processing methods. Traditional powder metallurgy remains the largest application domain, supported by steady demand from components used in automotive, industrial machinery, and structural hardware. However, the growth narrative is increasingly shaped by additive manufacturing, where molybdenum powders are evaluated for their suitability in complex geometries, thermal stability, and post-processing performance. Research and commercial quantities of molybdenum powder are also being consumed by semiconductor manufacturing and high-temperature application sectors, where purity and consistency directly influence yield and reliability.
This demand-side evolution pushes suppliers to think beyond volume pricing and toward value-added services. Technical consultation, sample programs, grade customization, and joint development with end-users are becoming differentiators. Buyers are increasingly willing to pay for predictability and performance assurance, especially when production downtime or component failure carries significant cost.
Ferrochrome Powder Market
Supply Chain and Cost Structure Realignment
The link between upstream concentrate pricing and downstream powder costs creates a continuous pressure point that shapes procurement timing, inventory strategy, and contract structuring. When concentrate prices rise, powder prices follow with measurable lag and sensitivity, forcing producers to manage feedstock exposure carefully. Vertically integrated operations that control reduction capabilities and raw material inputs gain a structural advantage in margin stability, while non-integrated suppliers must rely on hedging, long-term agreements, or strategic stockpiling to mitigate volatility.
At the same time, global production volumes have expanded, with total molybdenum production reaching 672.6 million pounds in 2025, a 4 percent increase from the prior year, while usage rose 3 percent to 671.8 million pounds. This near-balance between production and consumption indicates a market that is tightening at the margin, where small disruptions or demand spikes can translate into price movement and allocation challenges. Supply chain resilience is therefore not just a regulatory response but a commercial necessity.
Competitive Landscape and Leading Strategies
The competitive environment features a mix of integrated producers, specialty suppliers, and research-oriented distributors, each pursuing distinct strategic positioning.
- Elmet Technologies operates through fully integrated powder reduction capabilities in the United States, serving alloys, stainless steel, and superalloy applications. This integration supports consistent feedstock control and tailored output for industrial alloy markets, positioning the company as a reliability-focused supplier for demanding metallurgical applications.
- Sumitomo Electric Industries manufactures 3N-purity molybdenum powder with grain sizes ranging from 0.8 to 6.0 micrometers via hydrogen reduction of high-quality raw material. The emphasis on controlled grain size and purity aligns with customers requiring repeatable performance for specialized processing, particularly where particle morphology influences flow and sintering behavior.
- American Elements supplies both commercial and research quantities of molybdenum powder and related metal powders, catering to a broad customer base that spans production-scale buyers and laboratory-scale developers. This dual-channel approach enables the company to capture early-stage demand signals and transition research-grade interest into commercial supply relationships.
- Goodfellow Corporation provides high-purity molybdenum powder up to 5N for semiconductor manufacturing, aerospace, and high-temperature applications. The focus on ultra-high purity and application-specific support targets segments where contamination control and material consistency are non-negotiable, allowing the company to compete on performance rather than volume.
- Stanford Advanced Materials supplies molybdenum metal powder for fabricated metal processing and industrial applications, emphasizing accessibility and broad industrial coverage. This positioning supports customers who need dependable supply for standard processing workflows and volume-oriented procurement.
- G K Min Met Alloys Co manufactures pure molybdenum powder as a core product for industrial use, anchoring its offering in purity and industrial applicability. The company's focus on pure-grade powder serves buyers seeking a straightforward, performance-reliable input for conventional powder metallurgy and related processes.
These players illustrate a market where differentiation is achieved through purity tiers, particle engineering, integration depth, and application specialization rather than sheer scale. The moderate concentration levels suggest that consolidation is possible, particularly as buyers seek fewer, more reliable supply partners amid regulatory and cost volatility. At the same time, new entrants with capabilities in spherical powder production, advanced hydrogen reduction, or niche high-purity segments can carve out positions by addressing unmet specifications. The trend is therefore one of selective convergence: larger, integrated players may absorb specialized capabilities, while focused suppliers compete on technical precision and customer proximity.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, several trends are likely to shape the market's evolution and create distinct commercial opportunities.
Worldwide Ammonium Molybdate Market
- Additive manufacturing and high-purity specialization will accelerate premium segment growth. As 3D printing and advanced coating processes mature, demand for spherical and high-purity molybdenum powders is expected to outpace the broader market average. Suppliers that can guarantee tight grain size distributions, low contamination, and reproducible batch performance will capture higher-margin contracts. The commercial opportunity lies in building application-specific grade portfolios, offering technical co-development, and establishing qualification pathways that reduce customer adoption friction.
- Regional supply diversification will become a standard procurement posture. Regulatory controls, import volume increases, and concentrate cost sensitivity are pushing buyers to construct multi-region sourcing strategies. Over the next few years, this will favor suppliers with transparent compliance records, flexible logistics, and the ability to provide alternative grades without compromising performance. Companies that invest in regional inventory hubs, long-term offtake agreements, and clear traceability will be better positioned to secure supply in volatile conditions.
- Vertical integration and feedstock control will separate margin performers from price-takers. The direct transmission of concentrate price movements into powder pricing means that companies with integrated reduction capabilities or secured feedstock channels will enjoy greater margin stability. This dynamic encourages strategic partnerships, capacity expansion in integrated facilities, and long-term contracts that lock in raw material economics. For buyers, it means evaluating supplier resilience as part of total cost of ownership, not just unit price.
These trends carry inherent risks and uncertainties. Regulatory timelines may shift again, altering the pace of diversification and the cost of alternative sourcing. Concentrate price volatility can compress margins unexpectedly, especially for producers without hedging mechanisms. Technical adoption in additive manufacturing and high-purity applications may progress faster or slower than anticipated, depending on downstream equipment compatibility, certification requirements, and total cost comparisons with conventional alternatives. Stakeholders should therefore treat these trends as directional signals rather than fixed forecasts, and build flexibility into capacity, inventory, and supplier qualification strategies.
Strategic Recommendations for Decision-Makers
Different stakeholder groups can extract actionable value from the current market dynamics by aligning strategy with the underlying drivers.
For manufacturers and producers:
PW Consulting
- Evaluate vertical integration or long-term feedstock arrangements to reduce exposure to concentrate price swings and stabilize margin profiles.
- Invest in spherical and high-purity grade capabilities where application demand is growing faster than the commodity segment, and build technical support infrastructure to accelerate customer qualification.
- Develop multi-region supply options and transparent compliance documentation to meet buyer expectations for resilience and traceability amid regulatory uncertainty.
For investors and strategic planners:
- Focus due diligence on suppliers with differentiated technical capabilities, integration advantages, and demonstrated ability to navigate regulatory shifts without supply disruption.
- Monitor segment-level demand signals, particularly in additive manufacturing and high-purity applications, as leading indicators of margin expansion and premium pricing potential.
- Assess consolidation opportunities where fragmented supply bases and buyer demand for reliability create conditions for strategic acquisitions or partnerships.
For procurement and supply chain leaders:
- Adopt dual-track sourcing strategies that balance cost efficiency with resilience, including qualified alternative suppliers, strategic inventory buffers, and flexible grade substitutions where performance allows.
- Incorporate total cost of ownership metrics that account for regulatory risk, delivery reliability, and technical support, rather than relying solely on unit price comparisons.
- Engage suppliers early in qualification and joint development processes to secure capacity, lock in specifications, and reduce lead-time exposure during periods of demand acceleration.
The molybdenum powder market is moving through a period where technical differentiation, regulatory agility, and supply chain resilience determine competitive outcomes. Stakeholders who align their strategies with these forces can capture growth in premium segments, stabilize margins amid cost volatility, and build sourcing postures that withstand policy shifts. For executives and investors seeking deeper segmentation data, regional dynamics, and customized strategic scenarios, comprehensive research reports provide the granularity needed to translate these directional insights into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Molybdenum Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com