

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Lifeboat Market 4.5% CAGR Outlook: How Concentration and Regional Dynamics Reshape Growth to 2032

The Lifeboat Market: Strategic Shifts and Commercial Opportunities in a Maturing Industry
The global lifeboat market has evolved from a compliance-driven segment into a strategically significant component of marine safety infrastructure. After growing from approximately USD 170.0 million in 2020 to an estimated USD 220.0 million in 2025, the market is projected to expand at a compound annual growth rate of 4.5 percent through 2032. While the growth trajectory is steady, the real story lies in the structural shifts reshaping how lifeboats are designed, regulated, serviced, and integrated into broader vessel safety systems. For executives, investors, and operations leaders, understanding these dynamics is no longer optional; it is a prerequisite for making informed capital allocation, procurement, and product development decisions.
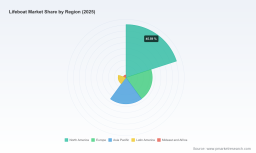
At a high level, the market is characterized by concentrated demand, increasingly stringent safety standards, and a growing emphasis on reliability over nominal compliance. The revenue base is anchored by lifeboat equipment itself, with passenger transportation representing the dominant end-use context. Regionally, demand is distributed across established maritime hubs and emerging safety-conscious markets, reflecting both regulatory maturity and varying fleet modernization cycles. What matters most, however, is not the headline figures alone, but the way these figures are being reshaped by technology, regulation, and operational expectations.
Core Challenges at the Current Inflection Point
The industry is navigating a set of overlapping pressures that are redefining competitive advantage and operational risk.
- Regulatory tightening around safety performance. Recent amendments to release mechanism standards and operational speed requirements are forcing manufacturers and operators to revalidate existing designs. Compliance is no longer a checkbox exercise; it is becoming a continuous validation challenge that affects design architecture, service protocols, and liability exposure.
- Performance validation under real-world conditions. Independent testing has raised concerns about stability and flooding risks in certain configurations when lifeboats are not fully loaded or are occupied under specific seating arrangements. This creates a broader market implication: design claims must be supported by reproducible testing, and procurement teams are increasingly scrutinizing evidence beyond baseline certification.
- Service and maintenance complexity. Guidance emphasizing manufacturer-certified personnel for the examination and operational testing of launching appliances and release gear is raising the bar for after-sales support. The market is shifting toward controlled service ecosystems, which affects cost structures, supplier relationships, and the economics of fleet maintenance over a vessel’s lifecycle.
Together, these challenges point to a market that is maturing rapidly. The winners will be those who can translate regulatory and performance pressure into product reliability, service competence, and transparent engineering evidence.
Key Drivers Reshaping the Lifeboat Market
The market’s direction is being shaped by four interconnected drivers. Each one carries implications for product strategy, procurement planning, and investment timing.
Technology Innovation and Design Evolution
Engineering improvements are steadily raising the bar for launch reliability, Structural resilience, and operator control. Advances in release mechanisms, hull configurations, and integration with davit systems are reducing failure modes that historically complicated launch operations. Equally important, the industry is seeing a stronger focus on designs that perform consistently across load conditions rather than only meeting minimum test scenarios. This matters because lifeboat performance is increasingly judged on operational reliability, not just certification compliance.
Regulatory and Standards Environment
Regulatory momentum is accelerating. New requirements addressing release mechanisms and lowering operational speeds are prompting redesigns and re-verification campaigns. In parallel, stronger expectations around maintenance and servicing are formalizing who can inspect and test launching appliances and release gear, and under what conditions. These changes are raising the importance of traceable service records, manufacturer-aligned maintenance pathways, and documented component integrity. The regulatory environment is effectively tightening both the design and service sides of the market.
Demand-Side Behavior and Fleet Expectations
Operators are increasingly treating lifeboats as part of an integrated safety system rather than isolated equipment. This is driven by a broader mindset in which passenger transport operators, offshore operators, and naval customers want assurance that evacuation assets will perform under stress, with predictable handling and reduced risk of flooding or instability. Procurement decisions are therefore placing greater weight on demonstrated performance, support coverage, and the ability to align lifeboat selection with vessel-specific operating profiles. The result is a more discerning buyer environment in which reputation for reliability and evidence of testing can influence selection as much as price.
Cost Structure and Service Economics
Lifecycle economics are becoming more important as service requirements become more specialized. When maintenance and testing must be performed by certified personnel or through authorized service pathways, operators face stronger incentives to plan for total cost of ownership rather than purchase price alone. For manufacturers, this creates opportunities to build value around service contracts, parts availability, and predictable maintenance schedules, while also increasing the importance of supply chain reliability for critical components. Cost structures are shifting from a one-time equipment transaction toward a longer-term service relationship.
Competitive Landscape and Leading Strategies
The market remains heavily concentrated, with a small group of established players holding a substantial share of revenue and technical influence. This concentration reflects the high barriers associated with certification, engineering expertise, service networks, and long-standing customer relationships in maritime and naval segments.
Strategic Positioning of Key Players
- VIKING Life-Saving Equipment A/S has built a strong reputation around integrated survival solutions, including free-fall lifeboats, fast rescue boats, and davit systems suited to merchant and offshore vessels. Its positioning emphasizes engineered reliability and the ability to deliver coordinated equipment packages rather than standalone products.
- Survitec Group Limited brings breadth across survival craft technology, including lifeboats, liferafts, and evacuation systems. Its strategic value lies in offering a wider safety ecosystem, which can simplify procurement and support for customers seeking multiple evacuation assets from a coordinated supplier base.
- Fassmer GmbH & Co. KG is recognized for lifeboats, rescue boats, and life-saving equipment tailored to cruise, ferry, and offshore applications. Its approach often centers on application-specific engineering and long-cycle project execution, with recent activity reinforcing its role in specialized training and operational boat programs.
- Zodiac Nautic Group contributes expertise in inflatable and rigid-inflatable boats alongside life rafts and safety equipment. Its competitive advantage is rooted in adaptable hull technologies and a strong association with versatile watercraft platforms that can support different operational needs.
- Ningbo New Marine Lifesaving Equipment Co., Ltd. participates through fast rescue boats, lifeboats, davits, and launching appliances, reflecting the growing presence of capable manufacturers in the broader marine safety supply chain. Its relevance lies in expanding manufacturing capacity and offering competitive equipment solutions across launch and support components.
Market Evolution and Strategic Trends
Several patterns are becoming visible in how the competitive landscape is evolving.
- Consolidation of service value. As maintenance and testing expectations tighten, suppliers that can offer credible, manufacturer-aligned service coverage are gaining strategic importance. The market is increasingly rewarding integrated product-and-service propositions over fragmented equipment sales.
- Differentiation through evidence and engineering. In an environment where performance questions are being raised through testing and regulatory scrutiny, transparency in design rationale, validation data, and service qualifications becomes a competitive asset.Providers that can demonstrate robust engineering support are better positioned to win demanding contracts.
- Selective new entry and regional expansion. While the top tier remains concentrated, broader manufacturing capacity and regional supply options are expanding. Newer or regional participants can compete by addressing specific cost, lead-time, or application needs, but they must also meet rising expectations for certification, service competence, and long-term support reliability.
- Project-driven cycles and institutional demand. Award activity in specialized segments, such as training boat programs, illustrates how institutional demand can create targeted growth opportunities. These projects often require strong execution credibility and can reinforce a supplier’s standing in demanding markets.
For buyers and investors, the practical implication is that competitive advantage is shifting from product presence alone to a broader combination of engineering credibility, service readiness, and the ability to reduce operational risk across the equipment lifecycle.
Future Trends and Commercial Implications for 2026–2032
Looking ahead, the market is likely to be shaped by a small number of high-impact trends. Each trend carries both opportunity and uncertainty.
Trend 1: Performance Standards Will Drive Redesign and Revalidation Activity
Regulatory amendments focused on release mechanisms and operational speed, combined with testing findings related to stability and flooding risk in certain conditions, are likely to sustain a wave of design refinement and verification work. This creates near-term demand for engineering support, testing coordination, and product updates, while also encouraging longer-term investment in more robust launch and stability characteristics. Commercially, this favors organizations that can respond quickly with credible engineering changes and clear documentation.
Trend 2: Service and Maintenance Will Become a Central Commercial Battleground
As servicing expectations increasingly emphasize certified personnel and manufacturer-aligned examination and testing, the after-sales segment will grow in strategic importance. Operators will look for predictable maintenance pathways, component availability, and support coverage that reduces downtime and compliance risk. For manufacturers and service providers, this means revenue and customer loyalty will depend more on lifecycle support quality than on initial equipment sales alone.
Worldwide Wafer Boat Market
Trend 3: Procurement Will Shift Toward Integrated Safety Assurance
Buyers are expected to place greater value on coordinated solutions that combine lifeboats, launching appliances, and related evacuation elements with consistent support standards. The trend is toward fewer, more trusted procurement relationships for safety-critical assets, especially where operators seek to simplify accountability and reduce integration risk. This benefits suppliers that can offer end-to-end assurance and penalizes those that are seen as strong on product but weaker on systemic support.
Floating Dock Market
Risks and Uncertainties
Despite the constructive outlook, several uncertainties deserve attention.
- Regulatory interpretation and enforcement may vary by region and flag state, creating uneven compliance timelines and different speed of adoption across markets.
- Testing-related scrutiny could accelerate redesign costs for certain product lines and create short-term margin pressure while validation cycles are completed.
- Service qualification requirements may constrain the supply base if certified capacity does not expand in step with demand, potentially increasing turnaround times and support costs.
- Demand cyclicality in shipping, offshore, and naval programs can influence the pace of new equipment orders, even as retrofit and service demand remains more resilient.
Actionable Guidance for Decision-Makers
The market’s next phase will reward organizations that align strategy with the direction of regulation, performance expectations, and service economics. The following priorities are most relevant for different stakeholder groups.
PW Consulting Automotive & Machinery Research Center
For Manufacturers and Equipment Suppliers
- Strengthen engineering evidence packages that address stability, release behavior, and performance across load conditions. Transparent validation support is becoming a differentiator in competitive procurements.
- Invest in certified service capacity and clear maintenance pathways. Lifecycle support is increasingly a commercial prerequisite, not an optional add-on.
- Prepare for redesign and revalidation workloads triggered by updated release mechanism and speed requirements. Early readiness can convert regulatory pressure into share gains.
For Investors and Capital Allocators
- Focus on companies with credible service ecosystems and strong engineering reputations, since lifecycle support and compliance readiness are becoming central to long-term value creation.
- Monitor project-driven demand signals, especially in specialized training and institutional programs, as indicators of execution capability and market access.
- Assess exposure to redesign costs and certification cycles, which can affect short-term margins even when medium-term demand remains healthy.
For Procurement Teams and Vessel Operators
- Evaluate total cost of ownership with greater weight on service coverage, testing qualifications, and parts availability rather than purchase price alone.
- Request evidence of performance validation under conditions relevant to your operating profile, particularly where stability and flooding risk have become points of scrutiny.
- Simplify accountability by favoring suppliers that can support integrated evacuation systems and provide consistent maintenance standards across equipment types.
Effective decisions in this market require more than headline market size or broad growth estimates. Segmentation behavior, regional demand patterns, pricing dynamics, service economics, and company-level execution all influence who captures value as the market matures. Detailed breakdowns of these variables can help translate the strategic directions outlined here into procurement planning, product roadmap choices, and investment screening with greater precision. For decision-makers seeking a sharper view of market segments, competitive positioning, and forward demand scenarios, the full research report offers a more granular basis for action.
For detailed analysis of this topic, please visit the official page: Lifeboat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com