

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Foam Roller Market: Why 10.7% CAGR Signals Commercial & Regional Shifts Through 2032

Foam Roller Market Outlook: Strategic Trends and Commercial Opportunities Through 2032
Market Present: Scale, Trajectory, and Core Challenges
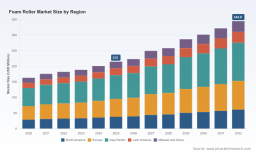
The global foam roller industry has transitioned from a niche recovery accessory into a mainstream wellness and fitness hardware category. Between 2020 and 2025, the market expanded from approximately USD 163.15 million to USD 215.0 million, reflecting a sustained uptake across both professional and consumer environments. Projections extending through the 2026–2032 forecast period point to continued momentum, with the market expected to reach roughly USD 344.8 million by the end of the horizon. This growth translates to a compound annual growth rate of 10.7%, a trajectory that signals both healthy demand expansion and periodic structural shifts rather than linear continuation of baseline sales.
It is useful to frame this expansion in terms of underlying pressure points rather than headline figures. The segment is no longer defined solely by volume of units sold; pricing architecture, material preferences, and end-user expectations are all moving in directions that reshape how manufacturers, distributors, and commercial buyers approach the category. The data indicates that total revenue is accumulating at a pace that outstrips simple population growth or gym membership expansion, implying that value capture is migrating toward higher-performing products, differentiated recovery protocols, and institutional procurement programs. At the same time, several discrete challenges are emerging that will determine which participants capture disproportionate share of the upside.
The Foam Roller Market's Core Challenges
Cartridge-level maturity in the basic consumer segment is one immediate constraint. Standard solid and hollow configurations, sold in default densities and generic dimensions, increasingly function as low-margin entry points. Buyers in price-sensitive channels treat these as interchangeable commodities, compressing the room for pure volume-driven growth. Companies that remain anchored in undifferentiated product lines risk being outflanked by competitors who bundle recovery applications, professional endorsements, or material claims into a more defensible value proposition.
Second, the cost backdrop tied to material inputs introduces structurally higher operating uncertainty. Pricing for key raw materials such as EVA has shown notable variance across geographies, with recent benchmarks in China and the United States indicating meaningful divergence in per-ton costs, while regional kg-level pricing has reflected similar dispersion between North America and Northeast Asia. Volatility of this type complicates both margin planning and inventory strategy, particularly for brands that operate multilayered distribution networks across multiple manufacturing origins. A firm that cannot hedge material exposure or flex sourcing quickly enough can see its price competitiveness erode even when end demand remains strong.
Third, the sustainability and regulatory conversation is moving from a peripheral marketing claim to a procurement-level requirement in certain commercial and institutional channels. The adoption of recycled and bio-based foam formulations is increasingly tied not only to product positioning but also to purchasing criteria in organizations that have committed to reduced virgin plastic usage and circular material targets. Players with legacy material architectures face a dual pressure: either invest in reformulation and supplier qualification, or accept narrowing access to contracts where material credentials are weighted alongside unit economics.
Key Drivers Reshaping the Segment
Innovation at the Intersection of Recovery and Automation
The most visible strategic shift is the migration from passive texture-based rollers toward products that embed measurable recovery benefits, guided usage patterns, or hands-free operation. Companies in the space are increasingly framing foam rollers as components within a broader recovery workflow rather than isolated stretching accessories. This is visible in product architectures that emphasize deeper tissue access, structured myofascial release, and mobility-oriented tension relief, as well as in newer automation efforts where AI-controlled or robotic rollers are being introduced to guide motion and pressure without direct hand operation. At the higher end of innovation, the category is beginning to accommodate devices that blend mechanical assistance with user programming, moving the foam roller closer to a service-like experience rather than a static consumable.
PW Consulting
The commercial significance of this shift is not simply product differentiation. It changes the economics of engagement. When a product offers a more repeatable, measurable, or guided recovery experience, it can justify premium positioning, recurring accessory sales, or stronger integration into clinical, athletic, and supervised wellness settings. That, in turn, creates a path to defend against price compression in the standard consumer tier.
Policy, Material Standards, and Sustainability Expectations
Regulatory and procurement environments are shaping demand in ways that are sometimes indirect but strategically important. The category is experiencing a gradual normalization of recycled content expectations, particularly for foam-based products where material sourcing decisions can influence whether an offering qualifies for certain institutional and sustainability-driven programs. Recycled EPP architectures and bio-based foam options are gaining traction as manufacturers align product development with internal environmental targets and external stakeholder expectations.
This dynamic does not simply reward environmental storytelling. It introduces a procurement sieve. In commercial gyms, rehabilitation settings, and corporate wellness facilities, purchase decisions increasingly privilege suppliers that can document material provenance, recycling rates, or reduced virgin polymer usage. Over time, these preferences harden into buying standards. Manufacturers that can speak credibly to material credentials while maintaining performance benchmarks are positioned to access channels that become more selective as the category matures.
Demand-Side Evolution: Aging Populations, Wellness Culture, and Non-Invasive Recovery
Longer-term demographic and behavioral shifts reinforce the category’s expansion beyond a purely athletic user base. An aging population and a broader consumer orientation toward non-invasive recovery tools are expanding the pool of potential users who seek mobility support, circulation comfort, and routine muscle care without clinical intervention. Health-conscious consumption is no longer restricted to dedicated fitness enthusiasts; it spans home users, older adults, and individuals managing routine stiffness or post-activity recovery. This broadens the application canvas and makes the product relevant in both family and commercial environments, though the value drivers differ by context.
In practice, the strategic implication is that the category’s growth is not solely reliant on the expansion of gym footfall or athletic participation. It is also supported by self-care routines, home fitness investments, and an increasing recognition of mobility maintenance as a daily habit. This diversification of user intent gives manufacturers multiple expansion paths, but it also requires clearer product-to-use-case alignment because the needs of a home fitness user, a physical therapy clinic, and a performance facility do not fully overlap.
Supply Chain and Cost Structure Realities
The material cost environment remains a central strategic constraint. Recent observations on EVA and foam pricing point to meaningful geographic dislocation: input benchmarks vary by region and by month, which affects landed cost, logistics planning, and the feasibility of aggressive price moves. In an environment where demand continues to grow but raw material pricing can shift the profitability equation quickly, supply chain flexibility becomes a competitive lever.
Yoga Mat Market
Companies that can coordinate sourcing across regions, qualify alternative material grades, or structure procurement contracts to reduce exposure to short-term pricing spikes gain more room to protect margins or to pass value-based pricing through without losing channel acceptance. Conversely, businesses that rely on static sourcing assumptions are more exposed to margin compression and to the temptation of discounting that can damage brand positioning.
Competitive Landscape and Strategic Positioning
The competitive field reflects a blend of specialized recovery brands, established fitness and equipment players, and emerging technology-forward entrants. Each is pursuing a different route to relevance, and the strategic variance is instructive.
TriggerPoint, based in Durham, North Carolina, anchors part of its positioning around patented self-massage patterns and a focus on deep tissue recovery and performance-oriented use. Its emphasis is less about generic rolling surfaces and more about structured texture and recovery specificity. That approach suits users who want a repeatable mechanical effect and supports premium positioning within performance and rehabilitation conversations.
RumbleRoller, operating from Baton Rouge, Louisiana, has built recognition around textured knobs intended for myofascial release and athlete recovery. Its most recent activity reinforces a continued focus on athletic, trainer, and physical therapy audiences, indicating a deliberate concentration on deep tissue utility and end-user credibility rather than broad consumer dilution. Recent marketing emphasis on deep tissue recovery for athletes and professionals underlines a positioning strategy that leans on functional differentiation and domain trust.
Yes4All, headquartered in Ho Chi Minh City, illustrates a different strategic logic: breadth, density options, and institutional accessibility. Its portfolio spans multiple sizes and densities using high-density EVA and EPP materials, aiming at both home fitness and institutional procurement. This orientation reflects a volume-aware strategy that prioritizes utility, specification flexibility, and cost-competitive offerings for buyers who want reliable product in varied context settings.
Technogym, from Cesena, approaches the category through a more system-integrated lens, presenting recovery rollers in the context of mobility, circulation, and personalized tension relief. As a broader equipment and wellness ecosystem player, Technogym is positioned to connect foam rollers to larger facility, programming, and user-experience narratives, which can be valuable in commercial environments that seek cohesive recovery arrangements rather than standalone accessories.
Adidas, based in Herzogenaurach, demonstrates how a major sportswear and fitness brand treats sustainability as a product identity. Its foam roller offering has been developed using recycled EPP materials with the explicit goal of reducing virgin plastic waste. This positions the brand at the intersection of material innovation and brand credibility, useful in channels where environmental commitments influence purchasing or where the product must align with broader corporate sustainability narratives.
RheoFit represents the most distinct strategic entry point: a move toward automation. Its recently introduced automatic foam roller with AI control targets hands-free deep tissue massage and recovery, signaling an attempt to shift the category from manual application toward guided or automated treatment. The product trajectory suggests a bet on convenience, repeatability, and a more technology-rich user experience, even if the category is still in early adoption for such models.
Market Structure Trends: Convergence, Fragmentation, and Increment Entrants
Taken together, the field suggests a market in which segments are simultaneously converging and diverging. On one side, the basic consumer tier faces commodity pressure and potential consolidation around players who can either manufacture efficiently at scale or reliably supply institutional channels. On the other side, differentiated recovery features, material credentials, commercial-system integration, and automation are opening pockets where distinct advantage can be built and defended.
This points toward a future in which the market structure is less uniform than it appears. Some players will compete through engineering and material performance; others through branding and ecosystem integration; others through cost-efficient product breadth; and others through automation and service-anchored experiences. The result is likely to be a more layered competitive environment in which winning depends on which layer a company chooses to dominate and how effectively it can align product, channel, and messaging accordingly.
Outlook for the Next Three to Five Years
Trend 1: Recovery as a Structured Behavior, Not an Occasional Tool
Over the next few years, foam rollers are likely to be used less as an occasional stretching accessory and more as a structured element in mobility and recovery routines. As non-invasive recovery tools gain wider acceptance across older demographics, home fitness users, and professionals seeking accessible muscle care, products that support repeatable routines and clearer use protocols will gain traction. The commercial opportunity lies in designing not only the product but the surrounding guidance, accessory ecosystems, and channel support that make usage consistent and outcome-oriented.
Worldwide Facial Roller Market
The risk is that this trend rewards only a subset of participants. If usage guidance, ergonomics, and perceived efficacy do not improve, consumers may cycle through low-differentiation products without forming durable loyalty. Brands that rely purely on surface-level features may find retention harder to sustain.
Trend 2: Sustainability Credentials as Procurement Gatekeepers
Material sourcing and environmental alignment will continue to move from a favorable brand attribute to a qualifying factor in select procurement environments. Recycled and bio-based foam architectures are gaining relevance because they can satisfy internal targets for organizations committed to lower virgin plastic usage. Over time, this could affect contract access, retailer preferences, and institutional demand, especially where sustainability criteria are formally weighted in purchasing decisions.
The upside is clear: manufacturers that can combine performance with credible material claims open doors to more selective and often higher-value channels. The uncertainty lies in how quickly standards harden and how consistently they are enforced across regions and buyer types. Premature assumptions about universal adoption can create misplaced investment, but lagging too far behind can narrow future access.
Trend 3: Technology-Enabled Recovery as a Differentiator and Price-Defense Mechanism
Automation and AI-controlled application are unlikely to replace conventional foam rollers across the entire market, but they can become a meaningful differentiator in premium and professional contexts. Hands-free or guided recovery devices address convenience, repeatability, and user experience considerations that manual tools do not. In practice, such offerings can help justify higher price points, attract early adopters, and create a stronger narrative around recovery precision.
At the same time, technology-driven products introduce their own risks: higher development cost, more complex manufacturing or service requirements, uncertain mainstream adoption curves, and potential fragility in the value proposition if the device experience does not match expectations. The strategic opportunity is to use technology where it solves a genuine pain point rather than as a generic premium label.
Strategic Actions for Decision-Makers
For Manufacturers
- Align product development with clearly defined use cases instead of broadening generically. Performance-oriented, home-care-oriented, and institutional-oriented needs differ enough to justify separate engineering priorities, density choices, and accessory strategies rather than a single line attempting to capture every buyer.
- Treat material sourcing flexibility as a strategic asset. Geographic pricing variance in raw materials means that sourcing, supplier qualification, and contract structures should be designed to reduce exposure to short-term cost swings and to support reformulation where sustainability requirements are becoming procurement-relevant.
- Use differentiation that connects to measurable user benefit. If a product relies on texture, density, recovery guidance, automation, or material claims, the benefit should be understandable and demonstrable to the intended buyer, because vague differentiation is quickly eroded by price competition.
For Investors
- Evaluate exposure by layer of the value chain. A company’s prospects may depend less on overall category growth than on whether it competes in a defensible niche, whether it has sustainable cost structures, and whether it can access channels that increasingly value performance or sustainability credentials.
- Watch for consolidation pressure in the commodity-adjacent end of the market and for technology or differentiation-driven models that may command stronger positioning. The most attractive opportunities are likely to sit at the intersection of real user value and clearer procurement or usage alignment rather than broad commodity exposure alone.
- Assess scalability carefully in technology-forward offerings. Automation and AI-connected devices can open premium pathways, but their investment case depends on adoption curves, service complexity, and whether the product solves a friction point that buyers will pay to remove.
For Procurement and Commercial Buyers
- Define selection criteria beyond unit price. In commercial and institutional settings, product durability, material credentials, recovery utility, and supplier reliability can matter as much as purchase cost, especially where program goals include sustainability or repeatable user outcomes.
- Shortlist suppliers that can demonstrate material and performance alignment with the intended environment. The relevance of EVA, EPP, recycled content, density options, and texture architecture depends on the setting, so procurement should match the specification to the actual use case rather than default to the lowest headline price.
- Monitor supplier roadmaps for reformulation, automation, and ecosystem integration. Buyers that understand which suppliers are investing in credible product evolution will be better positioned to negotiate multi-period agreements that balance cost, performance, and future-proofing.
The market environment through the forecast period will likely reward organizations that can connect product strategy to the forces actually shaping demand: structured recovery behavior, material and sustainability expectations, and selective technology adoption. The most resilient plans will be the ones that account for cost volatility, channel specificity, and the growing premium on credible differentiation rather than uniform volume expansion. For decision-makers who require a deeper breakdown of regional dynamics, segmentation detail, and competitive movement across the full 2026–2032 horizon, PW Consulting’s comprehensive market assessment provides a structured foundation for scenario planning and procurement strategy.
For detailed analysis of this topic, please visit the official page: Foam Roller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com