

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Knife Gate Valves Market: Why 5.8% CAGR and Wastewater Demand Change Everything

Knife Gate Valves Market: Strategic Shifts and Commercial Opportunities Through 2032
1. Market Trajectory and Defining Challenges
The global knife gate valves market has demonstrated consistent growth over the past five years, expanding from approximately $163 million in 2020 to an estimated $215 million in 2025. This trajectory reflects a compound annual growth rate of 5.8 percent, with projections indicating the market will surpass $320 million by 2032. The steady upward movement underscores the critical role of knife gate valves in handling slurries, abrasive media, and viscous fluids across heavy industry and municipal infrastructure. While the growth profile appears linear at first glance, a closer examination reveals underlying structural shifts that are reshaping competitive dynamics, pricing models, and end-user procurement behavior.
Elastic Sealing Gate Valve Market
Three key challenges are currently defining the industry's transition point. First, the sector is navigating mounting pressure from raw material cost volatility. Global stainless steel prices rose by 12 to 15 percent from 2024 to 2025, directly contributing to an 8 to 10 percent increase in the purchase price of valve products manufactured in China and other major production hubs. This input cost escalation is compressing margins for fabricators and forcing end-users to reconsider total cost of ownership calculations rather than focusing solely on upfront procurement expenses.
Second, compliance and standardization requirements are becoming more stringent. Knife gate valves deployed in severe service applications must now align with ASME Class 150 and 300 flange pressure ratings and meet MSS SP-135 specifications. Separately, stainless steel, bonnetless, flanged configurations are expected to conform to MSS SP-81 standards. These regulatory expectations are not merely technical checkpoints; they are reshaping qualification processes, extending lead times, and raising the barrier to entry for manufacturers without robust engineering documentation and testing capabilities.
Third, the industry is contending with persistent labor shortages in manufacturing. The scarcity of skilled fabricators and installation technicians is driving up costs for specialized valve production, particularly in slurry and wastewater applications where precision fitting and field adjustment remain labor-intensive. This workforce constraint is accelerating interest in modular designs, pre-assembled components, and automated actuation solutions that reduce on-site installation complexity.
PW Consulting
2. Core Drivers Reshaping the Market
Technological Innovation and Actuation Evolution
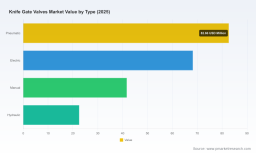
The shift toward automated and semi-automated valve actuation is one of the most consequential technology trends in the knife gate valves sector. Pneumatic configurations have historically dominated the product mix, reflecting their reliability in harsh environments and compatibility with existing plant control systems. However, electric actuation is gaining traction as industrial users seek tighter process control, reduced maintenance overhead, and integration with remote monitoring platforms. This transition is not simply a component swap; it represents a broader move toward valves as intelligent nodes within larger process ecosystems. Manufacturers that offer integrated actuation options, configuration software, and compatibility with supervisory control systems are positioning themselves for longer-term service relationships rather than one-time equipment sales.
Engineering advancements in valve body design and lining materials are also expanding the operational envelope of knife gate valves. Companies are introducing extended service models, bi-directional configurations, metal-cutting variants, and urethane-lined options that address abrasive wear, bidirectional flow requirements, and severe service conditions. These product developments are enabling end-users to standardize on fewer valve models across broader operating ranges, simplifying inventory management and reducing spare parts complexity.
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst. Environmental mandates around wastewater collection, stormwater management, and industrial effluent treatment are driving sustained capital investment in municipal and industrial piping systems. At the same time, the expectation that knife gate valves meet recognized pressure ratings and severe service standards is elevating the importance of certified product documentation. Procurement teams are increasingly requiring evidence of compliance with MSS SP-135, MSS SP-81, and related ASME flange classifications before awarding contracts. This regulatory emphasis favors established manufacturers with demonstrated testing records and clear traceability, while creating headwinds for lower-cost entrants that cannot readily substantiate performance claims.
In parallel, sustainability and durability expectations are influencing specification decisions. Operators are prioritizing valves that reduce fugitive emissions, withstand abrasive media without frequent replacement, and minimize downtime during maintenance windows. These priorities align with broader infrastructure modernization goals, particularly in regions where aging collection systems and process piping are being upgraded to improve reliability and reduce lifecycle costs.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by the relative growth trajectories of key application sectors. Wastewater treatment continues to represent a substantial demand center, reflecting ongoing investment in collection systems, stormwater infrastructure, and municipal treatment capacity. The pulp and paper industry remains a core application area, particularly where slurries, chemical recovery streams, and fiber suspensions require reliable isolation and flow control. Oil and gas operations also contribute meaningful volume, especially in regions where slurry handling and heavy media movement are integral to processing and extraction workflows.
Mining represents another significant demand segment, driven by the need to manage abrasive slurries, tailings, and mineral processing streams under demanding operating conditions. Power generation, while smaller in relative terms, provides steady demand for valves that can handle fly ash, biomass feedstocks, and other particulate-laden flows. Across these sectors, the common thread is a growing preference for valve solutions that combine severe service durability with operational flexibility, rather than simply meeting minimum functional requirements.
Supply Chain and Cost Structure Dynamics
The cost structure of knife gate valve production is being reshaped by the interplay of material pricing, labor availability, and geographic sourcing patterns. The increase in stainless steel prices has had a direct impact on valve pricing, particularly for manufacturers that rely on imported raw materials or produce in regions where input costs have risen sharply. This dynamic is prompting buyers to reevaluate supplier diversification strategies and consider nearshoring or dual-sourcing arrangements to mitigate price and supply continuity risks.
At the same time, the labor shortage in specialized fabrication is encouraging manufacturers to explore design simplifications, standardized sub-assemblies, and improved manufacturing workflows. Companies that can maintain quality while reducing labor intensity are better positioned to protect margins in an environment where both material and workforce costs are trending upward. For procurement organizations, this means that supplier selection is increasingly influenced by production resilience and process maturity, not just unit price.
3. Competitive Landscape and Leading Strategies
The knife gate valves market remains moderately concentrated, with the top three players collectively holding approximately 35 percent of revenue and the top five reaching roughly 48 percent. This structure indicates a market where established manufacturers maintain meaningful share, but there is still room for differentiation through product specialization, application focus, and regional presence. The competitive environment is not defined by a single dominant strategy; rather, it reflects a range of positioning choices that align with each company's engineering heritage, manufacturing capabilities, and target end markets.
Several leading manufacturers have built their market position around application-specific engineering and product breadth. Emerson, for example, has focused on Clarkson knife gate valves designed for heavy slurry service across mining, power, pulp and paper, and wastewater industries. This application-oriented approach allows the company to align its product line with the operational realities of high-abrasion and high-volume environments. Henry Pratt Company has differentiated through custom knife gate valves ranging from 2 inches to 96 inches and above, using carbon steel, stainless steels, and weldable alloys to meet specialized project requirements. DeZURIK has emphasized a broad portfolio that includes cast and fabricated options, with premier KGC extended service, bi-directional, metal cutting, KSV severe service, KUL urethane lined, and KSL slurry models. This breadth supports a strategy of matching specific valve configurations to distinct service conditions rather than offering a single generalized product.
Other manufacturers are competing through material specialization, actuation focus, or regional strength. ITT Engineered Valves offers the Fabri-Valve series, including C45 ductile iron, C67 bi-directional, and CF134 bonneted models, targeting users who need robust fabricated construction in demanding service. Orbinox has established a European manufacturing base with uni-directional, bi-directional, and wafer-style knife gate valves for industrial applications, giving it credibility in markets where European engineering standards and export networks carry weight. Red Valve Company has focused on Tideflex knife gate valves tailored for slurry and abrasive applications, emphasizing flexible element performance in challenging media conditions. Fabricast Valve has concentrated on pneumatic and manual knife gate valves, including large diameter models, serving customers who prioritize straightforward actuation options and wide size availability. Keckley Company produces low-pressure flanged and fabricated knife gate valves for pulp and paper, chemical, power, and mining applications, aligning its offering with sectors that require reliable low-pressure isolation. Hawle Armaturen has directed attention to wastewater networks and viscous fluids through the Erhard ERU K1 knife gate valve, reflecting a municipal and utility-oriented specialization.
The market is also showing signs of evolution in how companies engage with end-users and project ecosystems. Recent trade show participation highlights a continued emphasis on in-person technical engagement and direct showcase of valve capabilities. Elite Valve exhibited its complete range of engineered knife gate valves at the Valve World Calgary Conference & Expo in June 2026. DeZURIK attended the Design-Build for Water/Wastewater Conference in Dallas in April 2026 and the WEF Collection Systems and Stormwater Conference in Portland in July 2026, using these platforms to present knife gate valve solutions to water and wastewater professionals. These activities suggest that face-to-face technical marketing, project-focused demonstrations, and sector-specific conferences remain important channels for building specification awareness and supporting procurement decisions.
Looking ahead, the competitive landscape is likely to evolve along three dimensions. First, consolidation pressure may increase as larger valve and flow control groups seek to broaden their severe service portfolios through acquisition or strategic partnership. Second, segmentation is likely to deepen, with companies increasingly defining themselves by application niche, material capability, or actuation integration rather than competing solely on general-purpose product lines. Third, new entrants and regional manufacturers may continue to challenge incumbents in price-sensitive segments, particularly where standard configurations and shorter lead times are valued over highly specialized engineering. In response, established players are expected to reinforce their differentiation through compliance documentation, application engineering support, and long-term service relationships.
4. Forward Outlook: Trends and Opportunities to 2032
The next three to five years are likely to be shaped by three interconnected trends, each carrying distinct commercial implications.
Automation and digital integration will become baseline expectations rather than premium features. As pneumatic and electric actuation options mature and remote monitoring becomes more common in industrial and municipal settings, buyers will increasingly expect knife gate valves to support configuration flexibility, condition feedback, and integration with broader control architectures. This trend creates opportunities for manufacturers that can offer integrated actuation packages, predictable maintenance intervals, and compatibility with digital process platforms. It also raises the stakes for suppliers that remain focused only on mechanical valve hardware, since specification decisions may increasingly favor solutions that reduce operational uncertainty and simplify lifecycle management.
Severe service specification and compliance documentation will increasingly dictate winning vendor lists. The expectation that valves meet ASME flange ratings and MSS SP-135 or MSS SP-81 requirements is likely to intensify as project owners standardize procurement criteria and reduce discretion in vendor qualification. Companies that invest early in clear documentation, application-tested product lines, and reliable quality systems will be better positioned to secure specification shares in demanding sectors such as wastewater, mining, and pulp and paper. Conversely, price-driven sourcing without robust compliance support may face growing pushback in projects where failure risk or downtime costs are material.
Lifecycle economics will outweigh initial purchase price in more procurement decisions. The combination of rising stainless steel costs, labor constraints, and pressure to reduce maintenance disruption is pushing buyers toward a more total-cost-oriented evaluation. This shift favors product designs that extend service intervals, resist abrasive wear, simplify installation, and reduce the frequency of replacement. It also creates opportunities for manufacturers and distributors that can provide application guidance, configuration support, and service planning rather than transactional sales alone.
These trends intersect with meaningful commercial opportunities. Manufacturers can pursue growth by expanding actuation-integrated offerings, developing standardized severe service lines that reduce customization cost, and strengthening application-specific support for wastewater, mining, and pulp and paper projects. There is also potential in regional market expansion where infrastructure modernization and industrial processing investment are accelerating. For investors and strategic buyers, the market presents interest in companies with strong compliance credentials, application engineering depth, and the ability to serve both standard and severe service requirements without sacrificing margin. At the same time, uncertainty remains around raw material pricing trajectories, the pace of labor market normalization, and the degree to which end-users will consolidate procurement around fewer vendors or continue to diversify across multiple suppliers.
5. Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Prioritize application-specific differentiation over broad product proliferation. Knife gate valves are increasingly evaluated against service conditions, compliance expectations, and total cost of ownership, which means that clear positioning in severe service, wastewater, slurry, or custom-size applications can create more sustainable advantage than competing across too many generic configurations. Invest in documentation, testing, and engineering support that make it easier for specification engineers and procurement teams to justify selection during vendor qualification. At the same time, evaluate actuation integration and design simplification as margin-protection levers in an environment where material and labor costs are rising.
Butterfly Valves Market
For Investors and Strategic Buyers
Focus on companies with durable specification relationships, recognized compliance alignment, and the ability to serve demanding end markets without overreliance on price competition. Look for product portfolios that balance standard configurations with severe service capability, since this mix can support both volume stability and higher-margin project work. Assess whether the manufacturer's production model can withstand raw material volatility and labor constraints, and consider whether the business is positioned to benefit from infrastructure modernization, wastewater investment, and mining or pulp and paper process upgrades. Entry or expansion opportunities may be strongest where a supplier can pair technical credibility with regional reach and responsive project support.
For Procurement and Operations Leaders
Expand evaluation criteria beyond initial price to include compliance documentation, service durability, actuation integration, and installation complexity. In applications involving abrasive slurries, viscous fluids, or severe service conditions, the cost of downtime and premature replacement can outweigh modest savings on upfront procurement. Supplier diversification and dual-sourcing can also help manage exposure to material price swings and production bottlenecks. Where possible, standardize on valve models that have demonstrated alignment with relevant pressure ratings and service standards, while retaining flexibility for custom requirements on critical projects.
The knife gate valves market is moving from a period of steady expansion into a phase where technical differentiation, compliance readiness, and lifecycle value will play a larger role in determining commercial success. Companies that understand these shifts and act on them early will be better positioned to capture specification share, protect margins, and align with the next wave of infrastructure and industrial investment. For a more detailed view of segmentation dynamics, regional demand patterns, and customized strategic scenarios, the full PW Consulting market research report provides expanded data and decision-ready analysis across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Knife Gate Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com