

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Reciprocating Saw Blades Market: Metal Processing Leads 58% Share as CAGR Hits 5.85% Through 2032

The Reciprocating Saw Blades Market: Strategic Trends and Commercial Opportunities Through 2032
The reciprocating saw blades market is entering a phase defined by steady expansion, material science innovation, and shifting demand patterns across industrial and professional trade sectors. Valued at approximately 95.5 million USD in 2020, the market reached an estimated 123.4 million USD in 2025, reflecting a compound annual growth rate of roughly 5.85 percent through the 2020-2025 period. Forward projections indicate continued momentum through 2032, with revenue expected to approach 186.3 million USD by the end of the forecast horizon. Growth is not uniform across segments, nor is it immune to cost pressures and competitive dynamics. For executives and investors, the market presents a mix of incremental volume gains, margin compression risks, and opportunities tied to product differentiation and application-specific engineering.
Market Landscape and Core Challenges
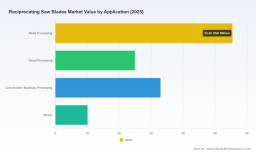
The base-year valuation of 123.4 million USD in 2025 places the market in a mid-tier industrial consumables category, characterized by fragmented supply, application-driven purchasing, and a meaningful share of replacement-driven demand. Market concentration remains moderate, with the top three players holding roughly 28.5 percent of revenue and the top five accounting for approximately 35.8 percent. This structure leaves room for regional specialists, tool-brand ecosystems, and value-oriented suppliers to compete on price, compatibility, or application expertise. Segment leadership is distributed across material types, with carbon steel blades commanding the largest share, followed closely by bi-metal designs, high-speed steel variants, and a smaller remainder of specialty or alternative materials. Application-wise, metal processing represents the dominant end-use, construction materials processing holds a substantial portion, wood processing contributes a meaningful share, and other applications round out the remainder. Regionally, Asia Pacific accounts for the largest revenue share, North America follows with a strong professional and contractor base, Europe maintains a mature but segmented demand profile, Latin America represents a smaller but growing market, and the Middle East and Africa comprise a modest share with region-specific procurement patterns.
Three structural challenges are reshaping how participants compete and where margins are expected to settle over the next several years.
- Raw material cost volatility is pressuring both premium and value segments. High-speed steel and carbide raw material pricing variations continue to influence production costs for industrial blade manufacturers, while premium carbide tips in reciprocating saw blades have shown year-over-year cost increases of roughly 15 to 20 percent driven by supply chain dynamics. This creates a difficult balance between maintaining performance credentials and protecting unit economics, especially for suppliers serving price-sensitive channels.
- Labor constraints are changing purchasing criteria on the demand side. Professional contractors report increasing demand for longer-life blades due to labor shortages in the trades. When skilled labor is scarce, downtime and blade change frequency become more costly, pushing buyers to prioritize durability, consistency, and reduced rework over lowest unit price. This shift rewards products that demonstrably reduce total cost of ownership, even if their sticker price is higher.
- Regulatory and safety expectations are reinforcing specification discipline. Industrial safety standards for tool use in construction and manufacturing continue to emphasize proper blade selection and handling. As compliance and site-safety expectations tighten, procurement teams increasingly require documentation, application matching, and consistent product quality, which raises the bar for suppliers that rely on generalized or loosely specified offerings.
Key Drivers Shaping the Market
Growth in the reciprocating saw blades market is being propelled by four interacting forces: material and design innovation, regulatory and safety pressures, demand-side behavior shifts, and supply chain and cost-structure dynamics. Each force has distinct implications for product roadmaps, channel strategy, and go-to-market positioning.
Technology and Material Innovation as a differentiator
Advancements in blade construction are moving the market beyond generic commodity blades toward application-optimized, longer-life solutions. Bi-metal blades incorporate high-performance edges electron-beam welded to high-strength steel backers, delivering multiple times the life of standard designs in demanding applications. Such engineering matters because reciprocating saws are used across demolition, metal cutting, pruning, and general-purpose tasks, each imposing different wear patterns and load conditions. Premium coatings and carbide-tipped technologies further extend service life and improve cutting efficiency across wood, metal, plastic, and mixed-material environments. The practical effect is a widening performance gap between top-tier offerings and entry-level alternatives, which creates commercial headroom for brands that can back up performance claims with consistent quality and clear application guidance.
Regulatory and safety standards reinforcing specification discipline
The continued emphasis on proper blade selection and handling in construction and manufacturing reinforces a market where compatibility, documentation, and reliability matter more than ever. For manufacturers, this means that product naming, packaging, and technical guidance are not cosmetic details; they are part of the value proposition. Blades that clearly communicate intended material use, tooth geometry rationale, and handling considerations reduce misuse risk and align with procurement teams seeking to standardize across crews and subcontractors. For distributors and large buyers, safety-driven standardization can increase repeat purchase consistency and reduce SKU proliferation, favoring suppliers with well-organized application matrices and clear replacement pathways.
PW Consulting
Demand-side behavior shifts in professional and industrial channels
Demand is being reshaped by the same labor pressures affecting many trades. As skilled workers become harder to recruit and retain, project owners and contractors are more willing to invest in tools and consumables that reduce time per cut, minimize blade changes, and lower the risk of blade failure during critical tasks. This behavior extends beyond professional contractors into industrial settings, where metal processing and construction materials processing demand higher throughput with fewer interruptions. In parallel, cordless and corded power tool ecosystems are increasingly influencing blade purchases. Buyers frequently seek blades labeled as compatible with their existing saw platforms, which rewards manufacturers that align product lines with popular tool brands and provide clear cross-compatibility. As a result, the market is seeing more emphasis on ecosystem fit, not just blade performance in isolation.
Supply chain and cost-structure dynamics
Cost structures remain sensitive to raw material pricing, particularly for high-speed steel and carbide inputs, which influence the economics of premium blade production. At the same time, value-oriented manufacturing capacity has expanded in global markets, offering competitive-priced options for distribution and professional use. This dual dynamic creates a bifurcated environment: premium suppliers compete on durability, coating technology, and application-specific performance, while lower-cost producers compete on price, broad compatibility, and distribution reach. The strategic question is how each participant manages the trade-off between margin protection and volume capture. Suppliers that can segment their offerings clearly, control variant complexity, and align pricing with demonstrated performance tend to navigate raw material swings more effectively than those forced into undifferentiated price competition.
Competitive Landscape and Leading Strategies
The market features a broad set of participants spanning American and European tool manufacturers, Japanese industrial brands, German engineering specialists, and value-focused suppliers with global distribution. Several names stand out for the way they position reciprocating saw blades within broader product ecosystems and application-specific value propositions.
The M.K. Morse Company emphasizes high-performance bi-metal and cobalt reciprocating saw blades, with product families designed for demolition, general purpose, and metal cutting. Its positioning centers on long blade life and American-made manufacturing, with updated guidance on matching blades to materials and applications. This focus on selection clarity is strategically important because it reduces buyer uncertainty and aligns with the safety and specification trends described earlier.
Worldwide Manual Hacksaw Blades Market
LENOX competes with professional reciprocating saw blades featuring advanced coatings and construction designed for extended life and faster cutting across wood, metal, and industrial applications. Its brand positioning leans toward professional users who value consistent performance and wear resistance, reinforcing a premium-professional lane in the market.
Diablo Tools distinguishes itself through carbide-tipped reciprocating saw blades that pair specialized coatings with high-density carbide for substantially longer life across wood, metal, plastic, and demolition applications. This approach targets the performance ceiling, appealing to users who want to minimize blade replacement frequency and maximize cut quality in mixed-material environments.
Milwaukee Tools integrates reciprocating saw blades into its professional tool ecosystem, offering models for pruning, metal cutting, and demolition with advanced tooth designs. The brand has continued to expand its blade lineup with new models across multiple sizes and price points, reinforcing a strategy that ties consumables to platform loyalty and professional contractor relationships.
DeWalt and Makita similarly embed blade offerings within broader power tool ecosystems, with DeWalt focusing on professional-grade blades integrated across its tool lines and Makita supplying blades compatible with its cordless and corded ranges for industrial and professional use. Bosch Power Tools and Metabo extend this pattern in professional demolition and heavy-duty settings, with Bosch emphasizing high-performance blades for demolition and metal cutting and Metabo offering blades for heavy-duty and general-purpose metal and wood cutting.
On the specialty and value side, Freud Tools provides carbide-tipped and bi-metal blades with advanced tooth geometry for precision wood, metal, and demolition cutting, while Wilh. Putsch GmbH & Co. KG concentrates on industrial-grade blades with a focus on durability and performance in metal cutting. Skil Tools addresses consumer and light-duty professional applications with more affordable options. In global value segments, KWCT and Greatstar provide competitively priced blades for wide distribution and professional use, and Moretop Tools builds its identity around coated reciprocating saw blades with advanced coatings for demanding cuts. Distributors and specialty suppliers such as HUB Industrial Supply and Brock Supply add another layer, with HUB focusing on precision industrial and manufacturing applications and Brock Supply emphasizing premium bi-metal blades with cobalt content for heavy-duty use. Disston rounds out the list with durable bi-metal blades for professional and industrial use.
Several strategic patterns emerge from this landscape. First, ecosystem alignment is a powerful differentiator. Brands that connect blade offerings to popular saw platforms and professional tool lines reduce switching friction and create natural repeat-purchase behavior. Second, application clarity is increasingly decisive. Suppliers that publish clear guidance on blade selection for specific materials and applications help buyers standardize and reduce risk, which strengthens procurement relationships. Third, the premium-versus-value divide is widening. Carbide-tipped and advanced-coated designs push the upper end of performance and life, while competitive-priced models serve broader distribution and price-sensitive channels. The result is a market where segmentation discipline matters more than ever.
Market structure is likely to continue evolving along two axes. On one side, consolidation pressures may intensify among mid-tier players seeking scale in distribution, raw material procurement, and application development. On the other, niche differentiation will remain viable for suppliers that can demonstrate measurable advantages in life, cut quality, or compatibility for specific end-uses. New entrants and regional suppliers can still gain traction by targeting underserved applications, offering well-defined compatibility with popular saw systems, or providing strong technical support and selection guidance. The key is not to compete on every front, but to own a defensible position in a clearly defined segment.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define how the reciprocating saw blades market grows and where value is captured.
- Application-specific engineering will move from a premium feature to a baseline expectation in higher-value segments. As buyers become more familiar with blade construction differences and more sensitive to downtime, demand will increasingly favor products designed for distinct material families and use cases rather than generic one-blade-fits-many approaches. Commercial opportunity lies in developing clear application families, simplifying SKU decision-making for distributors and large buyers, and pairing product lines with selection tools and guidance.
- Long-life consumables will gain share as labor scarcity and project scheduling pressures persist. Contractors and industrial operators are likely to keep prioritizing blades that reduce change frequency and maintain consistent performance over time. The opportunity here is not simply to market durability claims, but to quantify total cost of ownership in terms that procurement teams can act on, such as cuts per blade, replacement intervals, and reliability under defined conditions.
- Ecosystem and compatibility strategy will remain central to repeat purchase behavior. Suppliers that align blade lines with widely used saw platforms and communicate compatibility clearly are better positioned to capture recurring demand. This creates openings for tool brands to deepen consumables attach rates, and for independent blade suppliers to strengthen cross-compatibility messaging where it is credible and consistent.
- Cost-structure management will separate resilient suppliers from those exposed to raw material volatility. With carbide and high-speed steel pricing subject to fluctuations, companies that diversify material options, segment product tiers by performance and price, and control variant complexity are better placed to protect margins without sacrificing relevance. This also opens the door for hybrid strategies that pair premium coated or carbide-tipped lines with value-oriented bi-metal or carbon steel options, depending on channel and application needs.
These trends carry risk and uncertainty. Raw material pricing can compress margins if not managed through pricing strategy, product tiering, or sourcing flexibility. Demand may shift faster in some regions than others, particularly where construction activity, metal processing investment, or contractor labor markets diverge. Competition from value-oriented suppliers may intensify in price-sensitive channels, pressuring undifferentiated premium products. And regulatory or safety expectations can change the pace at which buyers adopt new specifications, especially in larger industrial accounts with formal procurement and compliance processes. Participants that monitor these signals and adjust segmentation, pricing, and application support accordingly will be better positioned to capture growth without racing into margin-eroding competition.
Actionable Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the board.
For manufacturers and suppliers, the most valuable moves are to sharpen segmentation, protect margin through clear tier architecture, and invest in application guidance that reduces buyer uncertainty. Build product lines around well-defined material and use-case families rather than broad, overlapping SKUs. Where advanced coatings or carbide-tipped designs justify premium positioning, ensure that performance claims are supported by consistent quality and clear handling guidance. At the same time, maintain credible value tiers for channels where price sensitivity and broad compatibility matter more than maximum life. Pricing strategy should reflect raw material volatility without forcing an all-or-nothing response, and variant complexity should be managed so that inventory, distribution, and customer support remain efficient.
For investors, the market rewards participants that combine ecosystem alignment, application clarity, and disciplined cost management. Look for companies with defensible positions in professional or industrial channels, strong repeat-purchase dynamics through tool-platform compatibility or specification standardization, and the ability to segment premium and value offerings without diluting brand identity. Pay attention to how suppliers are responding to labor-driven demand for longer-life blades and whether they can quantify total cost of ownership in a way that resonates with procurement teams. Monitor raw material exposure and the flexibility of product tiers, since these will influence margin stability as input costs move. Entry and expansion opportunities may exist for suppliers that can serve underserved application niches, strengthen compatibility messaging, or improve technical support and selection guidance in fragmented regional markets.
Circular Saw Blades Market
For procurement leaders and industrial buyers, the priority is to standardize on blades that match real application requirements and to evaluate total cost of ownership rather than unit price alone. Where labor constraints or project schedules make downtime costly, prioritize blade life, consistency, and compatibility with the saw platforms in use. Use selection guidance and application matching to reduce misuse risk and to align purchasing across crews and subcontractors. Develop specifications that reflect safety expectations and material conditions, and review supplier support and documentation as part of the evaluation, since these factors influence correct use and predictable performance over time.
Detailed segmentation data, regional dynamics, application-specific sizing, and competitive benchmarks can sharpen these decisions further. For teams that need granular breakdowns across type, application, and region, or that want customized scenarios for pricing, product tiering, and channel strategy, the full market study provides expanded data sets and actionable frameworks tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Reciprocating Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com