

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
SOM Market: 9.2% CAGR Trajectory and the Architecture Shift Reshaping 2032

System on Module Market Outlook: Strategic Trends and Commercial Opportunities (2026–2032)
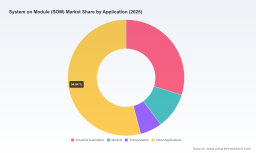
The System on Module (SOM) market has entered a phase of accelerated expansion, driven by the convergence of edge computing, industrial automation, and the proliferation of specialized embedded architectures. Between 2020 and 2025, global revenue climbed from approximately $1.2 billion to nearly $1.94 billion, reflecting a compound annual growth rate of roughly 9.2 percent through the forecast horizon extending to 2032. By the close of that decade, market size is projected to approach $3.43 billion, signaling a structural shift rather than a cyclical upturn. The trajectory is supported by sustained demand across industrial automation, medical device development, transportation systems, and a broad base of other application domains that continue to evaluate modular computing as a way to compress design cycles and manage long-term platform risk.
Market concentration remains relatively fragmented at the top tier, with the largest three participants holding a combined share in the mid-twenties and the top five extending only slightly further. This dispersion indicates that value capture is still distributed across regional specialists, architecture-focused suppliers, and broad-line embedded computing providers. At the same time, the competitive landscape is being reshaped by rapid productization cycles, architecture diversification, and an emerging emphasis on edge AI capabilities that extend well beyond traditional compute-density metrics. For executives and investors, the relevant question is no longer whether SOMs will continue to gain share in embedded design, but how to align product roadmaps, sourcing strategies, and portfolio investments with a market that is maturing while simultaneously fragmenting into more specialized use cases.
The period ahead will be defined by several intersecting forces: architectural choices between ARM, x86, and Power-based designs; the speed at which edge AI workloads migrate from proof-of-concept to production; the regulatory and compliance pressures that are altering the cost of packaging, materials, and end-of-life obligations in certain regions; and the supply chain dynamics that continue to reward suppliers who can offer predictable availability, long-term support, and validated integration paths. The following analysis examines these dynamics in detail, with an emphasis on what they mean for strategy, capital allocation, and operational planning.
Market Context and Critical Inflection Points
A Market Built on Modularization and Edge Expansion
The SOM market's growth story is rooted in a simple but durable premise: customers want to move faster without inheriting the full burden of board-level integration, long-term silicon validation, and multi-architecture porting. Modular platforms allow OEMs, integrators, and system builders to separate core compute selection from carrier-board design, thermal planning, and application software stacks. That separation has become increasingly valuable as embedded projects span longer lifecycles and face more demanding environmental, safety, and reliability requirements.
This dynamic has helped SOMs expand across industrial automation, medical systems, transportation, and a wide range of additional application areas where platform longevity and design flexibility matter as much as raw performance. The revenue pattern over the past several years reflects steady adoption rather than a one-time surge, with 2025 estimated at roughly $1.94 billion and the forward path suggesting continued double-digit momentum. More importantly, the composition of demand is shifting. Projects are no longer being evaluated solely on whether a module can meet today's compute target; they are being assessed on whether they can support future software updates, accommodate evolving security requirements, and remain available across multi-year production runs.
Key Pressures Shaping the Next Phase
Three pressure points stand out as especially consequential for the next planning cycle.
- Architecture decision complexity. The rise of multiple viable compute paths, including ARM-based designs, x86 options, and Power-based solutions, gives engineering teams more flexibility but also more evaluation overhead. Buyers must weigh performance-per-watt, software ecosystem maturity, long-term supply stability, and integration risk. This complexity increases the need for suppliers who can provide clear migration guidance and validated roadmaps rather than a broad catalog alone.
- Edge AI moving from acceleration to operating requirement. AI-related workloads at the edge are increasingly treated as baseline functionality rather than optional enhancements. That shift is pushing SOM suppliers to integrate specialized processing capabilities, optimize memory paths, and simplify the deployment of models in constrained environments. It also raises the bar for thermal management, software tooling, and lifecycle support, especially where devices must operate in industrial or medical settings.
- Regulatory surface area expanding beyond electronics itself. Packaging and extended producer responsibility requirements are tightening in several jurisdictions, and electronics suppliers that manufacture, distribute, or assemble in affected regions are exposed indirectly through packaging, logistics, and compliance documentation. While SOMs are not the central target of these rules, the broader operational environment is becoming more costly and more administrative. Suppliers that treat sustainability and compliance as design inputs rather than after-the-fact reporting items will have an operational advantage.
Taken together, these pressures suggest a market that will continue to grow, but with higher expectations around support, traceability, and architectural fit. Companies that compete primarily on price or catalog breadth without a clear migration path or application-specific validation may find it harder to hold share as design cycles lengthen and accountability increases.
Core Drivers Reshaping Demand and Supply
Technology Innovation as the Primary Accelerator
The most direct driver of SOM adoption remains technology innovation, but it is evolving in character. The immediate emphasis has shifted from generic compute availability to more targeted capabilities: integrated AI acceleration, improved power efficiency, smaller form factors for constrained installations, and architectures that can be adapted across multiple product generations. Recent product activity illustrates this direction clearly. In March 2026, Grinn launched the AstraSOM-261x, described as an ultra-compact Edge AI SOM built around the Synaptics Astra AI-native processor. At roughly the same time, the company introduced the aReady.CoM module to support Arm technology migration within its SOM portfolio. These releases are not isolated product announcements; they reflect a broader industry movement toward tightly optimized modules for edge AI and toward smoother migration between processor generations or ecosystems.
This shift matters commercially because it compresses the time between concept and deployment in edge scenarios where space, thermal budget, and software complexity are all constrained. It also favors suppliers that can pair hardware with evaluation platforms, carrier-board templates, and reference software flows. In practice, the winners are increasingly those who sell a design-ready environment, not just a module.
Policy and Regulatory Pressure as a Hidden Cost Structure
Regulatory developments are increasingly influencing the operational backdrop for embedded hardware suppliers. In the United States, multiple states advanced packaging and extended producer responsibility frameworks in 2025, with coverage expanding across material types and producer obligations. California's SB 54, for example, extends EPR requirements to certain single-use plastic food service ware and sets recycling-rate expectations for expanded polystyrene producers beginning in 2025. Oregon launched its packaging EPR program in July 2025, requiring participating producers to report material volumes through designated stewardship channels. Maine began formal rulemaking later in 2025 to update packaging stewardship rules and clarify recyclable, compostable, and reusable material listings. Similar activity is visible across Canadian provinces, where nine out of thirteen jurisdictions operated packaging EPR programs as of early 2025, covering plastics, paper and cardboard, glass, and metal packaging.
For SOM providers and their customers, the implication is not a direct electronics regulation but a wider compliance burden that touches packaging, distribution, and regional market access. As more jurisdictions move from voluntary sustainability initiatives to mandatory reporting and material requirements, companies with fragmented supplier documentation or inconsistent packaging standards will face higher administrative and logistical friction. This environment rewards suppliers who can standardize materials, provide clear reporting support, and align product design with regional compliance expectations early rather than retrofitting them during production ramp-up.
Demand-Side Shifts Toward Platform Durability and Edge Intelligence
On the demand side, the most meaningful change is a growing preference for platforms that are durable, modular, and capable of accommodating evolving workloads. Industrial automation projects, in particular, increasingly prioritize long availability windows, field upgradeability, and predictable software support. Medical applications require validated designs, stable documentation, and rigorous control over component changes. Transportation and other rugged use cases add environmental tolerance and lifecycle reliability to the mix. Across these segments, SOMs offer a way to reduce redesign friction when requirements change, which is especially valuable in programs that span years rather than months.
At the same time, edge intelligence is reshaping what customers consider "sufficient" performance. It is no longer enough for a module to deliver processing headroom; it must also support efficient inference, manageable power consumption, and integration paths that do not require extensive custom engineering for every deployment. This shift benefits suppliers with strong application alignment and clear software ecosystems, and it increases scrutiny of the total cost of ownership, including integration effort and long-term support.
Supply Chain and Cost Dynamics Favoring Predictability
Cost structures in the SOM market are being influenced by more than component pricing alone. Lead-time predictability, validation support, and regional availability increasingly affect purchasing decisions, particularly in applications where production disruptions carry high downstream costs. Suppliers that can provide transparent roadmaps, durable part availability, and design assistance reduce one of the largest hidden costs in embedded development: schedule uncertainty.
PW Consulting
The market is also seeing a gradual recalibration of where value is created. Some suppliers compete by offering broad architecture coverage and distribution reach; others compete through specialized vertical solutions and tighter integration with specific application domains. The result is a market in which cost leadership is less decisive than reliability of delivery, clarity of migration options, and the ability to reduce integration risk. That has important implications for both procurement strategy and supplier selection.
Competitive Landscape: Positioning, Differentiation, and Evolution
Differentiated Strategies Among Leading Participants
The competitive set in the SOM market reflects a wide range of positioning choices. Several suppliers focus on architecture-specific strength, while others emphasize multi-architecture breadth, ruggedization, or vertical application alignment. Rather than viewing the field through a single dimension, it is more useful to recognize that differentiation now comes from a combination of architecture expertise, application fit, integration support, and long-term availability commitments.
Toradex AG, based in Switzerland, is strongly associated with high-performance ARM-based modules for industrial, medical, and IoT applications. That focus gives the company a clear identity around ARM-centric design environments and application domains where longevity and embedded software continuity are priorities. Congatec AG, headquartered in Germany, concentrates on COM Express and SMARC-based modules optimized for embedded computing, positioning the firm around standardized form factors and scalable embedded platforms. Kontron AG, also in Germany, emphasizes x86 and ARM-based SOMs for industrial automation and edge computing, aligning its portfolio with sectors that demand a blend of performance and application-ready support.
Advantech Co., Ltd., based in Taiwan, rounds out a broad embedded footprint with rugged SOMs spanning ARM, x86, and RISC-V architectures, an approach that suits customers who need flexibility across multiple deployment environments. Aaeon Technology Inc., also in Taiwan, focuses on compact SOMs for edge AI and industrial applications, emphasizing small-footprint designs suited to space-constrained intelligent systems. Phytec Messtechnik GmbH, in Germany, offers the phyCORE SOM series based on ARM, PowerPC, and RISC-V for embedded systems, reinforcing a multi-architecture path for projects that may require diverse processor ecosystems.
SECO S.p.A., in Italy, provides industrial SOMs with ARM and x86 processors for automation and robotics, a positioning that highlights application-driven engineering rather than generic catalog breadth. Portwell Inc., also in Taiwan, supports high-performance SOMs across multiple architectures for edge computing, targeting applications where performance and integration flexibility both matter. Variscite Ltd., based in Israel, focuses on SOMs built around Renesas and NXP for industrial and automotive use, an approach that connects product strategy closely with specific processor ecosystems and use cases. SolidRun Ltd., also in Israel, concentrates on ARM-based SOMs for embedded and edge applications, reinforcing its identity around ARM-centric embedded design.
MYIR Tech, in China, offers SOMs with ARM and RISC-V processors for IoT and industrial projects, emphasizing accessible designs for broader deployment scenarios. iWave Systems, based in India, focuses on SOMs built on Qualcomm and NXP for mobile and embedded solutions, aligning its portfolio with communications-oriented and embedded applications. Grinn, headquartered in Poland, has carved out a niche in nano-sized Edge AI SOMs based on Synaptics processors, and its recent launches show a clear intent to push miniaturization and migration flexibility. Technexion, in Taiwan, provides ARM and NXP-based SOMs for robotics and industrial automation, reinforcing a vertical tilt toward mechatronics and automation workflows.
EMAC, based in the United States, addresses industrial and defense applications, a positioning that implies a greater emphasis on ruggedness, specialized support, and longer lifecycle accountability. Avalue Technology Inc., also in Taiwan, offers rugged SOMs for transportation and edge computing, reflecting the demand for environmental resilience in mobile and infrastructure-facing deployments. Forlinx, in China, focuses on SOMs for industrial and IoT deployments, positioning itself around practical embedded deployment rather than flagship performance alone. MSC Technologies, operating under Avnet in the United States, distributes SOM solutions through Avnet channels, adding the dimension of broad distribution reach and customer access across multiple application segments.
Computer On Module (COM) Market
Strategic Positioning Themes
Across this group, several positioning themes recur.
- Architecture specialization versus multi-architecture breadth. Some suppliers compete by going deep on one architecture family and the ecosystems that surround it, while others emphasize the ability to cover ARM, x86, RISC-V, and Power-based designs within a single engagement. Both models can work, but they attract different buyer profiles. Specialists tend to win when project teams want a clear path and deeply aligned tooling; broad-line suppliers win when procurement or engineering teams need flexibility across multiple programs.
- Application-centric engineering. The most meaningful differentiation often comes from application alignment. Suppliers that build reference designs, carrier-board guidance, and domain-specific support around industrial automation, medical systems, transportation, or edge AI reduce integration risk in ways that catalog listings cannot. This is especially important where certification, documentation, or long-term maintenance expectations are high.
- Miniaturization and edge AI readiness. The move toward smaller, purpose-built modules for AI workloads is creating a distinct value layer within the market. Modules that combine compact form factor with dedicated AI processing and migration-friendly design are likely to attract early adoption in edge scenarios where space and integration effort are constrained.
- Distribution and ecosystem reach. Distribution partnerships and channel access can matter as much as product features, particularly for buyers who prioritize sourcing simplicity, regional availability, and established procurement pathways. This dimension does not replace product differentiation, but it can amplify reach and reduce friction in volume programs.
How the Landscape Is Evolving
The market is not consolidating into a single dominant structure. Instead, it is evolving through a mix of specialization, selective convergence around edge AI, and expanding regional participation. Some suppliers are likely to deepen vertical focus in high-value sectors such as industrial automation or medical devices, while others will continue to compete by offering multi-architecture coverage and wider distribution. New entrants can still find space by addressing a specific form factor, processor ecosystem, or application niche, especially when they pair hardware with a compelling development experience.
At the same time, incumbents face growing pressure to prove long-term support, migration clarity, and application validation. The presence of multiple capable players reduces the risk of supplier lock-in, but it also raises expectations. Buyers increasingly compare not just features and unit cost, but the quality of engineering support, documentation stability, and the likelihood that a chosen module will remain viable through multiple product generations. In that environment, the strategic moat belongs to suppliers that can reduce uncertainty across the entire design lifecycle.
Forward-Looking Trends and Commercial Opportunities
Trend One: Edge AI as a Core Evaluation Criterion
Over the next three to five years, edge AI capability is likely to become a central part of SOM evaluation rather than a differentiating feature in a subset of projects. As inference moves from experimental deployment to routine operation, buyers will look for modules that combine efficient processing, manageable thermal profiles, and straightforward software integration. This trend opens commercial opportunities for suppliers that can offer validated AI-ready modules, reference software flows, and clear guidance on model deployment in resource-constrained environments.
The broader opportunity lies in helping customers move from prototype to production faster. Suppliers that reduce the friction of AI integration, including model portability, memory planning, and carrier-board compatibility, will be well positioned to capture design wins in automation, medical devices, smart infrastructure, and other edge-heavy domains. The risk is that expectations will rise quickly; modules that appear AI-capable on paper but lack practical deployment support may lose credibility in demanding applications.
Worldwide System on Module Boards Market
Trend Two: Multi-Architecture Navigation Will Become More Strategic
ARM, x86, RISC-V, and Power-based designs will continue to coexist, and the practical question will increasingly be how to choose and migrate between them without costly redesigns. Buyers will look for clearer migration paths, more transparent roadmaps, and support for transitions across processor generations. This creates an opportunity for suppliers that invest in migration tooling, documentation, and carrier-board strategies that simplify architecture changes.
This trend also creates risk for companies that treat architecture choice as a one-time decision rather than a lifecycle consideration. As software stacks, toolchains, and long-term availability expectations evolve, the cost of staying on a rigid platform may exceed the cost of building in migration flexibility. Organizations that ignore this dynamic may face avoidable redesign pressure later.
Trend Three: Operational Compliance Will Influence Supplier Preference
The expansion of packaging and extended producer responsibility requirements will continue to shape operational preferences, especially for suppliers serving multiple jurisdictions. While SOMs are not the primary subject of these rules, the broader compliance environment affects packaging, documentation, reporting, and regional market access. This creates a commercial advantage for suppliers that can standardize materials, streamline reporting, and help customers navigate regional obligations without disrupting production timelines.
The commercial implication is subtle but real. In programs where compliance overhead is high, buyers may favor suppliers who reduce administrative burden even if the immediate hardware price differential is small. Over time, this can shift competitive advantage toward suppliers with cleaner operational processes and stronger documentation discipline. The uncertainty lies in how quickly and uniformly these requirements spread; variability across regions can create uneven exposure and complicate global sourcing strategies.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Development Leaders
- Prioritize architecture decisions based on lifecycle fit, not just current performance. Evaluate migration paths, software ecosystem continuity, and long-term availability before committing to a platform. A module that supports a smoother transition across generations can reduce redesign risk more than a short-term performance advantage.
- Treat integration support as part of the product cost. Reference designs, carrier-board guidance, and application-specific validation can shorten development timelines and reduce engineering exposure. Select suppliers that offer a repeatable design environment rather than only a hardware module.
- Plan for edge intelligence as a baseline requirement in relevant applications. If a product roadmap anticipates AI-related features, choose a module strategy that can accommodate inference workloads without forcing a complete redesign later.
For Investors and Strategic Planners
- Focus on differentiation that compounds over time. In a fragmented market, durable advantages tend to come from application alignment, migration support, and integration tooling rather than catalog size alone. Companies that can demonstrate repeatable design wins in industrial automation, medical, transportation, or edge AI are likely to be more resilient than those competing on breadth without clear application fit.
- Watch for consolidation around edge AI value chains. As miniaturized AI modules and migration-friendly designs gain traction, expect more activity around specialized suppliers and potentially more partnerships that combine hardware, distribution, and software enablement. The opportunity is in platforms that reduce deployment complexity, not just in modules that add processing capability.
- Monitor regulatory exposure as a competitive variable. Suppliers that can anticipate regional compliance requirements and streamline documentation and packaging processes may gain preference in multi-region programs, even when hardware specifications are broadly similar.
For Procurement and Sourcing Teams
- Evaluate total cost of ownership beyond unit price. Factor in lead-time reliability, documentation quality, support responsiveness, and the operational burden of regional compliance. In many embedded programs, schedule stability and integration support matter more than marginal component savings.
- Build sourcing flexibility without sacrificing validation discipline. Multi-supplier strategies can reduce risk, but they should be paired with clear qualification criteria so that migration between suppliers does not create new integration debt.
- Confirm long-term availability expectations early. Where programs span several years, align procurement commitments with supplier roadmaps and change-control processes to avoid disruptive revisions during production.
For teams that need deeper segmentation, regional nuance, and supplier-by-supplier performance benchmarking, the full PW Consulting research suite provides a more detailed view of market structure, architecture splits, application demand, and competitive positioning. The complete report can support scenario planning, sourcing strategy, and investment prioritization with more granular data and customized analysis.
For detailed analysis of this topic, please visit the official page: System on Module (SOM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com